
 Generic Crop Protection Chemicals Market | 2026-2036
Generic Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Generic Crop Protection Chemicals Market Analysis
Formulation licensing revenue is reconfiguring margin pools away from molecule discovery toward post-patent production partnerships. Albaugh LLC leverages its North American manufacturing footprint to supply private-label herbicides to regional distributors. Nufarm Limited anchors its position through backward integration into active ingredient synthesis in Australia and Europe. United Phosphorus Ltd competes on price in emerging markets with a portfolio spanning wettable powders and emulsifiable concentrates.
Generic crop protection chemicals comprise off-patent synthetic or biological active ingredients formulated as herbicides, insecticides, fungicides, or rodenticides, typically manufactured through batch synthesis or continuous chemical processing at purity grades meeting FAO/WHO specifications. These products serve commercial agriculture by delivering pest, weed, and disease control at unit costs below proprietary equivalents. Herbicides capture the dominant share of product-type revenue as glyphosate and paraquat generics face sustained pull from soybean and corn systems. Liquid concentrate formulations lead volume shipments due to ease of tank-mixing and aerial application compatibility, though wettable powders retain share in rice paddies where water solubility constraints favor solid-phase delivery.
The EPA governs residue tolerance thresholds and label restrictions in the United States, while the EU Green Deal and F-Gas Regulation constrain formulation chemistries permitted in European member states. India's Central Insecticides Board mandates registration and batch testing under the Insecticides Act, shaping which generics reach the country's fragmented distributor network. Brazil's national environmental regulator enforces stricter buffer zones and aquatic toxicity assessments, filtering market access for imported emulsifiable concentrates. Stakeholders must track patent cliff timing for major molecules, regulatory harmonization pressures between export markets, and the accelerating shift toward bio-based adjuvants that could redraw competitive boundaries in formulation technology.
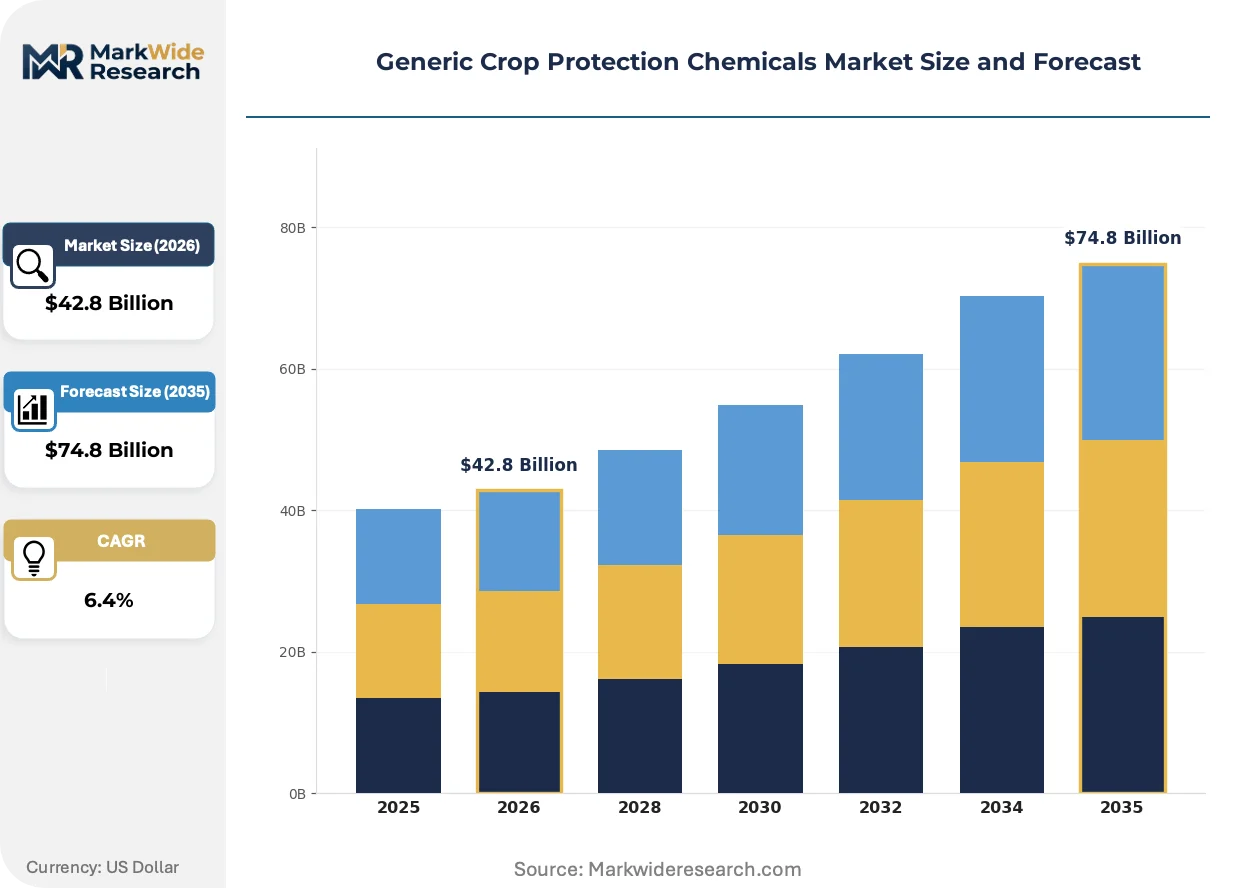
Market Dynamics
Patent cliff timing for major agrochemical molecules is compressing formulation licensing windows and forcing manufacturers to secure post-patent production partnerships before exclusivity expires. This structural pressure redistributes margin pools away from discovery toward backward integration into active ingredient synthesis and regional manufacturing scale.
Growth Catalysts
- Brazil's ANVISA residue protocols:Tighter monitoring of glyphosate and 2,4-D metabolites in soybean exports is accelerating farmer migration to registered generic alternatives with established MRL compliance documentation.
- Cooperative procurement in India:Cotton and soybean farmer cooperatives in Maharashtra and Gujarat are consolidating insecticide and herbicide purchases through bulk-tender mechanisms that favor generic wettable powders.
- Continuous processing technology:Shift from batch synthesis to continuous flow chemistry at FAO/WHO purity grades is reducing active ingredient production costs for post-patent manufacturers.
Market Restraints
- API supply concentration:China dominates technical-grade glyphosate and paraquat intermediate manufacturing, exposing formulators to input cost volatility and export license unpredictability.
- EU F-Gas and Green Deal constraints:Restrictions on solvent-based emulsifiable concentrates are forcing reformulation investments that erode generic cost advantages in European cereal districts.
- Biopesticide substitution:Bacillus thuringiensis and Trichoderma-based biologicals are capturing share in high-value vegetable systems where residue-free certification commands price premiums.
Strategic Opportunities
- Unguarded rice paddy segments:Wettable powder generics for brown planthopper and stem borer control remain underpenetrated in Vietnam's Mekong Delta and Indonesia's Java irrigation districts.
- Drone application compatibility:Low-viscosity liquid concentrates formulated for unmanned aerial vehicle tank-mixing are opening channel access to service-based spraying cooperatives in Argentina's Pampas.
- India's PLI scheme for agrochemicals:Production-linked incentives for technical-grade manufacturing are attracting capital toward captive synthesis plants in Gujarat's Dahej and Andhra Pradesh's Visakhapatnam clusters.
Industry Challenges
- Registration timeline compression:India's Central Insecticides Board mandates 24-36 month data generation periods for generic equivalence under the Insecticides Act, delaying market entry against patent-expiry schedules.
- Formulation chemist scarcity:Expertise in bio-based adjuvant compatibility and nano-emulsion stability is concentrated among retiring technical staff at legacy agrochemical firms.
- Label harmonization complexity:Divergent buffer zone requirements between Brazil's ANVISA aquatic toxicity assessments and US EPA drift mitigation labeling force dual-registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generic Crop Protection Chemicals Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural Fields, Greenhouses, Turf Management, Horticulture Formulation: Liquid Concentrate, Granules, Wettable Powder, Emulsifiable Concentrate End User: Farmers, Agricultural Cooperatives, Distributors, Research Institutions |
| Companies Covered | Atticus LLC, Generic Crop Science, Sipcam Agro USA, Nufarm Limited, United Phosphorus Ltd, Cheminova, Rotam Agrochemical Company Limited, AMVAC Chemical Co, Albaugh LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generic Crop Protection Chemicals Market Emerging Trajectories
Formulation chemistry is converging with precision application hardware and biological adjuvant science, compressing the traditional separation between synthetic active ingredients and their delivery systems. This convergence is redrawing competitive boundaries around tank-mix compatibility and residue performance rather than molecule novelty alone.
Nano-emulsion and micro-capsule formulation technology is hybridizing synthetic pyrethroids with botanical oil carriers to extend residual activity in tropical humidity conditions. Southeast Asian vegetable cooperatives in Thailand's Chiang Mai and Vietnam's Lam Dong provinces are adopting these hybrid concentrates for diamondback moth programs. The technology is hybridizing cost structures by allowing lower active ingredient loadings per hectare while maintaining efficacy thresholds demanded by export-oriented packing houses.
The EU Green Deal's Farm to Fork strategy is mandating 50% synthetic pesticide reduction targets by 2030, forcing generic manufacturers to reformulate around bio-based solvents and non-ionic surfactants. This regulatory pressure is compressing emulsifiable concentrate shelf life and accelerating degradation studies for new adjuvant combinations. Cereal herbicide generics in France's Beauce and Germany's Magdeburger Börde districts are most affected, with distributors stockpiling pre-reformulation inventories ahead of anticipated registration withdrawals.
Farmer buying committees in Brazil's Mato Grosso and Goiás soybean belts are disintermediating traditional distributor networks through direct tendering to formulation licensees. These committees aggregate 50,000-hectare annual volumes and specify drift-reduction nozzle compatibility and aerial application logistics as contract terms. The practice is most visible in regions where cooperatives operate owned spraying fleets and can enforce application protocol compliance through internal certification programs.
Generic Crop Protection Chemicals Market Segmentation
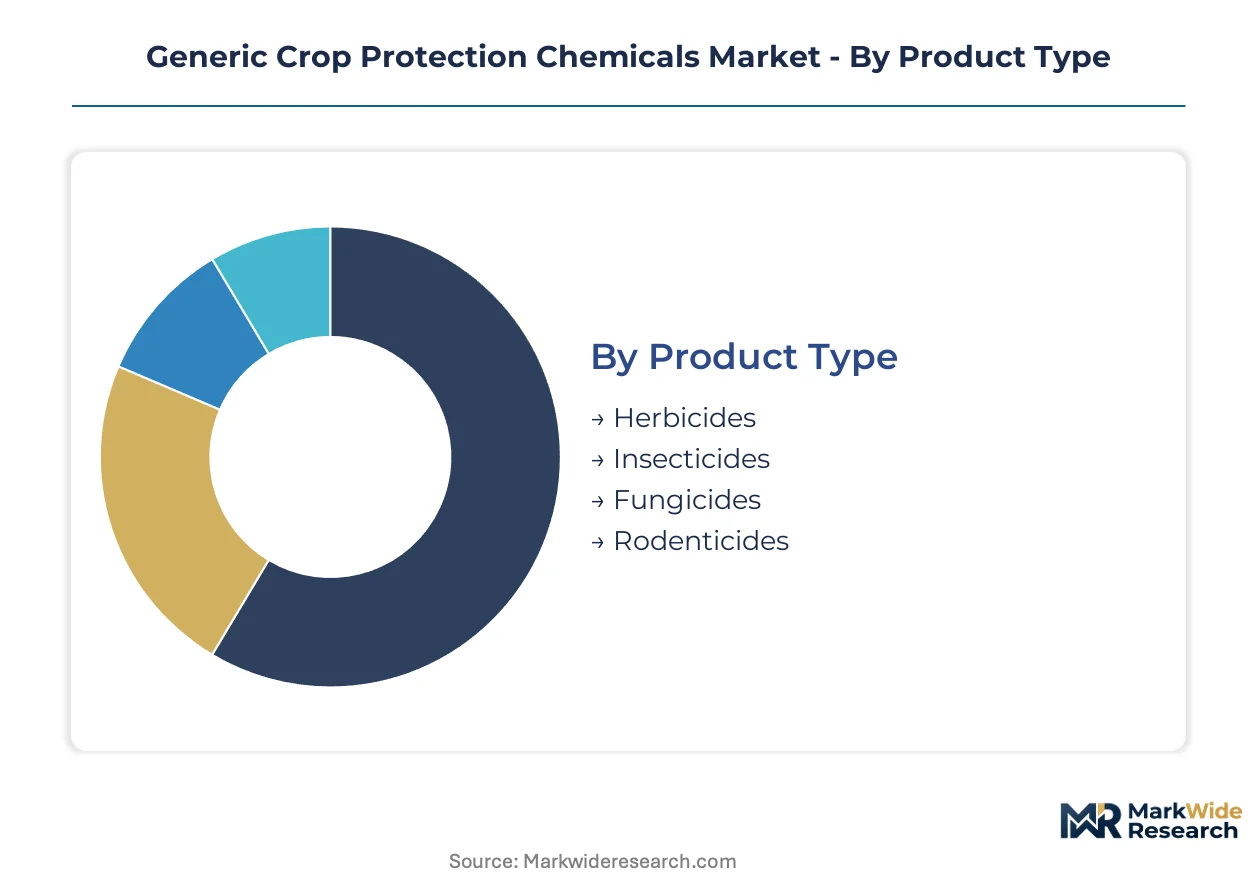
Segmentation in generic crop protection chemicals reveals how margin pools shift across formulation complexity, application protocols, and procurement channel structures. Technical specifications vary sharply between bulk agricultural deployment and precision horticulture systems.
Product Type:
After-sales intensity concentrates in herbicides and insecticides where drift mitigation and resistance management protocols demand ongoing technical support from formulators.
- Herbicides:Glyphosate and paraquat generics dominate procurement volumes for soybean and corn systems. Demand concentrates in Brazil's Mato Grosso and Goiás belts where farmer buying committees specify drift-reduction nozzle compatibility as contract terms.
- Insecticides:Pyrethroid and organophosphate formulations target cotton bollworm and brown planthopper populations. Maharashtra and Gujarat cooperatives bulk-purchase wettable powders for cotton belt applications under India's Insecticides Act registration requirements.
- Fungicides:Azole and strobilurin generics protect cereal and fruit crops against powdery mildew and rust pathogens.
- Rodenticides:Anticoagulant formulations serve grain storage and turf management segments with specialized bait station protocols.
Herbicides hold the largest share; momentum sits with insecticides as resistance management protocols expand advisory service attachments.
Application:
Cost tier stratification separates commodity row-crop deployment from premium horticulture systems where residue-free certification commands price premiums.
- Agricultural Fields:Broad-acre herbicide and insecticide applications across soybean, corn, and cotton systems. ANVISA's tighter glyphosate metabolite monitoring in Brazil is accelerating migration to registered generic alternatives with established MRL documentation.
- Greenhouses:Controlled-environment fungicide and insecticide programs for high-value vegetable and ornamental production. Thailand's Chiang Mai and Vietnam's Lam Dong provinces adopt hybrid nano-emulsion concentrates for diamondback moth control in export-oriented packing houses.
- Turf Management:Selective herbicide and fungicide maintenance for golf courses and municipal landscapes requiring aesthetic performance thresholds.
- Horticulture:Precision insecticide and fungicide programs for fruit and nut orchards where pre-harvest interval constraints shape product selection.
Agricultural fields absorb the dominant volume; horticulture generates the steepest margin expansion as residue-free certification requirements intensify.
Formulation:
Supply concentration in continuous flow chemistry capabilities is redistributing competitive advantage toward manufacturers with backward integration into active ingredient synthesis.
- Liquid Concentrate:Low-viscosity formulations optimized for tank-mixing and aerial application compatibility. Argentina's Pampas spraying cooperatives specify drone-compatible viscosity grades for unmanned aerial vehicle deployment.
- Granules:Controlled-release formulations for soil-applied herbicide and insecticide programs in rice paddy systems.
- Wettable Powder:Solid-phase delivery for water solubility-constrained environments. Vietnam's Mekong Delta and Indonesia's Java irrigation districts favor these formulations for brown planthopper and stem borer control in flooded paddies.
- Emulsifiable Concentrate:Solvent-based systems facing reformulation pressure from EU F-Gas and Green Deal constraints on petroleum-derived carriers.
Liquid concentrate leads volume shipments; wettable powders are gaining share fastest in Southeast Asian rice systems where water management limits liquid delivery options.
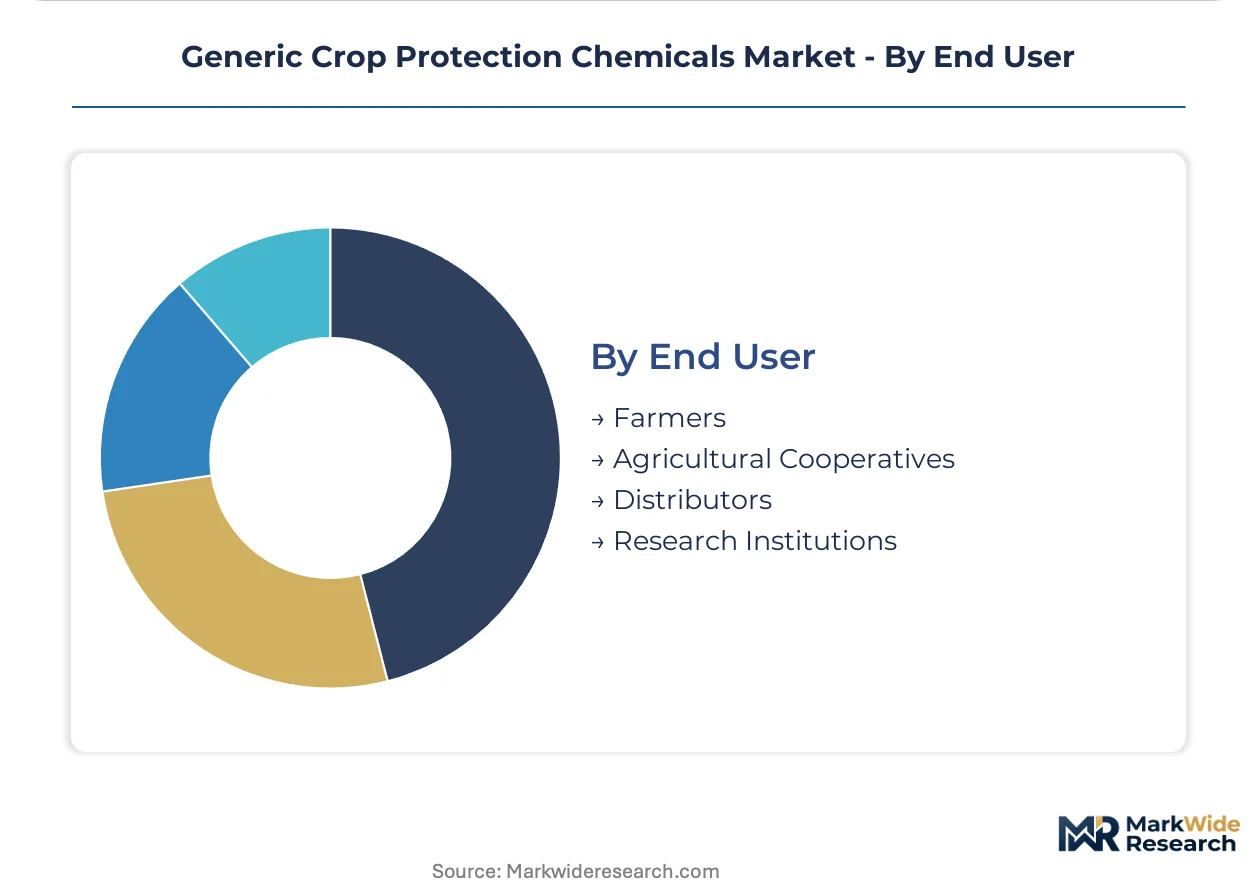
End User:
Procurement consolidation through cooperative structures is compressing distributor margins and elevating price transparency across tender-based purchasing.
- Farmers:Individual operators purchasing through retail distributor networks with label compliance support. India's fragmented distributor network operates under Central Insecticides Board batch testing mandates.
- Agricultural Cooperatives:Consolidated procurement entities aggregating 50,000-hectare annual volumes. Brazil's Mato Grosso cooperatives operate owned spraying fleets and enforce application protocol compliance through internal certification programs.
- Distributors:Regional logistics and credit-extension intermediaries facing disintermediation from direct tendering relationships.
- Research Institutions:Field trial and resistance monitoring programs generating efficacy data for registration submissions.
Agricultural cooperatives command the largest aggregate purchasing volume; farmers retain the broadest geographic coverage across fragmented landholding structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies: emerging market buyers optimize for unit cost per hectare, while European and North American operators absorb premium formulations to satisfy residue certification requirements. This demand bifurcation shapes where generic manufacturers concentrate formulation licensing partnerships versus backward integration investments.
Brazil
Soybean farmer buying committees in Mato Grosso and Goiás aggregate 50,000-hectare procurement volumes, disintermediating traditional distributors through direct tendering to formulation licensees. ANVISA's tighter glyphosate metabolite monitoring accelerates migration to registered generic alternatives with established MRL documentation. The Rondonópolis logistics corridor concentrates blending operations for drift-reduction formulations compatible with aerial spraying fleets.
India
Cotton and soybean cooperatives in Maharashtra and Gujarat consolidate insecticide and herbicide purchases through bulk-tender mechanisms favoring wettable powder generics. The Central Insecticides Board mandates 24-36 month data generation periods for generic equivalence under the Insecticides Act, compressing market entry windows against patent-expiry schedules. Dahej and Visakhapatnam industrial clusters attract PLI-linked capital toward captive technical-grade synthesis plants.
United States
EPA residue tolerance thresholds and drift mitigation labeling requirements elevate formulation compliance costs for row-crop herbicide generics. Private-label suppliers leverage North American manufacturing footprints to serve regional distributor networks with tank-mix-compatible liquid concentrates. The Midwest corn-soybean belt generates concentrated demand for glyphosate alternatives as resistance management protocols expand advisory service attachments.
Germany
EU Green Deal and F-Gas Regulation constraints force reformulation investments around bio-based solvents and non-ionic surfactants, eroding generic cost advantages in cereal districts. The Magdeburger Börde grain region stockpiles pre-reformulation inventories ahead of anticipated registration withdrawals. Continuous flow chemistry capabilities concentrate among legacy agrochemical firms facing formulation chemist scarcity in bio-based adjuvant compatibility.
Vietnam
Mekong Delta rice systems favor wettable powder generics for brown planthopper and stem borer control where water solubility constraints limit liquid delivery options. Nano-emulsion hybrid formulations penetrate export-oriented vegetable cooperatives in Lam Dong province for diamondback moth programs. Drone application compatibility specifications from service-based spraying cooperatives open channel access for low-viscosity liquid concentrate suppliers.
Generic Crop Protection Chemicals Market Vendor Landscape
Capability concentration sits with backward-integrated active ingredient synthesizers; scale advantage sits with formulation licensees operating regional manufacturing footprints. The vendor base stratifies across three tiers: technical-grade producers controlling intermediate supply, regional blenders optimizing logistics proximity, and private-label suppliers serving distributor consolidation. Dominant competitive moves include patent cliff pre-positioning through production partnerships and continuous processing technology adoption to compress unit costs.
Among North American private-label specialists, Albaugh LLC and Atticus LLC occupy positions emphasizing manufacturing footprint leverage for regional distributor supply. Nufarm Limited exemplifies the backward-integrated archetype through captive synthesis capabilities spanning Australian and European production assets. United Phosphorus Ltd represents emerging-market price competition through portfolio breadth across wettable powders and emulsifiable concentrates. These three anchors illustrate how margin pools redistribute toward post-patent production partnerships and away from molecule discovery.
| Leading Market Players |
|---|
| Atticus LLC |
| Generic Crop Science |
| Sipcam Agro USA |
| Nufarm Limited |
| United Phosphorus Ltd |
| Cheminova |
| Rotam Agrochemical Company Limited |
| AMVAC Chemical Co |
| Albaugh LLC |
| Others |
Supply Flow & Price Mechanics
Shandong province's glyphosate technical-grade manufacturing clusters anchor global intermediate supply, translating concentration into pricing leverage over downstream formulators in Brazil and India. Cost pass-through from Chinese export license volatility feeds directly into wettable powder and liquid concentrate quotations across Latin American cooperative procurement tenders.
Pricing Analysis
After-sales revenue from resistance management advisory services and drift-mitigation protocol support drives lifetime value for herbicide and insecticide suppliers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume scale, with Brazil's farmer buying committees commanding standard-tier discounts through 50,000-hectare aggregate volumes. Cost compression in economy-tier emulsifiable concentrates is intensifying because EU F-Gas reformulation mandates erode generic cost advantages. Smallholder farmers in India's fragmented distributor network exhibit highest price sensitivity; export-oriented horticulture cooperatives in Vietnam's Lam Dong province absorb premium-tier hybrid formulations for residue-free certification.
Supply Chain Analysis
Export-control scrutiny on dual-use chemical precursors limits flow of certain organophosphate intermediates from concentrated manufacturing zones. Technical-grade synthesis concentrates in China, India, and Germany, with Shandong and Jiangsu provinces hosting glyphosate and paraquat intermediate production. Formulation draws from petroleum-derived solvents, botanical oil carriers, and non-ionic surfactants facing EU Green Deal substitution mandates. Single-source vulnerability in Chinese glyphosate technical supply exposes formulators to input cost volatility and export license unpredictability. Distribution runs through regional blender networks and cooperative direct-tender channels, bypassing traditional distributor intermediaries in Brazil's Mato Grosso belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic crop protection chemicals are approaching a platform-economics inflection where formulation compatibility with precision application hardware and biological adjuvant interoperability determines competitive boundaries. Tank-mix standardization and drone-spraying protocol convergence reshape value capture around delivery-system integration rather than molecule novelty alone.
For Market Incumbents: Build regulatory data moats by pre-positioning MRL compliance documentation ahead of ANVISA's tightening glyphosate metabolite protocols in Brazil. Secure backward integration into active ingredient synthesis through captive technical-grade plants in India's Dahej and Visakhapatnam clusters to defend against API supply concentration risk from Chinese intermediate dominance. Expand continuous flow chemistry capabilities to compress unit costs against emerging continuous processing entrants.
For New Entrants and Emerging Players: Build out drone-compatible low-viscosity liquid concentrate formulations targeting Argentina's Pampas spraying cooperatives and Vietnam's Mekong Delta service-based aerial application providers. Underpenetrated wettable powder segments for brown planthopper control in Indonesia's Java irrigation districts offer lowest competitive density. Partner with farmer buying committees in Brazil's Goiás belt on direct-tender contracts specifying drift-reduction nozzle compatibility as contract terms.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated formulators with captive synthesis capabilities spanning multiple regulatory jurisdictions. Long-term viability hinges on navigating EU Green Deal solvent reformulation mandates and biopesticide substitution pressure in high-value vegetable systems. Acquisition targets should demonstrate continuous processing technology adoption and established registration pathways under India's Insecticides Act. Watch for inflection signals in India's PLI scheme disbursement rates toward technical-grade manufacturing as capital allocation indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive technical-grade production in Gujarat's Dahej cluster reduces exposure to Chinese export license volatility. |
| Continuous Flow Chemistry Adoption | Shift from batch synthesis compresses active ingredient production costs for post-patent manufacturers meeting FAO/WHO specifications. |
| Drone Application Formulation Development | Low-viscosity concentrates compatible with unmanned aerial vehicles open channel access to Argentina's Pampas spraying cooperatives. |
| EU Green Deal Reformulation Investment | Bio-based solvent and non-ionic surfactant substitution preserves registration access in German cereal districts facing F-Gas constraints. |
| Cooperative Direct-Tender Partnerships | Brazil's Mato Grosso farmer buying committees aggregate 50,000-hectare volumes and specify drift-reduction compatibility terms. |
Methodological Framework
Operator-level perspectives from formulation chemists at legacy agrochemical firms, procurement leads at Brazilian agricultural cooperatives, regulatory affairs specialists navigating India's Central Insecticides Board, and technical directors at continuous processing equipment suppliers anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, FAO/WHO specification databases, ANVISA registration filings, and SEC 10-K disclosures from publicly traded agrochemical manufacturers. Bottom-up volume modeling across formulation types and top-down market sizing through production capacity assessments were triangulated for convergence.
Scenario-bracketing around patent cliff timing, regulatory harmonization pressures, and biopesticide substitution rates bounded the projection range across the analysis window. Segmentation dimensions modeled include product type, formulation complexity, application protocol, and procurement channel structure. CAGRs were derived from slope analysis of historical volume trajectories adjusted for structural shift parameters including continuous processing adoption curves and cooperative procurement consolidation rates. Industry-specific inputs encompassed ANVISA residue protocol implementation timelines and India's PLI scheme capital attraction patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese technical-grade manufacturers or accelerated EU registration withdrawals would shift outcomes. Material shifts in Brazil's glyphosate metabolite enforcement intensity, Indian cooperative procurement centralization, or bio-based adjuvant technology maturation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Global Acephate Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
South America Molluscicides Market
Crop Protection
Grain Protectant Market
Crop Protection
Dicamba Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Tembotrione Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
US Pest Control Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
China Fungicide Market