
 Indonesia Crop Protection Chemicals Market | 2026-2036
Indonesia Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Crop Protection Chemicals Market Intelligence
Subscription-based agronomic advisory bundled with chemical purchases is restructuring how Indonesian distributors capture farmer loyalty. Bayer AG leverages its digital farming platform to embed crop protection within seasonal input packages. PT Biotis Agrindo anchors its position through localized formulation facilities serving Sumatran oil palm and rubber estates. Syngenta Group competes via integrated seed-to-harvest protocols that lock in recurring chemical volumes across Kalimantan corn belts.
Indonesia crop protection chemicals comprise synthetic and biological formulations engineered to control weeds, insects, fungi, and rodents across tropical agroecosystems, with active ingredients typically formulated as emulsifiable concentrates, wettable powders, or granules for foliar or soil application. Herbicides command the largest product-type share as palm oil and rice farmers battle glyphosate-resistant weed complexes, while insecticides represent the fastest-expanding margin pool amid fall armyworm and whitefly pressure in horticulture. The distribution channel structure tilts toward wholesale networks supplying agricultural cooperatives, though direct sales to plantation conglomerates capture premium pricing through volume commitments and technical service bundling.
Indonesia's Ministry of Agriculture pesticide registration protocols, aligned with FAO/WHO Codex standards and ASEAN harmonization frameworks, determine which active ingredients gain market access and dictate label restrictions for aquatic buffer zones. The country's national food security agenda, enforced through BPSB (Plant Quarantine Agency) import permits and provincial extension mandates, channels procurement toward domestically formulated products. Stakeholders must track how pending restrictions on neonicotinoid and paraquat formulations will reshape portfolio composition and accelerate biological substitute development before regulatory deadlines crystallize.
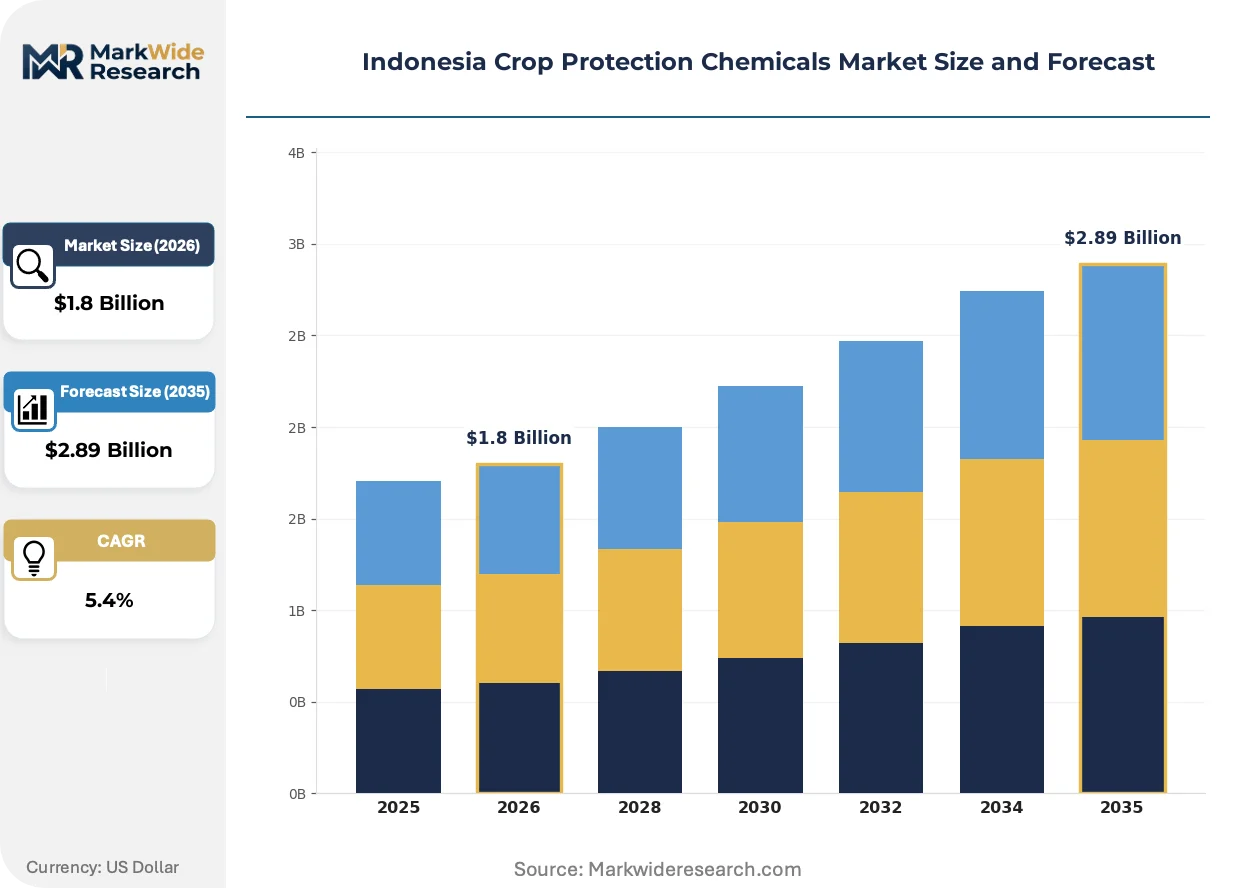
Market Dynamics
Indonesia's Ministry of Agriculture pesticide registration protocols are compressing product entry timelines and forcing reformulation investments ahead of neonicotinoid and paraquat restriction deadlines.
Growth Catalysts
- East Java cooperative procurement networks:Bulk purchasing agreements through agricultural cooperatives in Surabaya-Malang corridors aggregate smallholder demand into volume commitments that justify distributor technical service investments.
- FAO/WHO Codex alignment:Harmonization with ASEAN regulatory frameworks accelerates registration reciprocity and reduces redundant safety studies for imported active ingredients.
- Fall armyworm pressure:Spodoptera frugiperda infestations across Kalimantan corn belts generate recurring insecticide demand that locks growers into seasonal application protocols.
Market Restraints
- Active ingredient import dependency:Technical-grade glyphosate and 2,4-D concentrate imports from China expose formulators to shipping cost volatility and currency fluctuation risks.
- BPSB quarantine bottlenecks:Plant Quarantine Agency import permit processing creates 4-8 week delays that disrupt just-in-time inventory management for plantation conglomerates.
- Biological substitute efficacy gaps:Beauveria bassiana and Trichoderma formulations underperform against established synthetic chemistries in high-humidity tropical conditions, limiting grower switching.
Strategic Opportunities
- Sumatran oil palm estate digitization:Drone-based variable-rate application systems create precision agriculture service bundles that embed crop protection within aerial spraying contracts.
- Domestic formulation capacity expansion:Provincial tax incentives for manufacturing facilities in Batam and Medan enable tariff-free re-export positioning into Malaysian and Thai markets.
- Biologicals registration fast-track:Ministry of Agriculture's 2023-2026 sustainable agriculture roadmap prioritizes microbial pesticide approvals with abbreviated field trial requirements.
Industry Challenges
- Residue monitoring laboratory capacity:BPSB's limited testing infrastructure for MRL compliance verification creates shipment detention risks for export-oriented horticulture growers supplying Japanese and South Korean buyers.
- Extension officer technical training:Provincial agriculture departments lack sufficient field staff trained in integrated pest management protocols to support biological adoption at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Crop Protection Chemicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Crops, Orchards, Vineyards, Greenhouses Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Agricultural Companies, Farmers, Co-operatives, Exporters |
| Companies Covered | UPL Limited, Corteva Agriscience, Syngenta Group, Nufarm Ltd, ADAMA Agricultural Solutions Ltd, Bayer AG, FMC Corporation, PT Biotis Agrindo, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Crop Protection Chemicals Market Strategic Shifts & Innovations
Digital agronomy platforms are restructuring how Indonesian distributors capture farmer loyalty through bundled advisory-chemical service contracts.
RNA interference-based biopesticides are consolidating research pipelines as Bayer AG and Syngenta Group prioritize dsRNA formulations targeting lepidopteran pests in rice and corn systems. Sumatran plantation conglomerates are piloting these chemistries through exclusive technical partnerships that lock in multi-year supply commitments. The technology is consolidating competitive advantage around firms with proprietary delivery mechanisms and local fermentation capacity.
Indonesia's Ministry of Agriculture neonicotinoid phase-out mandates, aligned with EU REACH restrictions on pollinator-toxic active ingredients, are forcing portfolio recomposition toward sulfoximine and diamide chemistries. Formulators must complete reregistration dossiers for replacement molecules before 2026 enforcement deadlines. Kalimantan horticulture belts face the steepest adjustment costs due to whitefly management protocol dependencies.
Cooperative-led input financing is displacing traditional distributor credit arrangements across Java's rice intensification zones. Koperasi Unit Desa village cooperatives now aggregate member demand and negotiate seasonal payment terms directly with multinational suppliers, compressing independent retailer margins. This concentration is most visible in Banyuwangi and Jember districts where cooperative membership exceeds 70 percent of registered growers.
Indonesia Crop Protection Chemicals Market Segmentation
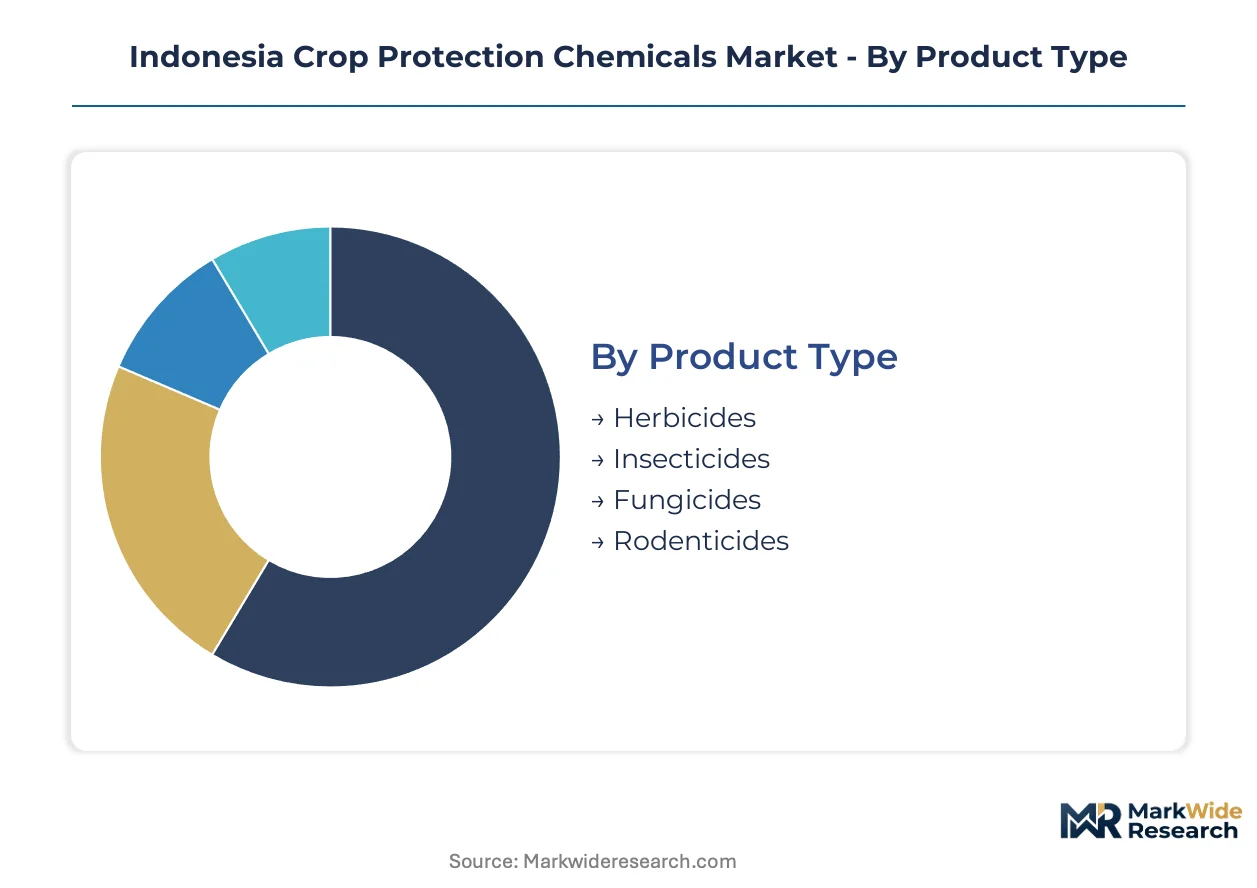
Segmentation reveals how capital deployment, regulatory exposure, and procurement power concentrate across Indonesia's crop protection value chain. Each dimension exposes distinct margin structures and entry barriers that shape competitive positioning.
Product Type:
Capital intensity varies sharply across chemistries, with synthesis complexity and registration costs determining which segments attract multinational investment versus domestic formulation.
- Herbicides:Glyphosate-based formulations dominate volume, requiring substantial investment in technical-grade import infrastructure and blending facilities. Demand clusters in Sumatran oil palm estates where resistant weed complexes drive repeated application cycles.
- Insecticides:These chemistries command premium pricing amid fall armyworm pressure across Kalimantan corn belts. Formulators must navigate neonicotinoid phase-out mandates while scaling replacement molecule production.
- Fungicides:Wettable powder formulations target rice blast and sheath rot in Java's intensive paddies, with seasonal humidity dictating application windows.
- Rodenticides:Zinc phosphide and anticoagulant baits serve plantation perimeter management, concentrated in estate conglomerates with integrated pest control protocols.
Herbicides absorb the bulk of installed capacity; insecticides are expanding most quickly.
Application:
Application setting determines service bundling potential and technical advisory intensity, with open-field crops offering scale economies against protected structures demanding precision delivery.
- Crops:Rice, corn, and palm oil dominate tonnage, with cooperative procurement aggregating smallholder demand into volume commitments that justify distributor technical investments.
- Orchards:Citrus and mango operations in East Java require specialized spray equipment and buffer zone compliance for export market access.
- Vineyards:Limited acreage concentrates in Bali and North Sumatra highlands, serving tourism-integrated wine production with boutique chemical requirements.
- Greenhouses:Controlled-environment horticulture in West Java demands low-residue formulations and integrated pest management protocols for premium supermarket supply chains.
Crop applications command the greatest formulation throughput; greenhouse systems are climbing the fastest on biological adoption rates.
Distribution Channel:
Channel selection reflects buyer scale and credit access, with plantation conglomerates bypassing intermediaries while smallholders depend on cooperative aggregation.
- Wholesale:Agricultural cooperative networks in Surabaya-Malang corridors aggregate village-level demand into bulk purchasing agreements that secure preferential pricing and technical service bundling.
- Retail:Independent agro-dealers serve dispersed smallholders with credit terms tied to harvest cycles, compressing margins through inventory carrying costs.
- Online:E-commerce platforms emerging in Java's urban periphery offer price transparency and input financing, though logistics constraints limit penetration to peri-urban zones.
- Direct Sales:Plantation conglomerates negotiate multi-year supply contracts with formulators, embedding aerial application services and residue monitoring within volume commitments.
Wholesale channels handle the majority of volume throughput; direct sales are gaining share fastest among estate consolidation.
End User:
End-user category shapes pricing power and technical service expectations, with exporter compliance requirements driving premium formulation demand.
- Agricultural Companies:Integrated plantation operators in Riau and North Sumatra specify active ingredient concentrations and application protocols, capturing economies through captive spraying services.
- Farmers:Smallholder rice growers in Central Java depend on provincial extension networks for application timing guidance, with input costs absorbing significant share of operating budgets.
- Co-operatives:Koperasi Unit Desa village cooperatives in Banyuwangi and Jember districts aggregate member demand to negotiate seasonal payment terms directly with suppliers.
- Exporters:Horticulture growers supplying Japanese and South Korean markets require MRL-compliant formulations and BPSB residue certification, accepting premium pricing for documentation integrity.
Co-operatives channel the largest collective procurement volume; exporters are expanding fastest on compliance-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's crop protection chemicals production concentrates in Java and Sumatra formulation facilities, while consumption spreads across archipelago farming belts with distinct regulatory and procurement profiles shaping regional demand patterns.
Java
East Java's Surabaya-Malang corridor anchors national rice intensification with cooperative-led bulk procurement aggregating smallholder demand. Provincial agriculture departments enforce BPSB quarantine protocols for import permit processing. Formulation plants in Sidoarjo and Gresik blend technical-grade concentrates for distribution across Central Java's paddies.
Sumatra
North Sumatra's oil palm estates drive herbicide volume through resistant weed management protocols requiring repeated glyphosate applications. The Ministry of Agriculture's pesticide registration requirements dictate active ingredient approvals for estate conglomerates. Medan-based facilities serve Riau plantation clusters with captive spraying service bundles.
Kalimantan
Central Kalimantan's corn belts generate insecticide demand from fall armyworm pressure across commercial farming zones. Provincial extension mandates channel procurement toward domestically formulated products under national food security agendas. Sampit and Palangka Raya distribution hubs supply seasonal application protocols to grower cooperatives.
Sulawesi
South Sulawesi's horticulture belts require low-residue formulations for export-oriented cocoa and vegetable production. BPSB residue certification protocols create compliance costs for growers supplying Japanese and South Korean buyers. Makassar logistics corridors connect to Bitung port facilities for chemical import handling.
Indonesia Crop Protection Chemicals Market Key Industry Players
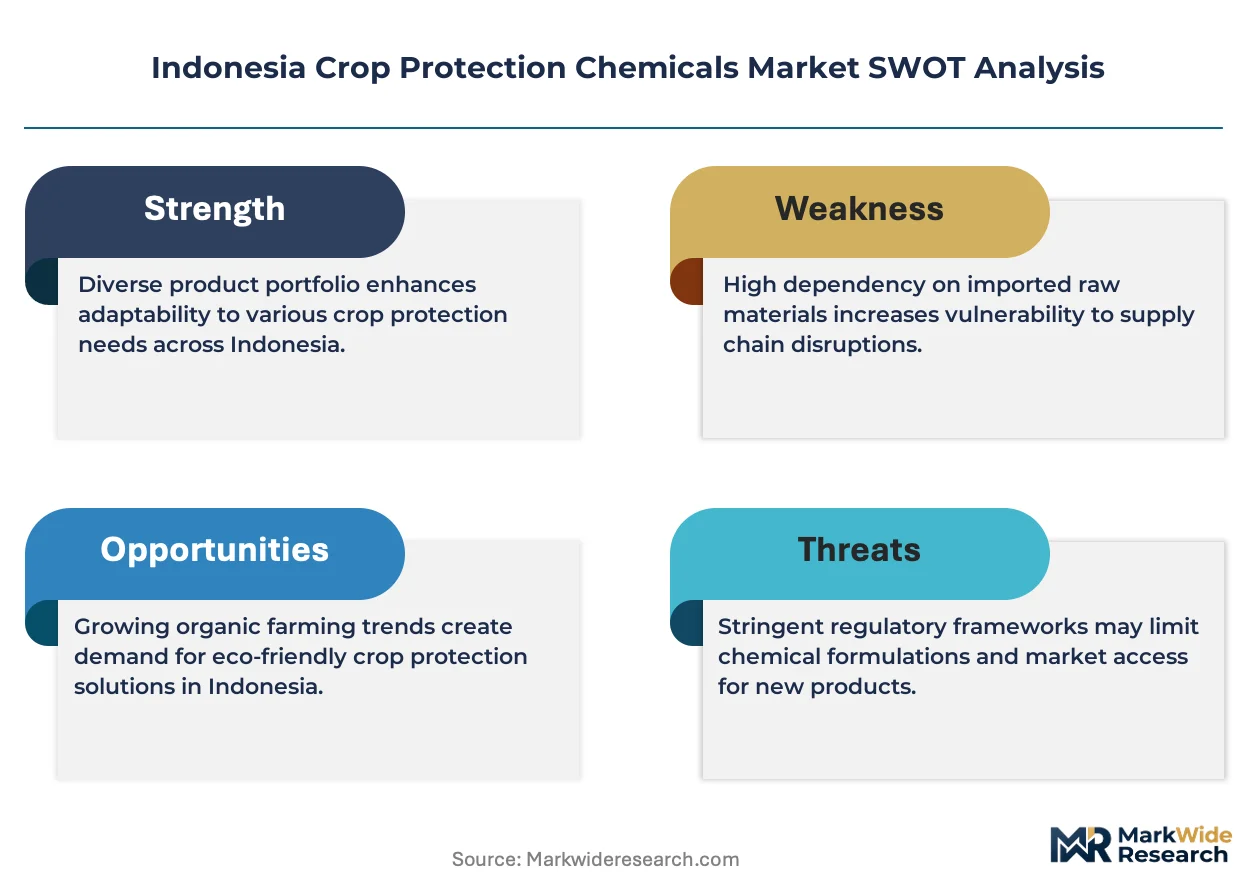
Top-tier vendors anchor multinational portfolios, while domestic formulators capture regional estate relationships through localized blending capacity and cooperative network penetration. The market structure tilts toward consolidated upstream active ingredient supply and fragmented downstream distribution. Three archetypes dominate: integrated agrochemical conglomerates with seed-to-harvest platforms, regional formulation specialists with plantation service contracts, and cooperative-integrated distributors with village-level credit arrangements. Capacity expansion in Batam and Medan tax-free zones and biological substitute development ahead of neonicotinoid deadlines represent the dominant competitive moves.
Within the multinational tier, Bayer AG and Syngenta Group exemplify integrated platform strategies embedding digital advisory within chemical procurement cycles. PT Biotis Agrindo occupies a position as the domestic specialist archetype, anchoring Sumatran estate relationships through localized formulation infrastructure. UPL Limited and ADAMA Agricultural Solutions Ltd represent the generic-active-ingredient scale players competing on technical-grade import efficiency and broad-spectrum portfolio breadth.
| Leading Market Players |
|---|
| UPL Limited |
| Corteva Agriscience |
| Syngenta Group |
| Nufarm Ltd |
| ADAMA Agricultural Solutions Ltd |
| Bayer AG |
| FMC Corporation |
| PT Biotis Agrindo |
| BASF SE |
| Others |
Cost & Logistics Intelligence
RNA interference-based biopesticide manufacturing is consolidating production economics around firms with proprietary fermentation capacity, simultaneously compressing formulation margins for generic-active-ingredient importers and concentrating supply power among integrated agrochemical conglomerates with captive bioprocessing infrastructure.
Pricing Analysis
Margin tightening in the insecticide tier reflects neonicotinoid phase-out mandates from Indonesia's Ministry of Agriculture forcing accelerated reregistration investments for replacement sulfoximine and diamide chemistries. Three-tier pricing structure across premium, standard, and economy levels separates MRL-compliant export formulations from domestic-grade wettable powders and unbranded generic concentrates. Price differentiation traces to certification grade and volume scale, with plantation conglomerates capturing economies through multi-year offtake commitments while cooperative-aggregated smallholders face higher per-unit costs. Cost-down pressure on standard-tier herbicides accelerates because Chinese technical-grade glyphosate import volatility feeds directly into domestic blender margins.
Supply Chain Analysis
Technical-grade active ingredient supply rests on Chinese chemical manufacturers for glyphosate and 2,4-D concentrates, Indian specialty producers for pyrethroid intermediates, and German agrochemical majors for proprietary sulfoximine molecules. Raw material dependencies span petrochemical feedstocks, phosphorus derivatives, and microbial fermentation substrates for biological substitute development. Single-source vulnerability concentrates in the Surabaya-Gresik formulation corridor where port congestion and BPSB quarantine processing create inventory disruption risks for plantation just-in-time protocols. Distribution runs through agricultural cooperative networks in East Java's Surabaya-Malang corridor aggregating village-level demand, with direct sales channels serving Sumatran estate conglomerates through captive aerial application service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's crop protection chemicals market is consolidating around integrated platform providers as neonicotinoid and paraquat regulatory deadlines force portfolio recomposition investments that weaker domestic formulators cannot fund.
For Market Incumbents: To counter cooperative-led procurement concentration in East Java's rice belts, Bayer AG and Syngenta Group should deepen backward integration into domestic formulation capacity through Batam and Medan tax-free zone facilities, while embedding digital agronomy advisory within seasonal input packages to lock in recurring chemical volumes. Channel control through Koperasi Unit Desa direct negotiation relationships represents the critical defensive lever against margin compression from independent retailer displacement. For New Entrants and Emerging Players: Launch via biologicals registration fast-track pathways under Indonesia's Ministry of Agriculture sustainable agriculture roadmap, targeting Beauveria bassiana and Trichoderma efficacy gaps in high-humidity tropical conditions where established synthetic chemistries face phase-out pressure. Kalimantan horticulture belts present the most penetrable geography given whitefly management protocol dependencies and limited incumbent biological substitution portfolios. A go-to-market angle anchored to drone-based variable-rate application service bundles bypasses cooperative procurement gatekeepers through direct estate relationships. For Investors and Strategic Acquirers: Re-rating potential sits with regional formulation specialists possessing Sumatran plantation service contracts and localized blending infrastructure, given Ministry of Agriculture mandates channeling procurement toward domestically formulated products under national food security agendas. Long-term viability over a multi-year horizon favors targets with captive biological fermentation capacity and neonicotinoid replacement molecule registration dossiers ahead of enforcement deadlines. The signal to watch is BPSB residue certification laboratory capacity expansion announcements affecting export-oriented horticulture grower compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Formulation Capacity Expansion | Provincial tax incentives in Batam and Medan enable tariff-free re-export positioning into Malaysian and Thai markets. |
| Biologicals Registration Fast-Track | Ministry of Agriculture's sustainable agriculture roadmap prioritizes microbial pesticide approvals with abbreviated field trial requirements. |
| Drone-Based Precision Agriculture Service Bundles | Sumatran oil palm estate digitization embeds crop protection within aerial spraying contracts locking in multi-year supply commitments. |
| Cooperative-Led Input Financing Displacement | Koperasi Unit Desa village cooperatives in Banyuwangi and Jember districts now negotiate seasonal payment terms directly with multinational suppliers. |
| RNA Interference Biopesticide Technical Partnerships | Exclusive multi-year supply commitments with plantation conglomerates consolidate competitive advantage around proprietary delivery mechanisms. |
Research Approach
Multi-period observation of cooperative procurement volume trends, BPSB import permit processing delays, and neonicotinoid replacement molecule registration timelines anchored the trend analysis, supplemented by interviews with formulation plant managers, agricultural cooperative procurement leads, plantation technical directors, Ministry of Agriculture regulatory affairs officers, and distribution channel partners. Secondary validation drew from Indonesia Central Bureau of Statistics agricultural input surveys, ASEAN harmonization framework documentation, FAO pesticide trade databases, and customs import records. Bottom-up triangulation across product-type demand aggregation and top-down validation through national food security agenda implementation tracking ensured analytical consistency.
Segment-weighting across the analysis window applied product-type splits for herbicides, insecticides, fungicides, and rodenticides; application settings spanning rice, corn, palm oil, and horticulture; distribution channel differentiation between cooperative wholesale and direct estate sales; and end-user categories distinguishing smallholder farmers from integrated plantation operators. CAGRs were derived through exponential growth modeling calibrated to historical import volume trajectories and provincial extension mandate intensity. Forecast inputs incorporated fall armyworm pressure severity indices and biological substitute efficacy trial outcomes.
Regulatory deadline acceleration, biological formulation performance volatility in tropical humidity, and BPSB laboratory capacity constraints are the dominant revision risks that could alter trajectory assumptions. A small set of named triggers including neonicotinoid enforcement timing and cooperative membership growth rates warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Crop Bactericides Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Pest Control Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Global Turf Protection Market
Crop Protection
Spain Crop Protection Chemicals Market