
 US Pest Control Market | 2026-2036
US Pest Control Market Size, Share, and Industry Trends Forecast 2026-2036
US Pest Control Market Outlook
Market Overview
Remote monitoring sensor networks and predictive analytics platforms are reshaping how pest management programs are deployed across commercial and residential portfolios. Rollins Inc. (Orkin) leverages its proprietary digital routing system to optimize technician dispatch density in urban corridors. Rentokil North America sustains competitive positioning through its integrated pest management protocols and IoT-enabled bait station networks. Arrow Exterminators anchors regional strength across the southeastern United States through employee ownership models and localized service infrastructure.
US pest control encompasses the professional management, elimination, and prevention of arthropod, rodent, and wildlife infestations through chemical, biological, mechanical, and cultural interventions, typically applied at threshold-based treatment intervals measured in days or weeks depending on pest pressure and seasonal biology. The industry's primary commercial purpose centers on protecting property integrity, ensuring food safety compliance, and reducing vector-borne disease transmission risk in built environments. Residential service contracts generate recurring revenue streams with high retention characteristics, while commercial accounts command premium pricing due to audit-driven compliance requirements in food processing, hospitality, and healthcare facilities. Termite control represents the most structurally intensive segment, with subterranean species causing disproportionate property damage in humid climates and driving substantial repair-linked indemnity exposure.
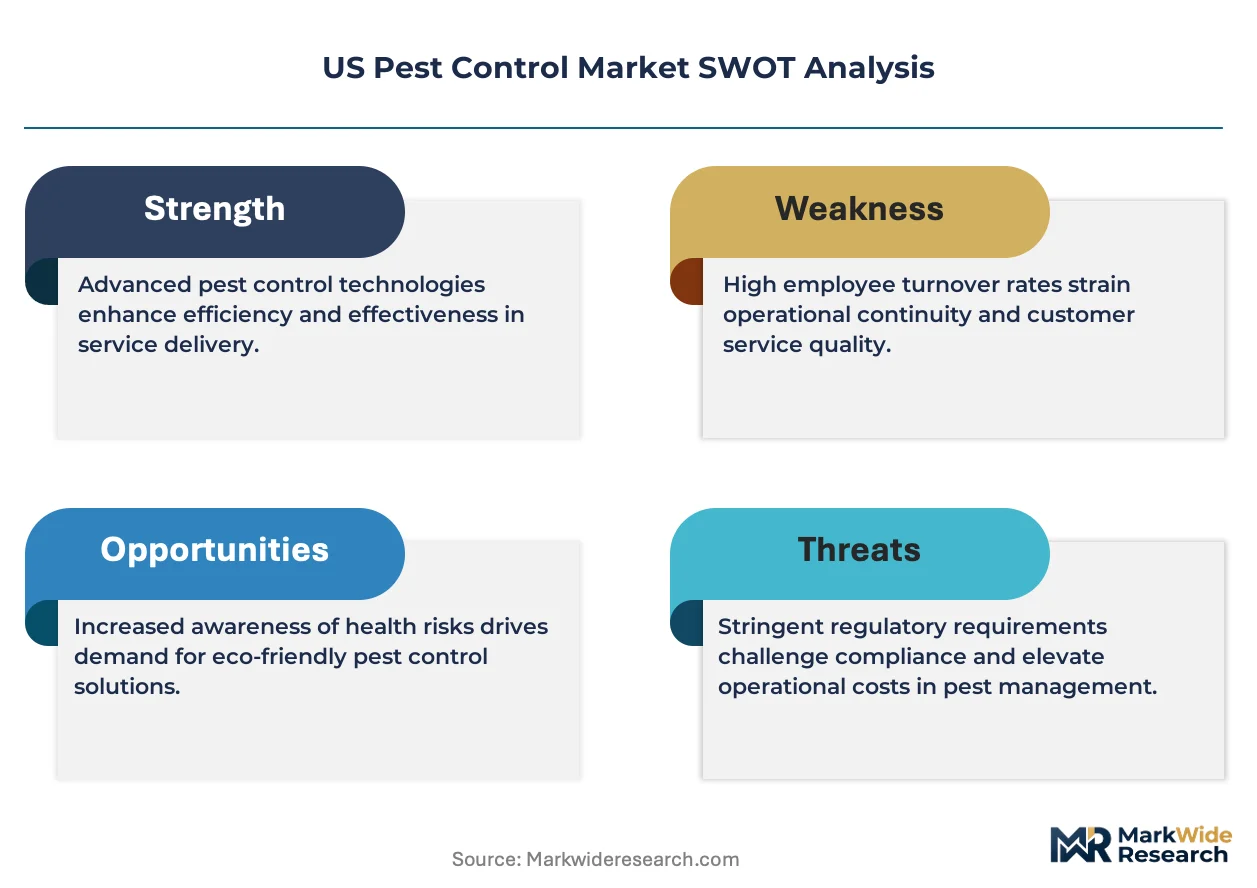
EPA registration requirements under FIFRA govern all pesticide products deployed in US pest control operations, while OSHA standards mandate worker protection during fumigation and confined-space treatments. State-level structural pest control boards in California, Texas, and Florida impose additional licensing, continuing education, and record-keeping obligations that raise barriers to market entry. Stakeholders must monitor evolving restrictions on neonicotinoid and pyrethroid chemistries, as regulatory pressure on conventional active ingredients accelerates investment in biological alternatives and precision application technologies.
Market Dynamics
The US pest control sector faces intensifying EPA scrutiny under FIFRA's amended registration review timelines, forcing operators to accelerate biological formulation R&D while maintaining service density in high-pressure Sun Belt corridors.
Growth Catalysts
- Vector-borne disease surveillance mandates:State health departments in Florida and Texas now require documented mosquito population monitoring for commercial properties, expanding recurring service contract scope.
- Neonicotinoid restrictions:EPA cancellation proceedings for clothianidin and thiamethoxam are redirecting R&D investment toward microbial pesticides and insect growth regulators.
- Food safety audit proliferation:Third-party certification programs like BRC and SQF now embed pest management scorecards, tightening vendor qualification standards for processing facilities.
Market Restraints
- Pyrethroid supply concentration:Active ingredient manufacturing for bifenthrin and permethrin concentrates among Chinese chemical producers exposes distributors to tariff volatility and shipping disruptions.
- Labor certification bottlenecks:State structural pest control boards in California and Florida impose 40-hour pre-licensure training requirements that constrain technician pipeline expansion.
- Biological efficacy gaps:Beauveria bassiana and Metarhizium anisopliae formulations demonstrate inconsistent performance in high-humidity subterranean termite applications.
Strategic Opportunities
- Smart building integration:IoT-enabled pheromone traps linked to facility management platforms create subscription data revenue streams beyond chemical application.
- Wildlife exclusion services:Urban raccoon and bat intrusion complaints in Atlanta and Houston metro areas outpace qualified operator availability.
- Green building certification alignment:LEED v4.1's integrated pest management prerequisites position certified providers for municipal and institutional procurement preferences.
Industry Challenges
- Entomological specialization scarcity:Urban entomology graduate programs at Purdue and Texas A&M produce fewer than 150 master's-qualified candidates annually against industry demand.
- Fumigation liability exposure:Sulfuryl fluoride application requires $5 million minimum general liability coverage that squeezes margin for mid-market operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pest Control Market |
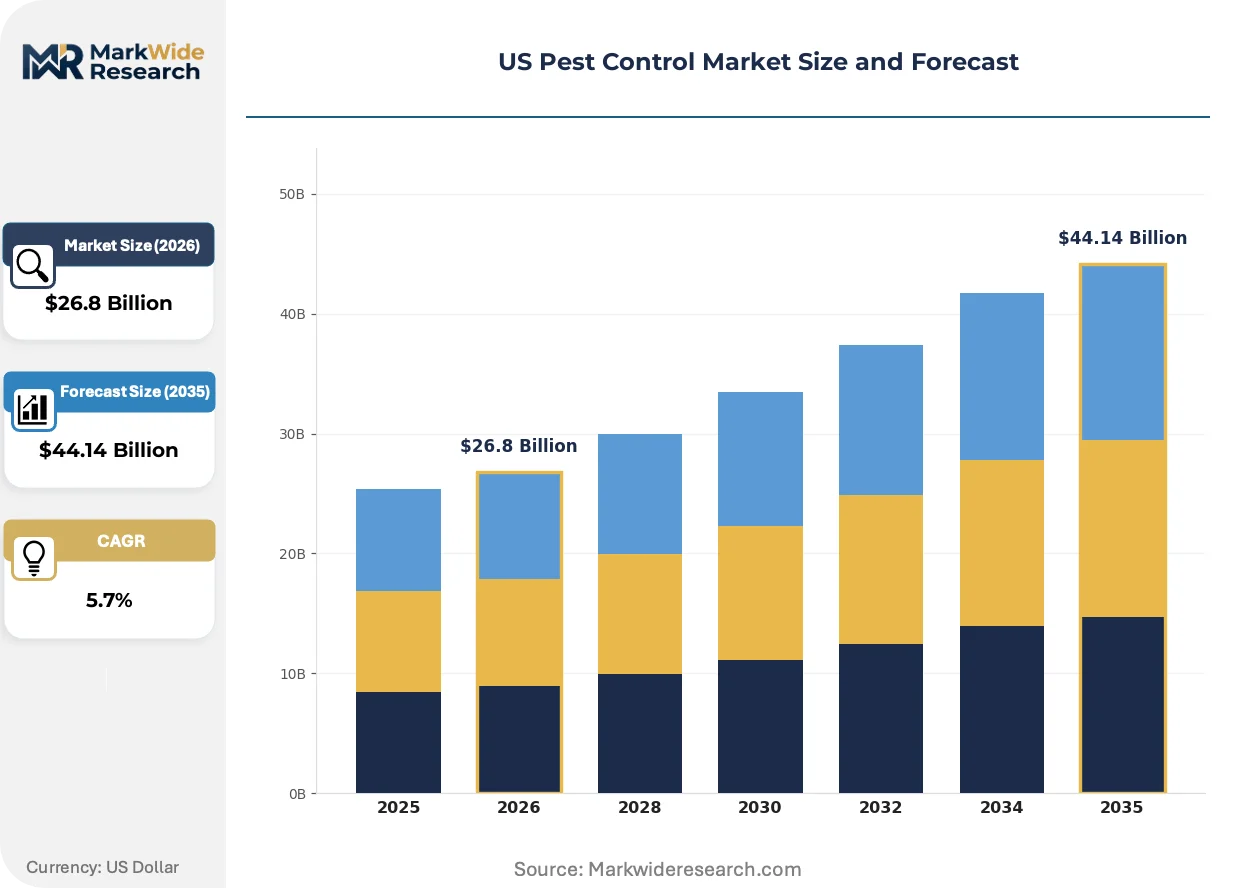
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $44.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Agricultural, Industrial Control Method: Chemical, Biological, Mechanical, Cultural Pest Type: Rodents, Insects, Wildlife, Termites End User: Homeowners, Businesses, Farmers, Landlords |
| Companies Covered | Rentokil North America, Arrow Exterminators, Rollins Inc. (Orkin), Cook's Pest Control, Truly Nolen, Terminix Global Holdings, Massey Services Inc., HomeTeam Pest Defense, Ecolab Pest Elimination, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pest Control Market Strategic Shifts
Digital sensing infrastructure and predictive biology platforms are compressing treatment intervals while elevating technician productivity metrics across residential and commercial service portfolios.
Remote monitoring sensor networks is migrating from perimeter termite bait stations toward interior rodent trap arrays in food processing facilities. Multi-site operators in the Midwest are deploying cellular-connected snap traps that transmit catch alerts within 90 seconds, reducing facility downtime and audit documentation labor. This sensor density is enabling outcome-based billing models that tie service fees to verified pest absence rather than scheduled visits.
EPA's 2024 revised ecological risk assessment for pyrethroids is accelerating formulation transitions toward botanical oils and silica-based desiccants. Product manufacturers face 18-month re-registration deadlines that compress R&D cycles and favor larger chemical houses with dedicated regulatory affairs divisions. California's Department of Pesticide Regulation has preemptively restricted bifenthrin concentrations below federal thresholds, creating state-specific product SKUs that fragment inventory management.
Procurement centralization among national property management firms is consolidating vendor panels and compressing contract renewal cycles from annual to quarterly performance reviews. Institutional buyers now demand real-time dashboard access to trap activity and pesticide application logs, displacing paper-based service tickets. This transparency requirement is most pronounced among REITs with Sun Belt multifamily exposure, where online review sensitivity amplifies pest complaint consequences.
US Pest Control Market Segmentation
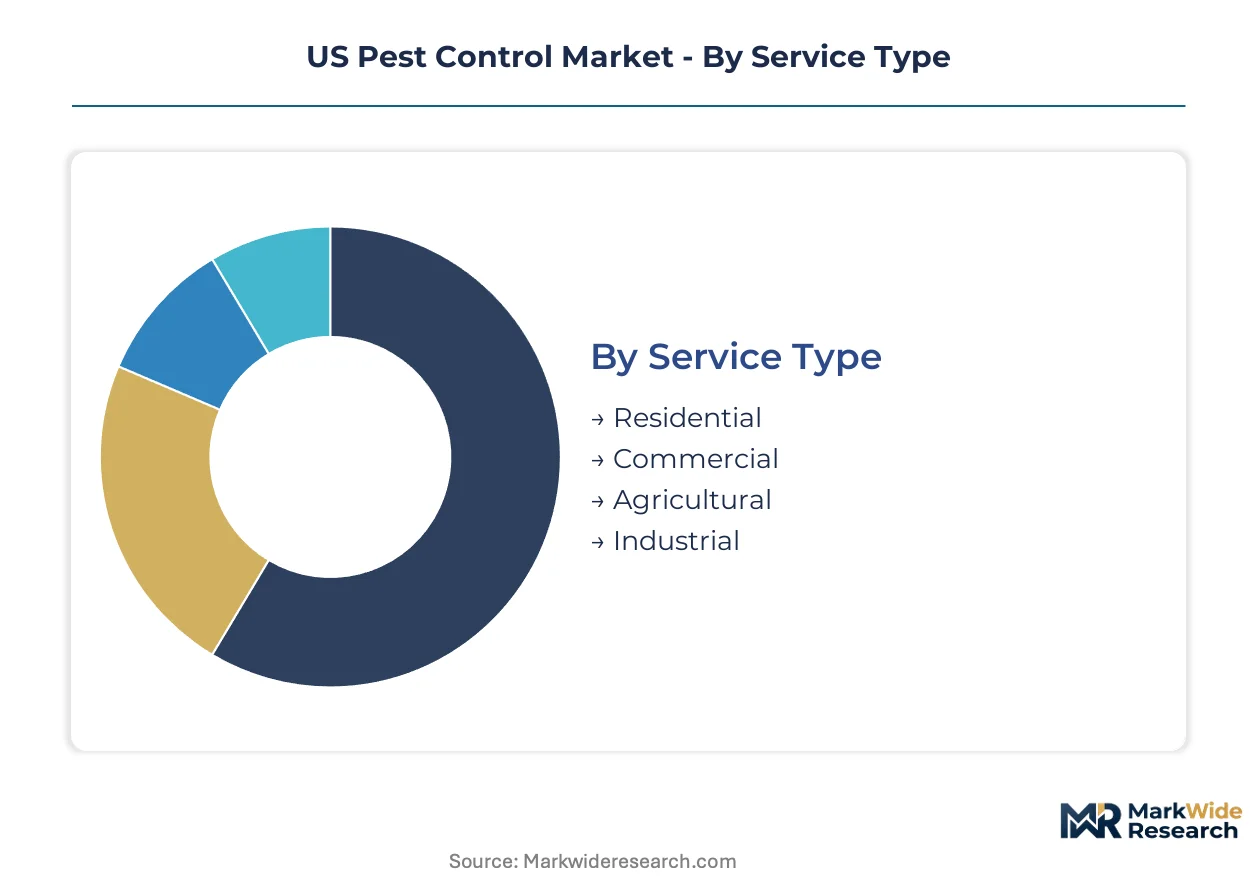
Pest control segmentation reveals distinct operational economics across service delivery models, with contract structure and compliance intensity varying sharply between residential subscriptions and commercial audit-driven accounts. Understanding these divides illuminates where technology investment and technician specialization generate differential returns.
Service Type:
Residential contracts anchor recurring revenue through annual subscriptions with high retention, while commercial accounts demand specialized protocols for food safety and healthcare compliance.
- Residential:Single-family and multifamily homeowners purchase quarterly or monthly perimeter treatments with termite warranty riders. Sun Belt states sustain year-round service frequency due to subterranean termite pressure and mosquito breeding cycles.
- Commercial:Food processing plants, hospitality chains, and healthcare facilities require documented integrated pest management plans with third-party audit compliance. Rollins Inc. and Rentokil North America dominate this segment through national account infrastructure and real-time reporting dashboards.
- Agricultural:Crop protection services target stored grain facilities and livestock operations with fumigation and biological control applications. EPA worker protection standards under FIFRA impose seasonal application windows that compress revenue recognition.
- Industrial:Manufacturing and warehouse complexes prioritize rodent exclusion and bird deterrent systems to protect inventory integrity. IoT-enabled trap monitoring is penetrating this segment fastest due to multi-site coordination requirements.
The dominant share belongs to Residential, while Commercial is closing the gap fastest through procurement centralization among national property management firms.
Control Method:
Method selection tracks regulatory pressure on conventional chemistries, with biological and mechanical alternatives gaining investment as EPA cancellation proceedings accelerate.
- Chemical:Synthetic pyrethroids, neonicotinoids, and organophosphates remain standard for rapid knockdown in termite and mosquito applications. California Department of Pesticide Regulation restrictions on bifenthrin concentrations below federal thresholds fragment product availability.
- Biological:Microbial pesticides employing Beauveria bassiana and Metarhizium anisopliae target specific pest species without non-target ecological damage. Formulation consistency in high-humidity subterranean environments remains a technical barrier.
- Mechanical:Physical barriers, traps, and exclusion sealing address wildlife intrusion and rodent pathways. Urban raccoon and bat complaints in Atlanta and Houston metro areas outpace qualified operator deployment.
- Cultural:Habitat modification, sanitation protocols, and structural maintenance reduce pest harborage without chemical intervention. LEED v4.1 integrated pest management prerequisites position certified providers for municipal procurement.
Chemical methods retain the largest deployment base, though Biological is expanding most quickly as R&D investment redirects from canceled active ingredients.
Pest Type:
Pest biology dictates treatment intensity, with eusocial insects requiring colony-level elimination and wildlife demanding exclusion expertise rather than lethal control.
- Rodents:Norway rats and house mice transmit pathogens and damage electrical infrastructure through gnawing. Cellular-connected snap traps now transmit catch alerts within 90 seconds in Midwest food processing facilities.
- Insects:Mosquitoes, cockroaches, and ants drive the highest service call volume with seasonal pressure peaks. Florida and Texas health departments mandate documented population monitoring for commercial properties.
- Wildlife:Raccoons, bats, and squirrels require humane exclusion and habitat modification under state wildlife regulations. Specialized licensing constraints limit operator supply relative to urban complaint volume.
- Termites:Subterranean species cause disproportionate structural damage in humid climates, driving repair-linked indemnity exposure. Remote monitoring sensor networks are migrating from perimeter bait stations toward predictive colony detection.
Termites command the highest per-customer lifetime value, while Insects generates the greatest absolute transaction volume through recurring service density.
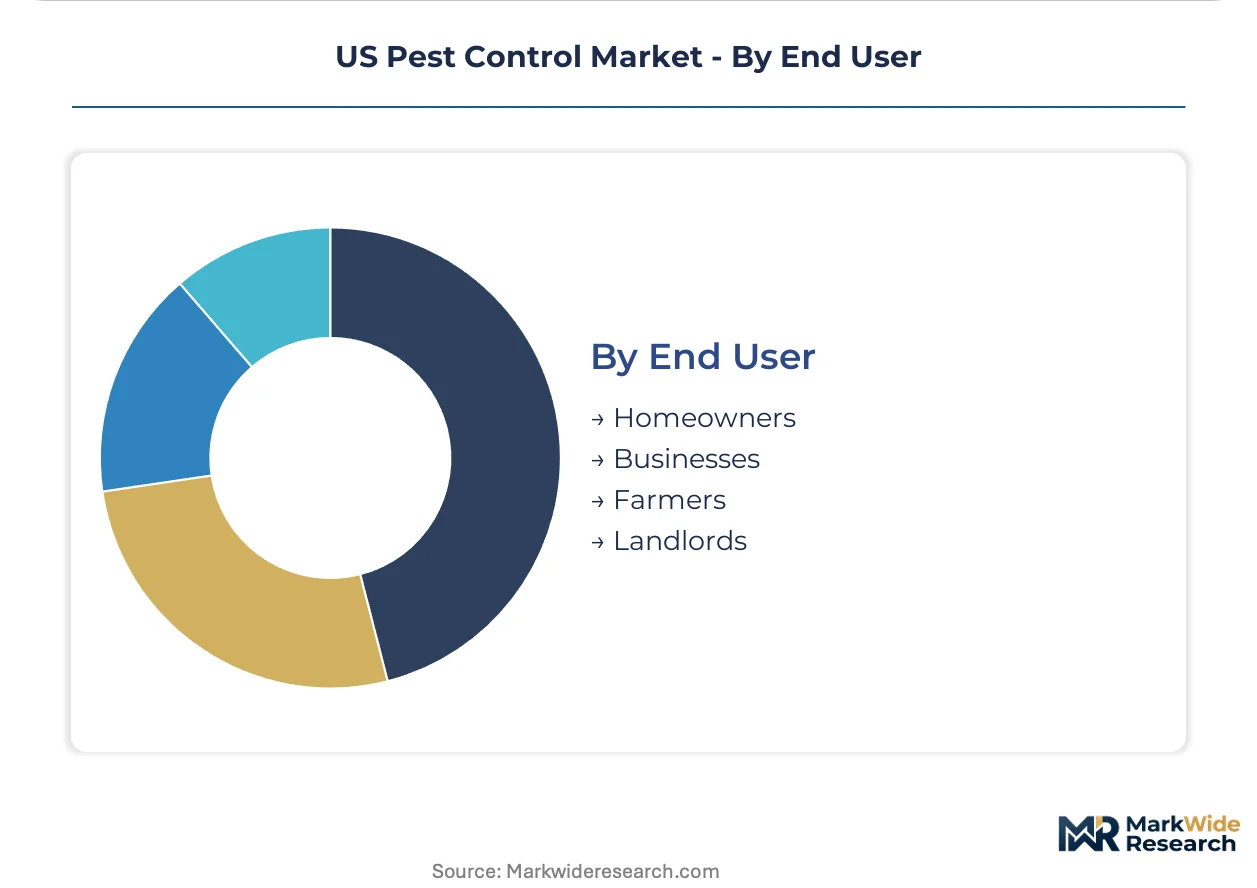
End User:
End-user procurement sophistication ranges from price-sensitive individual homeowners to institutional buyers demanding outcome-based performance metrics.
- Homeowners:Individual purchasers respond to seasonal promotion cycles and neighborhood infestation clustering. Online review sensitivity amplifies complaint consequences in Sun Belt multifamily markets.
- Businesses:Corporate facilities managers centralize vendor panels and compress contract renewal cycles to quarterly performance reviews. Real-time dashboard access to trap activity and pesticide logs is now standard.
- Farmers:Agricultural producers balance treatment cost against crop insurance requirements and export market phytosanitary standards. Fumigation liability exposure requires $5 million minimum general liability coverage.
- Landlords:Multifamily property owners face tenant turnover costs from pest complaints, driving preventive service investments. REITs with Sun Belt exposure prioritize providers with digital documentation capabilities.
Businesses account for the steepest expansion trajectory as audit-driven compliance tightens vendor qualification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Termite pressure corridors and vector-borne disease surveillance mandates concentrate demand across Sun Belt metropolitan zones, with EPA FIFRA enforcement and state-level structural pest control boards creating divergent compliance costs.
Southeast
Subterranean termite colonies and year-round mosquito breeding sustain the highest service contract density in the nation. Florida's Department of Agriculture mandates documented mosquito population monitoring for commercial properties, expanding recurring service scope. Atlanta anchors regional operator consolidation, where Arrow Exterminators leverages employee ownership models to retain technical talent.
Southwest
Scorpion intrusion and rodent pathway exclusion drive residential preventive service uptake in Phoenix and Tucson metro corridors. Arizona's structural pest control licensing requires 20 hours of continuing education biennially, raising technician pipeline constraints. Houston concentrates industrial fumigation capacity for petrochemical facility maintenance.
West Coast
Bed bug resurgence in multifamily housing and hospitality properties sustains urban service intensity in Los Angeles and San Francisco. California's Department of Pesticide Regulation restricts bifenthrin concentrations below federal EPA thresholds, fragmenting product availability. Seattle's damp climate drives carpenter ant and moisture-pest specialization.
Midwest
Stored grain facilities and food processing plants concentrate commercial rodent control demand across Illinois and Ohio. FDA Food Safety Modernization Act audit requirements tighten vendor qualification standards for processing facilities. Chicago anchors multi-site operator coordination for national account servicing.
Northeast
Tourism-dependent hospitality properties in New York and Boston sustain seasonal bed bug and cockroach service peaks. State-level continuing education mandates in New York and New Jersey constrain technician expansion relative to complaint volume. Philadelphia's aging housing stock drives structural pest harbor age remediation.
US Pest Control Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated national landscape where scale-driven routing optimization and biological formulation R&D define tier separation. Three archetypes dominate: integrated national operators with multi-site account infrastructure, regional employee-owned firms with localized technical depth, and chemical-specialist divisions of industrial hygiene conglomerates. Competitive moves concentrate on technician retention through equity participation and IoT-enabled service model differentiation.
Within the integrated national tier, Rentokil North America and Rollins Inc. (Orkin) exemplify scale-driven platform consolidation, while Arrow Exterminators anchors regional positioning through southeastern infrastructure density. These three occupy distinct competitive vectors: Rentokil emphasizes IoT-enabled bait station networks, Rollins deploys proprietary digital routing systems, and Arrow sustains technician retention through employee ownership structures.
| Leading Market Players |
|---|
| Rentokil North America |
| Arrow Exterminators |
| Rollins Inc. (Orkin) |
| Cook's Pest Control |
| Truly Nolen |
| Terminix Global Holdings |
| Massey Services Inc. |
| HomeTeam Pest Defense |
| Ecolab Pest Elimination |
| Others |
Value Chain & Pricing Dynamics
Chinese chemical manufacturing clusters around Shanghai and Jiangsu province concentrate pyrethroid active ingredient production, concentrating pricing power among intermediaries and exposing US distributors to tariff volatility that compresses margin tiers.
Pricing Analysis
Cost-plus contracts with pyrethroid feedstock indexation dominate commercial termite and mosquito service agreements, tying recurring revenue to volatile chemical input costs. Price differentiation hinges on EPA registration tier and IoT-enabled documentation capability, with national account providers commanding premiums over regional independents. Pricing pressure stems from biological formulation R&D costs as neonicotinoid cancellations accelerate. Residential subscribers in Sun Belt states show lowest price sensitivity due to structural damage indemnity exposure, while price-sensitive landlords in Midwest multifamily markets prioritize basic perimeter treatments.
Supply Chain Analysis
Upstream pyrethroid and neonicotinoid feedstock production concentrates in China, with secondary sourcing from India and limited US domestic capacity for microbial pesticide fermentation. Active ingredient manufacturing draws from chlorinated hydrocarbon precursors and botanical oil extracts, with biological formulations resting on Beauveria bassiana spore cultivation. Tariff exposure on Chinese chemical imports constitutes the primary structural risk. Distribution runs through national distributor networks serving regional operator buying cooperatives, with direct manufacturer relationships reserved for top-tier multi-site accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA's 2024 pyrethroid ecological risk assessment and accelerated FIFRA cancellation timelines constitute a regulatory inflection compressing R&D cycles and elevating biological formulation investment thresholds.
For Market Incumbents: Pre-empt biological efficacy gaps in subterranean termite applications by acquiring microbial pesticide specialists with proven humidity-stable formulations. Consolidate technician training infrastructure in Florida and California to bypass state licensing bottlenecks. Vertical integration into IoT sensor manufacturing secures outcome-based billing platform control against hardware commoditization.
For New Entrants and Emerging Players: Southwest metro corridors around Phoenix and Tucson present underpenetration in scorpion intrusion and rodent exclusion services relative to qualified operator supply. Wildlife exclusion in Atlanta and Houston offers white-space expansion with specialized licensing barriers protecting early movers. Target LEED v4.1 certification alignment to access municipal procurement preferences with lower competitive density.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among employee-owned regional operators with Sun Belt infrastructure density and documented retention above industry mean. Long-term viability favors platforms with biological R&D pipelines and IoT-enabled service differentiation over chemical-reliant legacy models. Monitor EPA registration review timelines for pyrethroid and neonicotinoid active ingredients as margin compression signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation R&D Partnership | Microbial pesticide consistency in high-humidity termite applications addresses EPA cancellation pressure on conventional chemistries. |
| IoT Sensor Network Deployment | Cellular-connected trap arrays enable outcome-based billing models that displace scheduled visit revenue structures. |
| Technician Equity Participation | Employee ownership models in Arrow Exterminators demonstrate retention advantages in licensed labor-constrained markets. |
| State Licensing Infrastructure Buildout | Pre-licensure training capacity expansion in California and Florida bypasses certification bottlenecks constraining competitor growth. |
| LEED v4.1 Certification Investment | Integrated pest management prerequisites position providers for municipal and institutional procurement preference access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA FIFRA registration databases, state structural pest control board licensing records, and SEC operator filings. Primary interviews engaged technical directors at national pest control platforms, procurement leads at Sun Belt REITs, state regulatory affairs officers, and entomology program faculty at Purdue and Texas A&M. Secondary sources included OSHA worker protection standards, California Department of Pesticide Regulation restriction notices, and IoT sensor manufacturer technical specifications. Bottom-up service contract modeling and top-down chemical consumption estimates were triangulated against operator revenue disclosures.
Forecast inputs span service type segmentation across residential, commercial, agricultural, and industrial accounts; control method transitions from chemical to biological and mechanical alternatives; pest type intensity variations; and end-user procurement sophistication tiers. CAGRs were derived from contract renewal rate analysis, technician productivity metrics, and biological formulation adoption curves. Industry-specific inputs incorporated EPA registration review timelines, state-level continuing education mandates, and IoT sensor penetration rates in food processing facilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed consolidators or hyperscaler technology entrants would shift outcomes. Biological efficacy breakthroughs in subterranean termite applications or accelerated pyrethroid restrictions could revise growth trajectories. Cross-checking against USDA pest damage indemnity claims and state health department vector surveillance mandates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Fumigation Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Soil Sterilizers Market
Crop Protection
North America Acaricides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Global Algaecides Market
Crop Protection
IPM Pheromones Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Global Acephate Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Germany Crop Protection Chemicals Market