
 North America Crop Protection Chemicals Market | 2026-2036
North America Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Crop Protection Chemicals Market Analytics
Operating lease structures for precision application equipment are reshaping competitive entry barriers across the North American farm input sector. Corteva Agriscience leverages its seed-chemistry integration to anchor premium pricing in the US soybean herbicide segment. BASF SE competes through specialized fungicide portfolios targeting Canadian canola growers. FMC Corporation differentiates via biologicals R&D intensity, positioning its pipeline for EPA bio-pesticide registration acceleration.
Crop protection chemicals encompass synthetic and biological formulations engineered to manage agricultural pests, diseases, and weeds through active ingredients such as glyphosate, neonicotinoids, and Bacillus thuringiensis derivatives, typically applied at rates measured in ounces or grams per acre to preserve yield potential and crop quality. The herbicides segment dominates value generation across the US Midwest and Canadian prairies, where glyphosate-tolerant cropping systems sustain volume pull-through. Bio-pesticides represent the fastest-expanding product type as EPA registration data requirements evolve to accommodate microbial and biochemical modes of action. Liquid formulations occupy the largest share of commercial volume due to compatibility with aerial and ground-based precision application systems.
EPA pesticide registration timelines and state-level 24(c) special local need permits shape product commercialization speed across US jurisdictions, while PMRA re-evaluation cycles govern market access in Canada. The FIFRA regulatory framework governs active ingredient approval, residue tolerance setting, and label restrictions that directly determine which chemistries growers can legally apply. Stakeholders must monitor state-level pollinator protection plans and emerging PFAS testing mandates as these frameworks increasingly restrict product eligibility and application windows.
Market Dynamics
Stacked-trait seed adoption across the US Corn Belt is compressing herbicide application windows and forcing companion chemistry bundling that reshapes distributor inventory requirements and grower procurement calendars.
Growth Catalysts
- EPA Bio-Pesticide Registration Streamlining:The agency's evolving data requirements for microbial and biochemical active ingredients are accelerating commercialization timelines for novel biological formulations targeting specialty crop pests.
- Glyphosate-Resistant Weed Pressure:Palmer amaranth and waterhemp infestations across Iowa, Illinois, and Indiana are compelling growers toward multi-mode-of-action programs that expand fungicide and insecticide bundling opportunities.
- Precision Application Hardware Leasing:Operating lease structures for drone and autonomous ground sprayers are lowering capital barriers for mid-scale operations in the Dakotas and Nebraska.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers control 70-80% of technical-grade glyphosate and glufosinate ammonium production, exposing North American formulators to tariff volatility and ocean freight disruptions.
- PFAS Testing Mandates:Emerging state-level requirements for per- and polyfluoroalkyl substance screening in formulated products are extending analytical validation timelines and raising compliance costs for registrants.
- Neonicotinoid Restrictions:Pollinator protection plans in California, New York, and Ontario are narrowing seed treatment and foliar spray windows for clothianidin and thiamethoxam applications.
Strategic Opportunities
- Canadian Canola Fungicide Expansion:Sclerotinia stem rot pressure in Saskatchewan and Manitoba is driving demand for SDHI-based fungicide programs that command premium pricing over strobilurin standards.
- Biological-Seed Integration:Microbial inoculant coatings for soybeans and dry beans represent underexploited white space as major seed houses seek differentiation beyond genetic traits.
- USDA Conservation Reserve Program Incentives:Cover crop establishment mandates in the 2023 Farm Bill are creating pull-through for herbicide burndown products and biological nitrogen fixers in the Mississippi Delta.
Industry Challenges
- Application Specialist Shortage:Certified crop adviser credentialing programs are failing to replenish retiring agronomists in the Texas High Plains, constraining grower advisory capacity during critical decision windows.
- 24(c) Permit Fragmentation:State-by-state special local need approvals for minor crop uses create label complexity that fragments inventory management and complicates national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Crop Protection Chemicals Market |
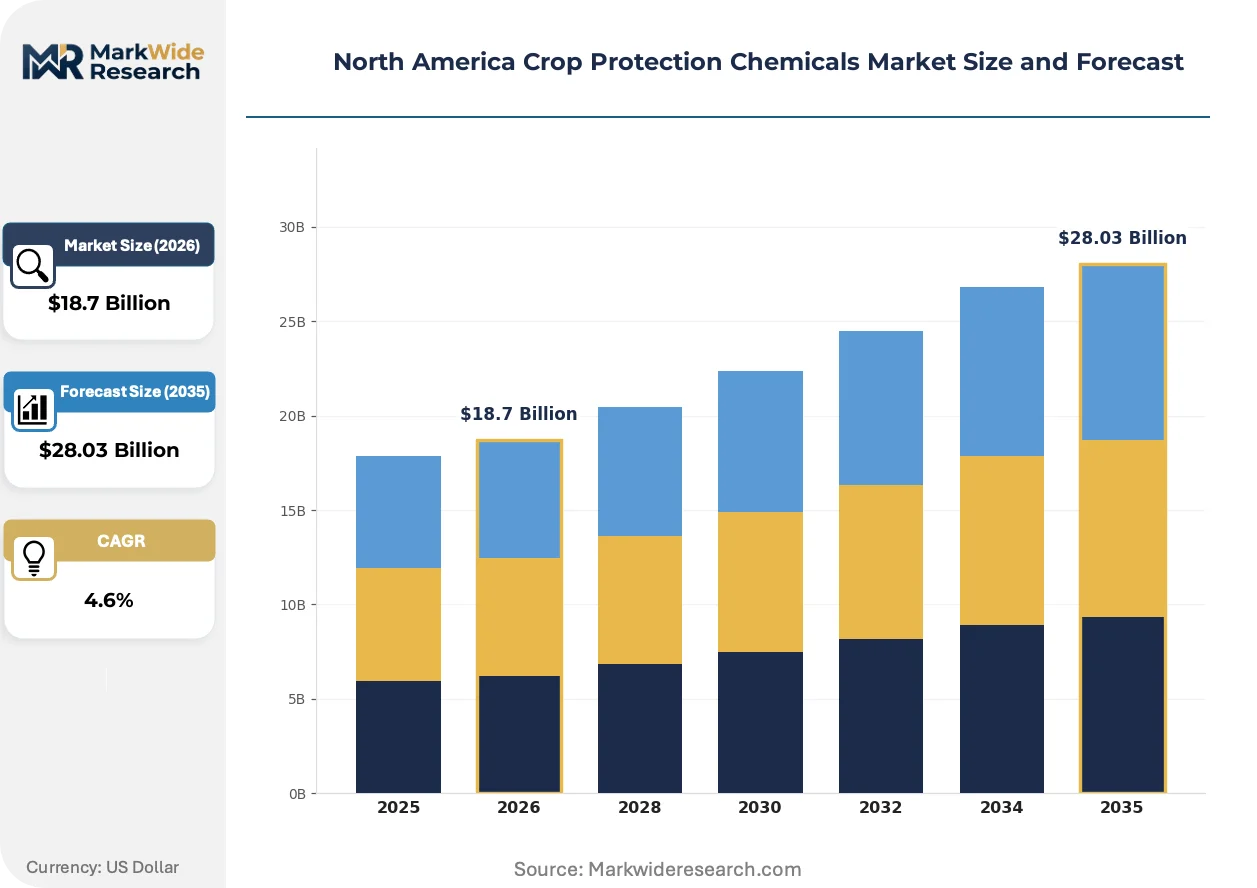
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Bio-pesticides End Use Industry: Agriculture, Horticulture, Forestry, Turf Management Formulation Type: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Online Retail, Agrochemical Dealers, Wholesalers, Supermarkets |
| Companies Covered | Bayer AG, Corteva Agriscience, BASF SE, FMC Corporation, Syngenta Group, Adama Agricultural Solutions, Sumitomo Chemical, UPL Limited, Nufarm Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Crop Protection Chemicals Market Evolving Landscape
Digital agriculture platforms are virtualizing field-level decision support, compressing the traditional agronomist-grower relationship and enabling algorithm-driven input recommendations that bypass conventional retail channels.
Variable-rate application technology is virtualizing spray prescription development. Large-scale corn and soybean operations in Minnesota and Wisconsin are adopting cloud-based platforms that integrate satellite imagery with soil sensor data to generate zone-specific chemical rates. This capability is virtualizing the role of field scouts and reducing per-acre consultation fees that previously anchored distributor revenue models.
The EPA's Endangered Species Act consultation requirements are reshaping product label restrictions. Biological opinions for threatened salmonid habitats in the Pacific Northwest are imposing buffer zones and seasonal application bans on organophosphate and carbamate insecticides. Specialty crop growers in Washington's Yakima Valley are responding by accelerating adoption of mating disruption pheromones and microbial insecticides that face fewer ecological restrictions.
Input purchasing consolidation among grain cooperatives is altering channel economics. Multi-state buying groups in the eastern Corn Belt are aggregating volume commitments to negotiate direct manufacturer contracts, disintermediating traditional independent retail agronomists. This concentration is most visible in Ohio and Indiana, where three regional cooperatives now control over 40% of soybean herbicide volume and demand price transparency tools that expose historical distributor markups.
North America Crop Protection Chemicals Market Segmentation
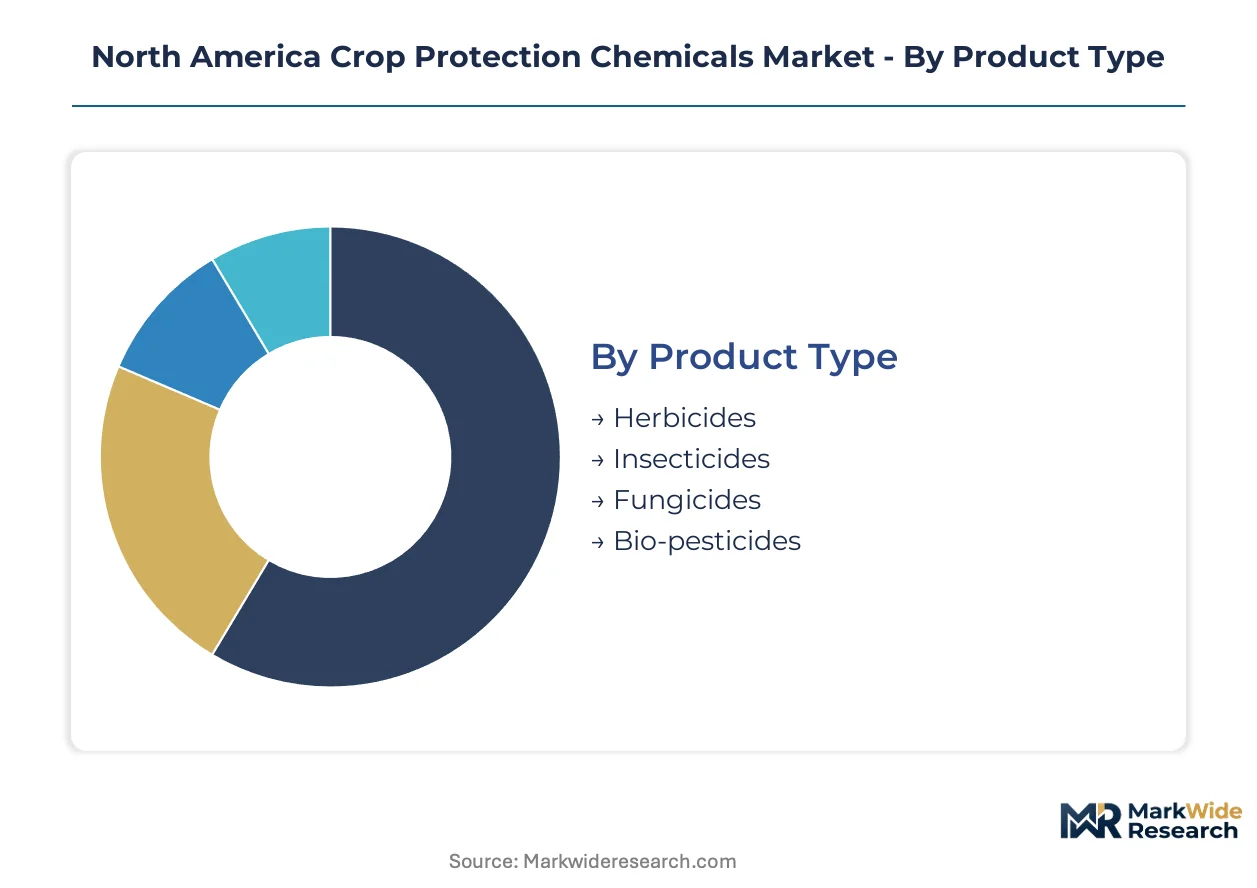
Crop protection chemical segmentation reveals how formulation chemistry, application method, and channel economics intersect to determine commercial viability across North American cropping systems. Understanding these category boundaries exposes where product development investments and distribution partnerships generate sustainable margin capture.
Product Type:
Use cases span from broad-acre weed control in commodity grains to precision pest management in high-value specialty crops, with each chemistry class commanding distinct regulatory pathways and grower procurement behaviors.
- Herbicides:Synthetic auxins, ALS inhibitors, and EPSP synthase blockers constitute the largest volume category, with glyphosate-tolerant trait platforms in Iowa and Illinois sustaining multi-billion-dollar demand. Waterhemp and Palmer amaranth resistance across the Corn Belt is forcing stacked-mode-of-action programs that expand companion chemistry bundling.
- Insecticides:Neonicotinoid seed treatments and pyrethroid foliar sprays dominate row crop protection, though EPA pollinator risk assessments and state-level 24(c) restrictions in California and New York are compressing application windows. Bt trait refuge requirements sustain demand for conventional chemistry in cotton and corn.
- Fungicides:SDHI and strobilurin chemistries protect against rust and blight in wheat and soybeans, with sclerotinia stem rot pressure in Canadian canola driving premium pricing for specialized formulations.
- Bio-pesticides:Microbial and biochemical active ingredients derived from Bacillus thuringiensis, Trichoderma species, and plant extracts are expanding most quickly as EPA registration streamlining accelerates commercialization for specialty crop applications in California's Central Valley.
The dominant share belongs to herbicides, while bio-pesticides are closing the gap fastest.
End Use Industry:
Customer economics diverge sharply between large-scale mechanized operations and intensive manual-labor systems, reshaping formulation preferences and service bundling requirements.
- Agriculture:Row crop and specialty crop production accounts for the majority of volume, with corn-soybean rotations in the US Midwest and wheat-canola systems in the Canadian prairies sustaining bulk herbicide and fungicide consumption. Precision agriculture adoption is compressing per-acre application rates while expanding total treated acreage.
- Horticulture:High-value fruit and vegetable production in Florida, California, and British Columbia demands residue-compliant chemistries with tight pre-harvest intervals, favoring bio-pesticide and reduced-risk synthetic formulations that meet export market maximum residue limits.
- Forestry:Aerial application of herbicides for site preparation and conifer release in the Pacific Northwest and Southeastern US operates under EPA forestry-specific label restrictions and state aerial applicator licensing requirements.
- Turf Management:Golf courses and municipal parks in Texas, Arizona, and Southern California represent a specialized channel with distinct seasonal demand patterns and aesthetic-driven performance standards that command premium pricing over agricultural equivalents.
Agriculture commands absolute volume leadership, though horticulture generates the highest per-acre revenue intensity.
Formulation Type:
Application equipment compatibility and drift mitigation requirements determine which physical forms achieve commercial traction across North American geographies.
- Liquid:Suspension concentrates and soluble liquids dominate commercial volume due to compatibility with aerial applicators and ground-based sprayers equipped with pulse-width modulation nozzles. The form enables tank-mix flexibility and uniform coverage across large-scale corn and soybean operations in Minnesota and Nebraska.
- Granular:Slow-release formulations suit pre-plant incorporated applications in conservation tillage systems, with demand concentrating in cotton and peanut production across the Mississippi Delta where soil incorporation reduces volatility losses.
- Powder:Wettable powder formulations persist in specialty crop and organic production systems where dry storage stability and reduced packaging weight offset mixing inconvenience and inhalation exposure risks.
- Emulsifiable Concentrate:Oil-based carriers enhance cuticular penetration for systemic insecticides and fungicides targeting tree fruit and nut crops in Washington's Yakima Valley and California's Central Coast.
Liquid formulations hold the installed base advantage, though granular alternatives are gaining ground in no-till cropping systems.
Distribution Channel:
Channel economics reflect the tension between agronomic advice bundling and price transparency demands across different grower scale categories.
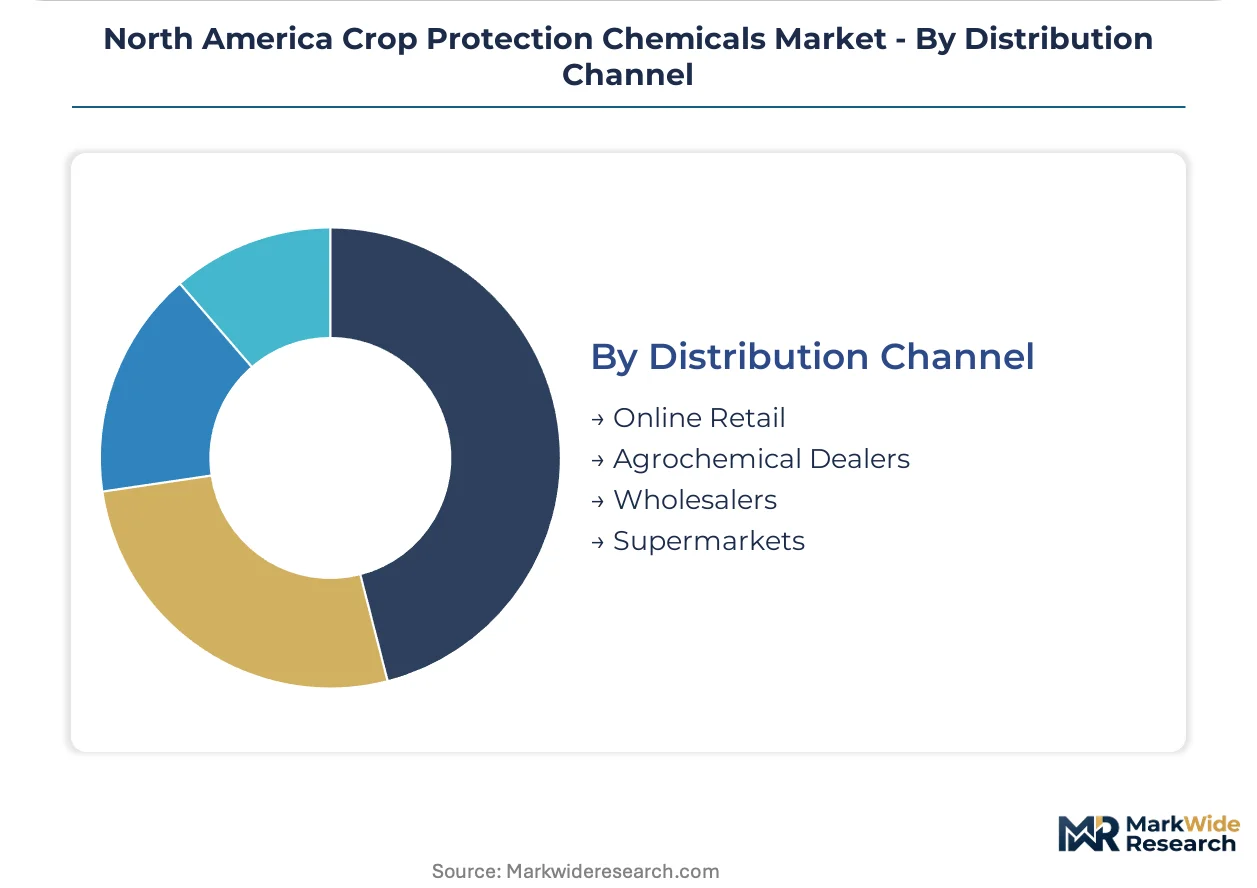
- Agrochemical Dealers:Independent retail agronomists and cooperatives dominate volume in the Corn Belt, combining product sales with certified crop adviser services that anchor grower loyalty through prescription recommendations and application timing alerts.
- Online Retail:E-commerce platforms are penetrating mid-scale operations in the Dakotas and Kansas where growers possess sufficient technical confidence to self-prescribe generic formulations, though EPA restricted-use pesticide requirements limit certain product categories.
- Wholesalers:Regional distributors serve smaller independent retailers and direct-to-grower buying groups, with inventory consolidation in Ohio and Indiana enabling volume-based manufacturer negotiations that bypass traditional retail markups.
- Supermarkets:Consumer-facing garden centers and home improvement chains capture residential turf and ornamental demand, with seasonally concentrated sales of ready-to-use formulations in suburban markets surrounding Dallas, Houston, and Phoenix.
Agrochemical dealers retain the structural lock on professional agriculture, while online retail is eroding share among technically sophisticated growers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Conservation Reserve Program incentives and EPA bio-pesticide registration streamlining are redistributing crop protection demand across North American jurisdictions. State-level pollinator protection plans and 24(c) special local need permits create regulatory patchworks that favor localized formulation strategies.
United States
Glyphosate-resistant weed pressure across Iowa, Illinois, and Indiana sustains multi-billion-dollar herbicide demand through stacked-trait seed programs. EPA FIFRA registration timelines and emerging PFAS testing mandates constrain product commercialization speed. California's Central Valley specialty crop growers accelerate biological pesticide adoption as EPA streamlines microbial active ingredient pathways.
Canada
Sclerotinia stem rot pressure in Saskatchewan and Manitoba canola production drives SDHI-based fungicide premium pricing over strobilurin standards. Health Canada PMRA re-evaluation cycles govern market access timelines for novel chemistries. The Prairie Provinces sustain bulk herbicide consumption through wheat-canola rotation systems that anchor distributor volume commitments.
Mexico
Export-oriented fruit and vegetable production in Sinaloa and Jalisco demands residue-compliant formulations meeting US EPA tolerance standards. Mexico's national agricultural regulator enforces maximum residue limits aligned with Codex Alimentarius to preserve market access. The Bajío Region's intensive vegetable operations concentrate biological pesticide trials for export-bound tomato and pepper crops.
North America Crop Protection Chemicals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. The market exhibits consolidated upstream technical-grade supply concentration against fragmented downstream formulation and distribution tiers. Three archetypes dominate: integrated seed-chemistry platforms, specialized fungicide portfolios, and biologicals R&D specialists. Competitive moves center on precision application equipment leasing partnerships and biological-seed coating integration.
Within the integrated platform tier, Bayer AG and Corteva Agriscience exemplify seed-chemistry convergence strategies that anchor premium pricing through trait-stack bundling. BASF SE occupies a position among specialized fungicide developers targeting canola and cereal protection segments. FMC Corporation represents the biologicals R&D archetype, positioning pipeline assets for EPA registration acceleration in specialty crop applications.
| Leading Market Players |
|---|
| Bayer AG |
| Corteva Agriscience |
| BASF SE |
| FMC Corporation |
| Syngenta Group |
| Adama Agricultural Solutions |
| Sumitomo Chemical |
| UPL Limited |
| Nufarm Ltd. |
| Others |
Value Network & Pricing Analysis
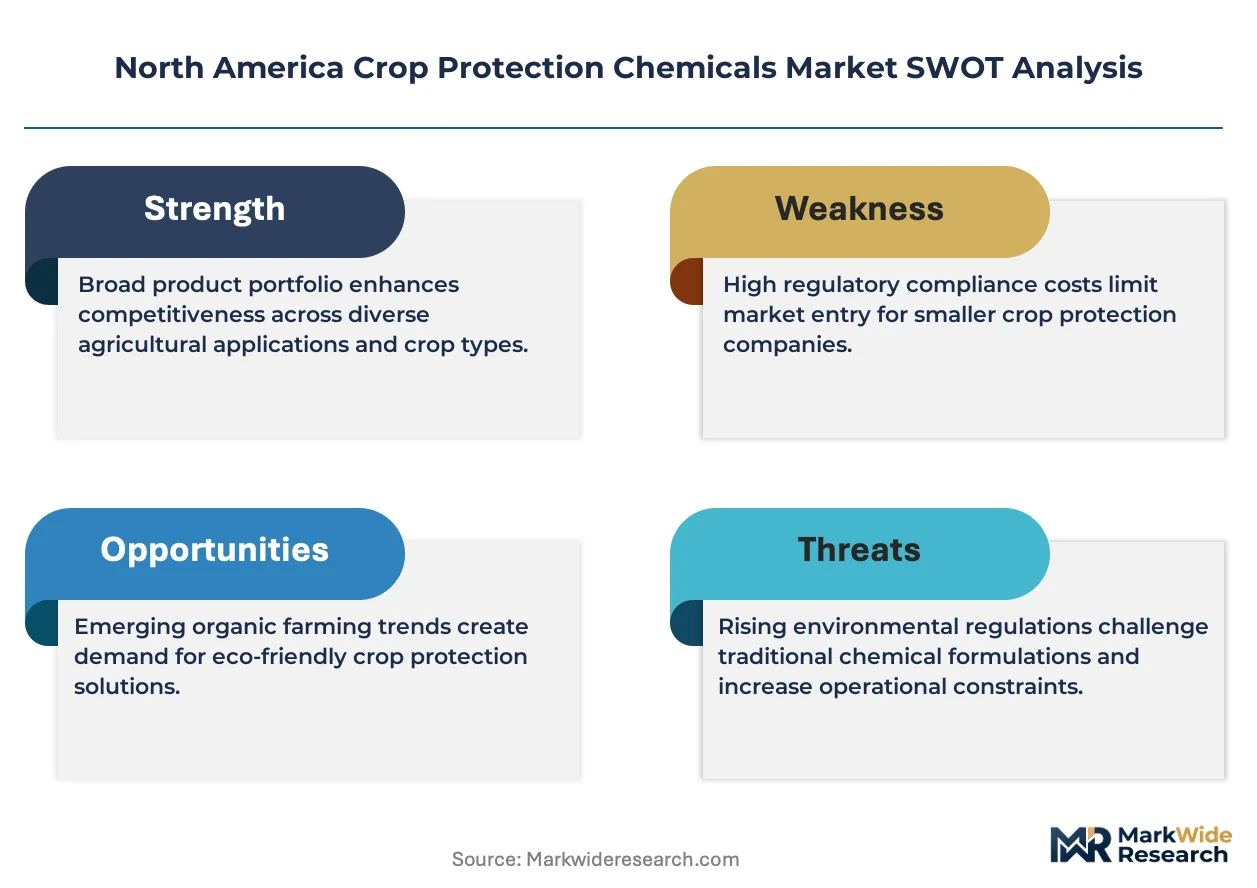
Chinese technical-grade glyphosate concentration determines both pricing tier spreads and supply chain shape across North American formulators, compressing margins on generic herbicides while rewarding backward-integrated players with captive active ingredient supply.
Pricing Analysis
Certification level creates the primary spread between EPA-registered premium formulations and state-24(c) permitted specialty products. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity, residue compliance tier, and bundled agronomic service intensity. Pricing pressure stems from generic glyphosate oversupply and cooperative buying group consolidation in Ohio and Indiana. Grain cooperatives exhibit highest price sensitivity, while specialty crop growers in California's Central Valley prioritize residue compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration resides with Chinese technical-grade producers and Indian generic formulators, with North American tolling capacity limited to blending and packaging operations. Active ingredient supply draws from Chinese glyphosate and glufosinate ammonium manufacturers, Brazilian 2,4-D producers, and Indian pyrethroid specialists. Tariff exposure on ocean freight and technical-grade imports represents the dominant structural risk. Distribution runs through independent retail agronomists and multi-state cooperatives that combine inventory holding with certified crop adviser services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in EPA registration entrenchment, where decade-long active ingredient approval timelines create switching costs that protect incumbent formulation portfolios.
For Market Incumbents: Build regulatory data moats by accelerating EPA bio-pesticide registration submissions ahead of pollinator protection plan expansions. Deepen backward integration into microbial active ingredient fermentation capacity to reduce Chinese technical-grade dependency. Lock in cooperative buying group volume commitments through multi-year herbicide supply agreements before generic price erosion intensifies.
For New Entrants and Emerging Players: Build out biological-seed coating integration partnerships with major seed houses seeking differentiation beyond genetic traits. Target Canadian canola fungicide white space where sclerotinia stem rot pressure outpaces incumbent SDHI supply. Pursue direct-to-grower digital platforms that disintermediate traditional retail agronomist relationships in the Dakotas and Nebraska.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biologicals R&D specialists with EPA registration acceleration capabilities. Long-term viability hinges on pollinator-compliant chemistry pipelines and precision application hardware leasing infrastructure. Acquisition targets should demonstrate microbial formulation expertise and 24(c) permit management systems. Watch EPA Endangered Species Act consultation timelines as inflection indicators for organophosphate and carbamate restriction severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Captive Bacillus thuringiensis production reduces Chinese technical-grade dependency for bio-pesticide formulators. |
| Precision Application Equipment Leasing Partnerships | Operating lease structures for drone sprayers lower capital barriers for mid-scale operations in Nebraska and the Dakotas. |
| Biological-Seed Coating Integration | Microbial inoculant partnerships with seed houses create differentiation beyond genetic trait stacking in soybeans. |
| EPA Bio-Pesticide Registration Acceleration | Streamlined microbial active ingredient pathways unlock specialty crop market access in California's Central Valley. |
| Cooperative Buying Group Volume Commitments | Multi-year supply agreements with Ohio and Indiana cooperatives anchor herbicide volume against generic erosion. |
Research Methodology
A spread of perspectives from EPA registration consultants, certified crop advisers at independent retail agronomists, procurement leads at grain cooperatives, and biologicals R&D directors converged on the working assumptions. Primary interviews combined with secondary validation against EPA registration databases, PMRA re-evaluation filings, USDA Conservation Reserve Program enrollment data, and customs trade records. Bottom-up acreage-by-crop modeling triangulated against top-down manufacturer volume disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product chemistry class, formulation type, end-use crop system, and regional regulatory cluster. CAGRs derived from historical volume trajectories and acreage expansion projections. Key forecast inputs included stacked-trait seed adoption curves and EPA bio-pesticide registration approval velocity.
Sensitivities concentrate around Chinese tariff policy shifts, PFAS testing mandate expansion, and pollinator protection plan adoption timelines. Forecasts reflect assumptions on regulatory pathway efficiency and cooperative buying group consolidation velocity. Quarterly review of EPA registration approval timelines and 24(c) permit issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Miticides Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
India Insecticide Market
Crop Protection
Crop Bactericides Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Isoxaflutole Market
Crop Protection
Global Insecticides Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
North America Insecticide Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Tebuconazole Market
Crop Protection
Grain Protectant Market
Crop Protection
Canada Crop Protection Chemicals Market