
 US Herbicide Market | 2026-2036
US Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
US Herbicide Market Insights
Market Context
Precision agriculture integration with drone-guided spraying is tilting product development toward variable-rate application compatibility. Bayer AG leverages its digital farming platform to sustain grower loyalty through bundled input programs. Corteva anchors its position through proprietary trait-herbicide systems that lock in acreage commitment across the Midwest. FMC Corporation differentiates via selective chemistry portfolios targeting resistant weed spectrums in soybean production.
Technical Definition and Segment Structure
US herbicides are synthetic or biological compounds formulated to inhibit weed germination or growth through enzyme disruption, hormonal interference, or photosynthesis inhibition, with active ingredient concentrations typically ranging from 0.5% to 50% depending on target crop and application method. Post-emergent formulations command the largest revenue pool due to established use in glyphosate-tolerant cropping systems, while organic-based alternatives represent the fastest-expanding category as certified acreage multiplies under USDA National Organic Program standards. Application segmentation reveals corn and soybean as mature volume anchors, whereas specialty crops generate disproportionate margin contribution due to smaller field sizes and higher per-acre input values.
Regulatory Environment
EPA Office of Pesticide Programs governs active ingredient registration and label requirements, while state-level departments of agriculture in Iowa, Illinois, and Nebraska enforce applicator certification and buffer zone compliance. FIFRA-mandated re-evaluation cycles are compressing product lifecycles and elevating R&D amortization costs for registrants. Stakeholders must monitor emerging state restrictions on neonicotinoid and chlorpyrifos alternatives as regulatory fragmentation threatens national label uniformity.
Market Dynamics
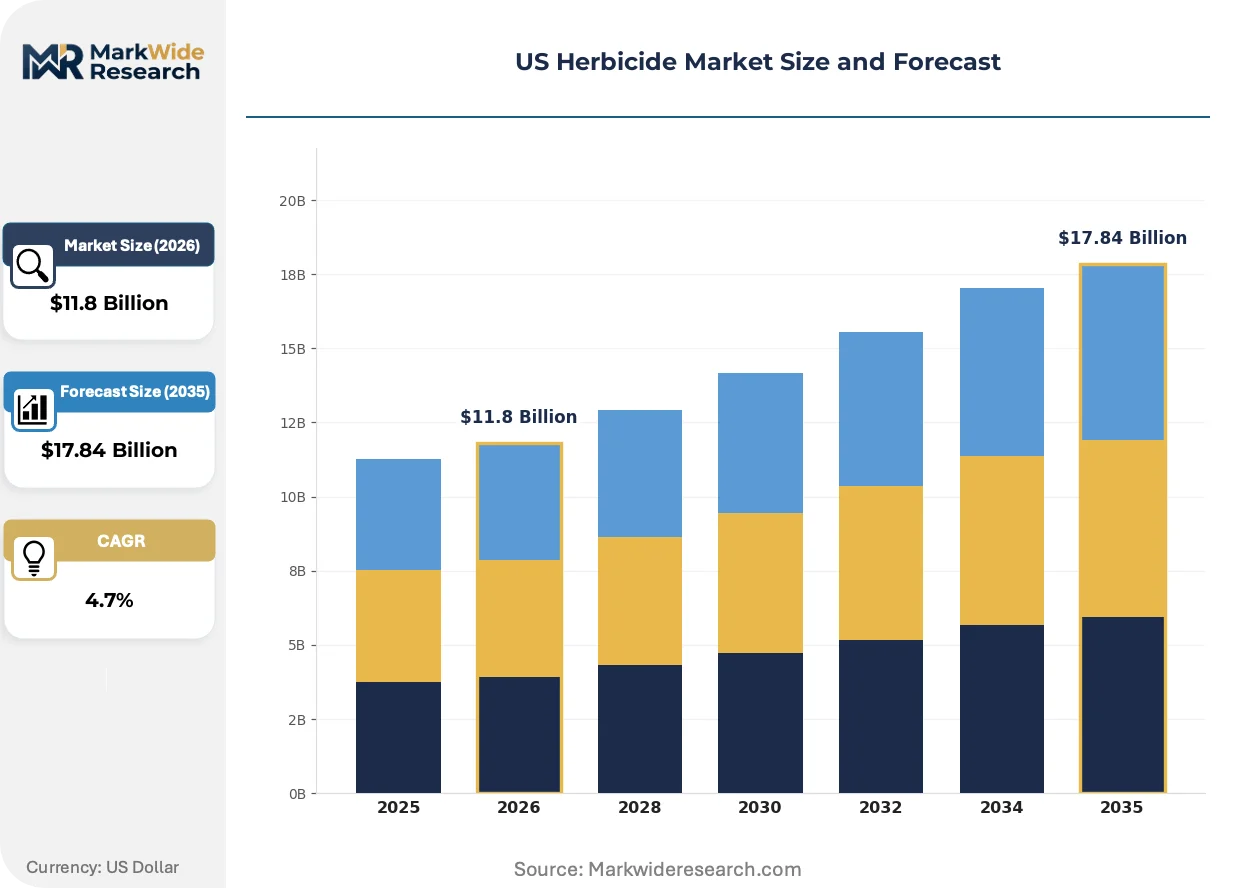
EPA re-registration pressure on glyphosate-based formulations is compressing product lifecycles and forcing registrants to accelerate novel chemistry pipelines while defending existing acreage positions through digital bundling.
Growth Catalysts
- Precision Application Technology:Drone-guided variable-rate spraying systems are expanding adoption among specialty crop growers in California and Florida, reducing per-acre chemical load while maintaining efficacy thresholds.
- FIFRA Re-evaluation Cycles:Mandatory EPA review timelines are accelerating formulation innovation as incumbents invest in next-generation chemistries to secure label continuity ahead of expiration deadlines.
- No-Till Farming Expansion:Residual weed control programs across Iowa, Illinois, and Nebraska are sustaining demand for pre-emergent herbicides as soil conservation practices lock in acreage commitment.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers control upstream synthesis of multiple herbicide intermediates, exposing US formulators to freight volatility and tariff uncertainty.
- Glyphosate Resistance Proliferation:Weed biotypes resistant to EPSP synthase inhibition now dominate multiple Corn Belt counties, degrading the efficacy foundation of trait-herbicide systems.
- Buffer Zone Expansion:State-level Department of Agriculture enforcement in Nebraska and Iowa is tightening proximity restrictions around water bodies, reducing sprayable acreage per application cycle.
Strategic Opportunities
- Biological Herbicide Convergence:Microbial bioherbicides derived from Phoma macrostoma and other plant pathogens are hybridizing with synthetic chemistries to create reduced-residue programs for organic transition acreage.
- Digital Input Bundling:Prescriptive agronomy platforms that integrate weather data, soil sensing, and weed pressure mapping are creating new loyalty mechanisms beyond price-based commodity competition.
- Specialty Crop Margin Capture:Smaller field sizes and higher per-acre input values in vegetable and tree-nut production offer disproportionate margin contribution versus commodity row crops.
Industry Challenges
- Applicator Certification Bottlenecks:State-level credentialing requirements for dicamba and 2,4-D choline formulations are constraining qualified operator availability during narrow application windows.
- Legacy Equipment Integration:Retrofitting existing sprayer fleets with pulse-width modulation and individual nozzle control systems demands capital outlay that mid-scale operations defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Herbicide Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-emergent, Post-emergent, Selective, Non-selective, Organic-based Application: Corn, Soybean, Cotton, Turf Management, Specialty Crops Formulation Type: Liquid Concentrate, Granular, Water-dispersible Granules, Emulsifiable Concentrate End User: Commercial Farmers, Lawn Care Services, Government Agencies, Golf Courses |
| Companies Covered | FMC Corporation, Syngenta, Bayer AG, Certis LLC, Valent Biosciences, BASF SE, Sumitomo Chemical, Gowan Company, Corteva, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Herbicide Market Trends and Innovations
Formulation science and application hardware are converging to enable sub-lethal dose precision, while regulatory fragmentation and biological alternatives are disrupting the commodity chemistry model that dominated the past two decades.
RNA interference herbicides targeting specific weed genes through topical application are hybridizing conventional and biotech approaches, with early pilots in Texas cotton systems demonstrating species-selective suppression without off-target crop damage. Specialty crop operators in California's Central Valley are piloting these platforms for invasive weed management in organic strawberry fields, though EPA registration pathways for nucleic acid-based pesticides remain undefined.
EPA Office of Pesticide Programs is tightening endangered species consultation requirements under revised FIFRA-ESA coordination procedures, extending registration timelines by 12-18 months for products with aquatic toxicity profiles. Corn and soybean registrants are responding by front-loading ecological risk assessments and preemptively restricting label claims in watersheds supporting threatened salmonid populations.
Input procurement through cooperative buying groups and regional agronomy hubs is displacing traditional dealer networks in the Midwest, compressing distributor margins while transferring price negotiation leverage to consolidated farm operations. This channel shift is most pronounced across Illinois and Indiana, where multi-county grower alliances now contract directly with formulators for volume-tiered pricing on residual herbicide programs.
US Herbicide Market Segmentation
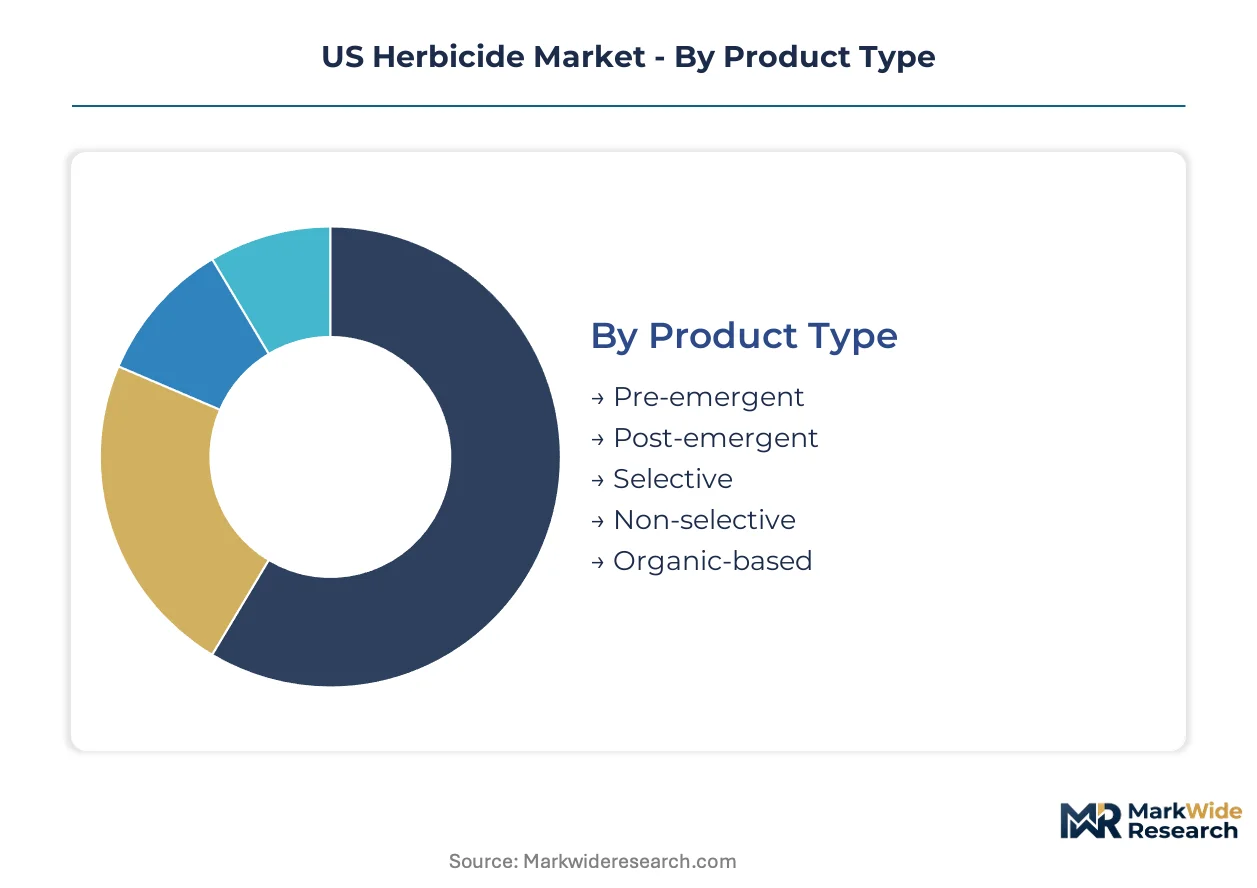
US herbicide demand fragments across multiple technical and commercial axes. Product chemistry, crop target, physical formulation, and buyer type each shape procurement patterns and margin structures differently.
Product Type:
Mature synthetic categories anchor volume while emerging biological alternatives capture premium positioning.
- Post-emergent:Formulations applied after weed emergence dominate acreage commitment in glyphosate-tolerant cropping systems. Corn and soybean growers across Iowa and Illinois rely on these for in-season weed control where resistance management protocols mandate rotation.
- Pre-emergent:Residual chemistry applied before planting creates early-season weed suppression barriers. No-till operations in Nebraska and Kansas depend on these programs to reduce tillage passes while maintaining clean fields through crop canopy closure.
- Selective:Chemistry targeting specific weed families without crop phytotoxicity fills rotation gaps where broad-spectrum options fail. Demand concentrates in specialty crop systems requiring precision weed management.
- Non-selective:Total vegetation control formulations serve burndown applications and industrial sites. Railway corridors and utility rights-of-way in Texas and Florida generate steady institutional demand.
- Organic-based:OMRI-listed formulations derived from botanical extracts and organic acids serve certified organic acreage. California Central Valley vegetable operators expanding organic transition programs are pulling these through distribution channels.
Post-emergent handles the majority of throughput; organic-based is climbing the fastest on share.
Application:
Volume concentration tilts toward commodity row crops while margin density favors intensive specialty systems.
- Corn:The largest single crop destination for herbicide active ingredients, with programs stacking pre-emergent residuals and post-emergent rescue treatments. Bayer and Corteva trait-herbicide bundles lock in multi-year acreage commitment across the Corn Belt.
- Soybean:Dicamba-tolerant and 2,4-D-tolerant trait platforms have restructured herbicide selection, though drift litigation and buffer restrictions constrain application windows. Illinois and Indiana applicators face compressed timing due to certification bottlenecks.
- Cotton:Texas High Plains and Mississippi Delta operations rely on glufosinate-based programs in LibertyLink systems. Weed resistance pressure from Palmer amaranth drives stacked chemistry approaches.
- Turf Management:Professional lawn care services and municipal park departments demand predictable performance across variable weather. Granular formulations dominate this segment for application efficiency.
- Specialty Crops:Vegetable, tree-nut, and fruit production in California and Florida generates disproportionate margin contribution per acre. Smaller field sizes and higher input values justify precision application equipment investments.
Corn and soybean together absorb the bulk of volume; specialty crops deliver the steepest margin per treated acre.
Formulation Type:
Physical form selection hinges on equipment compatibility, storage constraints, and drift mitigation requirements.
- Liquid Concentrate:Soluble and suspension concentrates dominate large-scale row crop operations for tank-mix flexibility and rapid field coverage. Iowa and Illinois commercial applicators favor these for custom application businesses.
- Water-dispersible Granules:Dry formulations that disperse in water reduce packaging weight and improve handler safety. Specialty crop operators in California integrate these with precision injection systems.
- Granular:Ready-to-apply dry formulations serve turf and ornamental markets where liquid handling infrastructure is absent. Golf course superintendents in Florida and Arizona specify these for spot treatments.
- Emulsifiable Concentrate:Oil-based carriers enhance cuticle penetration for hard-to-control weed species. Cotton growers in the Delta region specify these for morning glory and pigweed complexes.
Liquid concentrate commands the largest installed equipment base; water-dispersible granules are gaining share fastest in specialty crop channels.
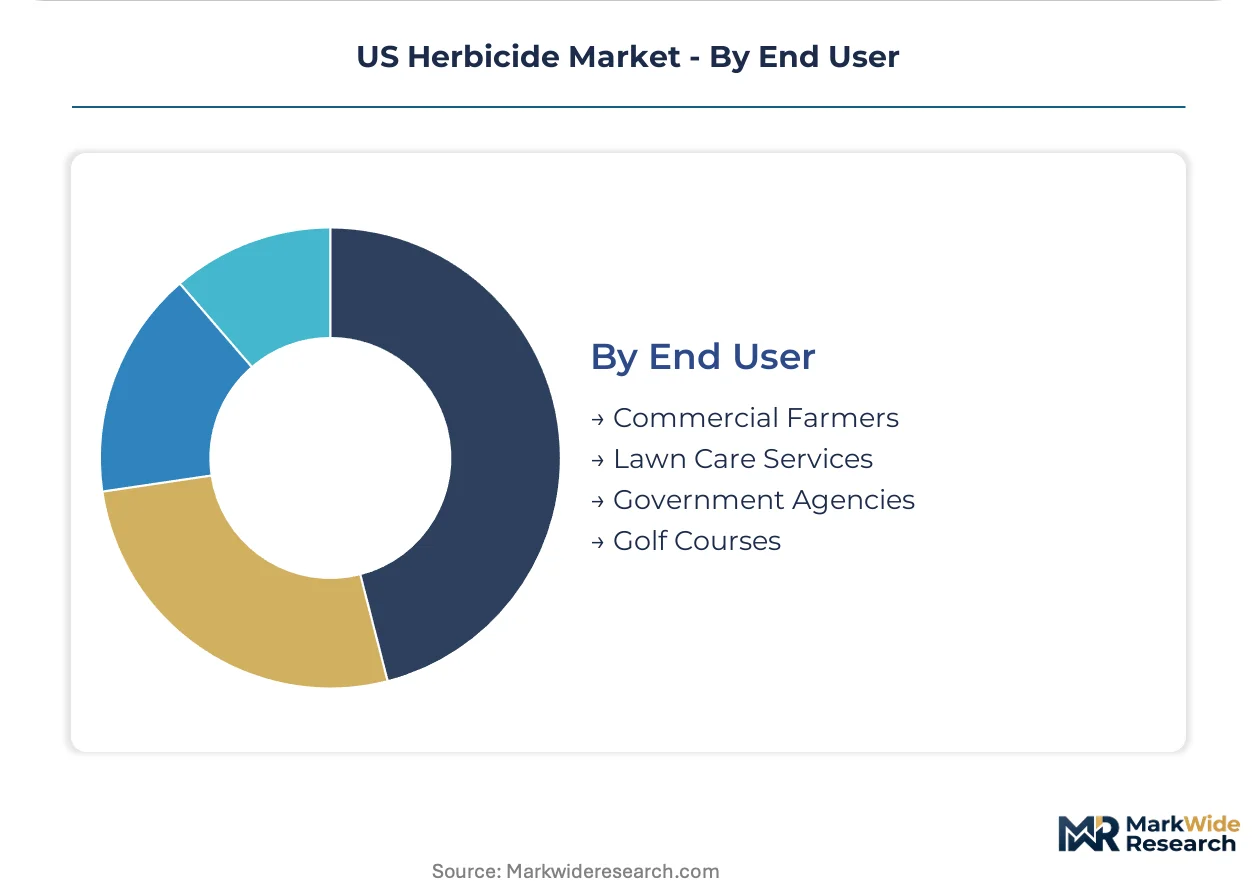
End User:
Buyer sophistication and procurement scale segment sharply across the customer base.
- Commercial Farmers:Consolidated operations across the Midwest contract directly with manufacturers or regional cooperatives for volume-tiered pricing. These buyers drive specification decisions for trait-herbicide systems.
- Lawn Care Services:TruGreen and regional operators procure through dedicated distribution with seasonal inventory programs. Customer retention depends on consistent visual results across suburban properties.
- Government Agencies:Federal and state departments of transportation manage vegetation control on highways and waterways. Procurement runs through competitive bidding with environmental compliance specifications.
- Golf Courses:Superintendent-directed purchasing emphasizes turf safety margins and playability recovery windows. Private clubs in Florida and California represent the highest per-acre input values in this category.
Commercial farmers move the greatest product tonnage; golf courses sustain the highest per-acre expenditure rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial farmers and specialty crop operators concentrate purchasing power across distinct agricultural zones, with procurement patterns diverging between consolidated Midwest row-crop operations and fragmented California vegetable producers.
Midwest Corn Belt
Iowa and Illinois soybean growers drive volume demand for dicamba-tolerant and 2,4-D-tolerant trait-herbicide systems. EPA applicator certification requirements for these formulations compress application windows during critical growth stages. Bayer and Corteva maintain strong positions through bundled input programs anchored in Des Moines and Chicago distribution hubs.
California Central Valley
Vegetable and tree-nut producers in Fresno and Kern counties generate premium-margin demand for precision application-compatible formulations. California Department of Pesticide Regulation enforces stricter buffer zones and air quality standards than federal baselines. Certis and Valent Biosciences serve organic transition acreage with microbial bioherbicides in this high-value specialty crop cluster.
Texas High Plains
Cotton operations in Lubbock and Plainview rely on glufosinate-based programs to manage Palmer amaranth resistance pressure. Texas Department of Agriculture oversees private applicator licensing with supplemental requirements for aerial application. FMC Corporation and Gowan Company anchor distribution through regional cooperatives serving the Panhandle cotton belt.
Florida Peninsula
Citrus and vegetable growers in the Indian River and Everglades regions pull through selective chemistry for weed management in sandy, high-leaching soils. Florida Department of Agriculture and Consumer Services mandates additional groundwater protection measures for certain active ingredients. Sumitomo Chemical and BASF SE target this market through specialized citrus and turf channels.
Pacific Northwest
Washington and Oregon wheat and potato producers require distinct herbicide rotations due to regional weed spectrums and export market residue restrictions. Washington State Department of Agriculture enforces buffers around salmon-bearing streams under enhanced EPA Endangered Species Act coordination. Syngenta maintains presence through cereal herbicide portfolios adapted to Palouse dryland conditions.
US Herbicide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that rewards scale in commodity row crops and agility in specialty segments. The vendor base organizes around three strategic archetypes: diversified agrochemical conglomerates with trait-herbicide integration, selective chemistry specialists targeting resistance management, and biological input providers capturing organic transition demand. Dominant competitive moves include digital platform bundling to lock in grower loyalty and preemptive ecological risk assessment investment to secure EPA registration continuity.
Among diversified agrochemical conglomerates, Bayer AG and Corteva occupy positions exemplifying trait-herbicide system integration across Midwest corn and soybean acreage. BASF SE represents the selective chemistry specialist archetype with portfolios addressing resistant weed spectrums. These three companies anchor the competitive landscape through distinct strategic postures rather than overlapping market approaches.
| Leading Market Players |
|---|
| FMC Corporation |
| Syngenta |
| Bayer AG |
| Certis LLC |
| Valent Biosciences |
| BASF SE |
| Sumitomo Chemical |
| Gowan Company |
| Corteva |
| Others |
Pricing and Supply Chain Analysis
Chinese manufacturers of glyphosate intermediates and 2,4-D acid concentrate pricing power in the hands of upstream synthesis operators, compressing margin pools for US formulators who must absorb freight volatility and tariff exposure while defending downstream distributor relationships.
Pricing Analysis
Cost-plus contracts indexed to benzene and chlorine feedstock benchmarks dominate active ingredient procurement between Chinese suppliers and US formulators. Price differentiation hinges on EPA registration tier and volume commitment scale, with Tier 1 registrants commanding premium positioning over generic entrants. Cost compression in the generic post-emergent segment is intensifying because of Indian import competition and cooperative buying group consolidation. Commercial farmers in Iowa and Illinois exhibit the highest price sensitivity through direct manufacturer contracting, while golf course superintendents in Florida show the least due to per-acre budget insulation and performance guarantees.
Supply Chain Analysis
Contract manufacturing concentration rests with Jiangsu Yangnong, Lier Chemical, and Nutrichem subsidiaries that control technical-grade synthesis capacity for phenoxy herbicides and sulfonylurea chemistry. Geographic supply concentration centers on Jiangsu and Shandong provinces in China, with secondary sourcing from India and limited US captive production in Louisiana and Texas. Raw material dependencies include aniline derivatives, chloroacetic acid, and phosphorus trichloride intermediates. Single-source vulnerability from Chinese environmental regulatory shutdowns poses structural risk. Distribution runs through regional cooperatives and dedicated agronomy hubs displacing traditional dealer networks across the Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US herbicide demand is accelerating through biological-synthetic hybrid disruption, with EPA registration pathways for RNA interference platforms creating a regulatory inflection that rewards first-movers with multi-year label exclusivity.
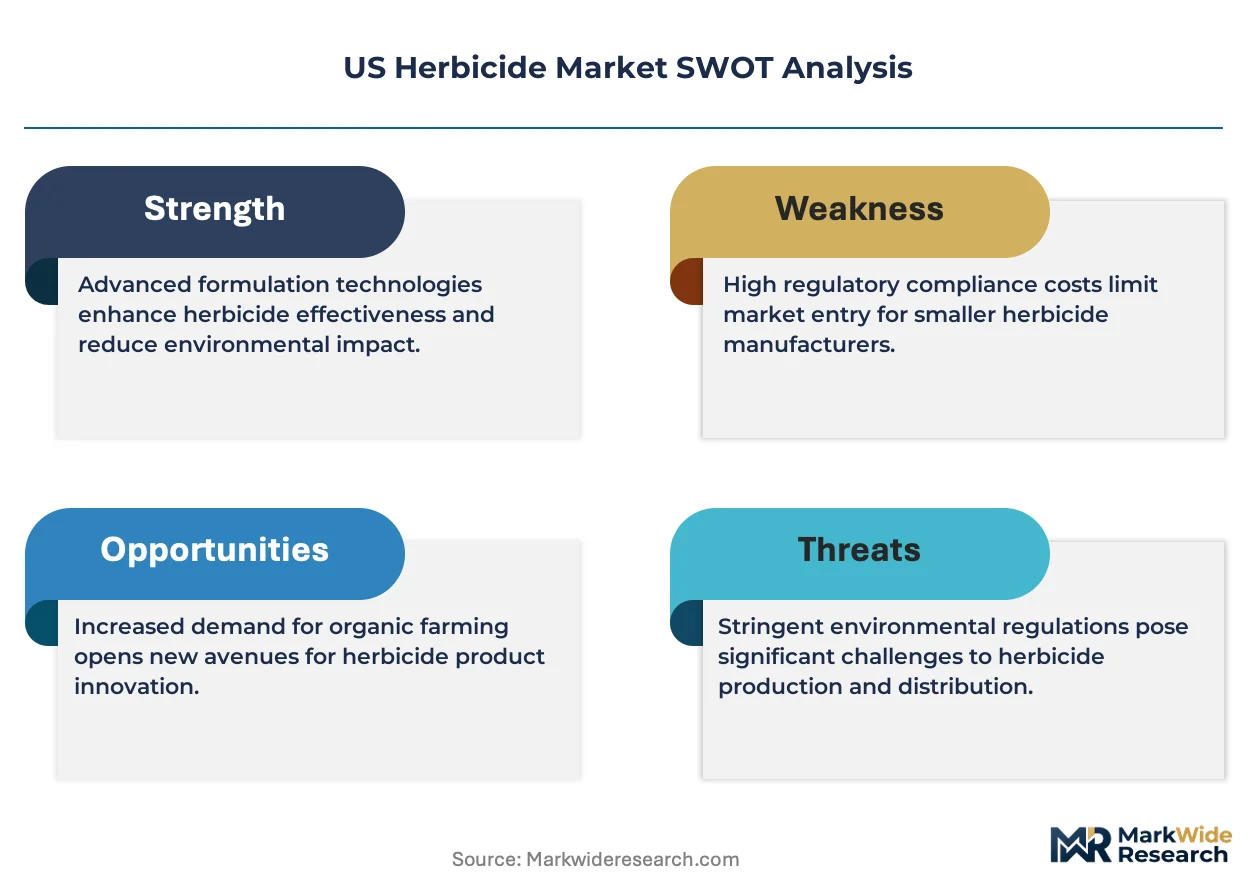
For Market Incumbents: Build digital platform moats through prescriptive agronomy bundling that locks grower loyalty beyond commodity price competition. Invest in backward integration into microbial bioherbicide fermentation capacity to capture organic transition acreage in California. Defend against Chinese generic entrants by front-loading ecological risk assessments for EPA registration continuity. For New Entrants and Emerging Players: Pursue specialty crop penetration in Florida citrus and California tree-nut systems where precision application compatibility commands premium positioning. Target the organic-based formulation segment as the most penetrable white space given supply scarcity and accelerating certified acreage expansion. Establish go-to-market presence through regional agronomy hubs rather than legacy dealer networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biological input specialists holding microbial strain libraries and OMRI-listed formulation pipelines. Long-term viability across the projection horizon favors platforms with EPA registration expertise and digital farming integration capabilities. Monitor EPA Office of Pesticide Programs registration timeline compression as the inflection signal indicating competitive window narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioherbicide Fermentation | Captures organic transition demand in California Central Valley vegetable systems. |
| Digital Platform Bundling | Bayer and Corteva leverage prescriptive agronomy to sustain grower loyalty. |
| EPA Registration Pre-Investment | Front-loaded ecological risk assessments secure label continuity amid FIFRA re-evaluation. |
| Specialty Crop Channel Expansion | Precision application compatibility commands disproportionate margin in Florida and California. |
| Cooperative Buying Group Partnership | Direct contracting with Illinois and Indiana grower alliances displaces traditional distribution. |
Research Methodology
Desk research of EPA registration databases, FIFRA docket filings, and USDA National Agricultural Statistics Service acreage reports preceded structured interviews with herbicide registrant regulatory affairs directors, commercial applicator business owners, cooperative procurement managers, and specialty crop operations managers. Secondary validation drew from SEC 10-K filings of publicly traded agrochemical companies, USITC trade data on active ingredient imports, and state Department of Agriculture enforcement records. Bottom-up volume estimates triangulated against top-down manufacturer revenue disclosures.
Assumptions held fixed across the analysis window include EPA re-evaluation cycle timelines, glyphosate tolerance acreage retention rates, and Chinese environmental regulatory enforcement intensity. Variables modeled across segmentation dimensions encompass product chemistry class, crop target, formulation type, and buyer procurement scale. CAGRs were derived through log-linear trend fitting adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated precision application technology adoption curves and organic certification acreage trajectories.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, freight rates, or tariff schedules would shift the trajectory. Forecasts reflect assumptions about EPA registration pathway efficiency and Chinese supply continuity. Quarterly review of EPA OPP registration timeline announcements and Chinese Ministry of Ecology and Environment enforcement alerts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Herbicides Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Avicides Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
US Insecticide Market
Crop Protection
Pest Control Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Isoxaflutole Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Larvicides Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Grape Fungicides Market