
 Indonesia Insecticide Market | 2026-2036
Indonesia Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Insecticide Market Insights
Domestic formulation capacity across East Java is broadening as Indonesian agrochemical producers scale technical manufacturing. PT Petrokimia Gresik leverages its state-owned fertilizer distribution network to anchor insecticide reach into remote farming cooperatives. Bayer AG competes through specialized crop protection portfolios targeting tropical pest complexes. PT Indo Acidatama Tbk sustains cost positioning in generic pyrethroid segments.
Indonesia insecticides comprise chemically synthesized or biologically derived agents formulated to disrupt arthropod nervous systems, growth cycles, or feeding behaviors, with active concentrations typically ranging from 0.5% to 40% depending on target pest and crop safety windows. These compounds serve primarily to protect food and cash crop yields from lepidopteran, hemipteran, and coleopteran infestations in tropical agricultural systems. Synthetic insecticides occupy the dominant revenue position due to established efficacy against resistant pest strains, while biopesticides represent the fastest-expanding category as export-oriented growers face tightening residue standards from European and Japanese buyers. Liquid formulations lead volume consumption in plantation agriculture, though granular types retain structural importance in rice paddy applications where water management complicates spray timing.
Indonesia's Ministry of Agriculture and the Pesticide Commission regulate active ingredient registration through toxicity evaluation and maximum residue limit protocols that directly determine which chemistries gain market access. BIS-equivalent national standards and the ASEAN harmonized pesticide framework shape import and local manufacturing compliance obligations. Stakeholders must monitor regulatory divergence between Indonesia's domestic tolerance settings and the stricter import requirements of key palm oil and coffee destination markets.
Market Dynamics
Palm oil plantation operators across Sumatra and Kalimantan are expanding chemical protection programs, creating concentrated demand pull that reshapes formulation supply chains and distribution networks toward plantation corridors.
Growth Catalysts
- ASEAN Harmonized Pesticide Framework:Registration reciprocity accelerates cross-border product approvals, reducing time-to-market for regional suppliers serving Indonesian growers.
- Java's Rice-Vegetable Rotation Zones:Intensive double-cropping systems generate recurring seasonal demand for insecticide applications against overlapping pest pressure windows.
- Biopesticide Registration Reforms:Ministry of Agriculture streamlines toxicity evaluation protocols, enabling faster market entry for microbial and botanical alternatives.
Market Restraints
- Active Ingredient Import Dependence:Domestic formulators rely on concentrated technical-grade imports from China and India, exposing margins to shipping cost volatility and currency fluctuation.
- Maximum Residue Limit Divergence:Indonesia's domestic tolerance settings for organophosphates and pyrethroids exceed European Union import thresholds, constraining export-oriented grower chemistry choices.
- Synthetic Chemistry Lock-In:Established efficacy against resistant lepidopteran and hemipteran strains slows grower transition to biopesticide alternatives despite regulatory encouragement.
Strategic Opportunities
- Kalimantan Plantation Corridor:Underpenetrated smallholder cooperatives in East Kalimantan present volume expansion potential for granular formulation distributors with rural logistics capabilities.
- Drone Application Services:Aerial spraying technology convergence with precision agriculture platforms enables new service-based revenue models bypassing traditional retail channels.
- Export Certification Alignment:European Union residue standard compliance creates premium positioning for biopesticide portfolios targeting certified sustainable palm oil growers.
Industry Challenges
- Registration Data Requirements:Field trial documentation and ecotoxicology studies demand 18-24 month preparation cycles, compressing product lifecycle returns before patent expiry.
- Formulation Technical Talent:Shortage of tropical pest biology specialists and adjuvant chemistry engineers constrains domestic R&D scale-up beyond generic replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Insecticide Market |
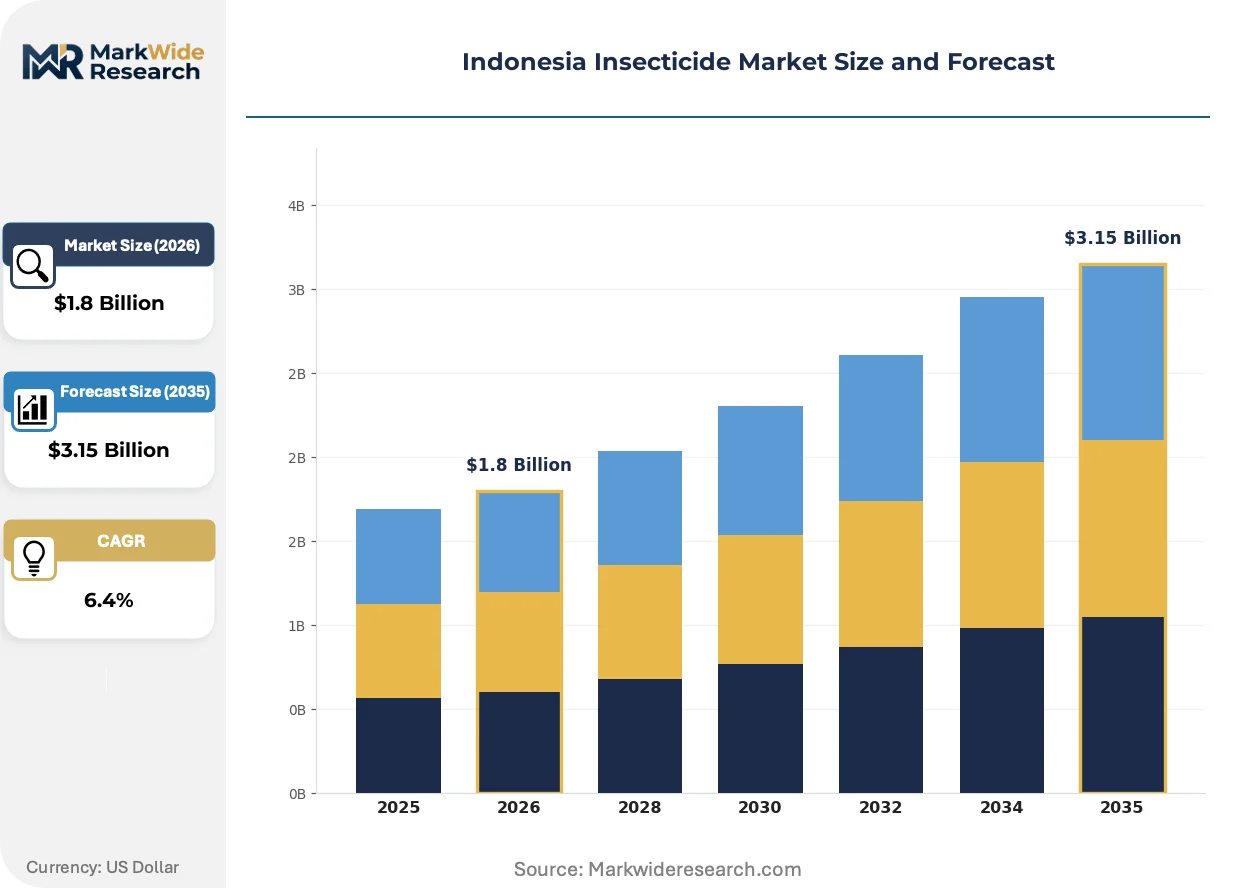
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Insecticides, Organic Insecticides, Biopesticides, Insect Growth Regulators Application: Agriculture, Public Health, Residential, Commercial Formulation Type: Liquid, Granular, Aerosol, Powder Distribution Channel: Online Retail, Agricultural Stores, Supermarkets, Others |
| Companies Covered | Bayer AG, Syngenta, BASF SE, Corteva Agriscience, FMC Corporation, PT Petrokimia Gresik, PT Indo Acidatama Tbk, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Insecticide Market Trends and Innovations
Biological control agents and precision delivery systems are restructuring competitive advantage away from volume chemistry toward integrated pest management service bundles.
RNA interference-based biopesticides are overtaking conventional microbial products in research pipelines. Plantation operators in Riau and North Sumatra pilot foliar applications against diamondback moth and oil palm bunch moth. The technology is overtaking pyrethroid rotations in grower trial programs by enabling species-specific targeting that preserves beneficial predator populations.
Indonesia's Pesticide Commission is tightening maximum residue limit protocols for organophosphate chemistries ahead of full ASEAN harmonization deadlines. Formulators must reformulate established products or withdraw registrations. Rice export processors in Central Java are accelerating residue testing infrastructure investment to maintain European Union market access.
Cooperative procurement consortia are consolidating smallholder purchase volume to negotiate direct manufacturer pricing. Plantation management companies and farmer cooperatives in Lampung and South Sulawesi are displacing independent agrochemical retailers with contracted supply agreements. This consolidation concentrates demand visibility upstream and compresses distributor margin pools in traditional wholesale channels.
Indonesia Insecticide Market Segmentation
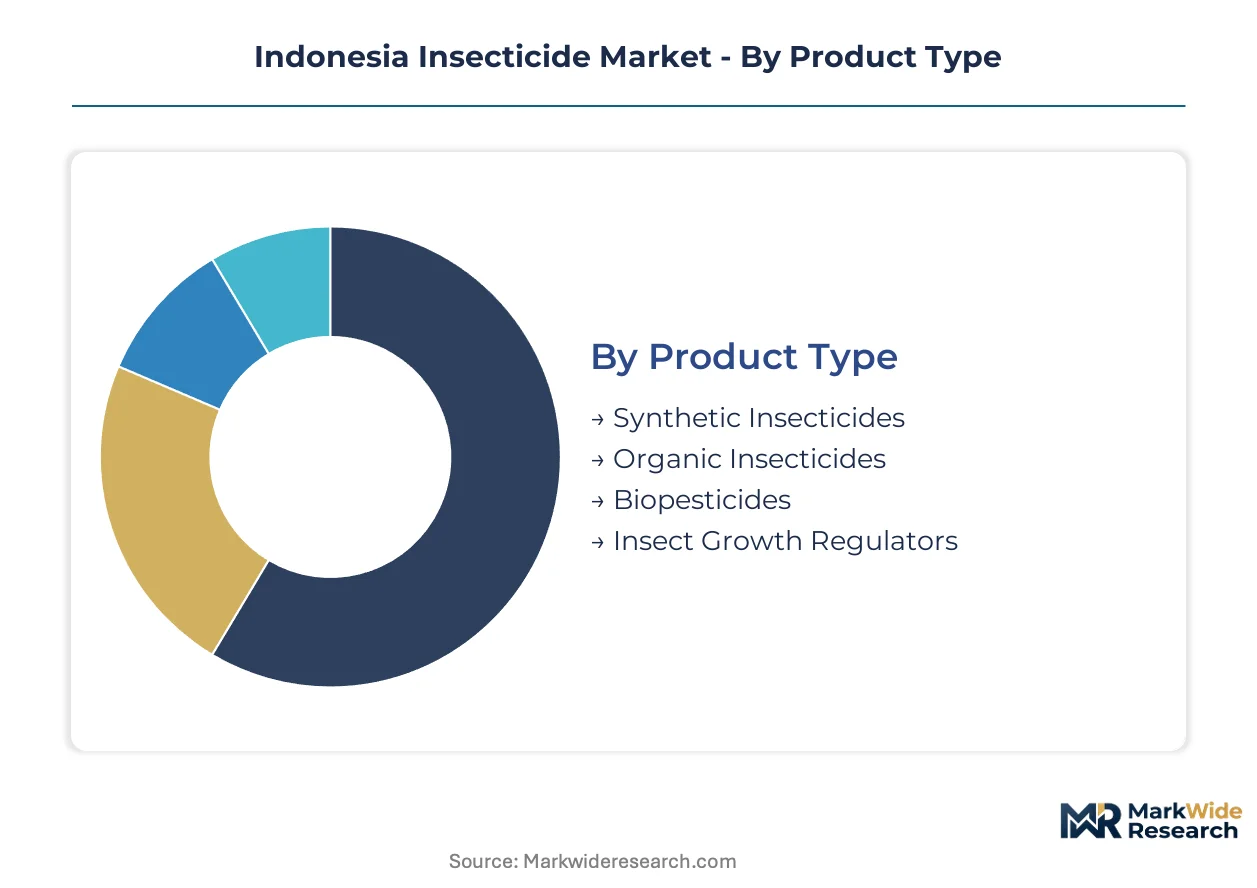
Indonesia's insecticide market fragments across four distinct dimensions that determine procurement patterns, margin structures, and regulatory exposure. Product chemistry dictates residue compliance requirements for export crops. Application context shapes formulation preferences between plantation-scale operations and smallholder holdings.
Product Type:
Buyers differentiate primarily by residue tolerance requirements in destination markets and resistance management protocols in target pest populations.
- Synthetic Insecticides:Chemically synthesized neurotoxic compounds including organophosphates, pyrethroids, and neonicotinoids formulated at concentrations from 0.5% to 40%. Demand concentrates in Sumatra and Kalimantan palm oil corridors where established efficacy against resistant lepidopteran strains sustains grower reliance despite tightening EU residue standards.
- Biopesticides:Microbial and botanical agents derived from Bacillus thuringiensis, Beauveria bassiana, or neem extracts that disrupt pest physiology through non-neurotoxic pathways. Java's intensive rice-vegetable rotation zones are accelerating procurement as export-oriented cooperatives face Japanese and European buyer certification requirements.
- Organic Insecticides:Naturally occurring mineral and plant-derived compounds including pyrethrum and diatomaceous earth approved for certified organic production systems. Smallholder cooperatives in Bali and Lombok deploy these for specialty crop segments serving domestic premium retail channels.
- Insect Growth Regulators:Synthetic mimics of juvenile hormones or chitin synthesis inhibitors that interrupt molting cycles rather than causing acute mortality. Public health vector control programs in Jakarta and Surabaya utilize these for dengue mosquito management to delay resistance development.
Synthetic insecticides lead volumes today; biopesticides are gaining share fastest.
Application:
End-use context determines batch size requirements, application equipment, and regulatory compliance intensity.
- Agriculture:Crop protection across food grains, vegetables, plantation crops, and horticulture representing the dominant volume channel. Rice paddy applications in Central and East Java sustain recurring seasonal demand against brown planthopper and stem borer pressure windows.
- Public Health:Vector control targeting malaria mosquitoes, dengue vectors, and filariasis transmission in urban and peri-urban environments. Ministry of Health procurement contracts concentrate demand through centralized tender mechanisms with specified active ingredient rotations.
- Residential:Consumer-directed formulations for household pest management including aerosols, coils, and surface sprays. Urban middle-class expansion in Surabaya and Bandung is expanding modern retail penetration of pre-packaged convenience formats.
- Commercial:Industrial and institutional applications spanning food processing facilities, warehouses, hospitality, and healthcare settings. HACCP-aligned facilities in Jakarta's manufacturing zones specify residual efficacy documentation and application certification protocols.
Agriculture dominates current procurement; public health programs show the steepest budget expansion trajectory.
Formulation Type:
Physical form selection hinges on water management constraints, equipment availability, and labor cost structures in target geographies.
- Liquid:Emulsifiable concentrates, suspension concentrates, and ultra-low-volume formulations designed for dilution and spray application. Plantation operators across Riau and North Sumatra favor these for aerial and mechanized ground application against oil palm bunch moth infestations.
- Granular:Slow-release formulations embedded in inert carriers for soil or water application in flooded cropping systems. Rice paddy management in West Java and Yogyakarta relies on these formulations where spray timing conflicts with water control schedules.
- Aerosol:Pressurized spray systems delivering fine particle dispersions for rapid knockdown in enclosed or targeted spaces. Urban residential markets in Jakarta and Medan absorb volume through convenience-oriented retail channels.
- Powder:Dry flowable and wettable powder formulations requiring reconstitution prior to application. Smallholder cooperatives in Sulawesi and Nusa Tenggara utilize these for lower-cost procurement and extended storage stability in humid tropical conditions.
Liquid formulations hold the largest volume position; granular types retain structural importance in rice-dominated sub-regions.
Distribution Channel:
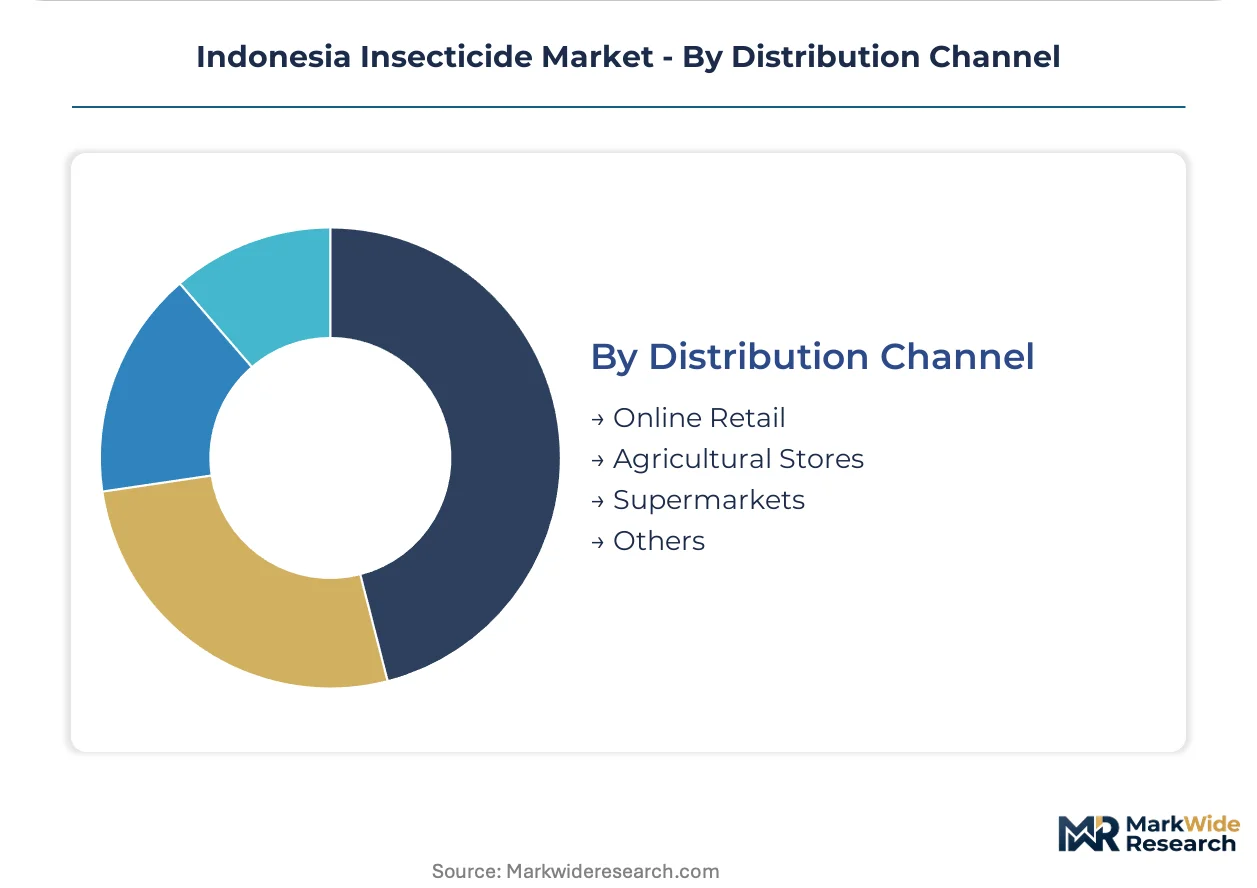
Channel selection reflects buyer scale, technical support requirements, and credit access needs across Indonesia's fragmented agricultural landscape.
- Agricultural Stores:Independent and cooperative-affiliated retailers serving smallholder communities with technical advice and seasonal credit terms. These outlets anchor rural distribution networks in Lampung and South Sulawesi where plantation management companies are consolidating procurement through direct manufacturer contracts.
- Online Retail:E-commerce platforms and direct-to-farmer digital channels enabling price transparency and bulk consolidation. Younger growers in Java's peri-urban vegetable zones are adopting these channels for input cost comparison and delivery convenience.
- Supermarkets:Modern retail chains stocking consumer-format products for residential and small-scale commercial users. Urban centers including Jakarta, Surabaya, and Makassar concentrate this channel's development alongside expanding middle-class household formation.
- Others:Government procurement systems, plantation direct supply agreements, and integrated pest management service providers. State-owned fertilizer distributors including PT Petrokimia Gresik leverage existing rural logistics infrastructure to extend insecticide reach into remote farming cooperatives.
Agricultural stores maintain the deepest penetration; online retail is climbing the fastest as smartphone adoption spreads across farming populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation facilities migrate toward regulatory jurisdictions with streamlined toxicity evaluation protocols, compressing registration timelines and reducing compliance overhead for technical-grade importers.
Sumatra
Oil palm bunch moth pressure across Riau and North Sumatra estates sustains concentrated demand for liquid formulations compatible with aerial application equipment. The Ministry of Agriculture's Pesticide Commission maintains domestic maximum residue limits for organophosphate chemistries that exceed European Union import thresholds, complicating export certification for growers serving Rotterdam and Hamburg processors. Plantation operators in Riau province pilot RNA interference-based biopesticide trials against resistant lepidopteran strains.
Java
Intensive rice-vegetable rotation systems in Central and East Java generate recurring seasonal procurement against brown planthopper and stem borer infestations. BIS-equivalent national standards and ASEAN harmonized pesticide framework obligations shape import compliance for Chinese technical-grade suppliers entering Surabaya port. Formulation plants in Gresik and Sidoarjo expand emulsifiable concentrate capacity to serve peri-urban vegetable cooperatives.
Kalimantan
East Kalimantan smallholder cooperatives present underpenetrated volume potential for granular formulation distributors with rural logistics capabilities. The Ministry of Agriculture's biopesticide registration reforms accelerate microbial product approvals for Beauveria bassiana-based alternatives targeting oil palm pest complexes. Plantation corridors near Balikpapan consolidate procurement through direct manufacturer contracts displacing independent agricultural retailers.
Sulawesi
Cocoa and clove smallholders in South Sulawesi utilize powder formulations for lower-cost procurement and extended storage stability under humid tropical conditions. Pesticide Commission residue testing infrastructure investment lags behind Central Java processing capacity, constraining export-oriented grower chemistry choices. Cooperative procurement consortia in Lampung and South Sulawesi negotiate direct manufacturer pricing bypassing traditional wholesale channels.
Bali and Lombok
Specialty crop segments serving domestic premium retail channels deploy organic insecticides including pyrethrum and diatomaceous earth for certified organic production systems. The Ministry of Agriculture's streamlined toxicity evaluation protocols enable faster market entry for botanical alternatives derived from neem extracts. Smallholder cooperatives in Tabanan and Gianyar sub-regions consolidate purchase volume through digital platforms.
Indonesia Insecticide Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biopesticide specialization and precision application service bundling. Domestic formulators rely on concentrated technical-grade imports from China and India, exposing margins to shipping cost volatility and currency fluctuation. Three archetypes dominate: multinational crop protection specialists with tropical pest portfolios, state-owned fertilizer distributors leveraging rural logistics infrastructure, and generic pyrethroid replicators competing on cost positioning. Consolidation concentrates demand visibility upstream through cooperative procurement consortia, while strategic partnerships between drone service providers and formulation manufacturers bypass traditional retail channels.
Within the multinational tier, Bayer AG and Syngenta occupy positions defined by specialized crop protection portfolios targeting resistant tropical pest complexes. BASF SE and Corteva Agriscience exemplify the research-intensive archetype with established field trial documentation capabilities navigating 18-24 month registration preparation cycles. Among domestic fabricators, PT Petrokimia Gresik anchors state-backed distribution reach into remote farming cooperatives through fertilizer network extension, while PT Indo Acidatama Tbk sits within the generic replication tier sustaining cost positioning in pyrethroid segments.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| PT Petrokimia Gresik |
| PT Indo Acidatama Tbk |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical |
| Others |
Pricing and Supply Chain Analysis
Backward integration into technical-grade active ingredient manufacturing anchors supply positioning and pricing power for Indonesian formulators navigating import dependency. State-owned distributors leverage captive fertilizer logistics networks to compress channel margins and undercut independent retailers in remote plantation corridors.
Pricing Analysis
Distributor margin compression in plantation procurement channels intensifies as cooperative consortia negotiate direct manufacturer contracts bypassing wholesale layers. Three-tier pricing structure across premium biopesticide, standard synthetic, and economy generic pyrethroid segments reflects certification grade and volume scale differentiation. Pricing pressure stems from currency fluctuation exposure on Chinese and Indian technical imports. Smallholder cooperatives in Sulawesi and Nusa Tenggara exhibit highest price sensitivity, while certified sustainable palm oil growers in Sumatra absorb premium positioning for EU-compliant chemistries.
Supply Chain Analysis
Technical-grade active ingredient supply rests on concentrated Chinese and Indian specialty chemical producers, with formulation capacity expanding across East Java. Pyrethroid precursors, organophosphate intermediates, and microbial culture substrates constitute critical input dependencies. Single-source vulnerability on shipping routes through Singapore Strait creates chokepoint exposure for just-in-time plantation replenishment. Distribution runs through state-owned fertilizer networks, independent agricultural retailers, and emerging drone application service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's insecticide market represents a late-cycle quality story as export certification requirements harden chemistry specifications toward residue-compliant biopesticide portfolios.
For Market Incumbents: To counter cooperative procurement consolidation displacing traditional wholesale channels, Bayer AG and Syngenta should deepen backward integration into microbial fermentation capacity for Beauveria bassiana production. Anchor channel control through exclusive supply agreements with plantation management companies in Riau and North Sumatra. For New Entrants and Emerging Players: Begin with underpenetrated East Kalimantan smallholder cooperatives lacking granular formulation distribution access. Target drone application service bundling as the go-to-market angle, bypassing agricultural retailer infrastructure entirely. For Investors and Strategic Acquirers: Roll-up economics work for precision application service platforms because plantation-scale aerial spraying contracts concentrate demand visibility and generate recurring revenue streams. Watch RNA interference biopesticide registration approvals as the inflection signal indicating technology transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Reduces import dependency on Chinese technical-grade supplies for biopesticide expansion. |
| Drone Application Service Platform Launch | Bypasses fragmented agricultural retailer networks in plantation corridors. |
| EU Residue Standard Certification Investment | Unlocks premium positioning for certified sustainable palm oil grower segments. |
| Cooperative Procurement Consortium Partnership | Captures consolidated smallholder volume through direct manufacturer contracting. |
| RNA Interference Biopesticide Registration | Enables species-specific targeting that preserves beneficial predator populations in grower trials. |
Research Methodology
Coverage spans Sumatra, Java, Kalimantan, and Sulawesi, with primary inputs from each region triangulated against secondary validation. Interviews with formulation plant managers, plantation procurement directors, Ministry of Agriculture regulatory officials, and agricultural cooperative leaders combined with customs trade data, ASEAN pesticide registration databases, and SEC filings from listed agrochemical producers. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Rate-of-change decomposition across the projection horizon segmented by product chemistry, application context, formulation type, and distribution channel. CAGRs derived from historical volume trajectories adjusted for regulatory approval timelines, plantation expansion patterns, and biopesticide substitution elasticities. Modeled inputs included Ministry of Agriculture registration pipeline data and European Union maximum residue limit revision schedules.
Several conditions sit outside the modeled scope, including abrupt ASEAN regulatory divergence, extreme currency volatility on technical imports, and accelerated resistance development in target pest populations. Forecasts reflect documented assumptions on registration timeline consistency and plantation yield recovery patterns. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Herbicide Safeners Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
India Insecticide Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Global Acaricides Market
Crop Protection
Europe Herbicide Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
South America Acaricides Market
Crop Protection
Soil Fumigant Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Grain Protectant Market