
 Global Insecticide Seed Treatment Market | 2026-2036
Global Insecticide Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insecticide Seed Treatment Market Foresight
The EU Green Deal's Farm to Fork strategy is broadening the addressable market for biological seed treatment alternatives as member states tighten neonicotinoid exemptions. Bayer AG sustains extensive field trial networks across European rapeseed programs to validate pyrethroid-based replacements. Syngenta Group dominates proprietary film-coating technologies that extend insecticide retention on high-value vegetable seeds. BASF SE anchors its position through backward integration into polymer binders that reduce active ingredient dust-off during planting operations.
Insecticide seed treatment denotes the application of crop protection chemistry directly onto seed surfaces prior to sowing, typically involving active ingredients suspended in polymer-based adhesive formulations at application rates of 50–400 grams per 100 kilograms of seed depending on pest pressure and crop value. The primary purpose is to establish a protective chemical barrier in the soil zone surrounding the germinating seed and emerging root system, targeting soil-dwelling insects and early-season foliar feeders during the crop's most vulnerable establishment phase. Neonicotinoid demand remains structurally dominant in North American and Brazilian row crop systems despite regulatory headwinds, while biopesticide segments command premium positioning in European specialty seed markets where residue limits under REACH drive substitution. Oilseed crops represent the fastest-growing application dimension as canola and sunflower expansion in Eastern Europe and Argentina creates new demand for flea beetle and cutworm protection at planting.
EPA registration requirements under FIFRA govern active ingredient tolerance establishment in the United States, while EFSA and national competent authorities enforce MRL harmonization across EU member states that directly determines which chemistries seed companies can legally coat and export. Brazil's national health surveillance agency ANVISA maintains separate residue protocols that frequently lag OECD harmonization, creating compliance complexity for multinational seed treaters operating across Americas supply chains. Stakeholders must monitor evolving pollinator risk assessments from EPA and EFSA as these determinations increasingly influence re-registration timelines and buffer zone requirements that reshape product economics for treated seed distribution.
Market Dynamics
Neonicotinoid phase-outs under EFSA and EPA pollinator risk assessments are compressing chemistry portfolios and forcing seed treaters to rebuild formulation pipelines around biopesticide actives and novel delivery polymers.
Growth Catalysts
- Brazil's Cerrado expansion:Soy and cotton frontier development in Mato Grosso and Goiás generates demand for soil-dwelling pest protection at planting, with ANVISA registration pathways enabling faster chemistry adoption than OECD-harmonized jurisdictions.
- EU Green Deal residue limits:REACH-driven MRL tightening for oilseed crops redirects breeding programs toward seed-applied biopesticide validation, expanding addressable market for microbial formulations in rapeseed and sunflower.
- Polymer film-coating advances:Proprietary adhesive systems reduce active ingredient dust-off during pneumatic planting, improving operator safety and planting precision in high-speed Midwest corn operations.
Market Restraints
- Active ingredient supply concentration:China dominates technical-grade neonicotinoid and pyrethroid manufacturing, exposing formulators to export license volatility and freight cost spikes.
- Regulatory fragmentation:Brazil's ANVISA maintains separate residue protocols from EPA FIFRA tolerances and EFSA MRL harmonization, forcing multinational seed treaters to maintain parallel compliance documentation.
- Biological formulation stability:Microbial seed treatments face shelf-life limitations in tropical storage conditions, constraining distribution radius from formulation plants in Brazil and Southeast Asia.
Strategic Opportunities
- Eastern European oilseed corridors:Canola and sunflower expansion in Romania and Ukraine creates demand for flea beetle and cutworm protection where neonicotinoid restrictions are less stringent than Western EU.
- Argentina's Pampas soybean belt:Integrated pest management adoption in Buenos Aires and Córdoba provinces prioritizes seed-applied chemistry for early-season aphid and stink bug management.
- US Midwest precision planting:Variable-rate application technology convergence with seed treatment equipment enables site-specific dosing based on soil pest pressure mapping.
Industry Challenges
- Formulation chemist scarcity:Expertise in polymer-rheology matching for high-value vegetable seeds concentrates among legacy agricultural chemistry specialists, constraining biopesticide pipeline expansion.
- Field trial infrastructure:Multi-season efficacy validation across diverse soil types and pest complexes demands capital-intensive plot networks that mid-scale treaters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insecticide Seed Treatment Market |
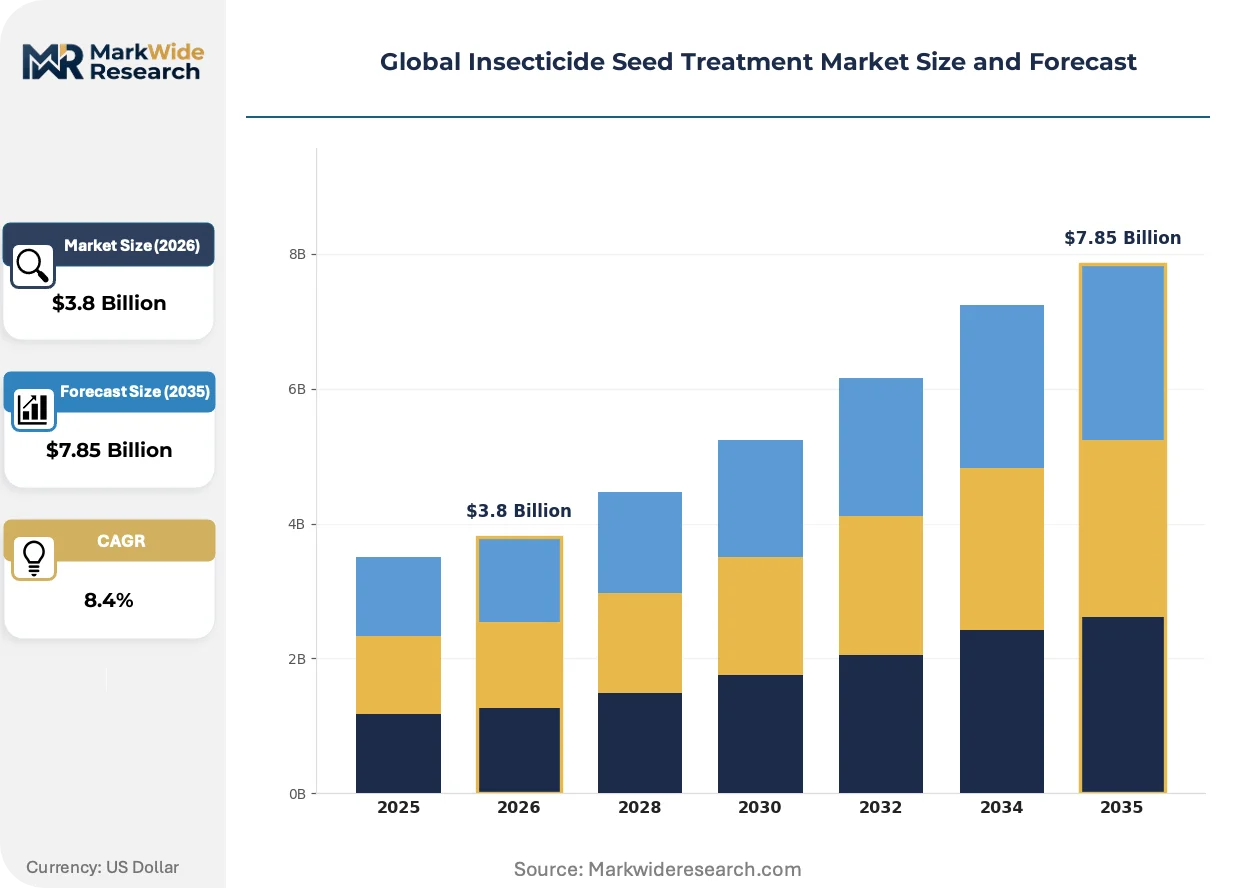
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neonicotinoids, Pyrethroids, Organophosphates, Carbamates, Biopesticides Application: Cereal Crops, Oilseed Crops, Pulses, Fiber Crops, Commercial Crops End User: Seed Companies, Agricultural Cooperatives, Contract Growers, Research Institutions Distribution Channel: Direct Sales, Agricultural Retailers, Online Platforms, Agrochemical Distributors |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, Corteva Agriscience, FMC Corporation, UPL Ltd, Valent U.S.A, Gowan Company, KENSO New Zealand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insecticide Seed Treatment Market Shifts & Advancements
Seed treatment chemistry is pivoting from broad-spectrum residual actives toward targeted biologicals and precision delivery systems, with regulatory pressure and planter technology evolution as twin accelerants.
Microencapsulation technology is unifying active ingredient protection with controlled-release kinetics, extending insecticide bioavailability through the critical germination window. Large-scale corn and soybean operators in Iowa and Illinois are adopting these formulations to reduce replant rates from early-season wireworm damage. The technology is compressing differentiation between premium and standard treatment tiers by democratizing extended protection previously limited to high-value specialty seeds.
EFSA's pollinator risk assessment guidance is mandating expanded field margin buffer zones and seasonal application windows for neonicotinoid-treated seeds across EU member states. Seed companies are reformulating rapeseed and sunflower portfolios around pyrethroid and microbial alternatives to maintain export eligibility. German and French regulators are enforcing the strictest interpretation, accelerating biopesticide registration queue processing at national competent authorities.
Buyer consolidation among US agricultural retailers is concentrating procurement leverage and compressing supplier margins on standard corn and soybean treatments. Independent seed treaters in Nebraska and Kansas are responding by unbundling application services from chemistry sales, charging per-acre treatment fees rather than per-unit seed premiums. This model shift is most visible in the Western Corn Belt where cooperative ownership structures dominate distribution channels.
Global Insecticide Seed Treatment Market Segmentation
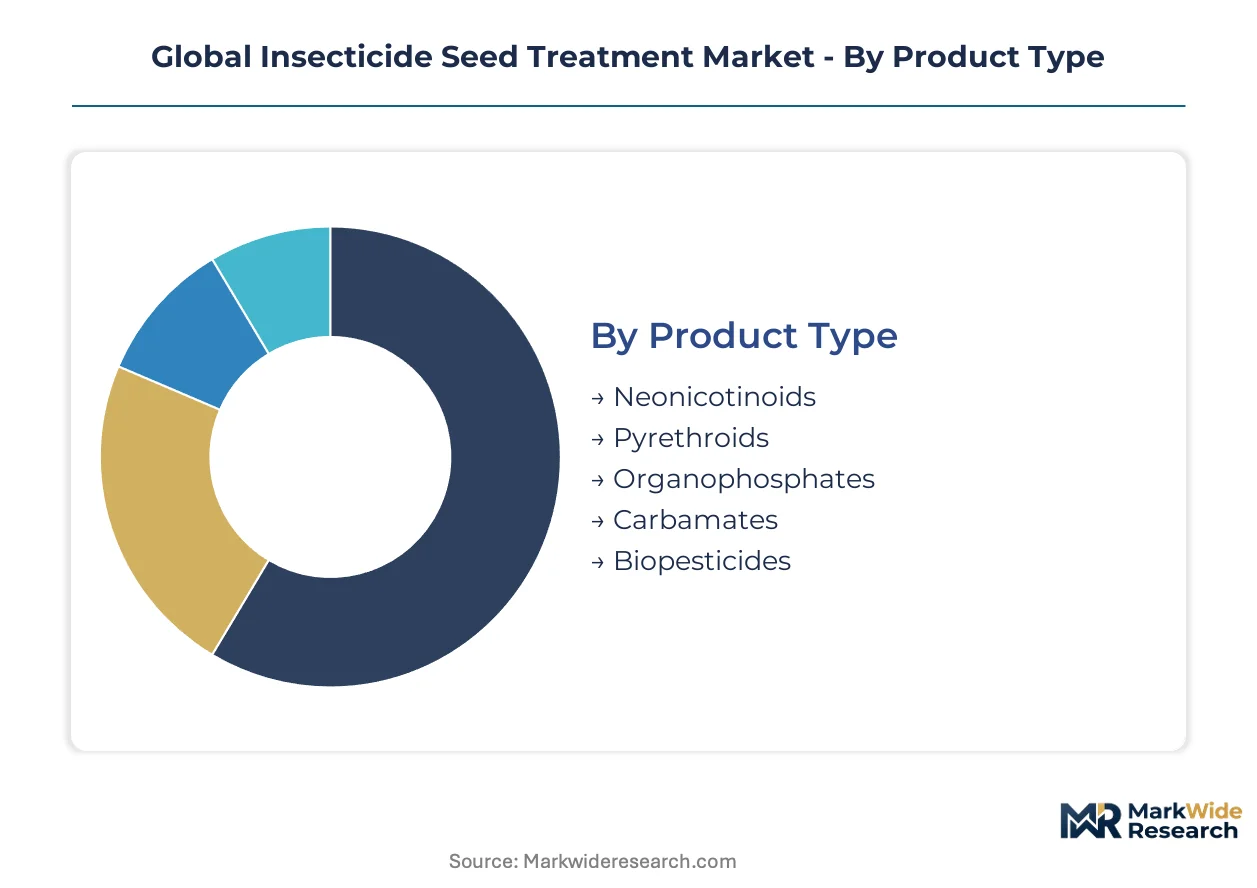
Segmentation in insecticide seed treatment reveals how formulation chemistry, crop value, and procurement authority intersect to determine pricing power and technical service requirements across distinct customer workflows.
Product Type:
Customization intensity spans from standardized synthetic actives to precision-formulated biologicals requiring polymer-rheology matching for each seed species.
- Neonicotinoids:Systemic chlorantraniliprole and imidacloprid formulations dominate North American and Brazilian corn-soy systems for early-season wireworm and aphid protection. Demand concentrates in Mato Grosso and Iowa where ANVISA and EPA registration pathways still permit broad use despite EFSA phase-outs.
- Biopesticides:Microbial formulations employing Beauveria bassiana and Bacillus thuringiensis require cold-chain logistics and shelf-life management. European rapeseed programs under REACH MRL tightening drive fastest adoption in Germany and France where national competent authorities accelerate biological registration queues.
- Pyrethroids:Contact-acting bifenthrin and lambda-cyhalothrin coatings serve as neonicotinoid replacements in EU sunflower and canola.
- Organophosphates:Chlorpyrifos-based treatments face regulatory compression across OECD jurisdictions.
- Carbamates:Carbofuran and thiram formulations persist in specific tropical soil pest complexes.
Leading the category by volume: Neonicotinoids. Growing fastest: Biopesticides.
Application:
Margin structure varies by crop establishment risk and seed value density per hectare.
- Oilseed Crops:Canola and sunflower seeds command premium treatment tiers due to high flea beetle and cutworm vulnerability during germination. Eastern European expansion in Romania and Ukraine creates new demand corridors where neonicotinoid restrictions remain less stringent than Western EU.
- Cereal Crops:Corn and wheat treatments emphasize cost efficiency at scale. US Midwest operators in Illinois and Indiana adopt microencapsulated formulations to reduce replant rates from wireworm damage in high-speed planting operations.
- Pulses:Soybean and chickpea treatments prioritize rhizobia compatibility alongside insect protection.
- Fiber Crops:Cotton seed treatments in Brazil's Cerrado target soil-dwelling pests during frontier expansion.
- Commercial Crops:Vegetable seeds require film-coating precision for high-value hybrid varieties.
Highest value per treated unit: Oilseed Crops. Steepest expansion trajectory: Cereal Crops.
End User:
Procurement authority determines whether chemistry selection prioritizes operational efficiency or genetic portfolio integration.
- Seed Companies:Bayer and Syngenta integrate treatment into breeding pipelines with proprietary polymer binders. Internal formulation capabilities allow backward integration into active ingredient sourcing and dust-off reduction technologies.
- Agricultural Cooperatives:Member-owned distributors in Nebraska and Kansas unbundle application services from chemistry sales, charging per-acre fees rather than per-unit premiums to defend margin position against retailer consolidation.
- Contract Growers:Specialty vegetable producers specify treatment protocols under processor agreements.
- Research Institutions:University plot networks validate multi-season efficacy across soil types.
Controlling procurement volume: Seed Companies. Gaining negotiating leverage: Agricultural Cooperatives.
Distribution Channel:
Channel selection reflects planter technology compatibility and technical service requirements.
- Agricultural Retailers:Consolidating buyers in the US Western Corn Belt concentrate leverage over standard corn and soybean treatments. Iowa and Illinois retailers demand polymer formulations compatible with pneumatic planting equipment.
- Direct Sales:Multinational seed treaters maintain captive channels for proprietary film-coating technologies in high-value vegetable seeds.
- Online Platforms:Emerging channel for specialty crop inputs with logistics constraints in tropical storage conditions.
- Agrochemical Distributors:Regional networks handle compliance documentation for ANVISA-EPA-EFSA regulatory fragmentation.
Capturing volume share: Agricultural Retailers. Expanding service scope: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso anchors global insecticide seed treatment activity through its Cerrado frontier expansion, where soy and cotton cultivation drives demand for soil-dwelling pest protection at planting. The region's ANVISA registration pathways enable faster chemistry adoption than OECD-harmonized jurisdictions, attracting multinational formulation investment.
United States
Iowa and Illinois corn-soy belt operators deploy microencapsulated neonicotinoid formulations to combat early-season wireworm damage during high-speed planting operations. EPA FIFRA tolerance requirements govern active ingredient registration, with buffer zone mandates expanding under pollinator risk reassessments. Midwest cooperative networks in Nebraska and Kansas unbundle application services to defend margins against retailer consolidation.
Brazil
Mato Grosso and Goiás frontier zones generate concentrated demand for chlorantraniliprole-coated seeds targeting soil pests in expanding soy and cotton hectares. ANVISA maintains residue protocols that frequently lag OECD harmonization, creating compliance complexity for multinational treaters operating across Americas supply chains. São Paulo-based formulation plants serve domestic distribution with limited tropical shelf-life reach.
Germany
Lower Saxony and Bavaria rapeseed programs drive pyrethroid and microbial alternative validation as EFSA neonicotinoid phase-outs tighten. The national competent authority enforces strict REACH MRL interpretations, accelerating biopesticide registration queue processing. Bayer AG maintains extensive field trial networks across European oilseed corridors to validate replacement chemistries.
Argentina
Buenos Aires and Córdoba provinces in the Pampas soybean belt prioritize seed-applied chemistry for early-season aphid and stink bug management within integrated pest management frameworks. The national agricultural technology institute validates multi-season efficacy across diverse soil complexes. Rosario-based cooperatives concentrate procurement leverage for standard treatment tiers.
France
Picardy and Champagne-Ardenne sunflower expansion creates demand for flea beetle protection where neonicotinoid restrictions exceed German stringency. EFSA pollinator guidance mandates expanded field margin buffers, forcing rapid portfolio reformulation around Beauveria bassiana microbial alternatives. Syngenta Group deploys proprietary film-coating technologies for high-value hybrid seed exports.
Global Insecticide Seed Treatment Market Competitive Landscape
The competitive structure tilts toward integrated agrichemical conglomerates with captive seed treatment divisions. Three to four multinational players control proprietary polymer binder and film-coating technologies that differentiate premium formulations from commodity treatments. Strategic moves concentrate on backward integration into active ingredient sourcing and dust-off reduction systems for pneumatic planter compatibility.
Among Swiss-German integrated conglomerates, Syngenta Group and Bayer AG occupy positions exemplifying the full-seed-pipeline archetype with internal formulation capabilities spanning breeding through treatment application. BASF SE anchors the polymer-chemistry specialist tier through backward integration into adhesive binders that reduce active ingredient dust-off. FMC Corporation represents the North American diversified agrichemical model with regional formulation presence.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| UPL Ltd |
| Valent U.S.A |
| Gowan Company |
| KENSO New Zealand |
| Others |
Supply & Pricing Matrix
Technical-grade neonicotinoid spot prices in China cascade through formulation plants into three-tier pricing structures across premium, standard, and economy levels, with polymer binder costs and ANVISA registration fees determining final treatment premiums in Brazilian distribution channels.
Pricing Analysis
Yield-protection value anchors pricing tiers, with microencapsulated formulations commanding premiums tied to replant-rate reduction in Iowa corn operations. Price differentiation separates dust-off-certified polymer coatings from commodity treatments, with brand premiums widening under EPA buffer-zone compliance costs. Cost compression in standard neonicotinoid tiers is intensifying because retailer consolidation in the Western Corn Belt concentrates procurement leverage. Agricultural cooperatives in Nebraska exhibit highest price sensitivity, while multinational seed companies demonstrate lowest sensitivity due to captive formulation capabilities.
Supply Chain Analysis
Brazilian local-content thresholds for ANVISA registration are reshaping sourcing patterns toward domestic formulation plants in São Paulo state. Active ingredient manufacturing concentrates in China, with polymer binder production anchored in Germany and the United States. Technical-grade chlorantraniliprole and imidacloprid feed from Chinese chemical parks, while film-coating equipment draws from Swiss and German engineering bases. Single-source vulnerability in Chinese technical-grade supply creates exposure to export license volatility. Distribution runs through agricultural retailers in the US Midwest and cooperatives in Brazil's Cerrado.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insecticide seed treatment sector is navigating a technology-transition phase, with microencapsulation and microbial formulations displacing legacy neonicotinoid coatings under tightening pollinator risk assessments.
For Market Incumbents: Deploy backward integration into polymer binder production to capture dust-off reduction premiums and defend margin position against retailer consolidation in the US Western Corn Belt. Accelerate biopesticide pipeline investment to preempt EFSA-driven chemistry phase-outs in German and French rapeseed programs. Threat: Formulation chemist scarcity constrains microbial product development velocity. For New Entrants and Emerging Players: Enter via Eastern European oilseed corridors in Romania and Ukraine, where neonicotinoid restrictions remain less stringent than Western EU and flea beetle protection demand is expanding with canola hectare growth. Target white-space in cold-chain microbial logistics for Beauveria bassiana distribution. Go-to-market angle: Partner with regional seed cooperatives for per-acre treatment fee models. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale treaters with ANVISA-registered portfolios and established field trial networks in Brazil's Mato Grosso frontier. Long-term viability hinges on biological formulation capabilities and polymer-rheology expertise across the projection horizon. Signal to watch: EFSA biopesticide registration queue acceleration as inflection indicator for microbial segment tipping point.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Binders | BASF SE's captive adhesive production reduces dust-off liability and secures pneumatic planter compatibility premiums. |
| Biopesticide Registration Acceleration | Queue prioritization at German and French competent authorities expands addressable market for microbial alternatives under REACH. |
| Microencapsulation Technology Deployment | Extended-release kinetics compress differentiation between premium and standard tiers in Iowa wireworm protection. |
| Per-Acre Treatment Fee Model | Nebraska and Kansas cooperatives unbundle application services to defend margins against retailer consolidation leverage. |
| Eastern European Field Trial Expansion | Bayer AG validates pyrethroid replacements across Romanian and Ukrainian rapeseed corridors ahead of EU MRL tightening. |
Research Methodology
Document review covered EPA FIFRA registration databases, EFSA guidance documents, ANVISA residue protocols, and OECD harmonization frameworks, complemented by interviews with seed company formulation directors, agricultural cooperative procurement managers, polymer chemistry R&D leads, and regulatory affairs specialists at national competent authorities. Secondary sources included customs trade data for technical-grade active ingredients, SEC 10-K filings of integrated agrichemical conglomerates, and field trial repository records. Bottom-up volume estimates from treated hectare expansion in Mato Grosso and Iowa were triangulated against top-down chemistry consumption projections.
Historical treatment adoption curves in Brazilian soy and US corn were cross-referenced against panel input from seed treater executives to model segment trajectories across the projection horizon. Segmentation dimensions encompassed formulation chemistry type, crop value density, procurement authority archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand functions incorporating planter technology diffusion and pollinator risk assessment timelines. Industry-specific inputs included ANVISA registration pathway duration estimates and EFSA MRL revision schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt neonicotinoid re-registration denial scenarios or sustained Chinese export license restrictions. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
IPM Pheromones Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
China Insecticide Market
Crop Protection
Iprodione Market
Crop Protection
South America Molluscicides Market
Crop Protection
Global Acaricides Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Isoxaflutole Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Global Aquatic Herbicides Market