
 South America Nematicides Market | 2026-2036
South America Nematicides Market Size, Share, and Industry Trends Forecast 2026-2036
South America Nematicides Market Analytics
The capital-intensity divergence between multinational and regional nematicide suppliers is collapsing as generic manufacturing scales across Brazil and Argentina. Syngenta leverages its seed-treatment integration to anchor premium positioning in soybean nematicide systems. Bayer CropScience sustains R&D intensity through in-house fermentation capacity for biological actives. FMC competes on granular formulation scale, occupying cost-sensitive field-crop segments in Argentina's grain belt.
Nematicides are biocidal or biological agents formulated to suppress plant-parasitic nematode populations in soil, typically delivered as soil-incorporated granules, seed coatings, or drench applications with active concentrations ranging from 0.5% to 40% depending on nematode species target and crop value. Their primary commercial purpose is to protect root architecture and yield in high-value row crops and vegetables where nematode pressure causes economically significant damage. Chemical nematicides still dominate volume but face margin compression from biological alternatives, while liquid formulations lead in application flexibility across Brazil's large-scale mechanized farms. Vegetable crops represent the fastest-growing application segment as protected horticulture expands in Colombia and Peru, though field crops retain the largest absolute revenue pool due to soybean and corn hectarage.
ANVISA governs nematicide registration and residue thresholds in Brazil under federal agrochemical legislation, while Argentina's national agricultural food safety and quality service enforces equivalent standards for imported and domestically manufactured products. Both frameworks are tightening environmental fate requirements, forcing reformulation away from organophosphate chemistries toward biological and reduced-risk synthetic alternatives. Stakeholders must monitor regulatory divergence between Mercosur harmonization proposals and national-level re-registration timelines to anticipate product availability shifts.
Market Dynamics
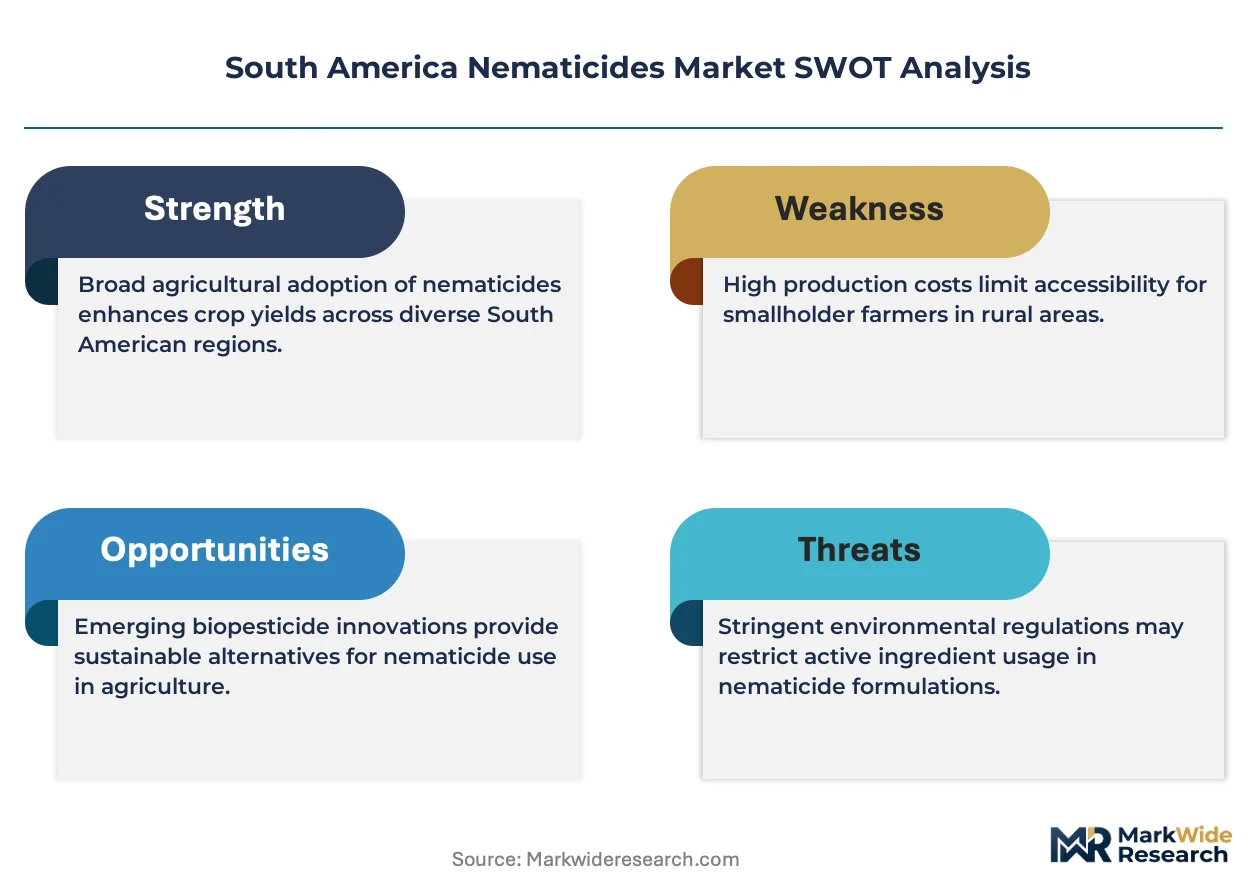
ANVISA's tightening residue limits under Brazil's updated agrochemical legislation are forcing wholesale reformulation away from organophosphate chemistries toward biological and reduced-risk synthetic alternatives. This regulatory compression is collapsing the capital-intensity gap between multinational and regional suppliers as generic manufacturing scales.
Growth Catalysts
- Seed-treatment integration:Soybean cultivation in Brazil's Cerrado region is expanding adoption of nematicide-treated seeds as a systemic delivery mechanism.
- Protected horticulture expansion:Vegetable crops in Colombia and Peru are driving demand for precision nematicide applications in controlled-environment agriculture.
- Biological active fermentation:In-house production capacity for biological nematicides is anchoring premium positioning in high-value row crop systems.
Market Restraints
- Re-registration timeline compression:ANVISA's accelerated re-registration schedules are creating product availability gaps before reformulation completion.
- Active ingredient concentration limits:Maximum residue thresholds for soil-applied organophosphates are constraining efficacy in Argentina's Pampas grain belt.
- Import dependency for biological strains:Domestic fermentation capacity shortfalls in Peru and Colombia create supply concentration risk for non-synthetic alternatives.
Strategic Opportunities
- Underpenetrated Andean vegetable corridor:Protected horticulture in Ecuador and Bolivia remains below nematicide saturation thresholds.
- Mercosur harmonization tailwinds:Proposed regulatory alignment could streamline multi-country registration for biological nematicide portfolios.
- Liquid formulation mechanization:Large-scale Brazilian farms are adopting precision application equipment compatible with liquid nematicide delivery.
Industry Challenges
- Soil microbiome compatibility testing:Biological nematicide developers lack standardized protocols for Cerrado and Pampas soil conditions.
- Application technician certification:ANVISA-mandated handler licensing is creating workforce bottlenecks during peak planting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Nematicides Market |
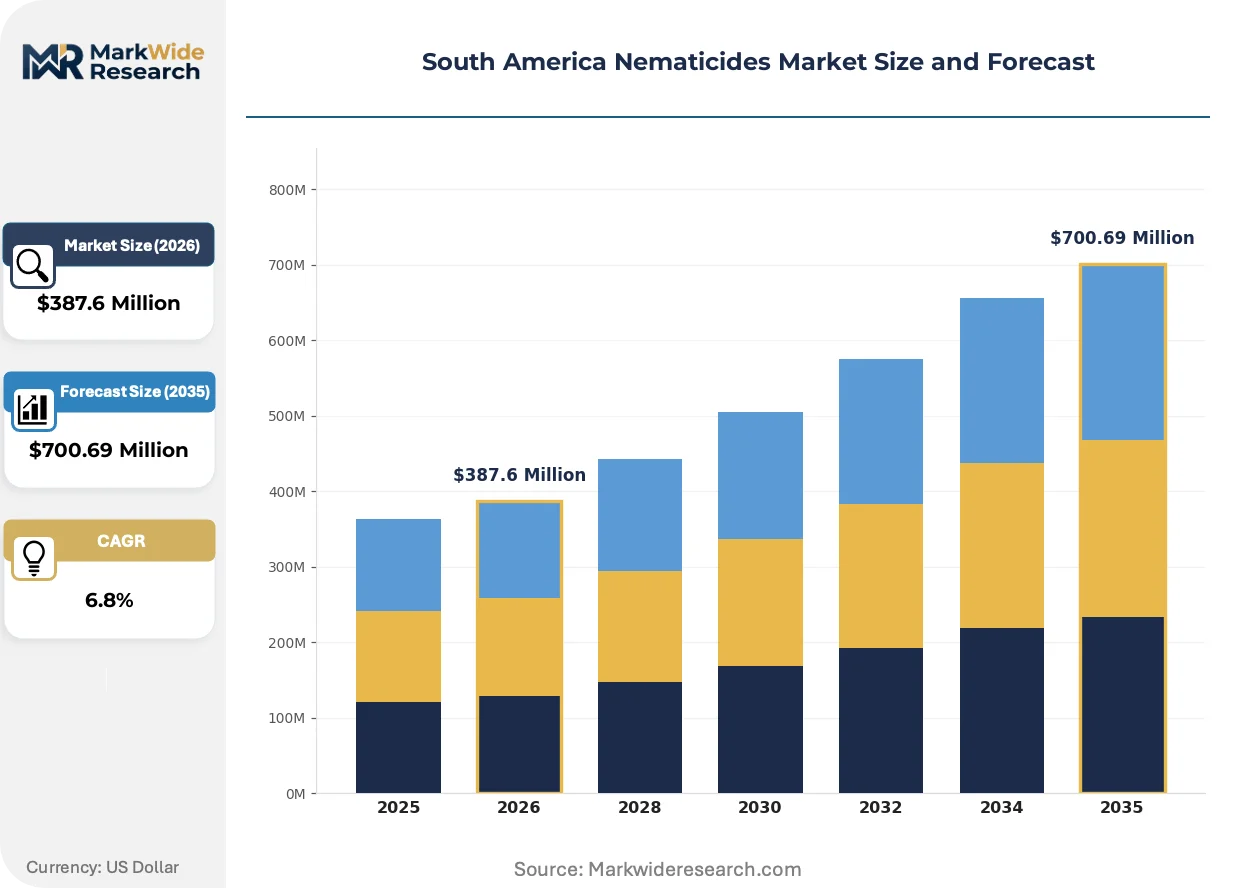
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Biological Nematicides, Chemical Nematicides, Synthetic Nematicides, Organic Nematicides Application: Vegetable Crops, Fruit Crops, Field Crops, Ornamental Plants Formulation: Granular, Liquid, Powder, Emulsifiable Concentrate Distribution Channel: Online Retail, Offline Retail, Distributors, Agronomy Services |
| Companies Covered | Adama, Corteva Agriscience, Sumitomo Chemical, Syngenta, Bayer CropScience, Agrivalle, BASF, FMC, UPL, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Nematicides Market Evolving Landscape
Biological nematicide actives are displacing synthetic organophosphates as the dominant R&D investment target. Formulation science and delivery mechanism innovation are converging to address the efficacy gap that previously constrained adoption.
Microbial fermentation-derived nematicides containing Purpureocillium lilacinum and Bacillus firmus are displacing organophosphate soil treatments in Brazilian soybean systems. Large-scale mechanized farms in Mato Grosso and Goiás are adopting these biological alternatives at pace despite higher per-hectare costs. The technology is displacing premium-priced synthetic chemistries in the seed-treatment segment while compressing margins for granular formulation suppliers.
ANVISA's updated agrochemical legislation is tightening environmental fate requirements for nematicide registration and residue thresholds. The industrial consequence is forced reformulation timelines that outpace biological active development cycles. Soybean and corn seed-treatment categories are most affected, with suppliers accelerating partnerships with domestic fermentation facilities to secure registration continuity.
Buyer procurement is consolidating around integrated pest management bundles that combine nematicide seed coatings with monitoring services. Argentina's grain cooperatives and Brazilian mega-farms are displacing standalone chemical purchases with outcome-based supplier contracts. This pattern is most visible in the Pampas region, where soil-applied nematicide volumes are shifting toward treated-seed channels controlled by multinational seed-treatment integrators.
South America Nematicides Market Segmentation
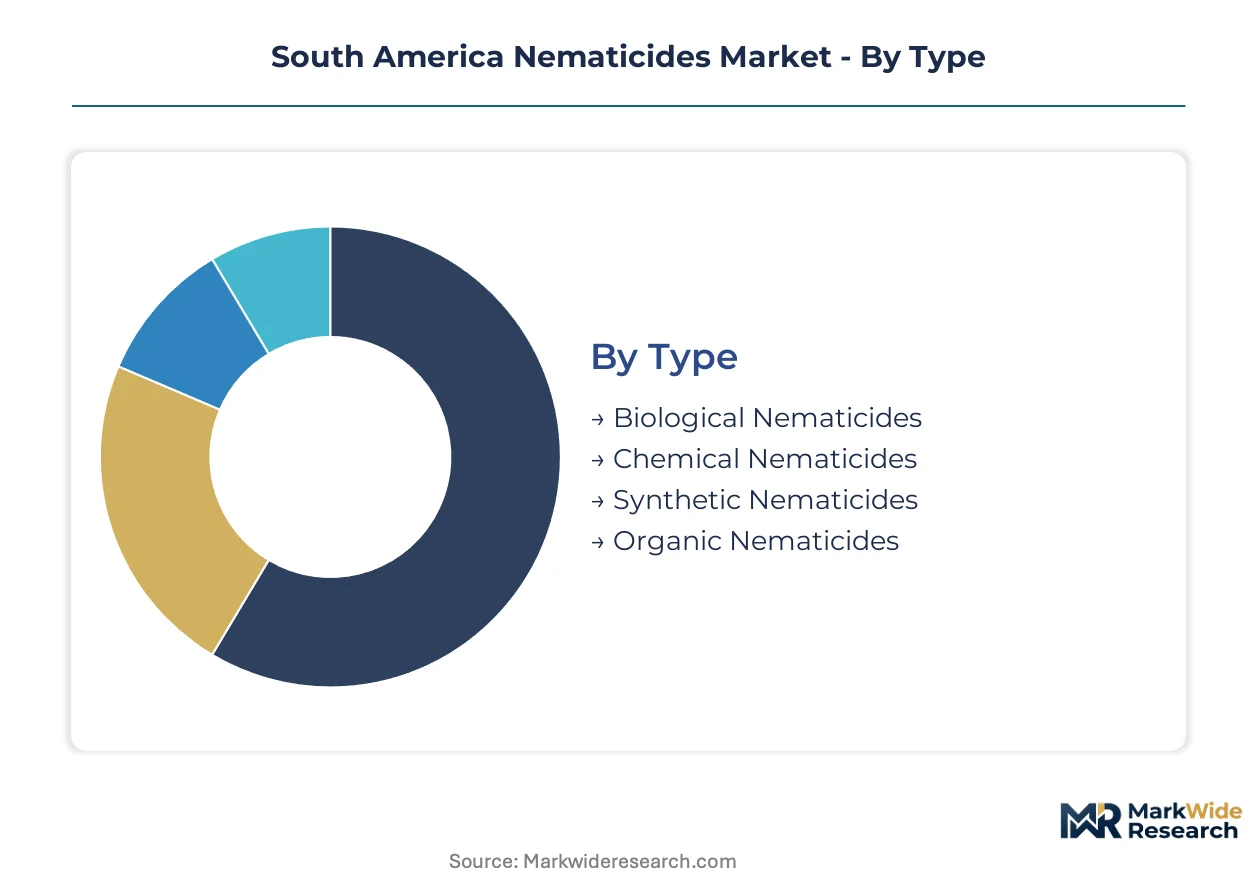
Nematicide segmentation in South America reflects divergent regulatory pressures across ANVISA's Brazilian framework and Argentina's agricultural safety standards. Suppliers must align product portfolios with tightening residue thresholds while addressing distinct agronomic needs across soybean monocultures and emerging protected horticulture zones.
Type:
ANVISA's accelerated re-registration schedules favor biological actives with streamlined environmental fate profiles over legacy organophosphate chemistries.
- Chemical Nematicides:Organophosphate and carbamate-based soil treatments retain dominant hectarage coverage in Argentina's Pampas grain belt. ANVISA's tightening maximum residue thresholds for soil-applied organophosphates are compressing efficacy windows and forcing reformulation investments.
- Biological Nematicides:Microbial fermentation-derived actives containing Purpureocillium lilacinum and Bacillus firmus displace synthetic alternatives in Brazilian soybean seed-treatment systems. Domestic fermentation capacity expansions in São Paulo and Paraná are reducing import dependency for these strains.
- Synthetic Nematicides:Reduced-risk synthetic alternatives with favorable environmental fate profiles occupy mid-tier positioning between biological and legacy chemical segments.
- Organic Nematicides:Plant-extract and essential-oil formulations serve certified organic operations in Colombia's protected vegetable corridors.
Established volume favors chemical nematicides; emerging adoption favors biological alternatives.
Application:
Customer procurement patterns split between outcome-based contracts for field crops and precision application bundles for high-value horticulture.
- Field Crops:Soybean and corn cultivation across Brazil's Cerrado and Argentina's Pampas generates the largest absolute revenue pool. Nematicide-treated seeds are displacing standalone soil-applied granules as systemic delivery mechanisms consolidate purchasing around integrated seed-treatment channels.
- Vegetable Crops:Protected horticulture expansion in Colombia's Bogotá savanna and Peru's coastal valleys drives precision nematicide demand. Controlled-environment agriculture requires compatible biological actives that preserve soil microbiome integrity for successive cropping cycles.
- Fruit Crops:Grape and citrus operations in Chile's Central Valley and Brazil's São Paulo state apply nematicides through drip irrigation systems.
- Ornamental Plants:Floriculture clusters in Colombia's Antioquia department and Ecuador's Quito plateau utilize reduced-rate applications for export certification compliance.
Field crops anchor supplier revenue; vegetable crops are climbing the fastest adoption trajectory.
Formulation:
Mechanization intensity across Brazilian mega-farms favors application technologies compatible with precision agriculture equipment.
- Liquid:Emulsifiable and suspension concentrates enable precision application through existing spraying infrastructure on Mato Grosso and Goiás mechanized operations. Compatibility with variable-rate technology supports outcome-based supplier contracts.
- Granular:Soil-incorporated granules retain cost-sensitive positioning in Argentina's grain belt cooperatives where equipment retrofitting lags. FMC and regional suppliers compete on formulation scale for this segment.
- Powder:Dry flowable formulations serve niche protected horticulture applications requiring tank-mix flexibility.
- Emulsifiable Concentrate:Traditional EC formulations face displacement where water-based alternatives reduce handler exposure compliance burdens.
Granular formulations dominate Argentina's Pampas; liquid alternatives gain share fastest in Brazil's Cerrado.
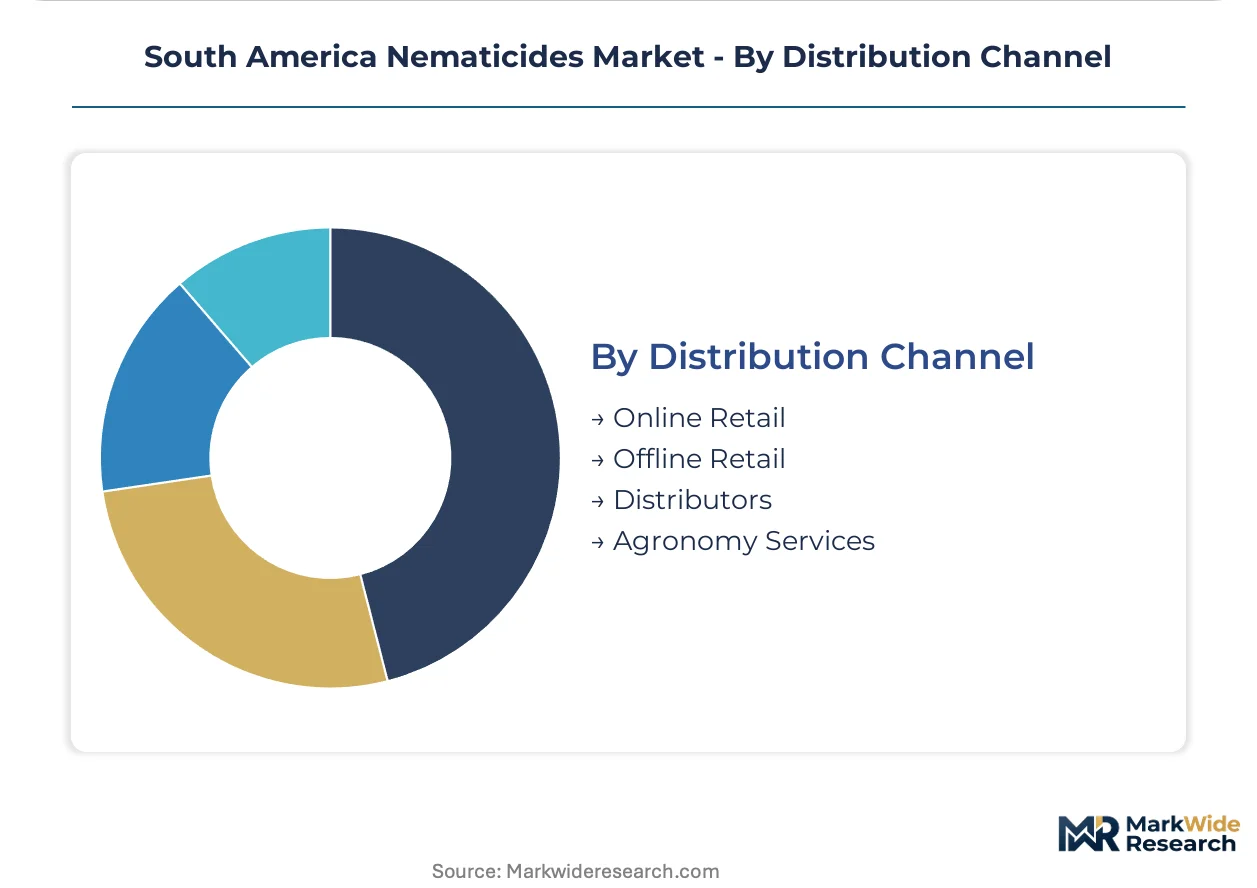
Distribution Channel:
Channel structure reflects the consolidation of Brazilian mega-farm procurement and the cooperative-dominated purchasing patterns of Argentina's grain belt.
- Agronomy Services:Integrated pest management bundles combining nematicide seed coatings with soil monitoring and application services displace standalone chemical purchases. Syngenta and Bayer CropScience anchor this channel through seed-treatment integration.
- Distributors:Regional agrochemical distributors retain relevance in Argentina's Pampas where grain cooperatives aggregate purchasing for member farms.
- Offline Retail:Traditional farm supply stores serve smallholder operations in Peru's Andean valleys and Ecuador's vegetable corridors with limited digital infrastructure.
- Online Retail:E-commerce penetration remains concentrated in Brazil's southern states where larger operations utilize digital procurement platforms.
Distributors and agronomy services command established volume; online retail channels show steepest expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's grain belt exhibits the sharpest price elasticity, with cooperatives driving volume through cost-optimized procurement. Brazil's mega-farms accept premium positioning for integrated seed-treatment systems. Colombia's protected horticulture corridor occupies the middle ground, balancing efficacy requirements against certification compliance costs.
Brazil
Soybean expansion across Mato Grosso and Goiás powers nematicide-treated seed adoption. ANVISA's accelerated re-registration schedules compress product availability windows for legacy chemistries. São Paulo and Paraná fermentation facilities are scaling biological active capacity to reduce import dependency.
Argentina
Pampas grain belt cooperatives aggregate purchasing for soil-applied formulations across corn and wheat rotations. The national agricultural food safety and quality service enforces residue thresholds that constrain organophosphate efficacy. Buenos Aires province distribution hubs channel volume toward cost-sensitive field-crop segments.
Colombia
Protected horticulture in the Bogotá savanna demands precision nematicide applications for export-certified vegetable production. The national agricultural institute regulates biological strain importation and soil microbiome compatibility testing. Antioquia department floriculture clusters utilize reduced-rate applications for phytosanitary certification compliance.
Chile
Central Valley grape and citrus operations deploy nematicides through drip irrigation infrastructure. The agricultural and livestock service administers residue monitoring programs aligned with European export market requirements. O'Higgins and Maule region concentrated plantings sustain steady demand for soil-incorporated formulations.
Peru
Coastal valley asparagus and avocado exports drive biological nematicide adoption for organic certification maintenance. The national agricultural health service regulates importation of microbial strains with limited domestic fermentation alternatives. Ica and La Libertad region controlled-environment operations require successive-cropping compatible actives.
South America Nematicides Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Multinational agrochemical conglomerates anchor premium positioning through seed-treatment integration and biological R&D pipelines. Regional generic manufacturers compete on formulation scale and distributor relationships. Strategic moves concentrate on domestic fermentation partnerships and precision application equipment compatibility.
Within the multinational tier, Syngenta and Bayer CropScience exemplify integrated seed-treatment positioning. FMC occupies cost-sensitive granular formulation segments. Among regional specialists, Agrivalle and UPL represent scaled generic manufacturing archetypes with distributor channel depth across Mercosur markets.
| Leading Market Players |
|---|
| Adama |
| Corteva Agriscience |
| Sumitomo Chemical |
| Syngenta |
| Bayer CropScience |
| Agrivalle |
| BASF |
| FMC |
| UPL |
| Others |
Value Network & Pricing Analysis
Ninety-day fermentation batch cycles for biological actives concentrate pricing power with São Paulo and Paraná facilities, compressing margins for Argentine granular suppliers dependent on imported organophosphate intermediates. Inventory positioning across Brazilian mega-farms now favors liquid formulation compatibility over cost-optimized soil-incorporated alternatives.
Pricing Analysis
After-sales service bundles combining soil monitoring with nematicide seed coatings now drive lifetime value capture for integrated suppliers. Three-tier pricing structure across premium biological seed treatments, mid-tier synthetic alternatives, and economy granular formulations reflects certification grade and volume scale differentiation. Pricing pressure stems from ANVISA's accelerated re-registration timelines forcing premature product exits before reformulation completion. Argentine grain cooperatives exhibit highest price sensitivity, while Brazilian mega-farms accept premium positioning for outcome-based IPM contracts.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for microbial strains imported from European fermentation specialists. Supply concentrates in Brazil for biological actives, China for organophosphate intermediates, and India for generic synthetic precursors. Raw material dependencies span fermentation feedstocks, active ingredient concentrates, and seed-treatment polymer coatings. Single-source vulnerability sits with Purpureocillium lilacinum strain imports for Colombian and Peruvian protected horticulture. Distribution runs through agronomy service channels for Brazilian mega-farms and regional cooperatives for Argentina's Pampas grain belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as ANVISA's regulatory compression splinters demand across biological alternatives, reduced-risk synthetics, and legacy reformulations, creating specialist niches for fermentation-scale players and precision application technology providers.
For Market Incumbents: Compound seed-treatment integration advantages by anchoring exclusive biological active supply agreements with São Paulo fermentation facilities before re-registration deadlines eliminate competitor product availability. Defend margin position through backward integration into in-house Purpureocillium lilacinum production capacity, neutralizing import dependency risks that constrain regional generic manufacturers. For New Entrants and Emerging Players: Lead with precision application equipment compatibility for liquid biological formulations targeting Colombia's Bogotá savanna protected horticulture corridor, where nematicide saturation remains below threshold and certification premiums support price realization. White-space concentration sits with Ecuador and Bolivia Andean vegetable operations lacking established supplier relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-transition play because ANVISA's environmental fate requirements will permanently displace organophosphate chemistries, favoring acquirers of domestic Brazilian fermentation assets with streamlined registration pathways. Acquisition target archetype: mid-cap biological active specialists with ANVISA-approved strain portfolios and scalable production infrastructure. Signal to watch: Mercosur harmonization proposal advancement creating multi-country registration efficiency for biological portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Expansion | São Paulo and Paraná facilities reduce import dependency for Purpureocillium lilacinum and Bacillus firmus strains. |
| Precision Application Equipment Partnership | Mato Grosso and Goiás mega-farms adopt variable-rate technology compatible with liquid nematicide delivery. |
| Biological Strain Registration Acceleration | ANVISA's streamlined environmental fate profiles favor microbial alternatives over legacy chemistries. |
| Integrated Pest Management Bundle Development | Argentine grain cooperatives shift procurement toward outcome-based contracts combining monitoring with treatment. |
| Mercosur Harmonization Alignment | Proposed regulatory convergence streamlines multi-country biological nematicide registration across Brazil, Argentina, and associate members. |
Research Methodology
A standing panel of fermentation facility operations managers, ANVISA regulatory affairs specialists, Argentine grain cooperative procurement directors, and Brazilian mega-farm agronomists provided ongoing calibration across primary interview cycles. Secondary validation drew from ANVISA registration databases, Brazilian customs trade records for nematicide active ingredient imports, SEC filings of multinational agrochemical conglomerates, and regional agricultural extension service reports. Bottom-up hectarage estimates by crop type and nematicide application rate triangulated against top-down manufacturer shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning nematicide type, application crop category, formulation technology, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating ANVISA re-registration timeline assumptions and biological active adoption elasticity parameters. Industry-specific forecast inputs included soybean hectarage expansion rates in Brazil's Cerrado and protected horticulture growth trajectories in Colombia and Peru.
The analysis sits within stated boundaries; outcomes outside ANVISA's current regulatory enforcement intensity or Mercosur harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding biological active efficacy parity achievement and domestic fermentation capacity scaling timelines. Specific risk factors that could revise projections include accelerated organophosphate phase-out schedules, trade disruption affecting microbial strain imports, and cooperative consolidation altering Argentine procurement concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Europe Acaricides Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Tebuconazole Market
Crop Protection
Nematicides Market
Crop Protection
Dicamba Market
Crop Protection
Pest Control Services Market
Crop Protection
North America Molluscicides Market
Crop Protection
Global Insecticides Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Grape Fungicides Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Propiconazole Market