
 Rodent Control Pesticides Market | 2026-2036
Rodent Control Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Rodent Control Pesticides Market Analytics
Chinese active ingredient manufacturers is pivoting toward consolidated production of bromadiolone and difenacoum intermediates to serve formulators in Europe and North America. Bayer AG leverages backward integration into chlorophacinone synthesis to secure cost positions in agricultural rodenticide contracts. BASF SE anchors its position through specialized brodifacoum formulations targeting commercial pest control operators. Rentokil Initial PLC competes by controlling service-led distribution channels that bundle bait station deployment with monitoring protocols.
Rodent control pesticides comprise chemical formulations designed to induce mortality in murine species, with anticoagulant compounds functioning through vitamin K antagonism that disrupts blood clotting cascades over multiple feedings. These products serve commercial, agricultural, and residential sectors where rodent-borne contamination threatens food safety, structural integrity, and public health infrastructure. Anticoagulants occupy the largest value share due to established efficacy and regulatory familiarity, while non-anticoagulants such as cholecalciferol and bromethalin represent the fastest-expanding category as resistance management and non-target toxicity concerns intensify. Pellet formulations dominate commercial and agricultural channels for controlled placement, whereas liquid concentrates gain traction in integrated pest management programs requiring dilution flexibility and precision application.
The EPA's risk mitigation decision for rodenticides restricts second-generation anticoagulant sales to certified applicators and mandates bait station use in residential settings, directly constraining consumer-channel product formats. ECHA's REACH and Biocidal Products Regulation frameworks govern active substance approval timelines across EU member states, creating extended registration cycles that favor incumbents with established dossiers. The EU Green Deal's Farm to Fork strategy further pressures agricultural rodenticide loadings through integrated pest management mandates and buffer zone requirements. Stakeholders must monitor regulatory divergence between jurisdictions where EPA restrictions tighten consumer access while EU frameworks emphasize substitution principles, requiring portfolio diversification across anticoagulant and non-anticoagulant chemistries alongside formulation innovations that reduce environmental persistence.
Market Dynamics
EPA risk mitigation measures are compressing consumer-channel access for second-generation anticoagulants while accelerating certified applicator consolidation and bait station standardization across commercial and agricultural procurement channels.
Growth Catalysts
- Urban pest management expansion:Metropolitan areas in the United States are scaling procurement of integrated rodent control programs. Municipal contracts now bundle monitoring protocols with bait station deployment.
- REACH framework consolidation:ECHA's Biocidal Products Regulation is streamlining active substance approvals across EU member states. Incumbents with established dossiers capture extended registration timelines.
- Resistance management protocols:Agricultural operators are rotating anticoagulant and non-anticoagulant chemistries to preserve efficacy. Cholecalciferol and bromethalin adoption is accelerating in California and Texas row-crop applications.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers dominate bromadiolone and difenacoum intermediate production. Formulators in Europe and North America face single-source dependency risks.
- EPA label restrictions:The agency's residential-use prohibitions on second-generation anticoagulants eliminate consumer-channel revenue streams. Product registration pathways now require multi-year efficacy and environmental fate studies.
- Non-target toxicity liabilities:Secondary poisoning incidents involving raptors and mammalian predators trigger litigation and reputational damage. Insurance costs for commercial applicators are rising in litigious jurisdictions.
Strategic Opportunities
- EU Farm to Fork substitution mandates:The Green Deal's integrated pest management requirements are creating openings for bio-based rodenticides with reduced environmental persistence. Buffer zone restrictions favor precision baiting technologies.
- Service-led distribution channels:Pest control operators are consolidating procurement through bundled monitoring and deployment contracts. Equipment-as-a-service models for connected bait stations are penetrating commercial facilities.
- Precision application convergence:Integration of GIS mapping with bait station telemetry is enabling targeted dosing in agricultural perimeters. California's Central Valley operators are piloting drone-assisted placement protocols.
Industry Challenges
- Toxicology expertise scarcity:Regulatory dossier preparation requires specialized knowledge of rodenticide metabolism and environmental fate. Contract research organizations with relevant track records command premium pricing.
- Legacy bait station retrofitting:Commercial facilities face capital outlays to replace non-compliant hardware with tamper-resistant enclosures mandated by EPA risk mitigation measures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rodent Control Pesticides Market |
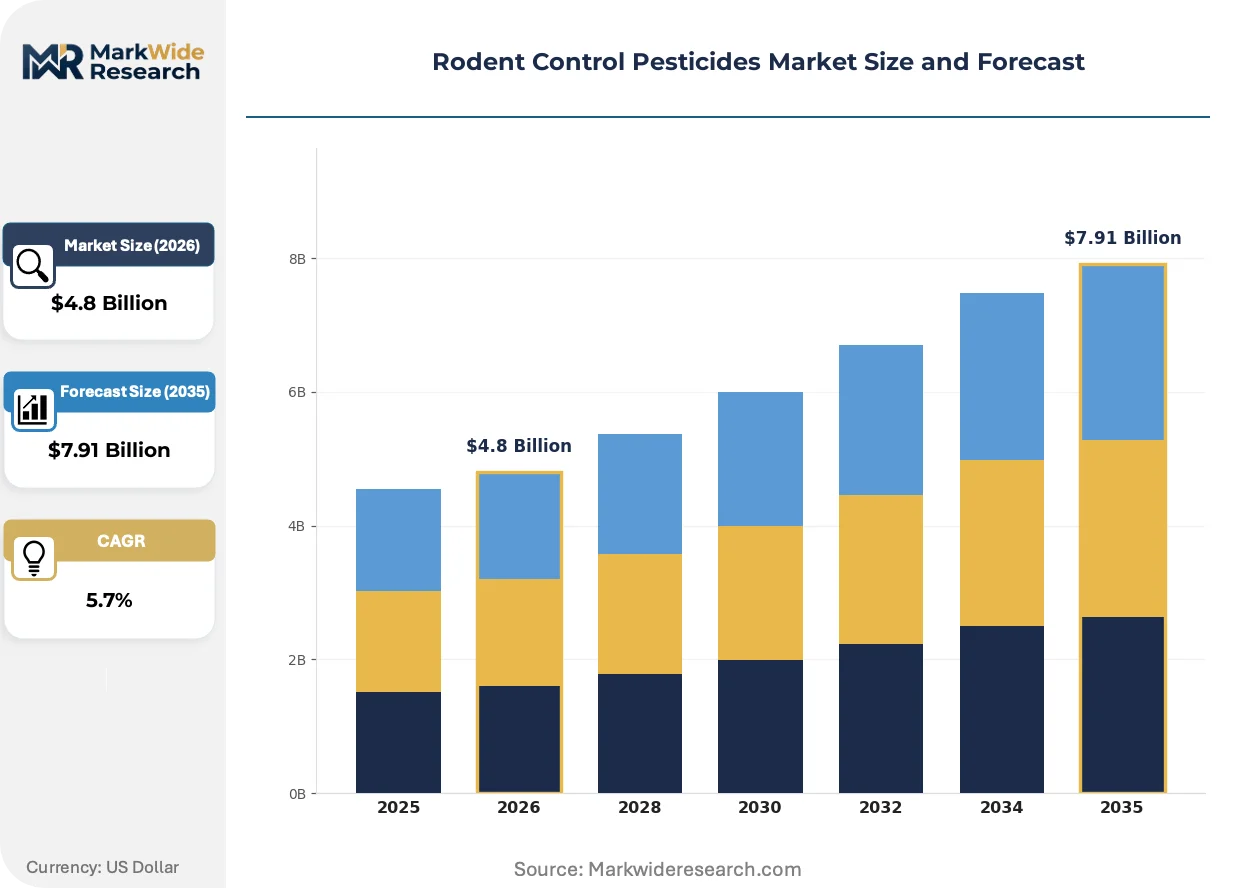
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Non-Anticoagulants, Rodent Bait Stations, Repellents Application: Residential, Commercial, Agriculture, Industrial Formulation: Granules, Pellets, Liquids, Powders Distribution Channel: Retail, Online, Distributors, Direct Sales |
| Companies Covered | Bayer AG, UPL Limited, Anticimex, Rentokil Initial PLC, Liphatech, Inc., BASF SE, Syngenta AG, Neogen Corporation, Bell Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rodent Control Pesticides Market Evolving Landscape
Digital monitoring systems and precision application technologies are displacing passive baiting protocols, while regulatory frameworks on both sides of the Atlantic accelerate chemistry diversification and service-model reinvention.
Connected bait stations equipped with sensors and cellular telemetry are automating rodent activity detection and consumption tracking. Commercial pest control operators in the United States are deploying these systems in food processing facilities and warehouse complexes. The technology is automating service route optimization and reducing unnecessary technician visits while generating compliance documentation for audit trails.
ECHA's Biocidal Products Regulation renewal cycles are compressing active substance approval timelines and favoring incumbents with complete toxicological dossiers. European formulators face extended data requirements for environmental risk assessments. Agricultural rodenticide suppliers are responding by prioritizing brodifacoum and difenacoum re-registrations over novel chemistry investments.
Certified applicator procurement is consolidating through multi-year service contracts that unbundle product supply from labor deployment. Food retail and logistics operators in Texas and California are shifting from spot purchases to integrated pest management subscriptions. This restructuring is most visible in metropolitan corridors where EPA restrictions have eliminated over-the-counter alternatives.
Rodent Control Pesticides Market Segmentation
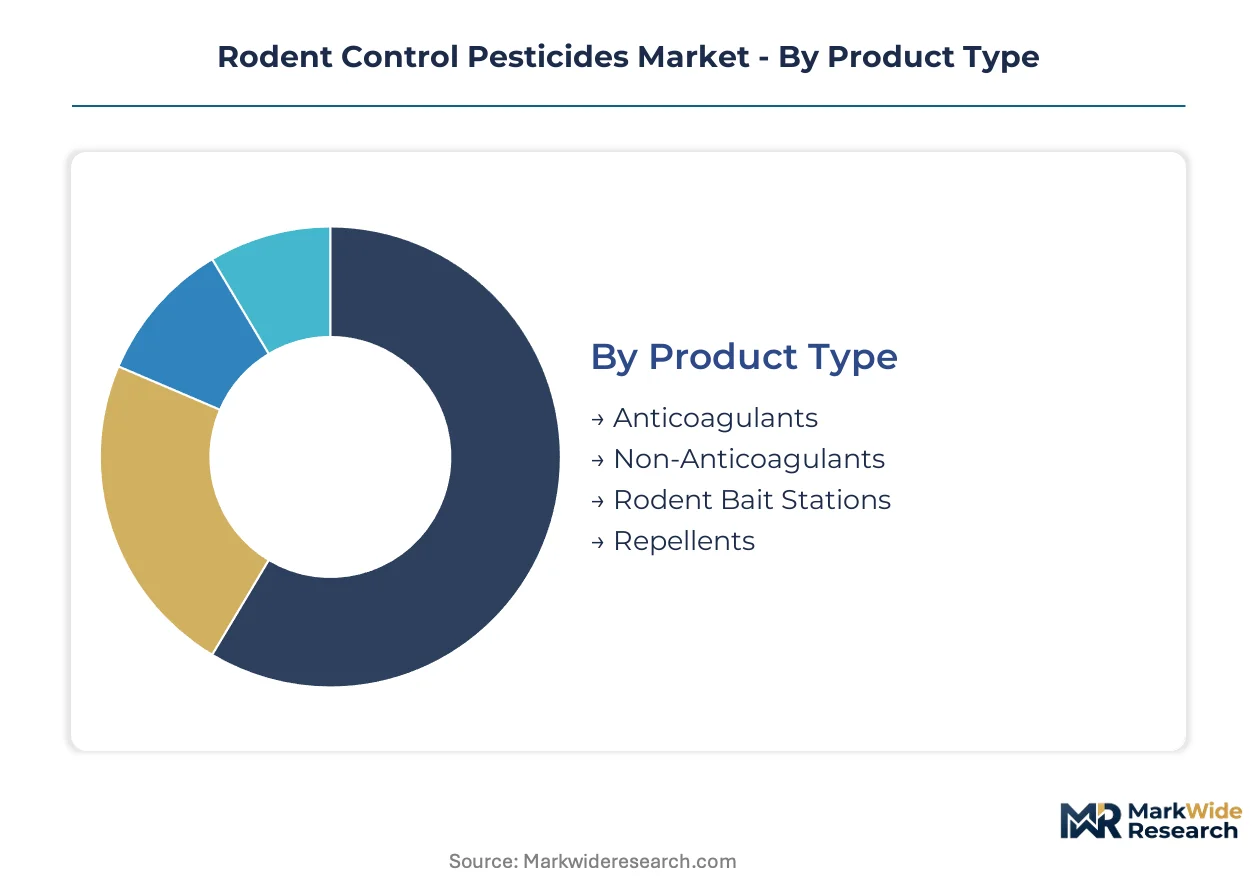
Rodent control pesticide segmentation reveals how regulatory pressure and application environment dictate chemistry selection and formulation investment. Procurement patterns diverge sharply between certified applicator channels and residual consumer access points.
Product Type:
Supply concentration in active ingredient manufacturing favors established anticoagulant chemistries while resistance protocols accelerate alternative chemistry development.
- Anticoagulants:Vitamin K antagonists including first-generation compounds (warfarin, chlorophacinone) and second-generation actives (bromadiolone, difenacoum, brodifacoum) function through cumulative clotting cascade disruption. EPA risk mitigation measures have compressed residential distribution for second-generation variants, concentrating demand in California and Texas agricultural and commercial channels where certified applicator requirements dominate procurement.
- Non-Anticoagulants:Cholecalciferol and bromethalin formulations operate through calcium mobilization and neurotoxic mechanisms respectively, offering rotation options for resistance management. These chemistries are expanding most quickly in metropolitan pest management contracts where secondary poisoning liability concerns intensify scrutiny of traditional anticoagulant deployments.
- Rodent Bait Stations:Tamper-resistant enclosures mandated by EPA residential-use restrictions anchor compliance infrastructure for integrated pest management programs.
- Repellents:Ultrasonic and chemical deterrents occupy niche positioning in prevention-focused protocols with limited mortality induction.
Today's leader: Anticoagulants. Tomorrow's challenger: Non-Anticoagulants.
Application:
End-use environment determines formulation specification, dosing protocol, and regulatory pathway complexity.
- Residential:EPA prohibitions on second-generation anticoagulant consumer sales have eliminated over-the-counter product formats. Demand concentrates in professional service subscriptions deploying bait station protocols in single-family and multi-unit housing across California metropolitan corridors.
- Commercial:Food processing facilities, warehouse complexes, and hospitality operators in Texas and California are consolidating procurement through multi-year integrated pest management contracts bundling monitoring telemetry with bait station deployment.
- Agriculture:Row-crop perimeters and grain storage operations rotate chemistries to preserve efficacy against resistant populations.
- Industrial:Manufacturing and logistics infrastructure requires perimeter protocols with audit documentation for food safety certification compliance.
Commercial applications command premium positioning through service integration. Agricultural volume sustains bulk formulation economics.
Formulation:
Physical form factor dictates application precision, environmental persistence, and handler exposure risk.
- Pellets:Extruded bait matrices enable controlled placement in bait stations and perimeter burrows. Commercial and agricultural channels in Texas favor pellet formats for mechanical dispenser compatibility and consumption monitoring.
- Liquids:Concentrates and ready-to-use solutions support precision application in integrated pest management programs requiring dilution flexibility. California Central Valley operators are piloting drone-assisted liquid placement protocols for agricultural perimeter coverage.
- Granules:Scatter-applied formulations serve broadcast treatment protocols with weather-resistant binding agents.
- Powders:Tracking powders and dust formulations occupy specialized tracking applications with limited volume contribution.
Pellet formulations dominate current procurement. Liquid concentrates show steepest expansion trajectory through precision application convergence.
Distribution Channel:
Channel structure reflects regulatory access tiers and service integration depth.
- Distributors:Pest control operator supply networks aggregate product procurement for certified applicators, consolidating volume through regional distribution centers serving Texas and California metropolitan markets.
- Direct Sales:Agricultural and commercial accounts with sufficient volume leverage manufacturer relationships bypassing distributor markups for bulk anticoagulant and non-anticoagulant formulations.
- Retail:First-generation anticoagulant and repellent products persist in hardware and garden center channels with constrained second-generation access.
- Online:E-commerce platforms face EPA enforcement scrutiny for restricted product listings, limiting legitimate channel development.
Distributor networks capture certified applicator consolidation. Direct sales penetration deepens with agricultural account scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting active ingredient production toward jurisdictions with streamlined chemical registration frameworks, while end-use demand concentrates in markets with stringent food safety enforcement.
United States
California and Texas metropolitan corridors drive certified applicator procurement of second-generation anticoagulants for agricultural and commercial contracts. EPA risk mitigation measures have eliminated consumer-channel sales while mandating tamper-resistant bait station deployment. The Central Valley agricultural cluster pilots drone-assisted liquid placement protocols for perimeter rodent control.
Germany
Integrated pest management mandates under the EU Green Deal's Farm to Fork strategy are accelerating substitution toward bio-based alternatives with reduced environmental persistence. ECHA's Biocidal Products Regulation renewal cycles favor incumbents with complete toxicological dossiers for brodifacoum and difenacoum. The Rhine-Ruhr industrial corridor concentrates formulator operations serving commercial pest control operators.
China
Active ingredient manufacturers in Jiangsu and Zhejiang provinces dominate bromadiolone and difenacoum intermediate production for export to European and North American formulators. The country's national chemical regulator maintains streamlined registration pathways for legacy anticoagulant chemistries. Yangtze River Delta production clusters face mounting environmental compliance costs that threaten cost positions.
United Kingdom
Urban pest management services in Greater London are consolidating procurement through multi-year integrated pest management subscriptions bundling monitoring telemetry with bait station deployment. The Health and Safety Executive's rodenticide stewardship scheme restricts amateur use of second-generation anticoagulants. Food retail and logistics operators in the Southeast are shifting from spot purchases to service-led contracts.
Brazil
Agricultural rodenticide demand concentrates in São Paulo and Mato Grosso grain storage and row-crop perimeter applications. ANVISA's pesticide re-registration requirements are extending approval timelines for novel chemistries. The country's national agricultural research corporation promotes resistance management protocols rotating anticoagulant and non-anticoagulant chemistries.
Rodent Control Pesticides Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital monitoring integration and service-led distribution models. The market exhibits tiered concentration with multinational chemical conglomerates controlling active ingredient synthesis and specialized formulators competing on application-specific efficacy. Three archetypes dominate: backward-integrated agrichemical conglomerates, service-anchored pest control operators, and precision equipment specialists. Competitive dynamics center on regulatory dossier completeness and bait station telemetry integration rather than price alone.
Among German and Swiss agrichemical conglomerates, Bayer AG and BASF SE exemplify backward-integrated producers with captive chlorophacinone and brodifacoum synthesis capabilities. Rentokil Initial PLC represents the service-led archetype, controlling distribution channels that bundle bait station deployment with monitoring protocols rather than competing on product supply alone.
| Leading Market Players |
|---|
| Bayer AG |
| UPL Limited |
| Anticimex |
| Rentokil Initial PLC |
| Liphatech, Inc. |
| BASF SE |
| Syngenta AG |
| Neogen Corporation |
| Bell Laboratories Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal buffer zone mandates gate qualified supply for precision baiting technologies and premium-tier pricing access for connected monitoring systems. Certified applicator consolidation in California and Texas metropolitan corridors is compressing distributor margins while elevating service-integrated contract values.
Pricing Analysis
Distributor margin layers in the certified applicator channel absorb 15-25 point markups before service bundling. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-enabled bait station systems from conventional hardware from unregistered generic actives. Price differentiation hinges on EPA registration tier and volume scale, with agricultural bulk procurement commanding steepest discounts. Cost compression in the consumer-channel tier is intensifying because EPA residential prohibitions eliminated over-the-counter revenue streams entirely. Food processing facilities in Texas demonstrate least price sensitivity due to audit compliance requirements, while independent pest control operators in secondary markets remain most margin-constrained.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Zhejiang provinces are elevating environmental compliance costs for Chinese intermediate manufacturers. Active ingredient supply concentrates in China for bromadiolone and difenacoum, with formulation finishing distributed across Germany, the United States, and Brazil. Raw material dependencies rest on naphthoquinone precursors, coumarin derivatives, and specialized polymer binders for bait matrices. Single-source vulnerability from Chinese intermediate concentration threatens European and North American formulator security. Distribution runs through pest control operator supply networks consolidating regional volume through Texas and California distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rodent control pesticides rests on chemistry diversification into non-anticoagulant alternatives and service-integrated delivery models that capture recurring revenue. Substitution mandates and resistance protocols are elevating premium-tier pricing power for precision application technologies.
For Market Incumbents: Extend regulatory dossier completeness into brodifacoum and difenacoum re-registrations ahead of ECHA renewal cycles to lock out challenger chemistries. Deepen backward integration into chlorophacinone synthesis to defend cost positions against Chinese intermediate volatility. Capture channel control through exclusive service contracts with food retail and logistics operators in California metropolitan corridors, neutralizing price competition from generic formulators. For New Entrants and Emerging Players: EPA risk mitigation measures in the United States open a window for telemetry-enabled bait station specialists to bypass traditional product registration barriers through equipment-as-a-service models. Target precision agriculture applications in California Central Valley row-crop perimeters where drone-assisted liquid placement protocols remain underpenetrated. Pursue go-to-market partnerships with established pest control operators seeking digital differentiation rather than competing on chemistry supply alone. For Investors and Strategic Acquirers: Roll-up economics work for regional pest control operators because certified applicator licensing requirements create local moats against national platform expansion. The 5-10 year viability window favors service-led distribution models over pure-formulation plays as EPA and ECHA restrictions compress product-channel access. Monitor ECHA active substance approval timelines as inflection indicator for incumbent competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Synthesis | Bayer AG's captive chlorophacinone production secures agricultural contract margins against Chinese intermediate volatility. |
| Telemetry-Enabled Bait Station Deployment | Rentokil Initial PLC's connected monitoring systems automate compliance documentation for food safety audits. |
| Non-Anticoagulant Chemistry Registration | Cholecalciferol and bromethalin dossiers capture resistance management demand in California row-crop applications. |
| Service-Led Distribution Consolidation | Multi-year integrated pest management subscriptions bundle product supply with labor deployment in Texas metropolitan corridors. |
| Precision Application Technology Pilot | Drone-assisted liquid placement protocols in California Central Valley reduce perimeter bait loading under buffer zone restrictions. |
Research Methodology
Direct dialogue with plant managers at active ingredient manufacturers, procurement leads at agricultural formulators, distribution channel partners in Texas and California, and technical R&D directors at bait station equipment specialists grounded qualitative findings. Secondary validation drew from EPA registration databases, ECHA biocidal product dossiers, customs and trade data for intermediate imports, and SEC filings of publicly traded agrichemical conglomerates. Bottom-up volume estimates from end-use application rates and top-down value triangulation from manufacturer revenue disclosures were reconciled across the analysis window.
Bottom-up modeling segmented demand by chemistry type, application environment, formulation format, and distribution channel depth. Top-down validation tracked active ingredient production capacity by manufacturing geography and formulator procurement patterns. CAGRs were derived from regression analysis of historical application rate trends against regulatory constraint intensities. Industry-specific forecast inputs included EPA risk mitigation compliance timelines and ECHA Biocidal Products Regulation renewal schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory acceleration or supply chain disruption scenarios. Forecasts reflect assumptions about certified applicator consolidation velocity and resistance protocol adoption rates. Material deviation in ECHA active substance approval timelines or Chinese environmental enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Isoxaflutole Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Europe Herbicide Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Propiconazole Market