
 Egypt Compound Feed Market | 2026-2036
Egypt Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Compound Feed Market Foresight
Egypt's push toward sustainable aquaculture under the National Sustainable Development Strategy is consolidating investment across feed value chains. Cargill leverages its Red Sea logistics infrastructure to supply soy-based protein meals to commercial dairy operations. Dakahlia Poultry Company anchors the northern Delta region through backward integration into grain storage and milling. Alltech competes on mycotoxin-binding technology, differentiating its additive portfolio for humidity-stressed Egyptian conditions.
Compound feed denotes nutritionally complete manufactured diets formulated from ground cereal grains, protein meals, vitamins, and additives, pelleted or mash-processed to deliver precise metabolizable energy and amino acid profiles for targeted livestock performance. Poultry feed dominates volume as Egypt's broiler sector scales to serve domestic protein demand, while aquaculture feed emerges as the fastest-growing category driven by tilapia intensification in Lake Nasser and Delta ponds. Ruminant feed remains mature, with margin pools shifting toward vitamin-premium formulations for high-yielding Holstein herds.
The Ministry of Agriculture and Land Reclamation enforces feed safety protocols aligned with FAO Codex standards, while the Egyptian Organization for Standardization and Quality mandates labeling and contaminant thresholds that shape import sourcing. The General Authority for Veterinary Services inspects commercial feed mills, restricting market access for non-compliant operators. Stakeholders must monitor regulatory alignment between domestic standards and export-market requirements as Egyptian poultry integrators seek Gulf Cooperation Council market entry.
Market Dynamics
Broiler integrators in the Sharqia Governorate cluster are consolidating feed procurement through captive milling operations, compressing margins for independent commercial mills and forcing asset-light restructuring across the Nile Delta supply base.
Growth Catalysts
- FAO Codex-aligned mycotoxin protocols:The Ministry of Agriculture and Land Reclamation's tightened import grain standards are accelerating investment in domestic testing infrastructure and local sorghum substitution programs.
- Tilapia intensification in Lake Nasser:Aquaculture feed demand is expanding as cage farming operations scale protein output for Cairo retail channels and Red Sea export processing.
- Backward integration by poultry integrators:Large-scale operators in Dakahlia and Sharqia are capturing grain storage and milling capacity to secure supply continuity against import volatility.
Market Restraints
- Hard currency access for soy meal imports:Egyptian pound depreciation and foreign exchange rationing are inflating working capital cycles for protein meal-dependent formulations.
- Single-source dependence on Black Sea wheat:Over half of imported feed grain originates from Ukraine and Russia corridors exposed to shipping disruption and quality inconsistency.
- Heat stress degradation of vitamin stability:High Delta humidity and summer temperature spikes accelerate premix potency loss, requiring costly climate-controlled storage infrastructure.
Strategic Opportunities
- Underpenetrated Sinai Peninsula aquaculture:Gulf of Suez brackish water ponds remain undeveloped for marine finfish feed applications as tourism infrastructure redirects capital flows.
- Biogas digestate-to-feed protein:Converging anaerobic digestion and single-cell protein cultivation technologies could displace imported soy meal in ruminant formulations.
- Direct-to-farm premix distribution:Bypassing traditional dealer networks through mobile ordering platforms reaches smallholder poultry operations in Upper Egypt governorates.
Industry Challenges
- Qualified feed formulator scarcity:Technical expertise in amino acid optimization and least-cost ration software remains concentrated among multinational-trained specialists in Cairo and Alexandria.
- ISO 22000 certification timelines:Small and mid-scale mills face 12-18 month compliance gaps blocking access to integrator-approved supplier lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Compound Feed Market |
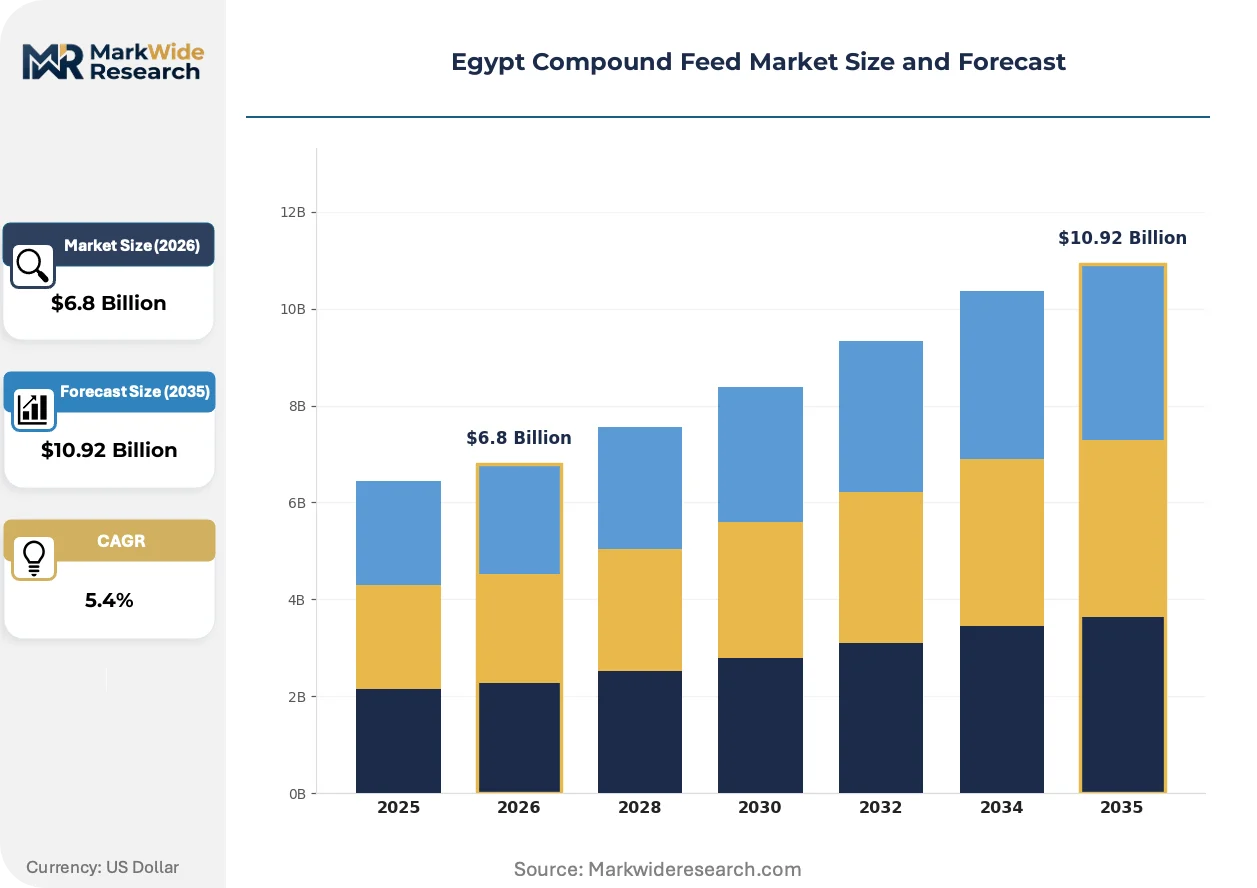
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Aquaculture Feed, Swine Feed End Use: Agriculture, Livestock Farming, Aquaculture, Pet Food Ingredient Type: Cereal Grains, Protein Meals, Vitamins, Additives Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Wadi Holdings SAE, J.D. Heiskell & Co, Cargill, Alltech, Land O'Lakes Purina, Archer Daniels Midland, Dakahlia Poultry Company, De Heus Animal Nutrition, Nutreco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Compound Feed Market Shifts & Advancements
Digital feed formulation platforms and precision premix dosing systems are compressing the technical gap between multinational suppliers and domestic mill operators across Egypt's poultry belt.
Near-infrared spectroscopy is automating real-time ingredient quality verification at receiving bays. Large integrators in the Delta region are deploying handheld NIR units to reject substandard grain shipments before unloading. This technology is automating procurement decision-making that previously relied on visual inspection and external lab turnaround.
The Ministry of Agriculture and Land Reclamation is harmonizing domestic feed safety standards with Gulf Cooperation Council import requirements. This regulatory convergence enables Egyptian poultry integrators to access Saudi and UAE retail channels. Exporters in the 10th of Ramadan industrial zone are restructuring formulation protocols to meet dual-certification thresholds.
Smallholder broiler operations are consolidating feed purchasing through cooperative buying groups. These aggregators negotiate volume discounts previously reserved for integrator-scale buyers. The Beheira and Kafr El Sheikh governorates show the densest cooperative network formation, displacing traditional village-level dealer intermediaries.
Egypt Compound Feed Market Segmentation
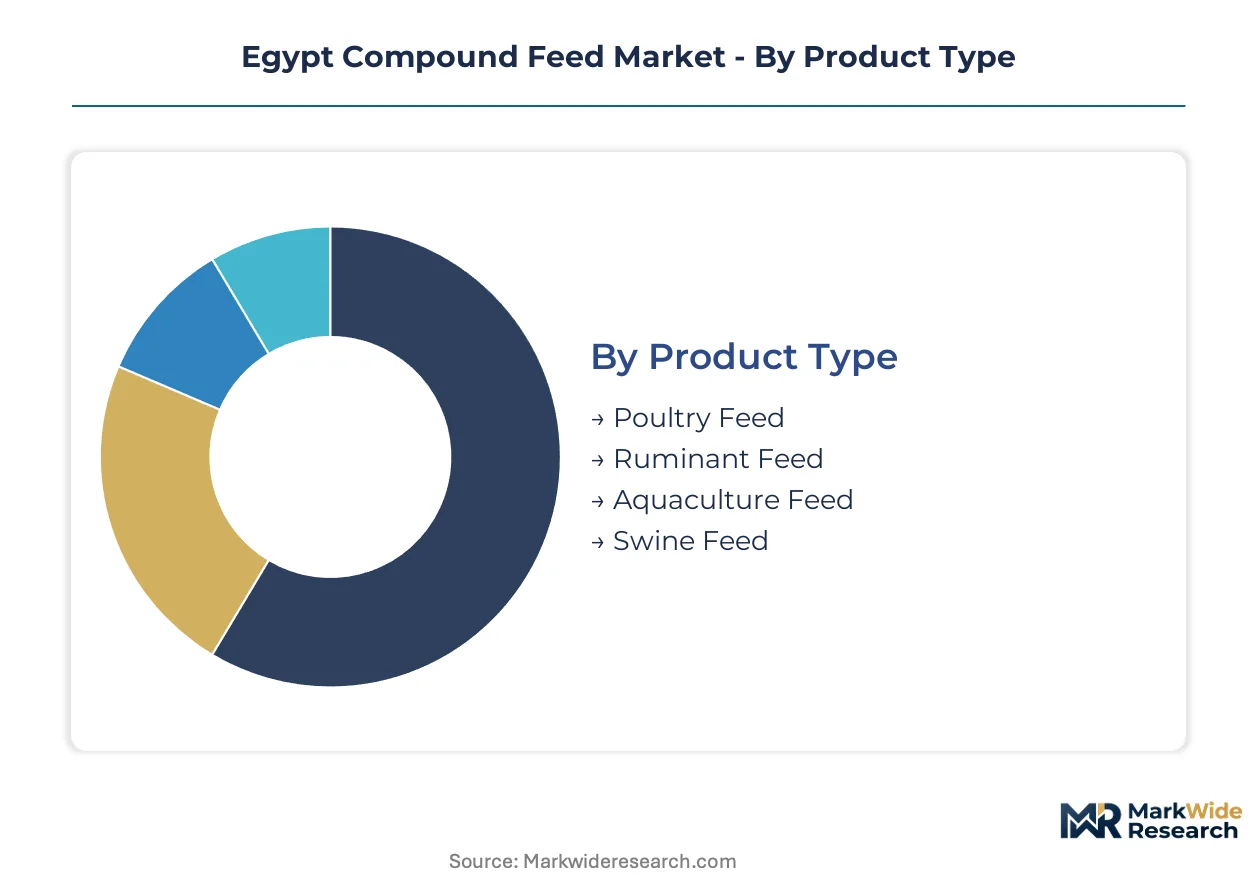
Compound feed segmentation in Egypt reflects divergent supply chain configurations across livestock systems. Poultry integrators, ruminant dairy operations, and emerging aquaculture cages each demand distinct formulation protocols and procurement rhythms.
Product Type:
Integration depth varies sharply: poultry feed operates through captive milling embedded within integrator operations, while aquaculture and ruminant feeds circulate through standalone commercial channels.
- Poultry Feed:Formulated from ground corn, soy meal, and amino acid premixes to deliver precise metabolizable energy for broiler weight gain targets. Demand concentrates in the Sharqia Governorate cluster where Dakahlia Poultry Company and comparable integrators scale commercial layer and broiler operations, driving procurement consolidation through backward integration into grain storage.
- Aquaculture Feed:Floating and sinking extruded pellets engineered for tilapia protein conversion ratios in cage and pond systems. Nile Delta pond operations and Lake Nasser cage farms anchor demand, with feed quality determining harvest timelines for Cairo retail distribution and Red Sea export processing.
- Ruminant Feed:Complete diets and concentrates supporting high-yielding Holstein dairy herds in commercial operations.
- Swine Feed:Niche formulations serving limited commercial pork production, constrained by religious dietary patterns and correspondingly small addressable base.
Volume placements concentrate in Poultry Feed; the faster expansion belongs to Aquaculture Feed.
End Use:
Cost tier stratification separates capital-intensive commercial operations from smallholder systems with distinct purchasing power and technical service requirements.
- Livestock Farming:Commercial dairy and beef operations purchasing bulk formulated feeds through mill-direct contracts, with payment terms reflecting working capital cycles tied to milk offtake schedules.
- Aquaculture:Cage and pond operators procuring species-specific extruded feeds, where feed conversion efficiency directly determines margin sustainability against fluctuating farm-gate prices.
- Agriculture:Diversified holdings combining crop and livestock operations with on-farm mixing capabilities and variable commercial feed dependence.
- Pet Food:Specialty formulations for companion animal retail channels, representing premium pricing tiers with distinct distribution infrastructure.
Margin pools concentrate in Aquaculture; the steepest expansion trajectory runs through Livestock Farming as dairy intensification accelerates.
Ingredient Type:
Supply concentration shapes procurement risk profiles, with protein meals exhibiting the tightest sourcing constraints and highest price volatility.
- Protein Meals:Soybean meal dominates amino acid supply, with Egyptian pound depreciation and foreign exchange rationing inflating working capital cycles for import-dependent formulations. Cargill leverages Red Sea logistics infrastructure to supply commercial dairy operations, while domestic sorghum substitution programs accelerate under tightened mycotoxin protocols.
- Cereal Grains:Corn and wheat comprise metabolizable energy foundations, with over half of imported feed grain originating from Ukraine and Russia corridors exposed to shipping disruption.
- Additives:Mycotoxin binders, enzymes, and acidifiers differentiating feed safety profiles under humidity-stressed Egyptian conditions.
- Vitamins:Premix components requiring climate-controlled storage infrastructure to counteract heat stress degradation of potency.
Procurement risk concentrates in Protein Meals; the fastest share gain belongs to Additives as safety protocols tighten.
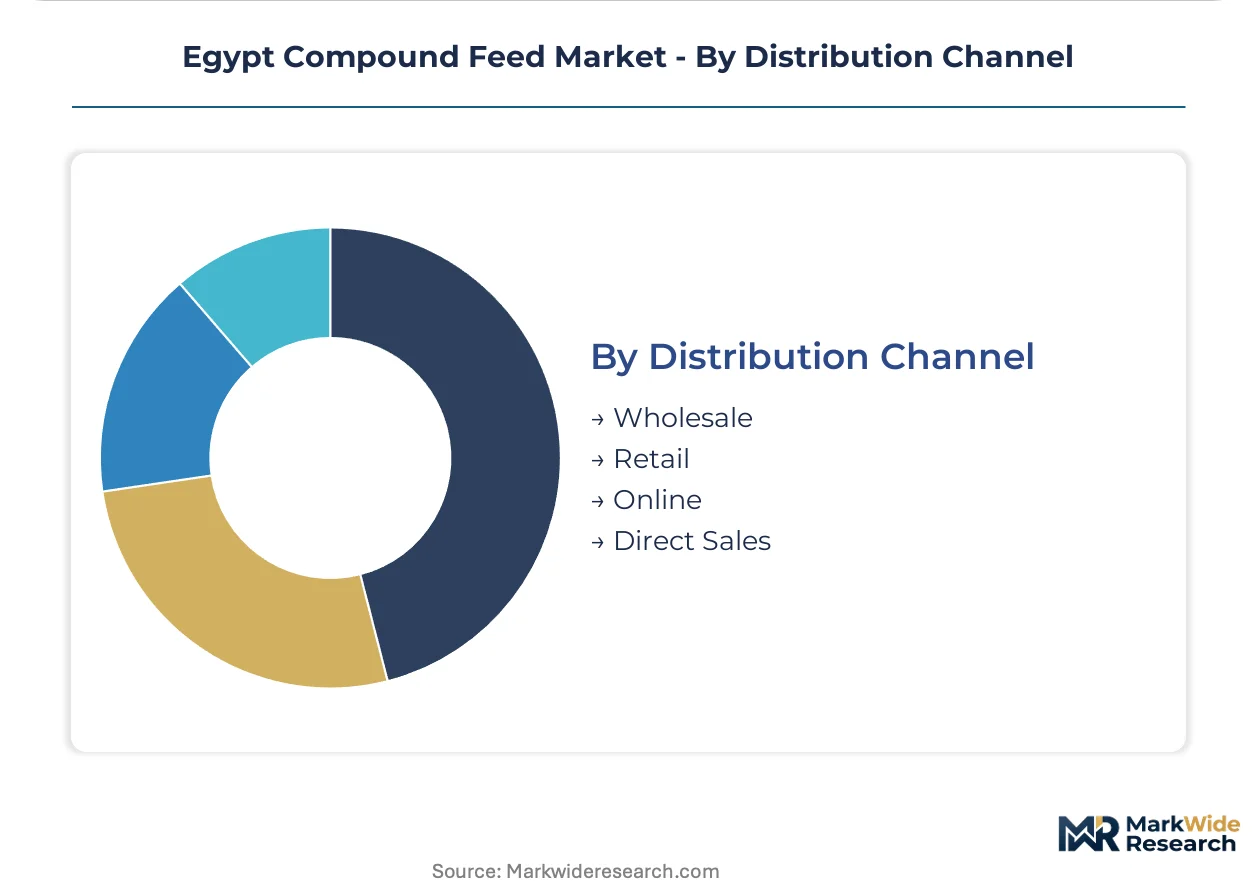
Distribution Channel:
Customer scale determines channel selection, with large integrators bypassing traditional intermediaries while smallholders aggregate through cooperative structures.
- Direct Sales:Mill-to-integrator contracts capturing volume commitments from Sharqia and Dakahlia poultry operations, with formulation customization and technical service bundled into pricing.
- Wholesale:Regional distributors serving mid-scale commercial farms across the Delta with standardized product portfolios and credit terms.
- Retail:Dealer networks reaching smallholder operations, increasingly displaced by cooperative buying groups in Beheira and Kafr El Sheikh governorates.
- Online:Emerging mobile ordering platforms targeting Upper Egypt smallholders with direct-to-farm premix distribution, bypassing traditional village-level intermediaries.
Transaction volume concentrates in Direct Sales; the most rapid channel expansion belongs to Online as digital platforms penetrate smallholder aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sharqia Governorate anchors Egypt's compound feed demand through its dense concentration of broiler integrators and commercial layer operations. The Nile Delta corridor generates the majority of national feed consumption as poultry clusters scale production for Cairo retail channels and Gulf export markets.
Nile Delta
Broiler farming operations in Sharqia and Dakahlia governorates drive protein meal procurement at scale. The Ministry of Agriculture and Land Reclamation enforces FAO Codex-aligned mycotoxin protocols that reshape grain import patterns. Dakahlia Poultry Company operates captive milling and grain storage infrastructure across the northern Delta, compressing margins for independent commercial mills.
Western Desert
Commercial dairy operations in Beheira and Gharbia governorates source soy-based protein meals through Red Sea logistics corridors. Cargill leverages Port Said and Suez Canal infrastructure to supply formulated feeds for high-yielding Holstein herds. Heat stress degradation of vitamin stability forces investment in climate-controlled storage across this humidity-exposed zone.
Upper Egypt
Smallholder poultry operations in Assiut and Sohag governorates aggregate feed purchasing through emerging cooperative buying groups. Mobile ordering platforms bypass traditional village-level dealer intermediaries to reach dispersed producers. Direct-to-farm premix distribution channels expand as digital penetration reaches agricultural communities.
Sinai Peninsula
Brackish water aquaculture potential in the Gulf of Suez remains underdeveloped for marine finfish feed applications. Tourism infrastructure redirects capital flows away from feed value chain investment. The zone represents latent demand should cage farming operations establish protein output for Red Sea export processing.
Lake Nasser
Tilapia intensification in Aswan Governorate drives floating and sinking extruded pellet demand for cage farming operations. Feed conversion efficiency determines harvest timelines for Cairo retail distribution. Aquaculture feed emerges as the fastest-growing category as protein output scales for domestic consumption and regional export.
Egypt Compound Feed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation technology and captive supply chain control. The market structures around three distinct tiers: multinational suppliers with integrated logistics infrastructure, domestic integrators with backward integration into grain storage and milling, and regional commercial mills serving fragmented smallholder demand. Strategic archetypes include Red Sea corridor logistics specialists, Delta-based poultry integrators with captive milling capacity, and premix technology providers differentiating on mycotoxin-binding formulations. Competitive moves concentrate on backward integration into grain procurement and ISO 22000 certification acceleration to access integrator-approved supplier lists.
Among multinational suppliers, Cargill and Alltech occupy positions at opposite ends of the value chain. Cargill exemplifies the logistics-anchored archetype through Red Sea infrastructure leverage. Alltech represents the additive-technology specialist tier competing on mycotoxin-binding differentiation. Dakahlia Poultry Company anchors the domestic integrator segment with backward integration into grain storage and milling across the northern Delta. These three patterns illustrate how competitive positioning splits between supply security control and formulation technology premium capture.
| Leading Market Players |
|---|
| Wadi Holdings SAE |
| J.D. Heiskell & Co |
| Cargill |
| Alltech |
| Land O'Lakes Purina |
| Archer Daniels Midland |
| Dakahlia Poultry Company |
| De Heus Animal Nutrition |
| Nutreco |
| Others |
Supply & Pricing Matrix
Broiler integrator consolidation in Sharqia Governorate is compressing procurement leverage for independent mills, forcing supply restructuring toward captive grain storage and volume-contract pricing tiers. Egyptian pound depreciation against soy meal import costs is accelerating margin bifurcation between backward-integrated operators and asset-light commercial formulators.
Pricing Analysis
Feed conversion efficiency anchors value-based pricing, with formulations priced against broiler weight gain outcomes and dairy milk yield coefficients. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified integrator supply from uncertified commercial mill output and cooperative-aggregated smallholder purchases. Pricing pressure stems from foreign exchange rationing inflating protein meal working capital cycles. Smallholder cooperatives in Upper Egypt exhibit highest price sensitivity; large integrators with captive milling show lowest sensitivity due to supply security premiums.
Supply Chain Analysis
Spent grain and milling byproduct flows from Dakahlia Poultry Company operations feed ruminant concentrate blending, creating circular protein recovery loops. Raw material sourcing concentrates on Ukraine, Russia, and Argentina for wheat and corn, with Brazilian and US soybean meal filling amino acid gaps. Single-source vulnerability runs through Black Sea shipping corridors exposed to disruption. Distribution runs through mill-direct contracts for integrators, wholesale distributors for mid-scale farms, and cooperative aggregators for smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's compound feed sector is consolidating around procurement scale and certification barriers, with currency volatility and mycotoxin protocol tightening forcing sub-scale mills toward exit or acquisition.
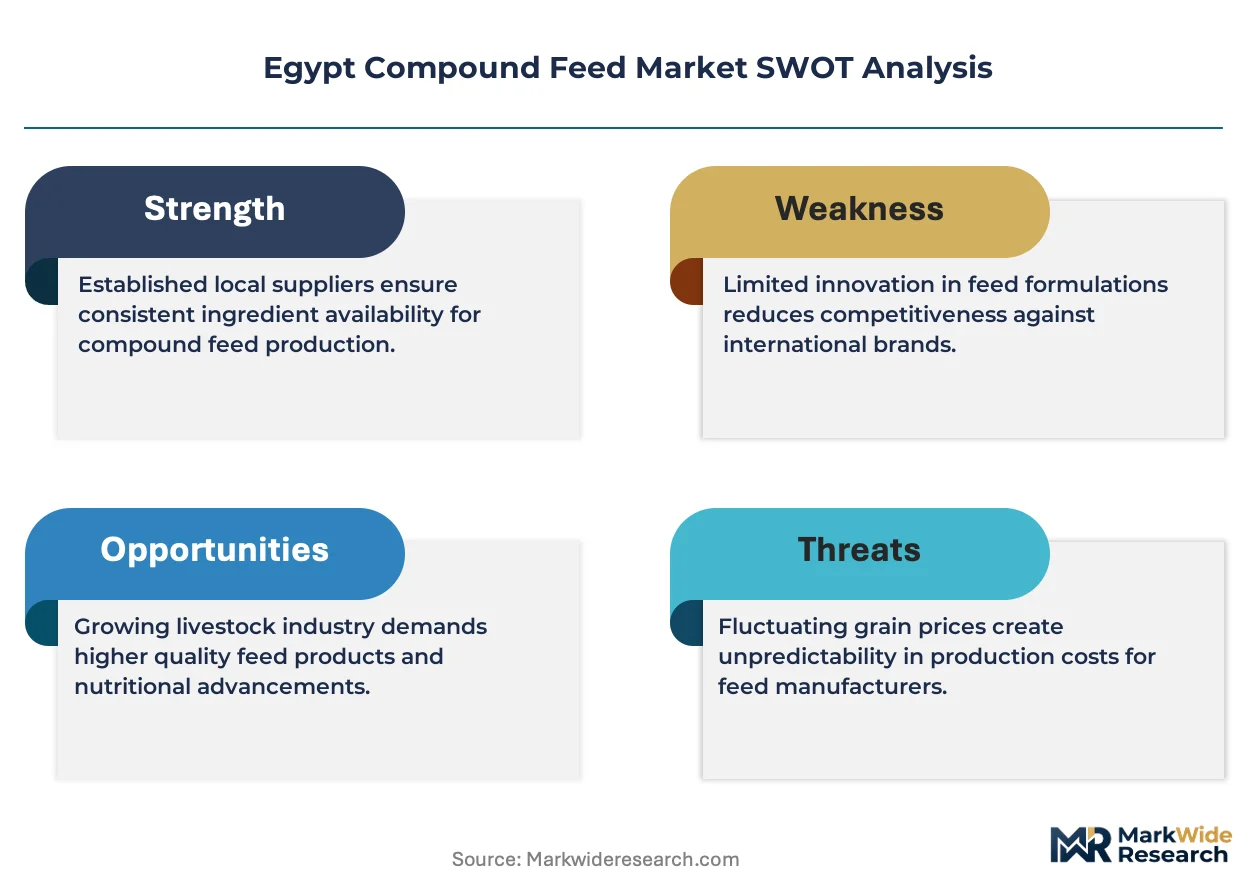
For Market Incumbents: Lock in grain storage capacity across the northern Delta before import volatility escalates working capital requirements for competitors. Accelerate ISO 22000 certification timelines to capture integrator-approved supplier status as Dakahlia Poultry Company and comparable operators tighten procurement lists. Defend formulation margins by embedding mycotoxin-binding technology into premium premix tiers, differentiating against commodity competitors. For New Entrants and Emerging Players: The mid-tier price gap between Cargill-supplied premium dairy formulations and uncertified commercial mill output offers entry space for mobile-enabled premix distribution. Target Upper Egypt smallholder poultry operations through direct-to-farm digital platforms, bypassing cooperative intermediaries in Beheira and Kafr El Sheikh. Lead with least-cost ration software bundled into premix sales, closing the technical capability gap against multinational-trained formulators. For Investors and Strategic Acquirers: The window for entry favors regional commercial mills with 12-18 month ISO 22000 compliance trajectories and existing integrator relationships. Acquisition targets should show captive grain storage or Red Sea logistics access as defensive moats. Monitor Egyptian pound stability against soy meal import costs as the primary inflection signal for margin pool redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Storage | Dakahlia Poultry Company's captive milling model secures supply continuity against Black Sea disruption. |
| ISO 22000 Certification Acceleration | Compliance gaps block access to integrator-approved supplier lists in Sharqia Governorate clusters. |
| Mobile Platform Distribution | Direct-to-farm premix channels bypass traditional dealer networks in Upper Egypt governorates. |
| Mycotoxin-Binding Technology Investment | Alltech's additive differentiation captures premium pricing under humidity-stressed Egyptian conditions. |
| Red Sea Logistics Infrastructure Leverage | Cargill's Port Said and Suez Canal access enables soy meal supply to commercial dairy operations. |
Research Methodology
Trade databases, customs records, and Ministry of Agriculture regulatory filings formed the secondary backbone of this analysis. Primary interviews with feed mill operations managers, poultry integrator procurement leads, veterinary services inspectors, and grain trading desk executives were cross-validated against import shipment data and FAO Codex alignment documentation. Bottom-up volume estimates from governorates were triangulated against top-down national consumption benchmarks.
Historical trendline analysis of broiler feed conversion ratios, dairy milk yields, and aquaculture harvest timelines informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, end-use application, ingredient composition, and distribution channel dimensions with regional governorates as a geographic overlay. CAGRs were derived from fitted growth curves applied to volume and value baselines, with tilapia intensification rates and integrator consolidation pace as key forward inputs.
Inputs from customs and regulatory sources were available through the study window; gaps in smallholder cooperative transaction data introduce uncertainty bands around Upper Egypt volume estimates. Forecasts reflect assumptions about currency stability and Black Sea shipping continuity. Practitioners should monitor Egyptian pound depreciation trends and FAO Codex enforcement intensity for early signals of procurement pattern shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Organic Feed Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Malaysia Floriculture Market