
 Grain and Cereal Crop Protection Market | 2026-2036
Grain and Cereal Crop Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Grain and Cereal Crop Protection Market Foresight
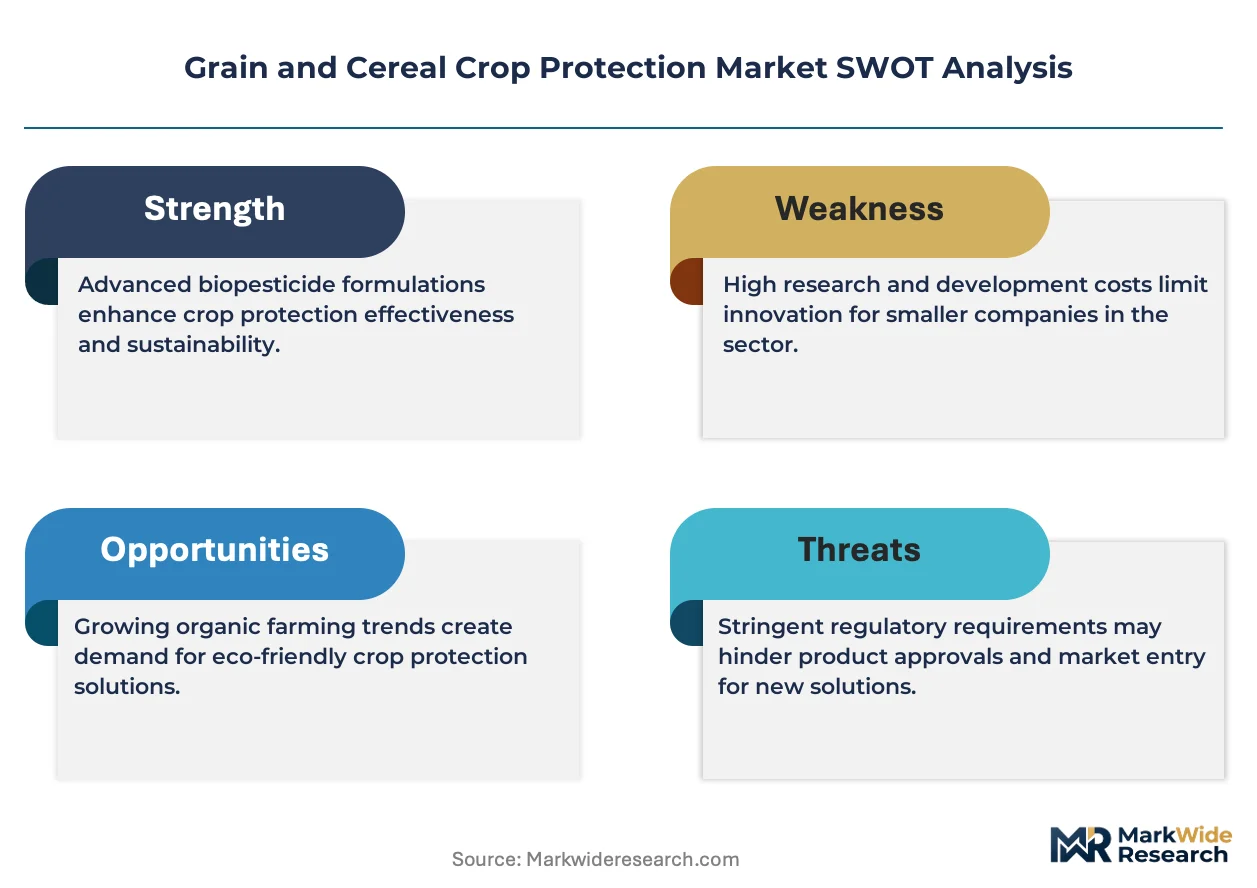
Capital-intensity divergence between precision-formulation laboratories and generic manufacturing networks is redrawing competitive boundaries in crop protection. BASF Agricultural Solutions leverages its proprietary seed-treatment integration to sustain premium positioning in corn protection systems. UPL Ltd. anchors its cost structure through backward integration into active-ingredient synthesis, while Corteva Agriscience competes through proprietary trait-stacking technologies that bundle herbicide tolerance with insect resistance.
Grain and cereal crop protection encompasses chemical, biological, and integrated pest management agents formulated to suppress weeds, insects, and fungal pathogens across wheat, corn, barley, and rice cultivation systems. Active ingredients typically combine synthetic molecules such as pyrethroids, triazoles, and glyphosate derivatives with adjuvants that enhance leaf-surface adhesion and rainfastness, serving the primary purpose of preserving yield potential and grain quality from planting through harvest. Herbicides command the largest revenue share within pest control methods due to widespread glyphosate-resistant weed pressure, while biopesticides represent the fastest-expanding category as residue-conscious food processors tighten procurement specifications. Spraying technology dominates application methods, though drip-irrigation chemigation is gaining traction in arid-zone corn production where water scarcity constrains conventional ground-rig access.
The EPA regulates pesticide registration and tolerance thresholds in the United States, while the EU Green Deal and Farm-to-Fork Strategy mandate pesticide reduction targets that reshape product portfolios across European markets. REACH compliance and emerging PFAS restrictions in the European Union compound formulation complexity, forcing reformulation investments that favor players with dedicated regulatory-affairs infrastructure. Stakeholders must monitor biological-pesticide registration pathways and resistance-management mandates as these frameworks determine which chemistries retain market access and which face phased withdrawal.
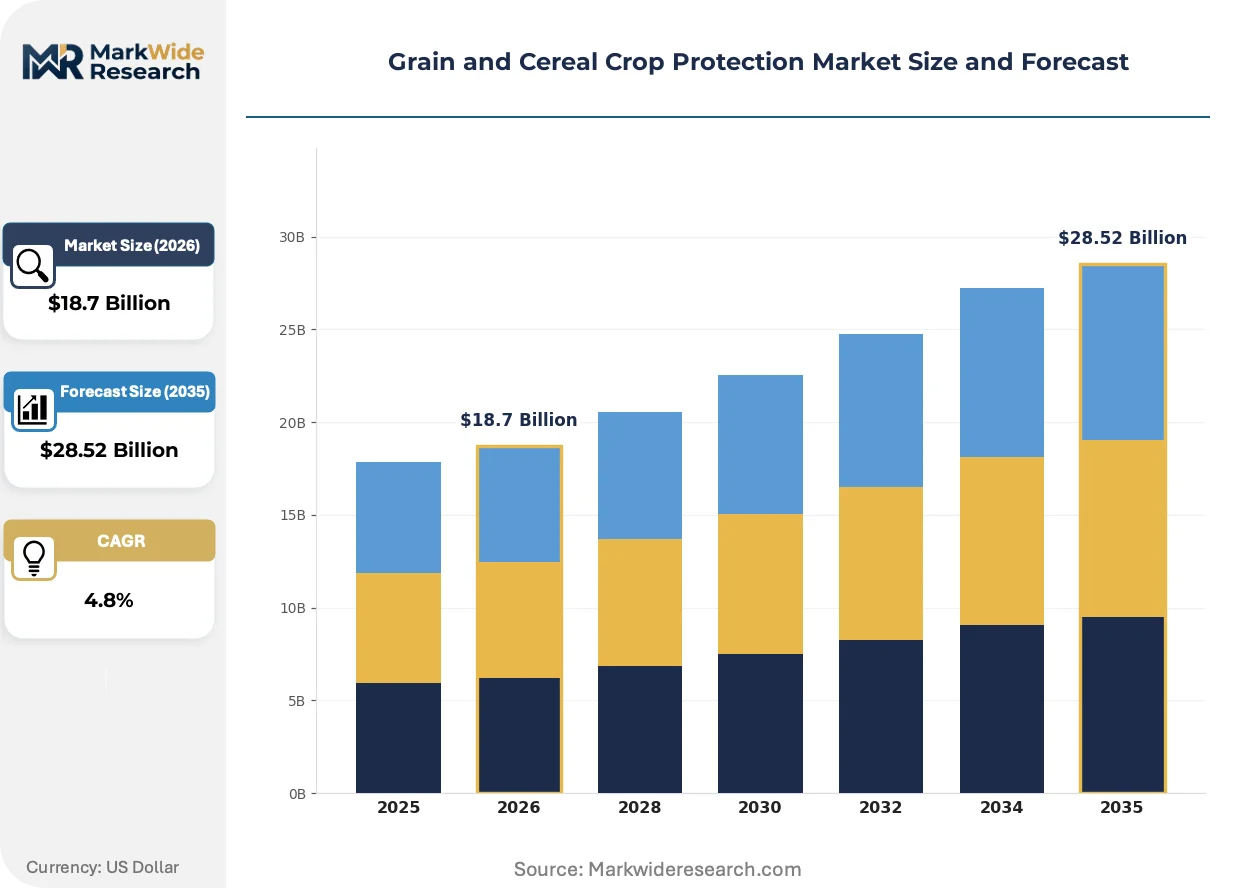
Market Dynamics
Neonicotinoid phase-outs across multiple jurisdictions are compressing legacy chemistry margins while accelerating biological formulation R&D pipelines and reshaping supplier competitive hierarchies.
Growth Catalysts
- EU Farm-to-Fork pesticide reduction mandates:Binding targets for chemical load reduction are redirecting procurement budgets toward biopesticide portfolios and integrated pest management service bundles.
- Drone-based variable-rate application systems:Precision spraying hardware is expanding addressable acreage in Brazil's Cerrado belt where terrain limits ground-rig access.
- Residue-conscious food processors:Major grain buyers are tightening maximum residue limits in procurement contracts, pulling through demand for biological alternatives with favorable toxicology profiles.
Market Restraints
- Active ingredient supply concentration:China dominates intermediate synthesis for pyrethroids and triazoles, exposing formulators to export license volatility and freight cost spikes.
- REACH compliance cost escalation:European Union substance registration and emerging PFAS restrictions are forcing multimillion-euro reformulation investments that favor capital-heavy incumbents.
- Biological shelf-life limitations:Live microbial formulations require cold chain infrastructure absent in many emerging market distribution networks, constraining addressable geography.
Strategic Opportunities
- Seed-treatment biological integration:Microbial inoculant compatibility with precision planter equipment opens premium positioning in North American corn systems where farmers bundle protection with genetics.
- India's rice belt biological penetration:Low current biopesticide adoption rates in eastern rice-growing states create first-mover terrain for locally manufactured fermentation-derived products.
- Carbon credit monetization frameworks:Emerging soil carbon protocols in Australia and Canada enable crop protection suppliers to bundle emissions reduction verification with biological product sales.
Industry Challenges
- Resistance management protocol complexity:Rotational chemistry requirements across multiple pest species strain technical advisory capacity at distributor level.
- Biological registration data requirements:Efficacy validation timelines for microbial products lag synthetic benchmarks, delaying revenue realization despite pipeline investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain and Cereal Crop Protection Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pest Control Method: Insecticides, Herbicides, Fungicides, Biopesticides Crop Type: Wheat, Corn, Barley, Rice Application Technology: Spraying, Drip Irrigation, Granular, Drenching Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | FMC Corporation, ADAMA, Syngenta Crop Protection, Sumitomo Chemical, Nufarm, BASF Agricultural Solutions, UPL Ltd., Corteva Agriscience, Bayer CropScience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain and Cereal Crop Protection Market Shifts & Advancements
Digital agronomy platforms are compressing the information gap between formulation suppliers and field-level application decisions, rewiring how protection products are specified and performance-validated.
RNA interference crop protection is fragmenting the herbicide tolerance trait landscape. Bayer and Syngenta are advancing sprayable dsRNA formulations targeting specific weed species. Large-scale corn and soybean growers in the US Midwest are piloting these precision biocontrol tools. The technology is fragmenting traditional herbicide market structure by enabling trait-agnostic weed suppression without transgenic crop modification.
EPA's evolving Endangered Species Act consultation requirements for pesticide registration are extending approval timelines for new synthetic chemistries. The agency's 2024 biological evaluation mandates for threatened species habitats are forcing earlier-stage ecological risk assessment integration. Corn and cotton herbicide registrants are responding by front-loading pollinator and aquatic toxicity data packages to preempt registration delays.
Grain elevator procurement specifications are tightening residue maximum limits ahead of regulatory thresholds. Major US food processors and export-oriented Brazilian cooperatives are implementing third-party certified low-residue programs. This specification escalation is most visible in wheat destined for EU and Japanese import markets where tolerances for glyphosate and neonicotinoid metabolites sit below domestic US standards.
Grain and Cereal Crop Protection Market Segmentation
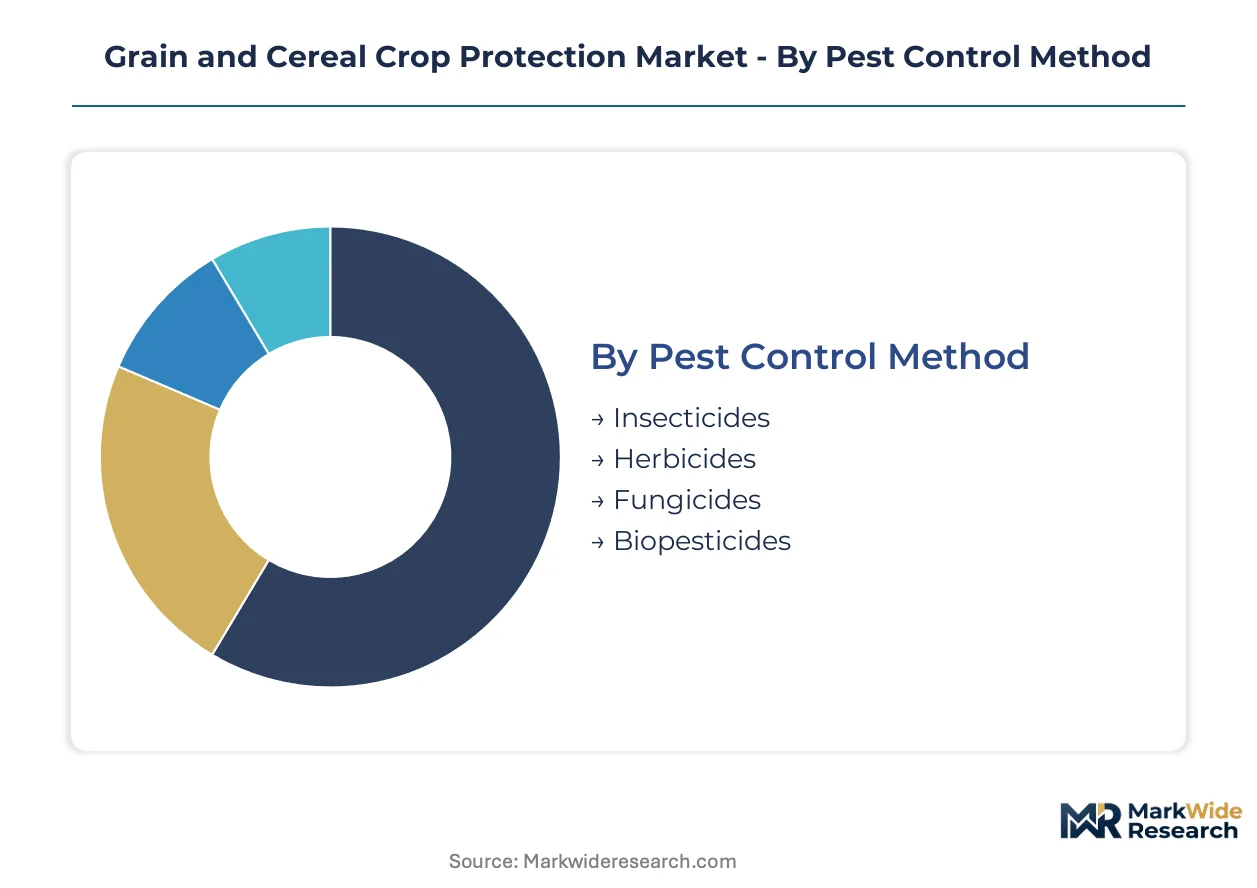
Segmentation in grain and cereal crop protection reveals where formulation R&D investments concentrate and how application constraints reshape channel economics. Distinct margin pools emerge across pest control chemistry tiers, crop-specific resistance profiles, and precision application hardware compatibility.
Pest Control Method:
Margin concentration follows resistance pressure intensity and regulatory withdrawal timelines, with biological alternatives capturing expanding premium positioning.
- Herbicides:Formulations based on glyphosate derivatives, triazines, and auxin mimics dominate planted acreage coverage. Glyphosate-resistant weed pressure across the US Corn Belt and Brazilian Cerrado sustains demand for novel mode-of-action discovery despite mounting regulatory scrutiny.
- Insecticides:Pyrethroid, neonicotinoid, and diamide chemistries target lepidopteran and coleopteran pests in corn and wheat systems. EPA's evolving neonicotinoid restrictions are compressing legacy product margins while accelerating pyrethroid-diamide rotation protocols.
- Fungicides:Triazole, strobilurin, and SDHI formulations suppress Fusarium and rust pathogens in humid wheat and barley regions. Resistance management mandates in the EU and Australia drive multi-site fungicide premix adoption.
- Biopesticides:Microbial and biochemical formulations derived from Bacillus thuringiensis, Trichoderma, and plant extracts serve residue-conscious procurement channels. EU Farm-to-Fork reduction targets and Japanese maximum residue limits are pulling through double-digit demand expansion in export-oriented grain systems.
The dominant share belongs to herbicides, while biopesticides are closing the gap fastest.
Crop Type:
Volume distribution tracks planted hectare totals and per-acre protection intensity, with corn commanding the highest chemical input expenditure per hectare.
- Corn:Intensive insecticide and herbicide deployment accompanies trait-stacked seed systems across North American and Brazilian production belts. Rootworm and fall armyworm pressure sustain soil-applied and foliar insecticide rotations alongside glyphosate-tolerant weed management platforms.
- Wheat:Fungicide-heavy protection profiles target stripe rust and Fusarium head blight in high-rainfall European and Australian growing regions. Integrated pest management adoption is expanding across the US Great Plains as growers rotate chemistries to preserve azole efficacy.
- Rice:Aquatic application constraints favor granular and drift-reduced formulations in flooded paddy systems across India, China, and Southeast Asia. Stem borer and sheath blight complexes drive insecticide-fungicide bundling in mechanized transplanting zones.
- Barley:Lower protection intensity per hectare reflects smaller planted area and reduced disease pressure relative to wheat in European and Australian malting barley zones. Fusarium and net blotch management prioritizes triazole prothioconazole in premium malting quality segments.
Corn anchors absolute revenue contribution, with wheat gaining share through fungicide premiumization in quality-focused export corridors.
Application Technology:
Equipment capital requirements and terrain accessibility determine technology penetration rates, with precision application systems capturing margin expansion in large-scale farming zones.
- Spraying:Ground-rig and aerial application of liquid formulations dominates arable crop protection across flat terrain regions. Drone-based variable-rate systems are penetrating Brazil's Cerrado belt where topography limits conventional equipment access.
- Granular:Soil-applied insecticide and fertilizer-pesticide blends target corn rootworm and early-season weed suppression at planting. Precision planter compatibility sustains demand in North American no-till systems where seed-furrow placement optimizes root zone protection.
- Drip Irrigation:Chemigation of systemic insecticides and fungicides through subsurface drip lines serves arid-zone corn and wheat production in Israel, Spain, and California's Central Valley. Water scarcity constraints and labor cost escalation accelerate adoption where infrastructure exists.
- Drenching:High-volume liquid application to soil or plant base targets nematode and soil-borne pathogen complexes in rice seedling nurseries. Manual and mechanized drenching persists in smallholder Asian rice systems where transplanting labor remains available.
Spraying retains volume dominance, though drip irrigation is climbing fastest in water-stressed premium vegetable-corn rotation zones.
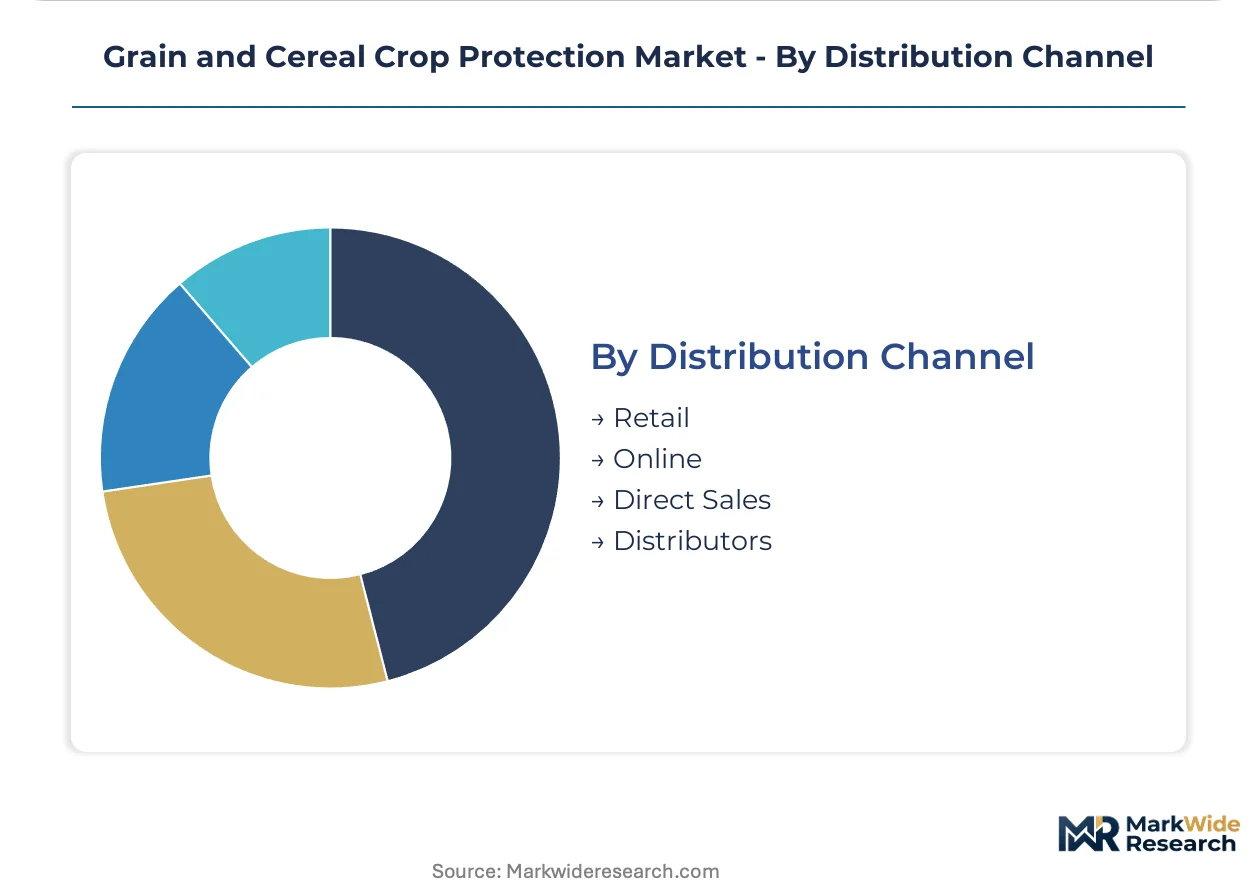
Distribution Channel:
Channel economics reflect technical advisory intensity, with bundled agronomy services sustaining distributor margins against price-transparent online alternatives.
- Distributors:Independent and cooperative distribution networks dominate input procurement for commercial grain operations across the US Midwest, Brazil, and Australia. Resistance management planning, application timing advice, and credit terms lock in grower loyalty at scale.
- Direct Sales:Manufacturer-direct relationships serve large integrated farming enterprises and grain elevator cooperatives with volume-based pricing and custom formulation services. Bayer, Syngenta, and Corteva field sales organizations target 5,000+ hectare operations in Argentina and Ukraine.
- Retail:Farm supply stores and garden center channels capture hobby farm and smallholder demand in peri-urban and transition zone geographies. Shelf-space constraints favor established brand recognition over novel biological entrants in this fragmented segment.
- Online:E-commerce platforms aggregate generic and branded chemistries for price-sensitive growers with independent agronomic advisory capacity. Indian and Chinese agricultural input marketplaces are expanding SKU breadth, though cold-chain biological products remain underrepresented.
Distributors command the largest revenue share, while direct sales are gaining ground fastest through enterprise farming consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazilian and North American grain belts where trait-stacked seed systems bundle premium chemistries, while Asian rice-growing regions compete on generic formulation cost curves.
United States
Corn Belt growers drive demand for rootworm-resistant trait packages and glyphosate-tolerant weed management platforms. EPA's evolving neonicotinoid restrictions and Endangered Species Act consultation requirements are extending registration timelines for new synthetic chemistries. Iowa and Illinois field operations anchor precision application adoption where drone-based variable-rate systems penetrate large-scale farming enterprises.
Brazil
Cerrado expansion sustains herbicide and insecticide intensity as farmers convert native savanna to mechanized soybean-corn rotations. ANVISA's residue monitoring protocols align with EU import specifications, pulling through demand for low-toxicity formulations. Mato Grosso and Goiás distribution networks dominate volume flows where terrain constraints accelerate aerial and drone-based application hardware deployment.
China
Domestic rice and wheat protection concentrates on granular formulations and drift-reduced spraying in flooded paddy systems. MEE enforcement of dual carbon goals is tightening manufacturing emissions standards for active ingredient synthesis. Jiangsu and Shandong chemical clusters supply pyrethroid and triazole intermediates while facing export license volatility under environmental compliance audits.
Germany
Malting barley and wheat production in Bavaria and Lower Saxony prioritizes triazole-based Fusarium management for premium export quality segments. REACH compliance and emerging PFAS restrictions under ECHA oversight are forcing multimillion-euro reformulation investments. Rhineland-Palatinate formulation laboratories serve as regulatory-affairs hubs navigating EU Farm-to-Fork pesticide reduction mandates.
India
Eastern rice-growing states present first-mover terrain for locally manufactured biopesticides with low current adoption rates. BIS standards and FSSAI residue limits are tightening procurement specifications for export-oriented basmati corridors. Punjab and Haryana wheat belts sustain generic herbicide demand where smallholder consolidation is gradually shifting channel economics toward distributor-led bundled services.
Grain and Cereal Crop Protection Market Competitive Landscape
Concentration sits with integrated agricultural science conglomerates that combine proprietary seed genetics, formulation R&D, and direct field sales organizations. Three archetypes dominate: trait-stacking technology providers, backward-integrated active ingredient manufacturers, and precision-formulation laboratories serving residue-conscious procurement channels. Competitive moves center on biological alternative pipeline acceleration and seed-treatment integration partnerships that lock in multi-year grower commitments.
Among the integrated science conglomerates, BASF Agricultural Solutions, UPL Ltd., and Corteva Agriscience occupy distinct positioning vectors. BASF exemplifies the seed-treatment integration archetype through proprietary corn protection systems. UPL represents cost-structure optimization via backward integration into active-ingredient synthesis. Corteva anchors trait-stacking competitive positioning that bundles herbicide tolerance with insect resistance genetics. These three entities collectively illustrate how capital-intensity divergence between precision laboratories and generic manufacturing networks is redrawing competitive boundaries.
| Leading Market Players |
|---|
| FMC Corporation |
| ADAMA |
| Syngenta Crop Protection |
| Sumitomo Chemical |
| Nufarm |
| BASF Agricultural Solutions |
| UPL Ltd. |
| Corteva Agriscience |
| Bayer CropScience |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Brazilian cooperatives and Chinese intermediate manufacturers lock in pyrethroid and triazole supply while capping price volatility for formulators serving the Cerrado expansion belt. These arrangements bundle volume commitments with freight cost absorption, creating procurement visibility that spot-market buyers cannot replicate.
Pricing Analysis
Configured-to-order pricing for microbial inoculant-seed treatment bundles commands 40-60% premiums over standard glyphosate-based herbicide programs. Three-tier pricing structure across premium, standard, and economy levels stratifies by residue certification grade and cold-chain handling requirements. Price differentiation hinges on EU Farm-to-Fork compliance documentation and ANVISA-aligned toxicology profiles. Cost compression in generic pyrethroid segments is intensifying because Indian and Chinese manufacturers are expanding fermentation and synthesis capacity. Smallholder cooperatives in eastern India exhibit highest price sensitivity, while North American corn belt enterprises with elevator-direct contracts show least elasticity.
Supply Chain Analysis
Inventory buffers for live microbial formulations require 2-8 week cold-chain lead times that constrain distributor stocking depth in tropical climates. Active ingredient synthesis concentrates in China, India, and Germany, with Jiangsu and Shandong chemical clusters supplying pyrethroid intermediates. Formulation draws from specialty surfactant feedstocks and precision-coated seed substrates. Single-source vulnerability sits with Chinese export license volatility under MEE environmental audits. Distribution runs through cooperative networks in Brazil and Australia, independent agronomy retailers in the US Midwest, and government-subsidized depots in India's rice belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of regulatory-affairs infrastructure capable of navigating simultaneous EPA, REACH, and ANVISA submission pathways is concentrating competitive advantage among capital-heavy incumbents with dedicated compliance teams.
For Market Incumbents: Consolidate biological formulation pipelines through acquisition of microbial strain libraries and fermentation engineering capabilities to offset neonicotinoid margin compression. Prioritize backward integration into cold-chain distribution networks in Brazil and India where biological shelf-life limitations currently constrain addressable geography. Lock in multi-year seed-treatment partnerships with precision planter equipment manufacturers to defend against generic manufacturers entering the corn protection bundle market. For New Entrants and Emerging Players: Lead with locally manufactured biopesticide fermentation facilities in India's eastern rice-growing states where current adoption rates sit below 5% and import dependency creates cost disadvantages. Target drone-based variable-rate application service bundling in Brazil's Cerrado belt where terrain constraints exclude ground-rig competition. Pursue carbon credit monetization frameworks in Australia and Canada as a differentiated value proposition that synthetic chemistry incumbents cannot easily replicate. For Investors and Strategic Acquirers: Capital is best deployed toward precision-formulation laboratories with established regulatory-affairs infrastructure capable of fast-tracking biological registrations across multiple jurisdictions. Long-term viability favors entities with seed-treatment integration capabilities and proprietary microbial strain IP rather than pure-play generic manufacturers. Monitor EPA biological evaluation timelines for threatened species habitats as an inflection indicator for synthetic chemistry registration delays that would accelerate biological substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Pipeline Acceleration | Fast-tracks microbial registration ahead of EPA neonicotinoid withdrawal deadlines. |
| Seed-Treatment Integration Partnership | Locks multi-year grower commitments through precision planter equipment compatibility. |
| Cold-Chain Distribution Buildout | Extends biopesticide addressable geography into tropical smallholder markets. |
| Regulatory-Affairs Infrastructure Investment | Enables simultaneous REACH, EPA, and ANVISA submission capacity. |
| Carbon Credit Protocol Development | Bundles emissions verification with biological sales in Australia and Canada. |
Research Methodology
Cross-validation between primary interviews with formulation R&D directors, regulatory affairs leads at crop protection manufacturers, distributor agronomists, and grain elevator procurement managers anchors the qualitative findings. Secondary sources include EPA registration databases, EFSA residue monitoring reports, ANVISA toxicology assessments, and customs trade data on pyrethroid intermediate flows. Bottom-up triangulation across pest control method, crop type, and application technology segments reconciles with top-down market sizing.
Sensitivity analysis around EU Farm-to-Fork mandate implementation pace and EPA neonicotinoid withdrawal timelines tests forecast robustness across the analysis window. Segmentation dimensions modeled include pest control chemistry tier, crop-specific resistance profile, precision application hardware compatibility, and regional regulatory cluster. CAGRs derive from acreage expansion projections, per-hectare protection intensity trends, and biological substitution elasticity assumptions. Input variables capture drone penetration rates in Brazil, cold-chain infrastructure buildout in India, and carbon credit adoption curves in Australia.
Underlying assumptions cover stable trade policy for Chinese intermediate exports, with deviation risk concentrated in MEE environmental audit enforcement and EU PFAS restriction scope expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Pest Control Products Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Azoxystrobin Market
Crop Protection
North America Molluscicides Market
Crop Protection
Tebuconazole Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
United States Nematicides Market
Crop Protection
North America Insecticide Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
China Insecticide Market
Crop Protection
Vietnam Crop Protection Chemicals Market