
 Russia Crop Protection Chemicals Market | 2026-2036
Russia Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Crop Protection Chemicals Market Analytics
The agrochemical distributor network is narrowing as sanctions reshape import logistics. Bayer CropScience AG sustains its presence through localized formulation facilities, while Syngenta International AG navigates licensing complexities to maintain seed-treatment portfolios. Schelkovo Agrohim dominates domestic manufacturing of generic herbicides, leveraging backward integration into active ingredient synthesis.
Crop protection chemicals encompass synthetic and biological formulations designed to control weeds, insects, fungal pathogens, and plant growth disorders, typically applied at rates measured in grams of active ingredient per hectare to preserve yield potential across commercial agriculture. Herbicides occupy the largest product type position due to expansive cereal monoculture, while suspension concentrates gain formulation share as growers prioritize water-based delivery systems with lower solvent exposure. Oilseed applications represent the fastest-expanding crop segment as sunflower and soybean plantings displace fallow acreage in the Southern Federal District.
Russia's national agricultural regulator oversees pesticide registration under tightening residue maximum limits, while the Eurasian Economic Commission harmonizes technical standards across member states. The country's import substitution mandates now require domestic production certificates for state-procured crop protection programs. Stakeholders must track regulatory divergence between Russian national standards and EAEU technical regulations to anticipate product re-registration timelines and local content thresholds.
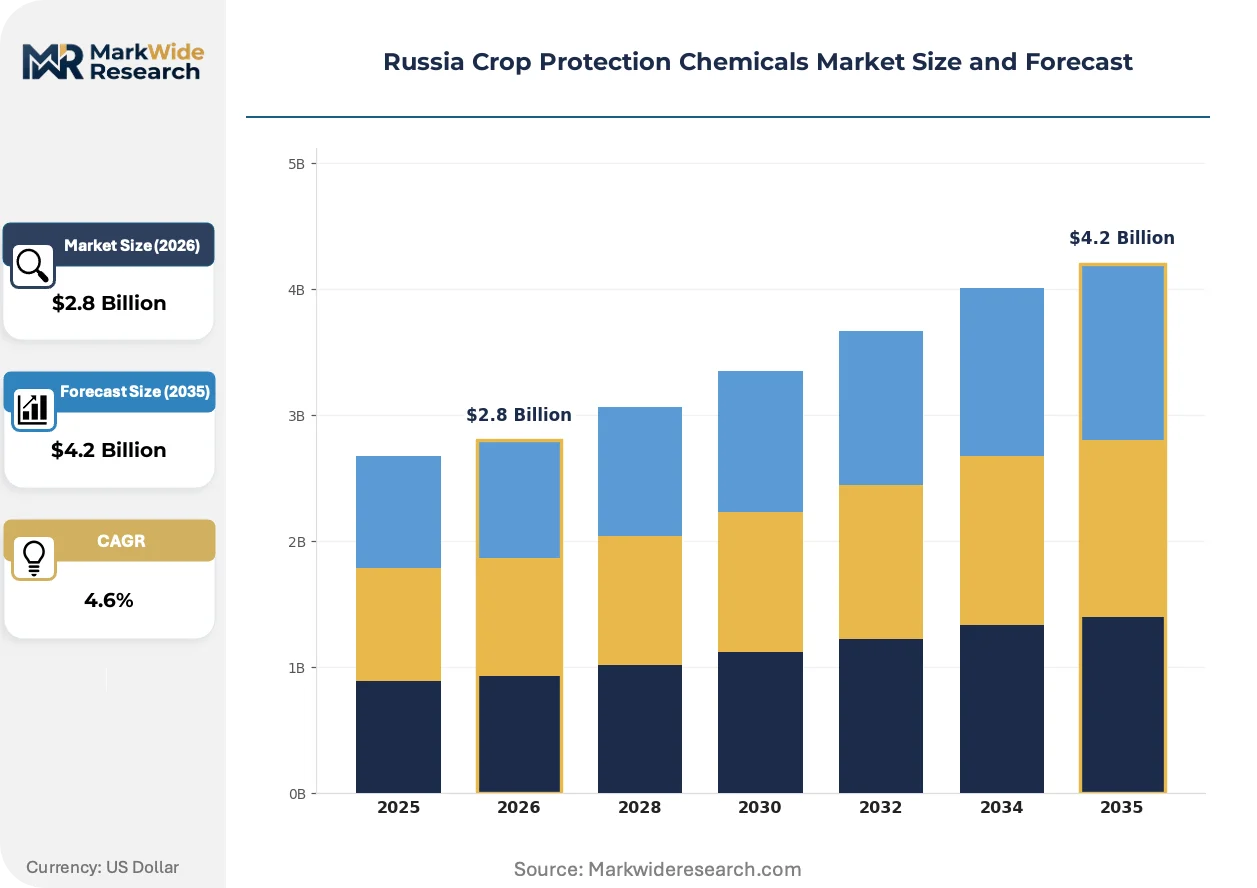
Market Dynamics
Import substitution mandates from Moscow are forcing domestic formulators to rebuild active ingredient supply chains previously anchored to Western technical imports, compressing product development timelines while opening captive demand for localized synthesis capacity.
Growth Catalysts
- Import Substitution Mandates:State procurement rules now require domestic production certificates, redirecting volume toward Voronezh and Krasnodar manufacturing clusters.
- Sunseed Expansion:Sunflower and soybean plantings displace fallow acreage across the Southern Federal District, generating incremental herbicide and fungicide demand.
- Residue Standard Harmonization:EAEU technical regulations are converging pesticide maximum limits across member states, simplifying multi-country registration for compliant formulators.
Market Restraints
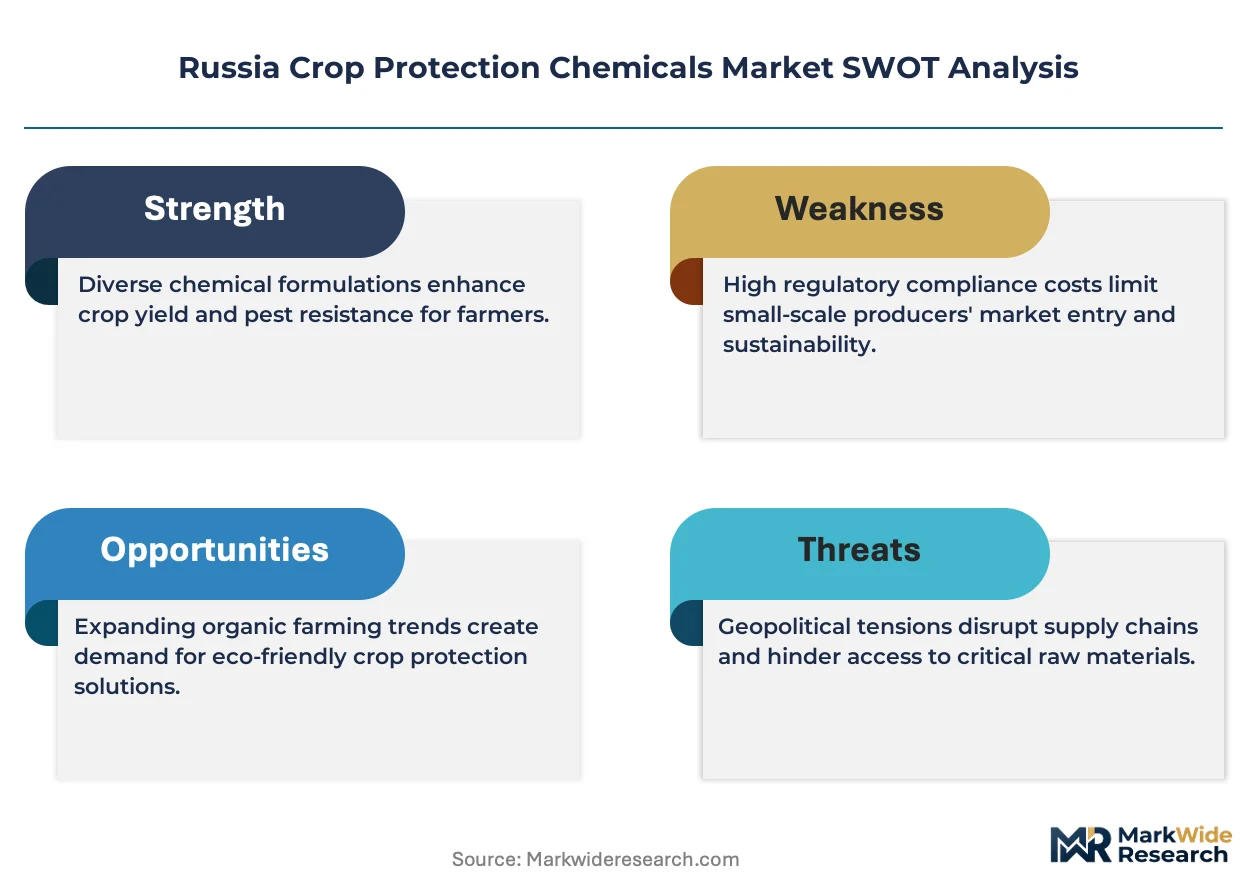
- Technical Import Dependency:Active ingredient synthesis for novel chemistries remains concentrated outside Russia, exposing formulators to logistics friction and payment system disruptions.
- Registration Timeline Compression:Russia's national agricultural regulator is tightening residue maximum limits while accelerating re-registration deadlines, forcing portfolio rationalization.
- Generic Price Erosion:Schelkovo Agrohim and domestic competitors have expanded glyphosate and 2,4-D capacity, collapsing margins on commodity herbicide segments.
Strategic Opportunities
- Biological Formulation Gap:Microbial inoculants and biopesticide segments remain underdeveloped versus synthetic chemistry, offering first-mover positioning for fermentation-based entrants.
- Seed Treatment Bundling:Licensing complexities around trait technologies are pushing distributors toward integrated seed-plus-chemistry packages with captive financing.
- Central Black Earth Consolidation:Large cereal operations in Kursk and Tambov oblasts are professionalizing procurement, creating volume anchor contracts for qualified suppliers.
Industry Challenges
- Formulation Chemist Scarcity:Sanctions have disrupted knowledge transfer from Western technical centers, creating bottlenecks in suspension concentrate and micro-emulsion development.
- Active Ingredient Synthesis Scale-Up:Captive production of technical-grade materials requires capital-intensive multi-purpose reactor installations with extended commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Crop Protection Chemicals Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Growth Regulators Application: Cereals, Fruits, Vegetables, Oilseeds Formulation Type: Granules, Liquids, Emulsifiable Concentrates, Suspension Concentrates Sales Channel: Direct Sales, Distributors, Online Retail, Local Stores |
| Companies Covered | Bayer CropScience AG, Syngenta International AG, BASF SE, Corteva Agriscience, Adama Ltd, FMC Corporation, UPL Limited, Schelkovo Agrohim, RosAgroChim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Crop Protection Chemicals Market Evolving Landscape
Formulation chemistry and application technology are pivoting toward water-based delivery systems as residue regulations tighten and operator safety standards elevate across Russian commercial agriculture.
Suspension concentrate formulations are migrating from emulsifiable concentrates in wheat and barley applications across the Central Black Earth region. Large cereal growers are specifying SC products to reduce solvent exposure during tank-mixing operations. This migration from oil-based carriers is compressing demand for aromatic solvent imports while expanding domestic adjuvant blending capacity.
Russia's national agricultural regulator is implementing tightened pesticide residue maximum limits under harmonized EAEU technical regulations. Formulators must re-register existing portfolios with expanded toxicology dossiers and revised good manufacturing practice certifications. Oilseed segments face the steepest compliance burden, as sunflower and soybean export contracts now specify EU-aligned residue thresholds.
Buying committees at agricultural holding companies are consolidating procurement decisions previously dispersed across regional farm managers. Distributor networks are responding with dedicated account teams and inventory consignment arrangements. This concentration is most visible in Krasnodar Krai, where vertically integrated agribusinesses now negotiate direct supply agreements bypassing traditional retail channels.
Russia Crop Protection Chemicals Market Segmentation
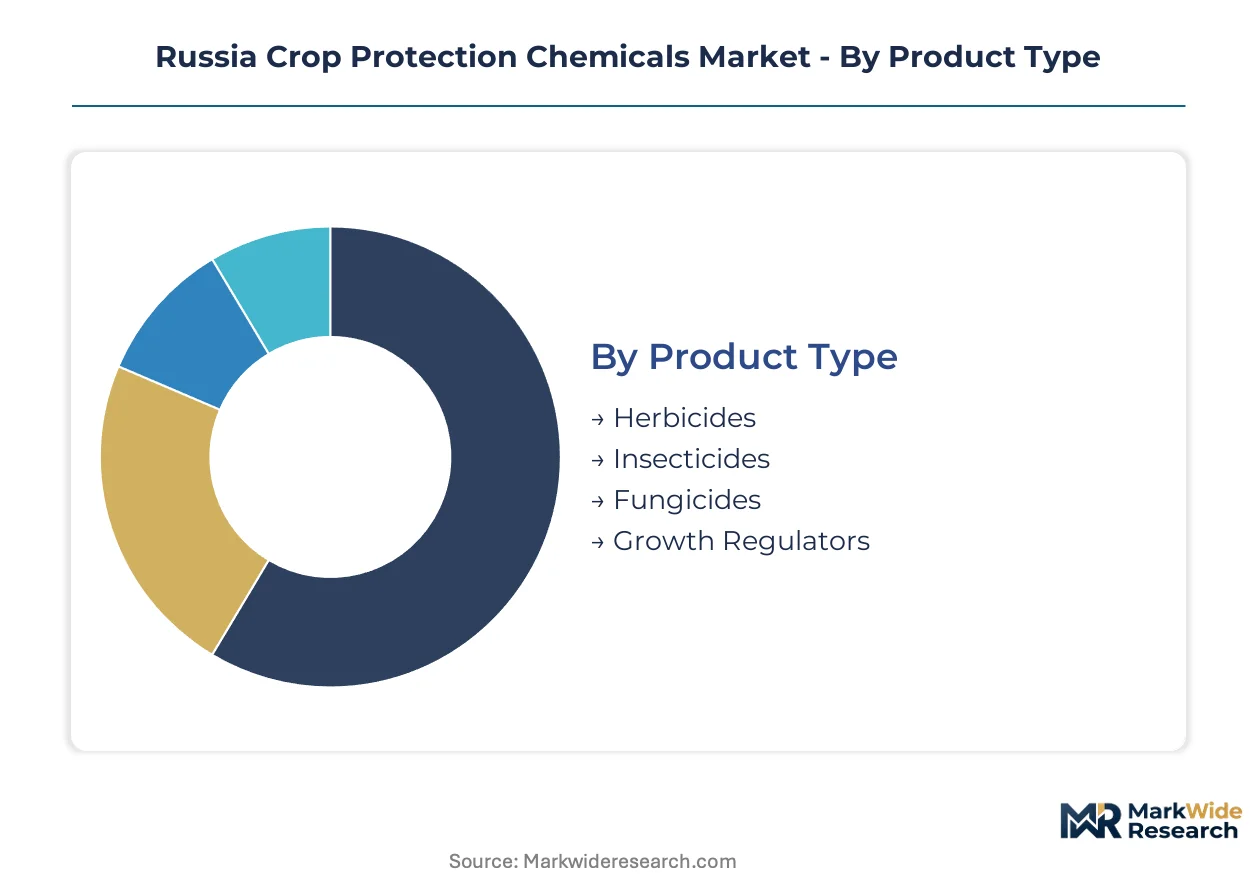
Russia's crop protection chemicals market fragments across four distinct dimensions, each revealing divergent margin profiles and procurement patterns. Technical registration requirements and import substitution mandates reshape competitive positioning within every segment tier.
Product Type:
After-sales service intensity varies sharply across chemistries, with herbicide users demanding seasonal technical support while growth regulator buyers prioritize precision dosing calibration.
- Herbicides:Synthetic auxins, triazines, and glyphosate formulations dominate cereal monoculture weed control. Demand concentrates across the Central Black Earth region's wheat and barley operations, where Schelkovo Agrohim has expanded generic glyphosate capacity under tightened residue limits. State procurement rules now require domestic production certificates, redirecting volume toward Voronezh manufacturing clusters.
- Fungicides:Azole and strobilurin chemistry protects against rust and septoria in humid growing zones. Sunflower and soybean plantings across Krasnodar Krai drive steepest demand expansion, as oilseed export contracts specify EU-aligned residue thresholds that force portfolio upgrades.
- Insecticides:Pyrethroid and neonicotinoid formulations target aphid and Colorado potato beetle pressure in vegetable systems.
- Growth Regulators:Gibberellin and cytokinin products manage lodging risk in intensive cereal production.
Herbicides hold the largest share; momentum sits with fungicides.
Application:
Cost tier differentiation separates commodity grain programs from high-value specialty crop protocols, with oilseed operations occupying a mid-tier investment position.
- Cereals:Wheat and barley applications consume the majority of herbicide volume across Kursk, Tambov, and Voronezh oblasts. Large holding companies professionalize procurement through centralized buying committees, negotiating direct supply agreements that bypass traditional distributor networks.
- Oilseeds:Sunflower and soybean plantings displace fallow acreage across the Southern Federal District, generating incremental fungicide and herbicide demand. EAEU residue harmonization simplifies multi-country registration for compliant formulators serving export-oriented crushers.
- Fruits:Orchard and vineyard applications in Krasnodar Krai require specialized fungicide rotations.
- Vegetables:Protected cultivation and open-field vegetable systems in Volgograd oblast use intensive insecticide programs.
Cereals dominate volume; oilseeds climb the fastest.
Formulation Type:
Volume concentration favors liquid delivery systems, with water-based alternatives displacing solvent-heavy legacy formats under tightening operator safety standards.
- Suspension Concentrates:Water-dispersible solid particles suspended in aqueous carriers reduce solvent exposure during tank-mixing. Central Black Earth cereal growers specify SC products exclusively, compressing demand for aromatic solvent imports while expanding domestic adjuvant blending capacity.
- Liquids:Ready-to-use solutions and soluble concentrates dominate smallholder retail channels. Local stores in Tambov and Kursk oblasts stock liquid formats for convenience, though large operations prefer concentrates for freight efficiency.
- Emulsifiable Concentrates:Oil-based carriers persist in legacy product registrations despite regulatory pressure.
- Granules:Soil-applied formulations target specific pest complexes in vegetable seedbed preparation.
Suspension concentrates gain share fastest; liquids retain the largest installed base.
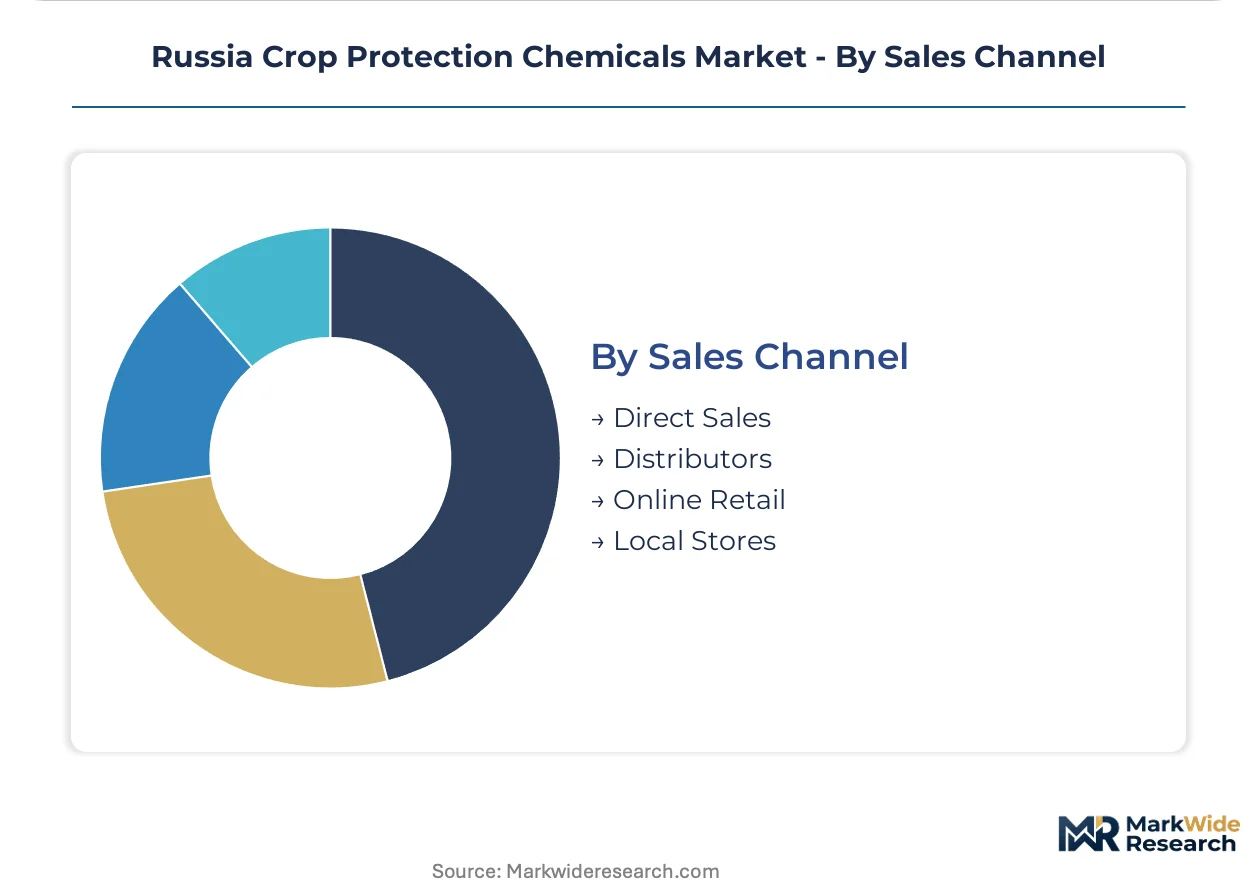
Sales Channel:
Customer type stratification separates institutional agricultural holdings from fragmented smallholder procurement, with distributor consolidation reshaping middle-tier access.
- Distributors:Regional agrochemical dealers maintain inventory consignment arrangements with large cereal operations. Account teams in Krasnodar Krai now bypass retail entirely, serving vertically integrated agribusinesses through dedicated supply contracts with captive financing terms.
- Direct Sales:Seed-treatment bundling and trait licensing push manufacturers toward integrated seed-plus-chemistry packages. Bayer CropScience leverages localized formulation facilities to sustain direct relationships despite sanctions complexity.
- Local Stores:Independent retailers serve smallholder vegetable and fruit producers with break-bulk quantities.
- Online Retail:Digital procurement platforms emerge for generic herbicide spot purchases.
Distributors hold the largest share; direct sales expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import substitution mandates and EAEU regulatory harmonization are redistributing manufacturing capacity toward domestic clusters while tightening residue standards reshape procurement patterns across Russian agricultural regions.
Central Black Earth Region
Wheat and barley monoculture drives herbicide consumption across Kursk, Tambov, and Voronezh oblasts. The national agricultural regulator enforces tightened pesticide residue maximum limits under EAEU technical regulations. Voronezh manufacturing clusters expand generic glyphosate formulation capacity to meet state procurement domestic content requirements.
Southern Federal District
Sunflower and soybean plantings displace fallow acreage across Krasnodar Krai and Rostov oblast, generating incremental fungicide and herbicide demand. EAEU residue harmonization simplifies multi-country registration for export-oriented crushers. Krasnodar-based vertically integrated agribusinesses negotiate direct supply agreements bypassing traditional distributor networks.
Volga Federal District
Samara and Saratov oblasts concentrate oilseed processing infrastructure with backward linkages to crop protection procurement. Import substitution policies redirect technical-grade material sourcing toward captive domestic synthesis installations. Tolyatti chemical complexes repurpose multi-purpose reactor capacity for agrochemical intermediate production.
North Caucasus Federal District
Stavropol Krai and Republic of Adygea specialize in high-value fruit and vegetable production requiring intensive fungicide rotations. Regional distributors maintain inventory consignment arrangements with large horticultural operations. Pyatigorsk formulation facilities adapt emulsifiable concentrate lines toward water-based suspension concentrate migration.
Ural Federal District
Chelyabinsk and Kurgan oblasts anchor spring wheat production with seasonal herbicide application windows compressed by shorter growing seasons. The Eurasian Economic Commission harmonizes technical standards across member states for cross-border product registration. Yekaterinburg distribution hubs coordinate logistics for generic herbicide spot purchases through emerging digital procurement platforms.
Russia Crop Protection Chemicals Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational formulators navigating sanctions complexity and domestic manufacturers capturing state-mandated procurement volume. Tier-one players retain seed-treatment and proprietary chemistry positions through localized production certificates. Tier-two domestic specialists exploit backward integration into active ingredient synthesis for commodity herbicide segments. Competitive moves concentrate on licensing negotiations for trait technologies and capacity expansion in suspension concentrate formulation lines.
Within the multinational tier, Bayer CropScience AG and Syngenta International AG exemplify archetypes adapting to regulatory fragmentation through localized facility strategies. Among domestic manufacturers, Schelkovo Agrohim occupies a position representing generic capacity expansion and captive synthesis integration. These three anchors illustrate the structural tension between proprietary chemistry access and import substitution mandates reshaping competitive positioning.
| Leading Market Players |
|---|
| Bayer CropScience AG |
| Syngenta International AG |
| BASF SE |
| Corteva Agriscience |
| Adama Ltd |
| FMC Corporation |
| UPL Limited |
| Schelkovo Agrohim |
| RosAgroChim |
| Others |
Value Network & Pricing Analysis
Active ingredient import dependency from China and India compresses margin buffers across Russian formulators while simultaneously widening price spreads between domestically synthesized generics and Western-origin proprietary chemistries. This structural sourcing vulnerability forces procurement committees to tier supplier relationships around technical-grade availability, with payment terms and inventory risk allocation becoming the primary negotiation levers.
Pricing Analysis
Certification level under Russia's domestic production certificate regime creates the primary spread between state-eligible and import-dependent product tiers. Contract-based long-term offtake dominates institutional procurement, while spot purchasing persists for generic herbicide volume. Price differentiation rests on residue compliance grade and captive synthesis depth, with commodity glyphosate segments experiencing cost compression from Schelkovo Agrohim capacity additions. Large cereal operations in Kursk and Tambov oblasts exhibit lowest price sensitivity due to yield-protection economics, whereas smallholder vegetable producers in Volgograd oblast drive hardest bargain hunting.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now characterize distributor relationships with vertically integrated agribusinesses in Krasnodar Krai. Geographic supply concentration centers on China for technical-grade glyphosate and 2,4-D acid, India for pyrethroid intermediates, and domestic Voronezh clusters for formulated product finishing. Raw material dependencies include aromatic solvents, surfactant packages, and polymer dispersants. Single-source vulnerability from payment system disruptions threatens active ingredient flows. Distribution runs through regional dealers with inventory consignment arrangements, though direct manufacturer contracts are displacing traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling represents the fastest-expanding revenue layer, with seasonal agronomic support and precision dosing calibration outpacing pure chemistry sales growth across the Central Black Earth region.
For Market Incumbents: Insulate proprietary chemistry positions by deepening captive synthesis integration in Voronezh manufacturing clusters, while accelerating suspension concentrate line conversions to meet water-based formulation demand. Defend against Schelkovo Agrohim's generic expansion by locking multi-year seed-treatment bundling contracts with Krasnodar-based agricultural holdings. Certification investment under tightened EAEU residue harmonization serves as the critical retention lever.
For New Entrants and Emerging Players: The North Caucasus Federal District's high-value fruit and vegetable segment offers underpenetrated white-space for microbial inoculant and biopesticide entrants, with Stavropol Krai operations seeking alternatives to intensive fungicide rotations. Target direct supply agreements with horticultural cooperatives bypassing distributor markups. Lead with fermentation-based manufacturing narratives to differentiate from synthetic chemistry incumbents.
For Investors and Strategic Acquirers: The market sits at an import substitution acceleration phase that favors domestic manufacturers with backward integration into active ingredient synthesis. Long-term viability hinges on regulatory alignment with EAEU technical standards and residue limit convergence. Acquisition targets should demonstrate multi-purpose reactor commissioning progress and domestic production certificate portfolios. Watch for re-registration timeline compression as the inflection signal indicating portfolio rationalization pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captive technical-grade production insulates Voronezh formulators from import logistics friction. |
| Suspension Concentrate Line Conversion | Water-based formulation migration aligns with Central Black Earth operator safety standards. |
| Seed-Treatment Bundling Partnerships | Integrated seed-plus-chemistry packages lock Krasnodar agribusinesses into multi-year supply contracts. |
| Biological Formulation Development | Microbial inoculant capacity addresses underdeveloped biopesticide demand in oilseed segments. |
| EAEU Regulatory Harmonization Compliance | Converged residue standards enable multi-country registration for export-oriented crushers. |
Research Methodology
A standing panel of agrochemical formulators, procurement leads at agricultural holdings, distributor account managers, and regulatory affairs specialists provided ongoing calibration throughout the study. Primary interviews with plant managers at Voronezh and Krasnodar manufacturing clusters combined with secondary validation from customs trade data, Eurasian Economic Commission technical regulations, and SEC filings of listed multinational parents. Bottom-up volume builds across herbicide, fungicide, and insecticide segments triangulated against top-down market sizing from import substitution policy targets.
Scenario-bracketing around regulatory timeline compression and technical import availability framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product chemistry type, crop application, formulation technology, and procurement channel tier. CAGRs derived from trend extrapolation of historical import volumes adjusted for domestic capacity commissioning schedules. Forecast inputs incorporated EAEU residue harmonization implementation pace and state procurement domestic content threshold enforcement.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Schelkovo Agrohim or accelerated biological formulation entry would shift outcomes beyond modeled ranges. Macroeconomic sanctions evolution, regulatory divergence between Russian national standards and EAEU technical regulations, or breakthroughs in fermentation-based manufacturing economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Vietnam Fungicide Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Europe Acaricides Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Soil Fumigant Market
Crop Protection
Isoxaflutole Market
Crop Protection
Soil Sterilizers Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Metamifop Market
Crop Protection
US Insecticide Market
Crop Protection
IPM Pheromones Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
South America Insecticide Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Global Termite Control Market