
 Australia Greenhouse Horticulture Market | 2026-2036
Australia Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Greenhouse Horticulture Market Insights
Project finance tied to renewable energy certificates is reconfiguring capital access for controlled-environment agriculture ventures in Australia. Sundrop Farms leverages its solar-thermal desalination integration to sustain operations in Port Augusta’s arid conditions. Costa Group Holdings Ltd anchors national supply through its network of glasshouse facilities across multiple states. Perfection Fresh differentiates via premium tomato and berry varietals developed through proprietary propagation programs.
Australia greenhouse horticulture encompasses the cultivation of crops within engineered structures where temperature, humidity, light, and irrigation are actively managed to optimize yield and quality regardless of external climate conditions. These facilities typically employ hydroponic or substrate-based systems with recirculating nutrient solutions, achieving water use efficiencies exceeding conventional field agriculture. Vegetables dominate product type output, reflecting sustained retail procurement for tomatoes, cucumbers, and capsicums across supermarket chains. Hydroponics leads technology deployment due to its proven scalability and compatibility with existing greenhouse infrastructure nationwide. Commercial growers represent the core end user segment, capturing the majority of capital investment and production volume as they supply wholesale and retail channels.
Biosecurity regulation under the Department of Agriculture, Fisheries and Forestry shapes import protocols for propagation materials and equipment, while Food Standards Australia New Zealand governs pesticide residue limits and labeling requirements for domestic sale. The Water Act 2007 and associated Murray-Darling Basin compliance frameworks constrain extraction entitlements, pushing operators toward closed-loop recycling and atmospheric water generation. Stakeholders must monitor evolving energy market reforms and carbon accounting rules that will determine the cost structure of heated and illuminated production systems.
Market Dynamics
Water scarcity across the Murray-Darling Basin is compressing grower margins and forcing capital redeployment into closed-loop infrastructure. The Water Act 2007 entitlements framework has transformed irrigation access from an operational cost into a strategic constraint that shapes facility location decisions.
Growth Catalysts
- Murray-Darling Basin Plan compliance:Regulatory pressure from the Department of Agriculture, Fisheries and Forestry accelerates investment in recirculating hydroponic systems that reduce extraction volumes.
- Solar-thermal integration:Concentrated solar power systems now anchor greenhouse clusters in Port Augusta and Whyalla, cutting thermal energy costs for year-round tomato and capsicum production.
- Supermarket contract consolidation:Coles and Woolworths procurement teams are locking multi-year supply agreements with domestic glasshouse operators to secure consistent quality and traceability.
Market Restraints
- Natural gas price volatility:Heating costs for winter production cycles fluctuate with east coast LNG export parity pricing, eroding margin predictability for Victorian and Tasmanian operators.
- Propagation material import dependency:Biosecurity quarantine protocols under DAFF constrain seedling and grafted stock availability, creating 12-18 month lead times for new varietal introductions.
- Skilled technician scarcity:Climate control engineering and hydroponic nutrient management expertise concentrates in Adelaide and Melbourne, limiting expansion into regional Queensland and Western Australia.
Strategic Opportunities
- Atmospheric water generation:Emerging desiccant and condensation technologies enable operations in arid zones previously excluded from horticulture due to extraction entitlement limits.
- Carbon accounting integration:The Safeguard Mechanism reforms create pathways for greenhouse operators to monetize emissions reductions through Australian Carbon Credit Units.
- Specialty berry propagation:Proprietary breeding programs for premium strawberry and raspberry cultivars command price premiums in export markets across Southeast Asia.
Industry Challenges
- Integrated pest management certification:HACCP and Freshcare accreditation timelines stretch 8-14 months, delaying market access for new entrants seeking supermarket supplier status.
- Legacy soil-based infrastructure retrofit:Converting field-growing operations to substrate systems requires simultaneous upgrades to drainage, fertigation, and environmental control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Greenhouse Horticulture Market |
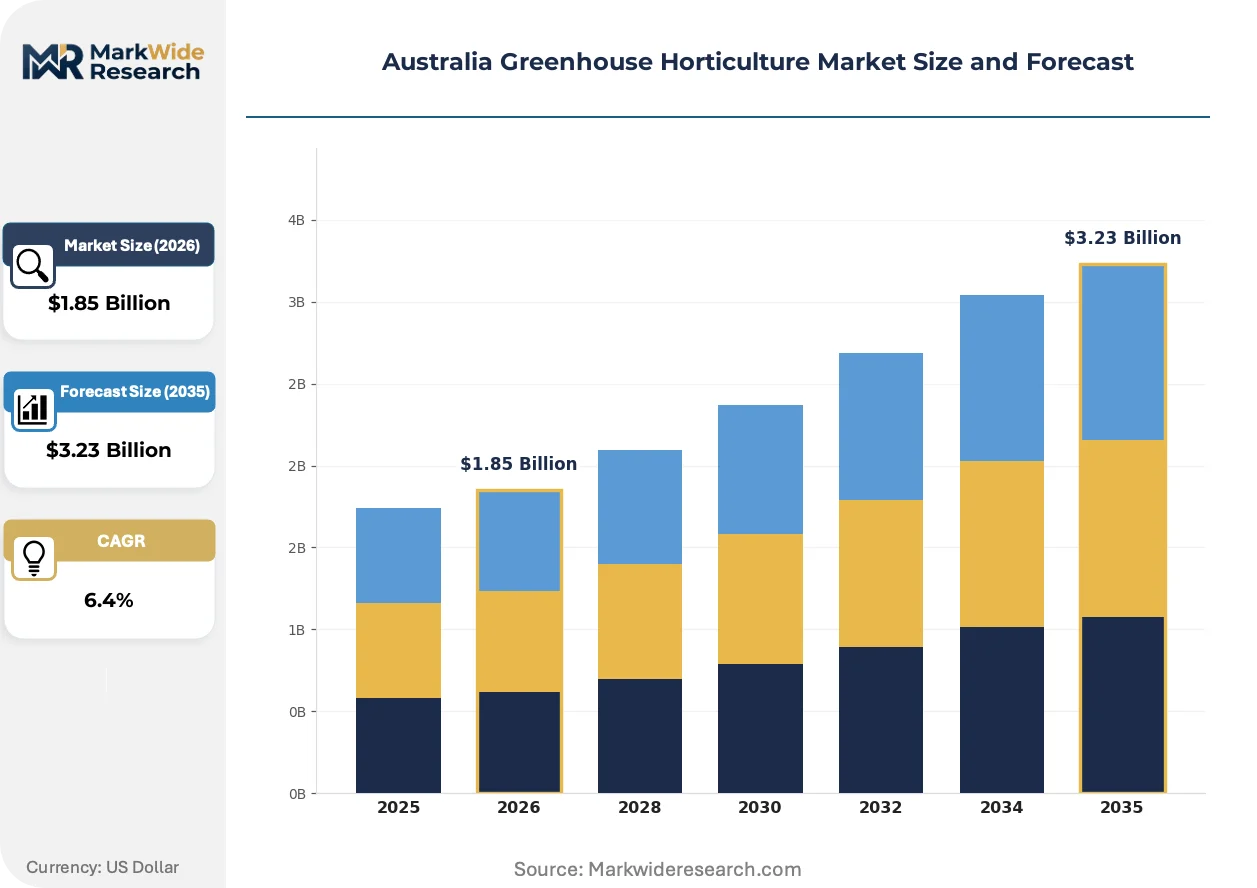
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tropicals, Vegetables, Flowers, Herbs Technology: Hydroponics, Aeroponics, Aquaponics, Soil-Based End User: Commercial Growers, Retailers, Wholesalers, Home Gardens Distribution Channel: Direct Sales, Online Retail, Grocery Stores, Farmer’s Markets |
| Companies Covered | Sundrop Farms, Apex Greenhouses, Tapex Horticulture Group, GreenLife, Costa Group Holdings Ltd, Fernland, Select Harvests Limited, Flavorite Hydroponic Tomatoes, Perfection Fresh, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Greenhouse Horticulture Market Trends and Innovations
Automation and renewable energy convergence is compressing the cost structure of controlled-environment production while reshaping workforce composition across Australian growing regions.
Sensor networks and cloud-based climate management platforms are digitizing greenhouse operations from manual thermostat adjustment to predictive environmental optimization. Large commercial growers in South Australia and Victoria are deploying these systems fastest, with adoption timelines compressing from five-year replacement cycles to 18-month upgrade windows. This digitization is enabling remote monitoring of multi-site portfolios and reducing on-floor technical staffing ratios by half.
The Water Act 2007 and associated Basin Plan recovery targets are forcing permanent water entitlement reallocation from traditional irrigators to high-efficiency greenhouse operators. This regulatory pressure is concentrating production in zones with recycled water infrastructure access and excluding legacy field growers from renewal contracts. South Australian operators with closed-loop systems are capturing transferred entitlements and expanding glasshouse footprints while field tomato producers in northern Victoria exit.
Retail procurement teams now mandate blockchain-traceable provenance and real-time quality dashboards as standard contract terms rather than premium options. This buyer-driven transparency requirement is displacing paper-based audit trails and third-party certification as primary trust mechanisms. The shift is most visible in strawberry and tomato categories where Coles and Woolworths control over seventy percent of domestic offtake and specify data integration protocols.
Australia Greenhouse Horticulture Market Segmentation
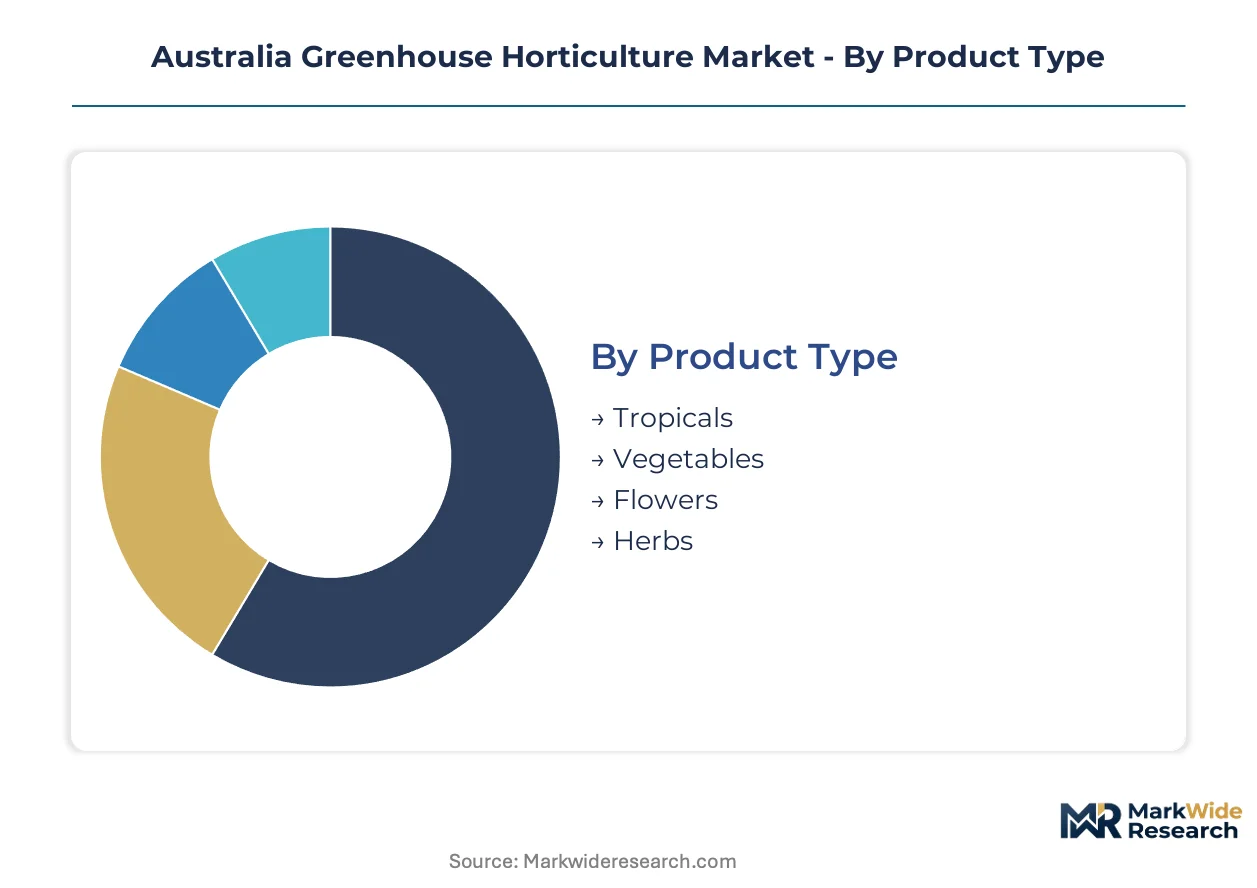
Segmentation in Australian greenhouse horticulture reveals how capital allocation, regulatory compliance, and supply chain configuration concentrate across distinct operational models. Each dimension shapes facility design, water entitlement requirements, and supermarket contract eligibility differently.
Product Type:
After-sales service intensity varies sharply across crop categories, with vegetables demanding continuous technical support for climate optimization while flowers require specialized post-harvest handling protocols.
- Vegetables:Tomatoes, cucumbers, and capsicums dominate output through hydroponic glasshouse systems optimized for supermarket shelf-life specifications. South Australian and Victorian clusters supply Coles and Woolworths procurement networks with year-round consistency enforced by renewable-thermal integration.
- Tropicals:Banana, papaya, and exotic fruit cultivation concentrates in Queensland protected structures where humidity control systems counter cyclone season volatility. These operations require specialized HVAC maintenance contracts given the precision of tropical microclimate replication.
- Flowers:Ornamental production serves event markets and floristry chains with cultivar-specific photoperiod management.
- Herbs:Basil, coriander, and specialty varieties supply foodservice distributors with rapid-turnover propagation cycles.
Vegetables holds the largest share; momentum sits with tropicals as Queensland infrastructure expands.
Technology:
Technology selection directly determines capital intensity, water entitlement efficiency ratings, and eligibility for Murray-Darling Basin compliance incentives.
- Hydroponics:Recirculating nutrient film and deep-water culture systems anchor commercial scale across South Australia and Victoria. These installations achieve extraction volume reductions that satisfy Water Act 2007 recovery targets while supporting tomato and capsicum volume contracts with major retailers.
- Aeroponics:Mist-based root delivery enables lettuce and leafy green density maximization in vertical configurations. Adelaide-based operators deploy these systems where land costs and water scarcity converge, though technical staffing requirements constrain regional expansion.
- Aquaponics:Fish-horticulture integration serves niche organic certification markets with integrated biological filtration.
- Soil-Based:Substrate and compost systems persist in legacy operations transitioning toward closed-loop infrastructure.
Hydroponics commands the installed base; aeroponics is gaining share fastest in metropolitan fringe developments.
End User:
End user type shapes facility scale, biosecurity protocol stringency, and traceability system investment requirements.
- Commercial Growers:Multi-hectare glasshouse operators in Port Augusta, Two Wells, and Warragul anchor national supply through centralized propagation, climate control engineering, and direct supermarket contracting. These entities capture renewable energy certificate financing and water entitlement transfers from exiting field irrigators.
- Retailers:Controlled-environment production for captive supply chains concentrates in Woolworths and Coles vertical integration initiatives.
- Wholesalers:Aggregation and distribution intermediaries serve independent grocers and foodservice with consolidated procurement.
- Home Gardens:Hobbyist-scale greenhouse kits and modular systems populate urban and peri-urban markets.
Commercial growers hold the largest share; momentum sits with retailers as direct sourcing accelerates.
Distribution Channel:
Channel configuration determines cold chain investment, quality certification requirements, and margin capture positioning.
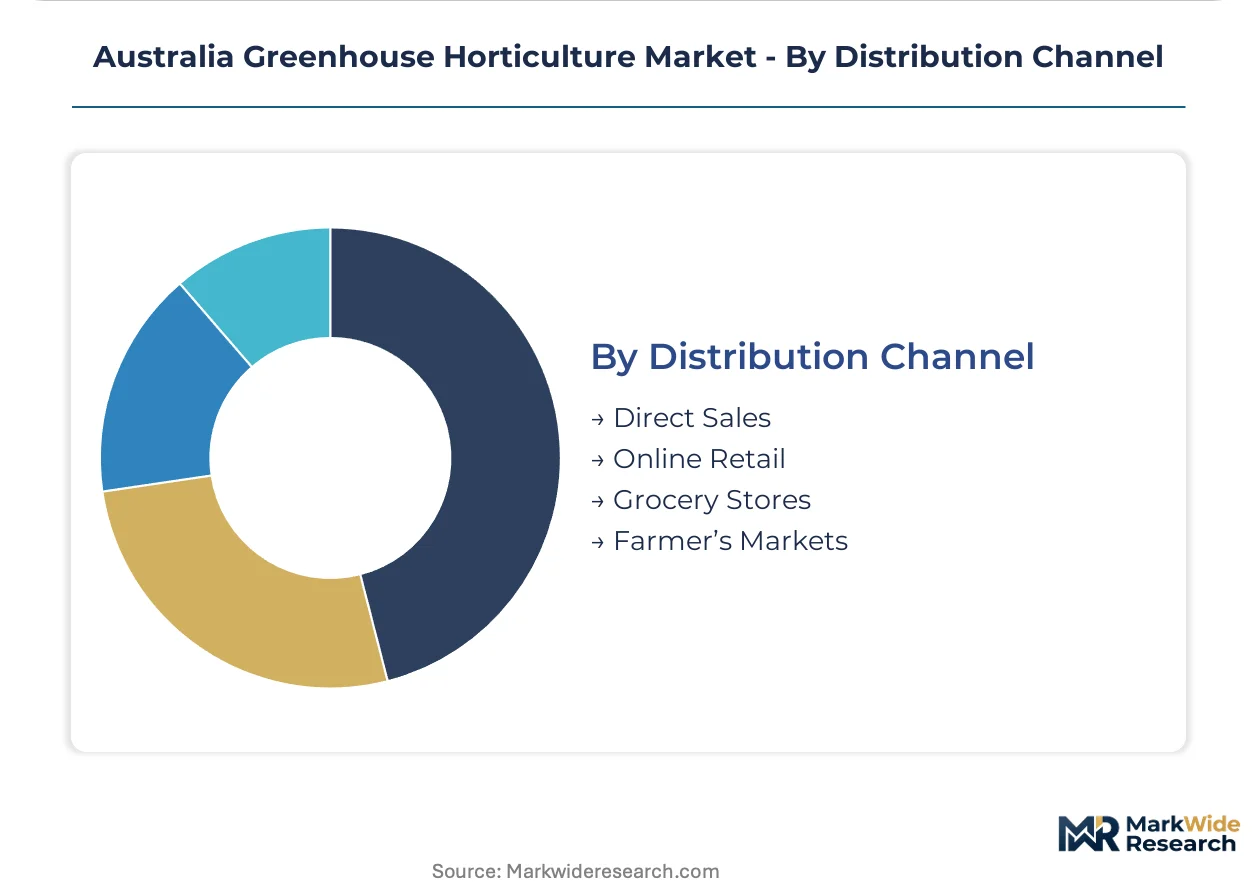
- Grocery Stores:Coles and Woolworths procurement teams mandate blockchain traceability, real-time quality dashboards, and multi-year volume commitments as standard contract terms. These specifications are displacing traditional wholesale intermediation and concentrating supply relationships with large-scale glasshouse operators.
- Direct Sales:Farm-gate and contract supply to processors captures premium pricing for proprietary cultivars.
- Online Retail:Subscription produce boxes and specialty ingredient platforms serve metropolitan consumers.
- Farmer's Markets:Localized premium positioning supports small-scale heirloom and specialty variety differentiation.
Grocery stores hold the largest share; momentum sits with direct sales as traceability technology reduces intermediary dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Water Act 2007 entitlements framework and Murray-Darling Basin Plan compliance requirements are redirecting capital toward high-efficiency greenhouse clusters. State-level renewable energy incentives and water trading mechanisms determine facility location economics.
South Australia
Solar-thermal desalination integration enables year-round tomato and capsicum production in Port Augusta and Whyalla. The state's water trading framework transfers extraction entitlements from exiting field irrigators to closed-loop glasshouse operators. Sundrop Farms anchors the Port Augusta cluster with concentrated solar power systems sustaining operations in arid conditions.
Victoria
Natural gas price volatility for winter heating cycles compresses margins in the Gippsland and Mornington Peninsula growing regions. Food Standards Australia New Zealand pesticide residue protocols govern supply contracts with Coles and Woolworths procurement networks. The Warragul-Two Wells corridor concentrates glasshouse infrastructure serving Melbourne's wholesale markets.
Queensland
Tropical fruit protected cultivation expands in Bundaberg and Bowen to counter cyclone season volatility. The state's biosecurity quarantine protocols under the Department of Agriculture, Fisheries and Forestry constrain propagation material imports. Humidity control engineering expertise concentrates in Brisbane, limiting regional expansion into Far North Queensland.
New South Wales
Blockchain-traceable provenance mandates from supermarket procurement teams drive technology investment in Sydney's peri-urban fringe. The Murray-Darling Basin Authority compliance frameworks constrain extraction access for legacy field growers. The Central Coast and Hawkesbury regions host transitioning operations adopting substrate-based hydroponic systems.
Western Australia
Atmospheric water generation pilot programs enable greenhouse development in the Wheatbelt beyond Murray-Darling entitlement zones. The state's renewable energy certificate financing supports solar-thermal integration for isolated operations. Perth's technical staffing concentration limits expansion into regional Kimberley and Pilbara zones.
Australia Greenhouse Horticulture Market Competitive Landscape
On the supply side, the industry is consolidating around multi-hectare glasshouse operators with direct supermarket contracting relationships. Three strategic archetypes dominate: renewable-thermal integrated desert operators, premium varietal propagators with proprietary breeding programs, and diversified national networks with multi-state facility portfolios. Capacity expansion through water entitlement transfers and backward integration into captive propagation supply represent the primary competitive vectors.
Among national-scale diversified operators, Costa Group Holdings Ltd occupies a position exemplifying multi-state glasshouse network consolidation. Sundrop Farms represents the renewable-thermal integrated archetype with its Port Augusta solar-desalination facility. Perfection Fresh anchors the premium varietal tier through proprietary tomato and berry propagation programs.
| Leading Market Players |
|---|
| Sundrop Farms |
| Apex Greenhouses |
| Tapex Horticulture Group |
| GreenLife |
| Costa Group Holdings Ltd |
| Fernland |
| Select Harvests Limited |
| Flavorite Hydroponic Tomatoes |
| Perfection Fresh |
| Others |
Pricing and Supply Chain Analysis
Propagation material imports from the Netherlands and Israel concentrate upstream supply for Australian greenhouse operators, locking margin pools with domestic propagators who control varietal access and biosecurity-cleared stock availability. Water entitlement trading under the Murray-Darling Basin Plan feeds directly into facility location economics, with closed-loop operators capturing cost advantages that field growers cannot match.
Pricing Analysis
Certification tier creates the primary spread, with HACCP and Freshcare-accredited produce commanding premium contract terms from Coles and Woolworths procurement teams while uncertified supply faces price compression. Three-tier pricing structure across premium proprietary cultivars, standard hydroponic lines, and commodity field-grown alternatives reflects traceability investment and varietal exclusivity. Pricing pressure stems from natural gas heating cost volatility in Victorian winter production cycles. Independent grocers and foodservice distributors exhibit highest price sensitivity, whereas supermarket direct contracts show lowest elasticity due to traceability mandates.
Supply Chain Analysis
Extended payment terms from equipment suppliers and supply-chain finance facilities through major banks support capital-intensive greenhouse infrastructure deployment across South Australia and Victoria. Glasshouse technology and climate control systems draw from the Netherlands, Israel, and Spain, while propagation materials hinge on biosecurity-cleared imports from the same corridors. Single-source vulnerability concentrates in specialized HVAC engineering and nutrient formulation supply. Distribution runs through supermarket direct procurement networks that displace traditional wholesale intermediation, with blockchain-traceable cold chain logistics now mandatory for contract eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
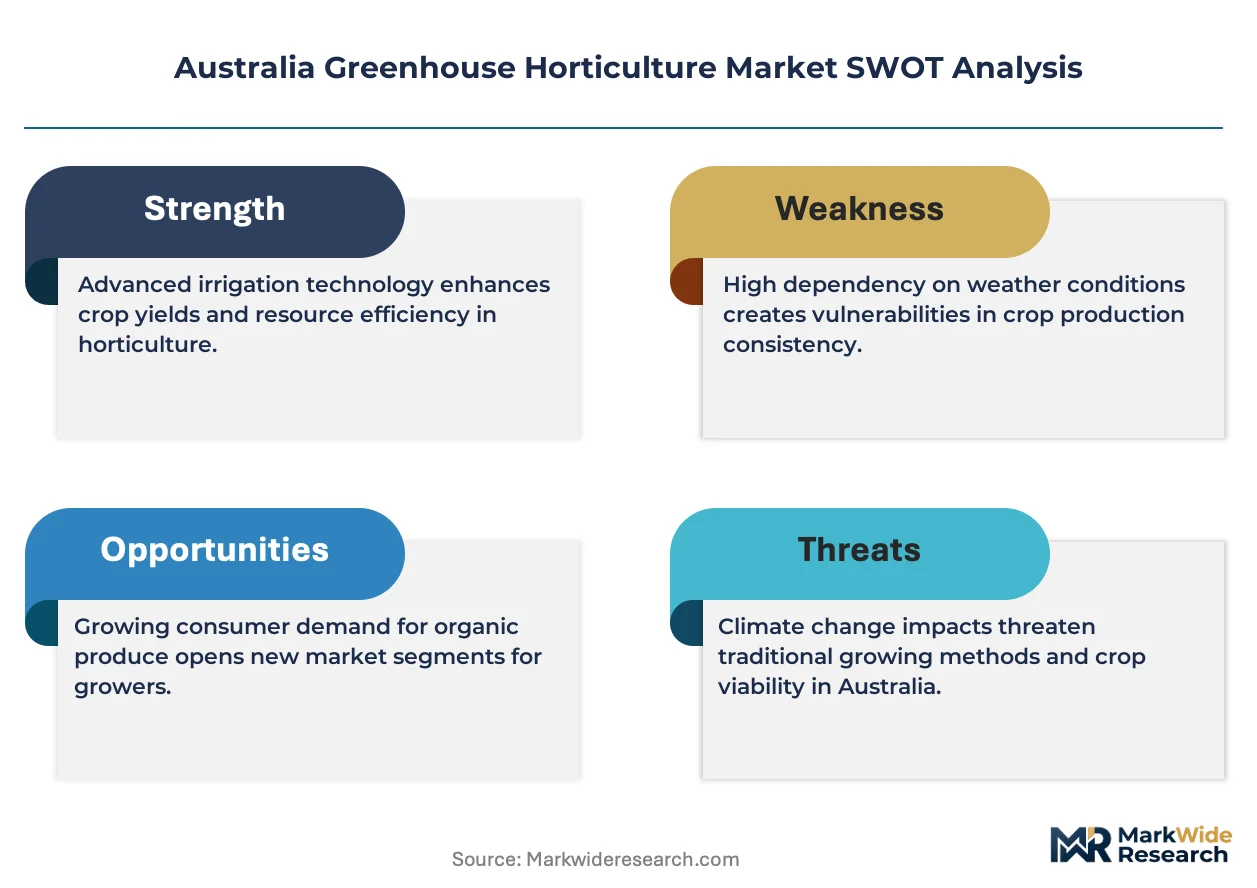
Australian greenhouse horticulture presents a defensive-moat market anchored by regulatory entrenchment around water entitlement transfers and biosecurity-cleared propagation access that newcomers cannot rapidly replicate.
For Market Incumbents: Harden market position through backward integration into captive propagation facilities that eliminate varietal import lead times, while securing long-term water entitlement transfers from exiting field irrigators in the Murray-Darling Basin. Costa Group and Perfection Fresh demonstrate this consolidation trajectory. Natural gas price volatility in Victorian heating cycles represents the primary margin threat requiring renewable-thermal hedging. For New Entrants and Emerging Players: Build out atmospheric water generation capabilities in Western Australian Wheatbelt zones beyond Murray-Darling entitlement constraints, where solar-thermal integration and isolation from incumbent clusters create white-space opportunity. Queensland tropical fruit protected cultivation offers secondary penetration potential given humidity control engineering scarcity in Far North Queensland. Direct-to-processor contracting for proprietary berry cultivars provides the cleanest go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed renewable-thermal integrated operators in Port Augusta and Whyalla that require growth capital for multi-site expansion. Five-to-ten year viability hinges on water entitlement portfolio depth and supermarket contract renewal rates. The signal to watch is Murray-Darling Basin Plan recovery target acceleration that would force additional field irrigator exits and concentrate supply with closed-loop glasshouse operators.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Irrigation Expansion | Water Act 2007 compliance transfers entitlements from field growers to greenhouse operators. |
| Solar-Thermal Integration | Sundrop Farms demonstrates concentrated solar power viability for arid-zone tomato production. |
| Proprietary Propagation Programs | Perfection Fresh commands price premiums through exclusive berry varietal control. |
| Blockchain Traceability Deployment | Coles and Woolworths mandate real-time quality dashboards as standard contract terms. |
| Atmospheric Water Generation Pilot | Western Australian Wheatbelt development bypasses Murray-Darling extraction limits. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Water Act 2007 entitlements data, Murray-Darling Basin Authority recovery reports, Food Standards Australia New Zealand pesticide residue databases, and supermarket procurement disclosure documents. Primary interviews incorporated greenhouse operations managers, climate control engineers, water trading brokers, Coles and Woolworths category buyers, and Department of Agriculture biosecurity officers. Bottom-up facility capacity modeling and top-down retail offtake estimation provided cross-validation.
Forecast inputs span hydroponic technology adoption curves, water entitlement transfer volumes, renewable energy certificate financing availability, and supermarket contract consolidation rates across the projection horizon. Segmentation dimensions modeled include product type, cultivation technology, end-user category, and state-level regulatory framework. CAGRs derive from facility expansion pipelines and historical entitlement reallocation patterns. Solar-thermal cost trajectories and natural gas price volatility assumptions shape thermal energy cost projections.
Stress conditions across water entitlement allocation scenarios, biosecurity quarantine duration extensions, and renewable energy policy discontinuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption timelines and regulatory compliance trajectories. Macroeconomic deviation, Basin Plan reform acceleration, or breakthrough atmospheric water generation cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Garden Cress Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Canada Microgreens Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Roselle Market
Vegetables
Spain Avocado Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Yam Products Market
Vegetables
South America Peas Market
Vegetables
Yarrow Market
Vegetables
Greenhouse Produce Market
Vegetables
Turkey Greenhouse Horticulture Market