
 Global Phosphine Fumigation Market | 2026-2036
Global Phosphine Fumigation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phosphine Fumigation Market Foresight
Grain export logistics is shifting toward phosphine-based fumigation as biosecurity protocols tighten at destination ports. UPL Limited anchors South Asian supply through its aluminum phosphide tablet distribution network. Degesch America dominates North American manufacturing with EPA-registered formulations. Solvay Group extends its European reach via REACH-compliant magnesium phosphide production.
Phosphine fumigation employs aluminum, magnesium, or zinc phosphide formulations that release hydrogen phosphide gas upon moisture contact, achieving lethal concentrations for stored-product insects at 200–1000 ppm over 72-hour exposure periods. Aluminum phosphide tablets hold the largest volume share due to cost efficiency and established handling protocols among cereal processors. Warehouse applications are expanding fastest as post-harvest losses drive public-sector investment in bulk storage infrastructure across emerging grain-exporting economies.
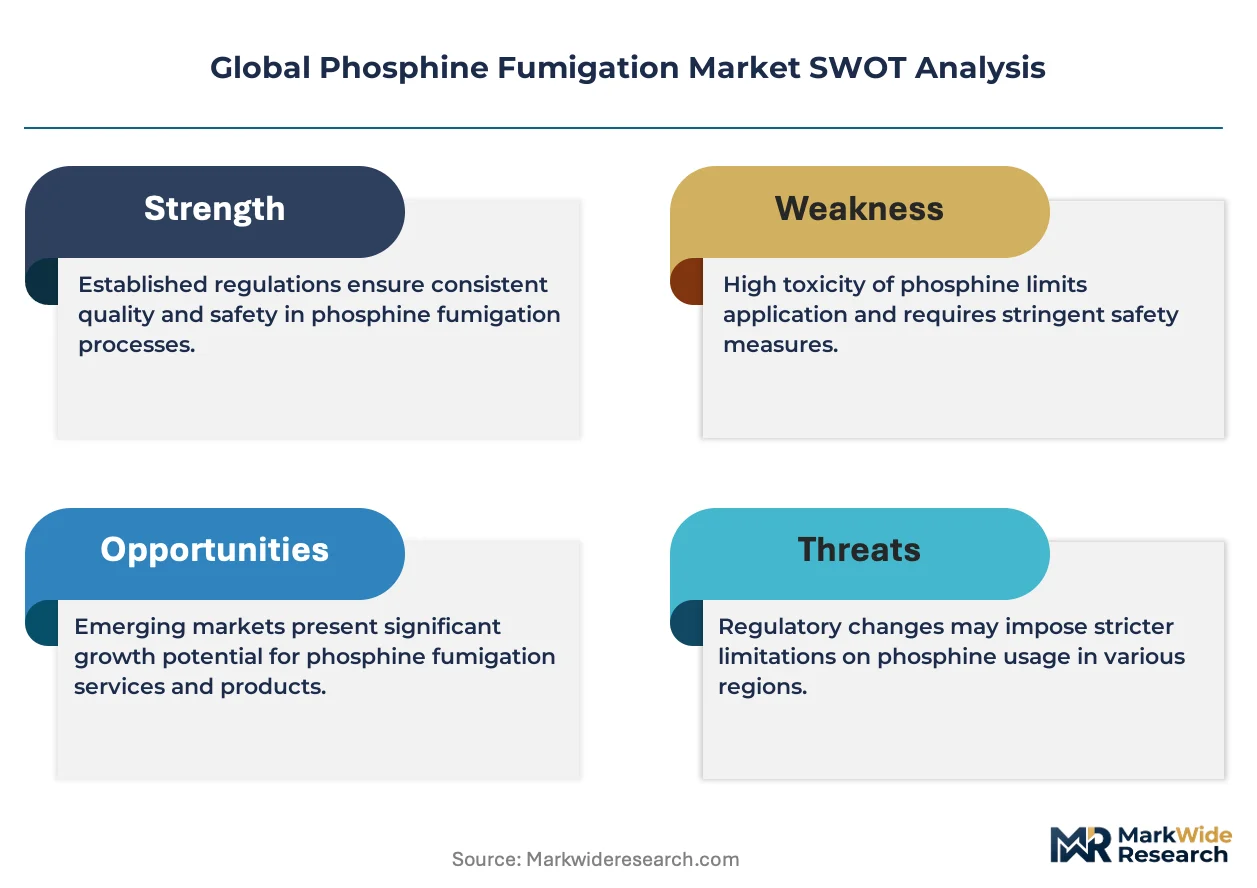
The EPA governs phosphine tolerance levels and applicator certification in the United States, while REACH classification rules in Europe restrict certain formulation chemistries and mandate exposure documentation. India's Central Insecticides Board regulates product registration and residue limits under the Insecticides Act. Stakeholders must monitor evolving residue standards and applicator safety mandates to sustain market access across jurisdictions.
Market Dynamics
Biosecurity mandates at destination ports are forcing grain exporters to standardize phosphine-based treatment protocols ahead of cargo loading, compressing fumigation windows and elevating formulation quality requirements across supply chains.
Growth Catalysts
- REACH residue tightening:ECHA's downward revision of phosphine tolerance thresholds in stored cereals is accelerating formulation upgrades toward magnesium phosphide with cleaner degradation profiles.
- Brazilian grain export surge:Port authorities in Santos and Paranaguá now mandate phosphine certificates for soybean and corn shipments, institutionalizing pre-shipment fumigation services.
- Aluminum phosphide tablet automation:Automated dispensing systems in Australian bulk elevators are cutting labor exposure while maintaining 200-1000 ppm concentration bands required for insect mortality.
Market Restraints
- Active ingredient concentration:EPA-registered aluminum phosphide formulations face manufacturing bottlenecks due to restricted phosphine gas precursor availability from concentrated Chinese chemical suppliers.
- Alternative treatment competition:Controlled atmosphere storage using nitrogen displacement is capturing premium organic grain segments that reject chemical residue entirely.
- Applicator certification scarcity:OSHA-mandated respiratory protection training creates labor pool constraints, extending service deployment timelines in peak harvest windows.
Strategic Opportunities
- Black Sea corridor expansion:Ukrainian and Romanian port infrastructure investments are creating demand for mobile fumigation units serving containerized grain exports.
- India's FSSAI integration:Food safety regulators are aligning phosphine residue limits with Codex Alimentarius standards, opening export-grade treatment contracts for domestic millers.
- Phosphine sensor convergence:Integration of electrochemical detection arrays with warehouse management software is enabling real-time concentration monitoring and automated ventilation triggers.
Industry Challenges
- Certification timeline compression:India's Central Insecticides Board registration renewals now require expanded toxicology dossiers, extending product approval cycles by 18-24 months.
- Legacy warehouse retrofit costs:Concrete silo sealing standards for gas retention compliance demand capital-intensive infrastructure modifications across public-sector storage networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phosphine Fumigation Market |
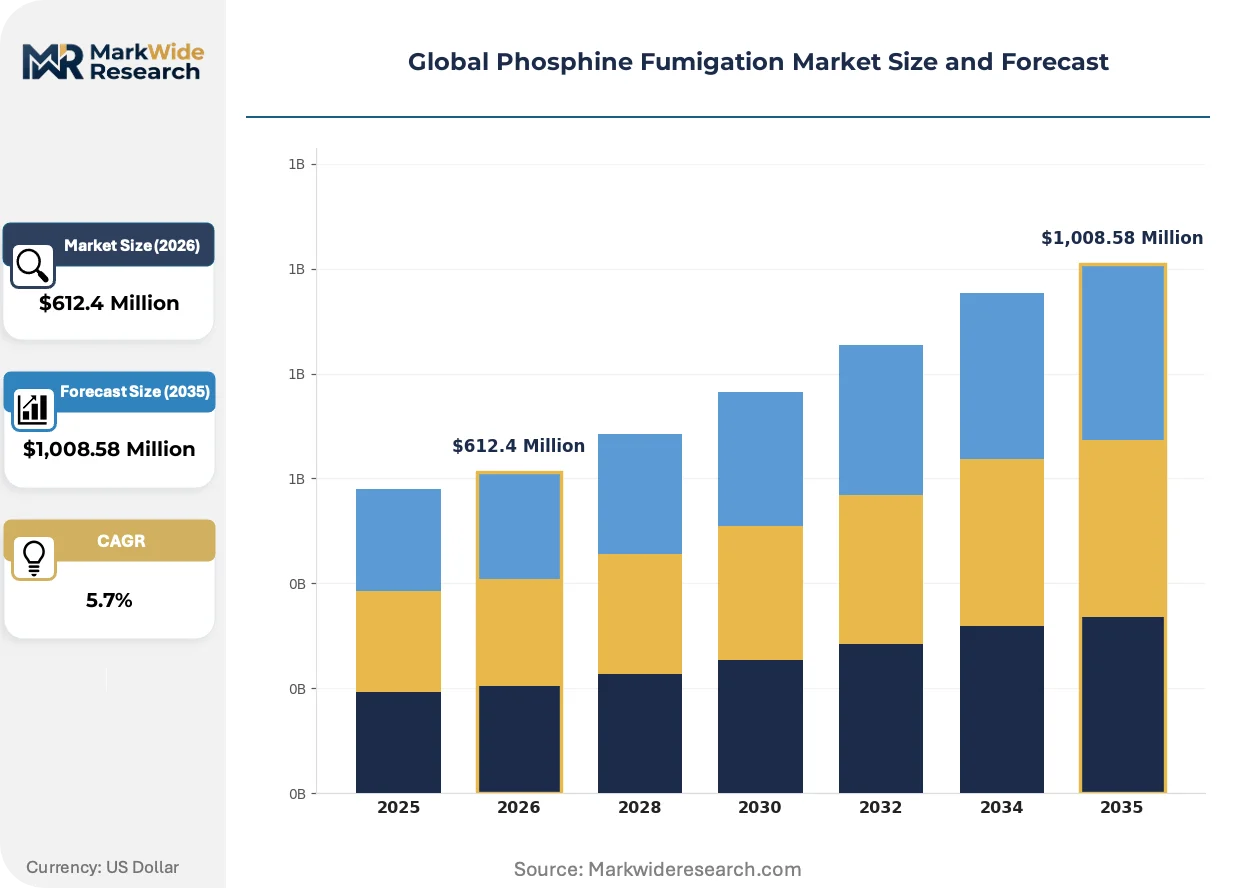
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,008.58 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Phosphide, Magnesium Phosphide, Zinc Phosphide, Calcium Phosphide Application: Stored Grains, Warehouses, Ship Holds, Food Processing Plants, Tobacco Storage End User: Cereal Processors, Grain Exporters, Pest Control Operators, Logistics Providers Packaging Type: Tablets, Pellets, Granules, Sachets, Loose Powder |
| Companies Covered | UPL Limited, Degesch America Inc, Solvay Group, Detia Degesch GmbH, Nufarm Limited, BASF SE, ADAMA Agricultural Solutions Ltd., Rentokil Initial Plc, AMVAC Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phosphine Fumigation Market Shifts & Advancements
Formulation chemistry and detection technologies are converging to reduce residue uncertainty and labor exposure simultaneously, while regulatory alignment across major grain-exporting jurisdictions is compressing compliance complexity.
Magnesium phosphide pellet formulations with controlled-release membranes are rewriting exposure management protocols in European bulk storage facilities. Grain cooperatives in Germany and France are adopting these chemistries to meet REACH documentation requirements with fewer ventilation cycles. The technology is compressing the trade-off between treatment efficacy and aeration downtime that has constrained warehouse throughput economics.
EPA's 2024 revisions to phosphine tolerance exemptions for processed foods are forcing formulation suppliers to submit refined dissipation studies. Food manufacturers in the United States are responding by segregating phosphine-treated grain streams earlier in processing to prevent cross-contamination into finished products. Breakfast cereal and snack segments with tight residue specifications are driving demand for third-party verification services.
Buyer consolidation among multinational grain traders is concentrating procurement authority with fewer sourcing managers who mandate standardized fumigation documentation across origin ports. Exporters in Australia and Brazil are adopting digital certificate platforms that integrate phosphine treatment records with blockchain traceability systems. This behavioral shift is most pronounced in soybean shipments to China, where customs authorities now require residue testing at discharge ports with rejection authority.
Global Phosphine Fumigation Market Segmentation
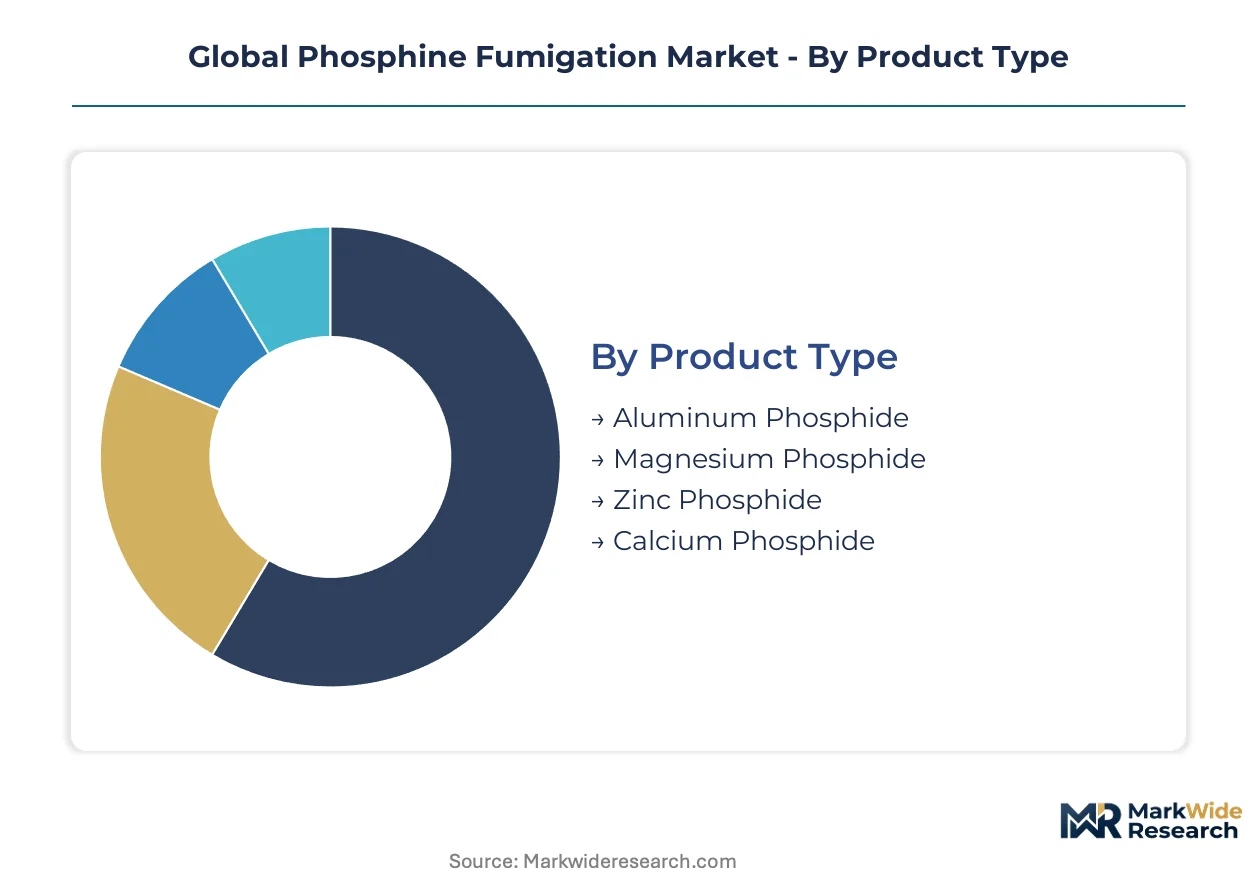
Phosphine fumigation markets fragment across formulation chemistry, treatment setting, and customer procurement authority. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape supplier positioning.
Product Type:
Volume leadership sits with aluminum phosphide, while premium chemistry migrates toward magnesium formulations under tightening residue regimes.
- Aluminum Phosphide:Tablet and pellet formulations generate hydrogen phosphide through moisture-activated hydrolysis, delivering 200-1000 ppm lethal concentrations across 72-hour exposure windows. Cereal processors in India and Brazil specify aluminum phosphide for cost-sensitive bulk grain treatments where established handling protocols minimize labor training burdens.
- Magnesium Phosphide:Controlled-release pellet technologies with membrane barriers enable cleaner degradation profiles that satisfy REACH documentation requirements with reduced ventilation cycles. German and French grain cooperatives specify magnesium phosphide formulations to compress aeration downtime and accelerate warehouse throughput.
- Zinc Phosphide:Rodenticidal applications dominate zinc phosphide consumption, with limited grain-storage deployment restricted to specific pest pressure scenarios.
- Calcium Phosphide:Industrial fumigation applications outside agricultural storage represent primary calcium phosphide demand, with minimal penetration into mainstream grain treatment protocols.
Mature deployment sits with aluminum phosphide. Newer deployment is concentrated in magnesium phosphide.
Application:
Facility type determines gas containment standards, aeration infrastructure, and regulatory inspection frequency.
- Stored Grains:Silo and warehouse bulk storage applications dominate phosphine consumption volume, with public-sector investment in emerging grain-exporting economies expanding concrete storage infrastructure. Ukrainian and Romanian port investments are driving mobile fumigation unit procurement for containerized export corridors.
- Warehouses:Post-harvest loss reduction mandates across government storage networks are accelerating warehouse sealing upgrades to meet gas retention compliance standards. Concrete silo retrofit costs remain a capital constraint across public-sector storage networks in India and Brazil.
- Ship Holds:Maritime fumigation during voyage requires specialized circulation equipment and crew safety protocols that elevate service provider certification requirements.
- Food Processing Plants:EPA tolerance revisions for processed foods are forcing segregation of phosphine-treated grain streams earlier in manufacturing to prevent cross-contamination into breakfast cereal and snack segments.
- Tobacco Storage:Cured leaf warehouses in tobacco-producing regions maintain distinct fumigation specifications due to moisture sensitivity and residue absorption characteristics.
Volume concentrates in stored grains. Fastest expansion is occurring in warehouses.
End User:
Procurement authority is consolidating among multinational grain traders who mandate standardized fumigation documentation across origin ports.
- Cereal Processors:Domestic millers in India are securing export-grade treatment contracts as FSSAI aligns phosphine residue limits with Codex Alimentarius standards.
- Grain Exporters:Australian and Brazilian exporters are adopting digital certificate platforms integrating phosphine treatment records with blockchain traceability systems for Chinese customs compliance.
- Pest Control Operators:OSHA-mandated respiratory protection training creates labor pool constraints, extending service deployment timelines during peak harvest windows.
- Logistics Providers:Third-party verification services are expanding to meet buyer consolidation demands among multinational grain traders.
Contracting authority is centralizing with grain exporters. Service provider capacity constraints concentrate among pest control operators.
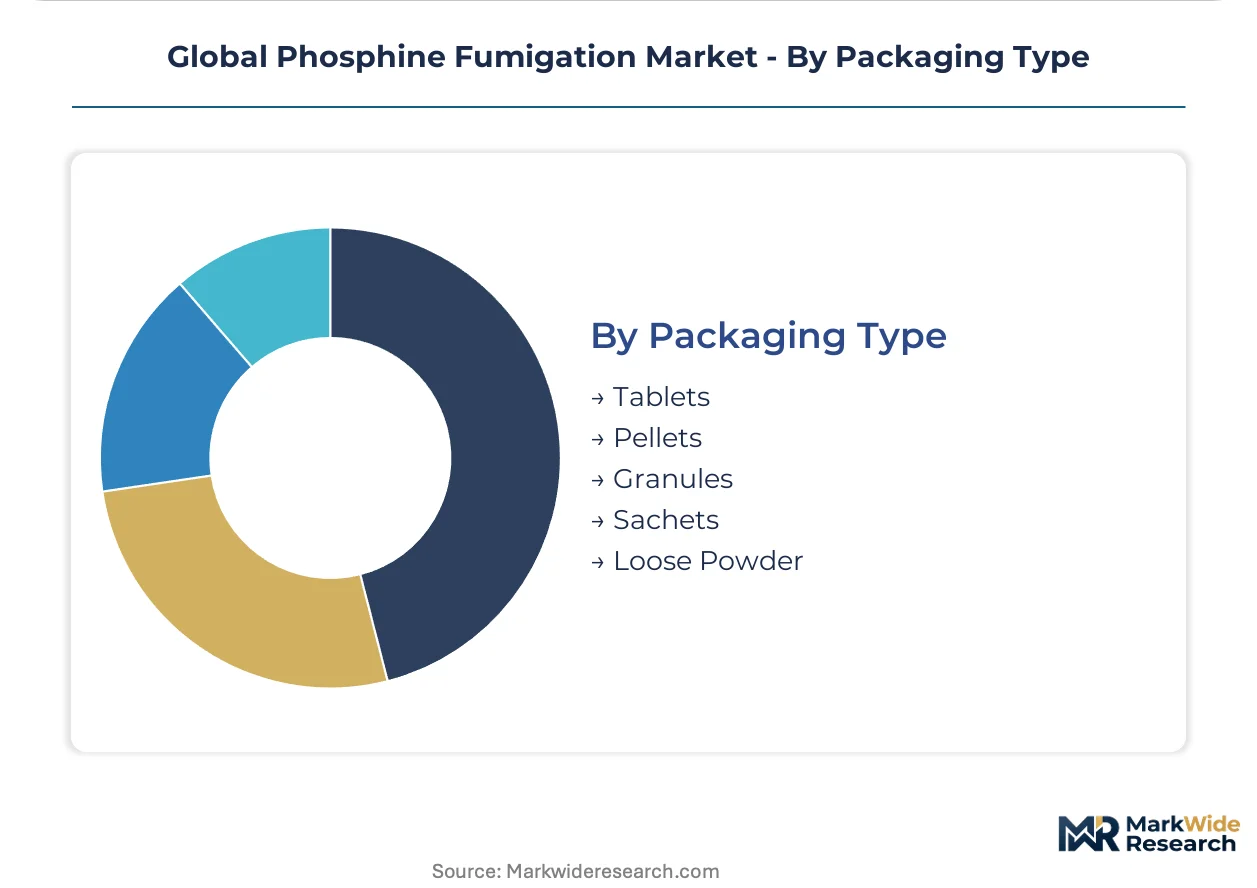
Packaging Type:
Form factor selection trades labor exposure reduction against dispensing automation capital requirements.
- Tablets:Australian bulk elevators are deploying automated dispensing systems that maintain concentration bands while cutting direct labor exposure to phosphine gas.
- Pellets:Controlled-release pellet formats with membrane barriers are penetrating European facilities seeking REACH compliance with fewer ventilation cycles.
- Granules:Surface-area-optimized granule formulations accelerate gas generation kinetics for rapid treatment initiation in time-compressed export windows.
- Sachets:Pre-measured sachet formats reduce weighing errors and applicator exposure in small-scale storage operations.
- Loose Powder:Bulk powder applications persist in specialized industrial fumigation outside agricultural grain storage protocols.
Automation investment is concentrating in tablets. Formulation innovation is migrating toward pellets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Santos and Paranaguá anchor Latin American phosphine logistics concentration, while Black Sea port investments and Indian grain belt infrastructure create complementary demand poles across three continents.
United States
EPA-registered formulation manufacturing concentrates in Gulf Coast chemical corridors, with OSHA-mandated respiratory protection training constraining applicator labor pools during peak harvest windows. The agency's 2024 tolerance revisions for processed foods force segregation protocols in breakfast cereal manufacturing. Houston and New Orleans host bulk chemical precursor import terminals serving domestic tablet production.
Brazil
Santos port authorities mandate phosphine certificates for soybean and corn shipments, institutionalizing pre-shipment fumigation services for Chinese export contracts. ANVISA alignment with international residue standards accelerates formulation registration timelines. Paranaguá's grain terminal operators deploy mobile fumigation units for containerized cargo compliance.
Germany
REACH classification rules restrict certain formulation chemistries and mandate exposure documentation across grain cooperative networks. ECHA's downward revision of phosphine tolerance thresholds drives magnesium phosphide adoption with cleaner degradation profiles. Bavarian bulk storage facilities lead membrane-controlled release pellet deployment.
India
FSSAI alignment of phosphine residue limits with Codex Alimentarius standards opens export-grade treatment contracts for domestic millers in Punjab and Haryana. Central Insecticides Board registration renewals now require expanded toxicology dossiers, extending approval cycles. Gujarat's chemical manufacturing clusters supply aluminum phosphide precursors to South Asian distribution networks.
Australia
Automated dispensing systems in Queensland and New South Wales bulk elevators cut labor exposure while maintaining 200-1000 ppm concentration bands. Biosecurity protocols at Brisbane and Sydney destination ports standardize treatment documentation for Asian grain buyers. TGA oversight of agricultural chemical safety frames applicator certification requirements.
Global Phosphine Fumigation Market Competitive Landscape
Top-tier vendors anchor EPA and REACH-compliant formulation manufacturing, while regional distributors and service operators occupy specialized niches in port logistics and warehouse automation. The competitive terrain splits between chemical producers with precursor supply control and application service providers with certified labor networks. Two dominant archetypes emerge: integrated agrochemical conglomerates with multi-jurisdictional registration portfolios, and fumigation service specialists with port authority relationships. Capacity expansion in magnesium phosphide pellet production and strategic partnerships for digital certificate platform integration represent the primary competitive vectors.
Within the integrated agrochemical tier, UPL Limited and BASF SE occupy positions spanning formulation manufacturing through distribution network control. Degesch America Inc exemplifies the North American manufacturing specialist archetype, while Solvay Group represents European REACH-compliant production capabilities. Detia Degesch GmbH anchors German-engineered phosphide technology heritage. These entities collectively illustrate how regulatory registration breadth and precursor supply security determine competitive positioning across the three major grain-exporting jurisdictions.
| Leading Market Players |
|---|
| UPL Limited |
| Degesch America Inc |
| Solvay Group |
| Detia Degesch GmbH |
| Nufarm Limited |
| BASF SE |
| ADAMA Agricultural Solutions Ltd. |
| Rentokil Initial Plc |
| AMVAC Chemical Corporation |
| Others |
Supply & Pricing Matrix
REACH classification rules for phosphine residue documentation gate qualified supply access and premium-tier pricing power across European grain cooperative networks. ECHA's downward tolerance revisions compress formulation upgrade cycles, forcing buyers toward magnesium phosphide pellets with cleaner degradation profiles that command 15-20% price premiums over aluminum phosphide tablets.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency spot purchases from contracted annual volumes across Brazilian and Australian export corridors. Premium-mid-economy pricing differentiation rests on certification grade (EPA-registered versus REACH-compliant) and after-sales service bundling with digital certificate platforms. Cost compression in aluminum phosphide tablets is intensifying because Chinese precursor supply constraints limit manufacturing flexibility. Cereal processors in India's grain belt states exhibit highest price sensitivity, while multinational grain traders in Santos and Paranaguá prioritize documentation reliability over unit cost.
Supply Chain Analysis
Reverse-logistics for spent phosphide formulations and contaminated packaging materials adds regulatory compliance layers to distribution economics across European bulk storage networks. Manufacturing concentrates in China for aluminum phosphide precursors, India for tablet finishing and South Asian distribution, and Germany for magnesium phosphide pellet engineering with membrane-controlled release technology. Active ingredient production draws from concentrated phosphine gas precursor availability, specialized pellet extrusion equipment, and REACH-compliant membrane materials. Single-source vulnerability in Chinese chemical supply creates structural exposure for EPA-registered formulation manufacturers. Distribution runs through agrochemical distribution networks anchored by UPL Limited in South Asia and Degesch America in North American Gulf Coast corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into phosphine gas precursor manufacturing represents the decisive upstream lever in this market's vertical-integration race. Control over concentrated chemical supply from Chinese and Indian manufacturing clusters separates margin-defensible suppliers from formulation-assemblers exposed to input volatility.
For Market Incumbents: Deepen captive supply arrangements with Chinese phosphide precursor manufacturers to secure EPA registration maintenance amid active ingredient concentration bottlenecks. Expand magnesium phosphide pellet capacity in Bavarian bulk storage corridors to capture REACH-driven formulation upgrade demand. Defensive consolidation through digital certificate platform partnerships protects against blockchain-traceability mandates at Chinese customs ports. For New Entrants and Emerging Players: Direct-to-exporter digital channels bypass established agrochemical distribution networks concentrated with UPL Limited and BASF SE. Target mobile fumigation unit deployment for Ukrainian and Romanian Black Sea port infrastructure investments as the most penetrable geography. White-space capture in third-party verification services for FSSAI-aligned residue documentation offers service-based entry with lower capital barriers than formulation manufacturing. For Investors and Strategic Acquirers: ECHA's downward revision of phosphine tolerance thresholds in stored cereals is the leading indicator that magnesium phosphide formulation specialists will command acquisition premiums over aluminum phosphide commodity producers. Long-term viability over the next decade favors REACH-compliant production capabilities with membrane-controlled release patent positions. Acquisition target archetype: German-engineered pellet technology specialists with established grain cooperative relationships. Monitor EPA tolerance revision patterns for processed foods as early signal of downstream segregation protocol demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive phosphine gas supply secures EPA registration continuity for aluminum phosphide tablet producers. |
| Magnesium Phosphide Pellet Capacity Expansion | REACH-compliant membrane-controlled release formats capture ECHA-driven formulation upgrade demand in European cooperatives. |
| Digital Certificate Platform Integration | Blockchain-traceability documentation satisfies Chinese customs mandates for soybean and corn shipment acceptance. |
| Mobile Fumigation Unit Deployment | Containerized grain export corridors in Ukrainian and Romanian ports create equipment demand pull. |
| Third-Party Verification Service Buildout | FSSAI-Codex alignment in India opens residue testing contracts for domestic miller export-grade treatments. |
Research Methodology
Document review covered EPA tolerance exemption filings, ECHA REACH registration dossiers, FSSAI residue limit notifications, and Central Insecticides Board registration records, complemented by interviews with formulation manufacturing plant managers, grain cooperative procurement leads, pest control operator service directors, and port logistics compliance officers. Secondary validation drew from customs and trade data for phosphide precursor movements, SEC 10-K disclosures from listed agrochemical conglomerates, and ANVISA formulation registration timelines. Bottom-up demand modeling for aluminum and magnesium phosphide consumption triangulated against top-down grain export volume projections.
Segment-level value and volume estimates across the projection horizon reflect disaggregated modeling by formulation chemistry, treatment facility type, and end-user procurement authority. The analytical framework incorporated grain storage infrastructure investment flows, biosecurity mandate adoption curves at destination ports, and applicator certification training capacity constraints. CAGRs were derived from regression analysis of historical formulation shipment data against grain export volume elasticities, with scenario weighting for regulatory alignment events.
The model holds under stable REACH and EPA regulatory trajectories; deviation in ECHA tolerance revision timing or FSSAI enforcement intensity would shift magnesium phosphide adoption curves. Forecasts reflect assumptions regarding Chinese precursor supply continuity and Black Sea port infrastructure completion schedules. Practitioners should monitor EPA processed food tolerance exemption proceedings and Ukrainian grain export corridor operational status for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Miticides Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
South America Insecticide Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Specialty Pesticides Market
Crop Protection
South America Acaricides Market
Crop Protection
Tebufenozide Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Global Insecticides Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Grape Fungicides Market
Crop Protection
Crop Bactericides Market
Crop Protection
Global Acaricides Market