
 Grain Fumigants Market | 2026-2036
Grain Fumigants Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Fumigants Market Analytics
The capital-intensity divergence between integrated formulators and regional distributors is redrawing competitive boundaries in grain protection chemistry. BASF SE leverages its global manufacturing footprint to sustain cost advantages in phosphine tablet production. Detia Degesch GmbH anchors its position through specialized expertise in aluminum phosphide formulations. UPL Limited competes across multiple geographies with diversified agrochemical portfolios.
Grain fumigants are volatile or gaseous biocidal compounds, typically containing aluminum or magnesium phosphide, sulfuryl fluoride, or methyl bromide, applied at concentrations measured in parts per million to eliminate insect infestations in stored commodities. Their primary industrial purpose is to protect cereal and oilseed inventories from post-harvest pest damage during extended storage cycles. Phosphine formulations dominate volume demand due to established efficacy against phosphine-resistant beetle populations, while sulfuryl fluoride captures premium positioning in structural fumigation applications where residue restrictions tighten. Warehouse treatment applications generate the most stable revenue base, whereas commodity storage for export trade offers faster growth as quarantine standards multiply.
The EPA regulates fumigant tolerances and applicator certification under FIFRA, while the USDA enforces phytosanitary protocols for interstate and export grain movements. Health Canada and the PMRA impose parallel residue limits that shape North American product registration strategies. Stakeholders must monitor evolving resistance management mandates and alternative chemistry approval timelines to align R&D portfolios with regulatory trajectories.
Market Dynamics
Phosphine resistance spreading through stored-product insect populations is forcing formulators to accelerate combination-chemistry development and recalibrate application protocols across commercial grain elevators.
Growth Catalysts
- Export quarantine mandates:The USDA enforces phytosanitary certification for international grain shipments, compelling elevator operators to maintain continuous fumigation coverage.
- Sulfuryl fluoride transition:EPA phase-down schedules under the Montreal Protocol redirect procurement toward alternatives approved for structural treatment in food-handling facilities.
- Aluminum phosphide tablet automation:Precision-dispensing systems in high-capacity silos reduce labor exposure while maintaining efficacy against resistant beetle strains.
Market Restraints
- Active ingredient concentration:Chinese and Indian manufacturers control over 70% of raw aluminum phosphide supply, creating geographic vulnerability in upstream sourcing.
- Applicator certification scarcity:EPA-mandated FIFRA credentialing limits expand slowly relative to facility operator demand across the Corn Belt.
- Residue tolerance compression:EFSA and Health Canada PMRA ratchet down maximum residue limits faster than reformulation cycles can accommodate.
Strategic Opportunities
- Brazilian export infrastructure:Port terminal expansion along the Santos corridor creates demand for containerized fumigation services meeting ANVISA import standards.
- Carbon credit stacking:Phosphine's lower global warming potential versus methyl bromide positions certified users for EU Green Deal transition financing mechanisms.
- Remote monitoring integration:IoT sensor networks paired with automated tablet release systems enable outcome-based service contracts with indemnity guarantees.
Industry Challenges
- Toxicology specialist recruitment:Industrial hygienist and certified applicator pipelines lag facility expansion timelines across Kansas, Nebraska, and Iowa.
- Legacy equipment retrofit costs:Concrete silo sealing and ventilation upgrades required for sulfuryl fluoride compatibility strain regional distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Fumigants Market |
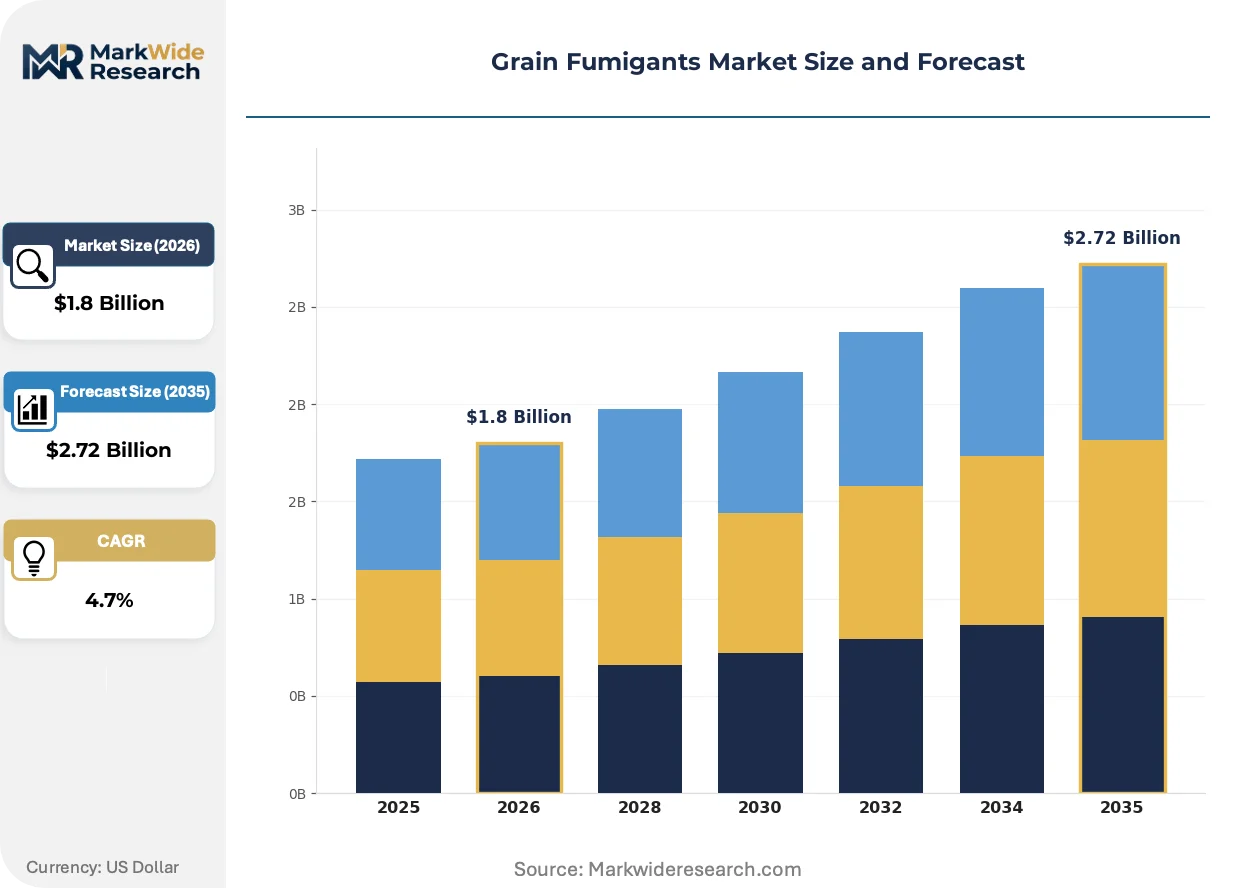
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphine, Methyl Bromide, Sulfuryl Fluoride, Carbon Dioxide Application: Warehouse Treatment, Soil Fumigation, Commodity Storage, Structural Fumigation End User: Agricultural Producers, Importers, Exporters, Food Processing Companies Formulation: Liquid, Gas, Solid, Aerosol |
| Companies Covered | UPL Limited, Detia Degesch GmbH, Douglas Products, Solvay, Corteva Agriscience, ECOTEC Fumigation, BASF SE, Noble Crop Science, Cardinal Professional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Fumigants Market Evolving Landscape
Formulation chemistry and application hardware are diverging sharply between commodity grain protection and high-value specialty crop storage, with regulatory pressure accelerating both tracks simultaneously.
Controlled-release phosphine generation is bifurcating the warehouse treatment segment. Large-scale cooperatives in Illinois and Indiana adopt magnesium phosphide-based sachet systems for extended 21-day exposure cycles. Small-to-mid elevators retain rapid-response aluminum phosphide tablets, compressing vendor margins on standardized product lines.
REACH authorization timelines under the EU Green Deal force European formulators to submit complete toxicology dossiers for phosphine precursors by 2027. BASF and Detia Degesch accelerate aluminum phosphide purity upgrades to preempt restriction scenarios. Export-oriented US elevators face parallel pressure as EU grain buyers demand residue documentation aligned with EFSA guidance.
Certification-driven procurement now dominates contract negotiations between regional distributors and facility operators. Third-party applicator credentials from the National Pest Management Association displace informal supplier relationships in Ohio and Missouri. This shift concentrates purchasing authority with agricultural cooperative procurement officers rather than individual elevator managers.
Grain Fumigants Market Segmentation
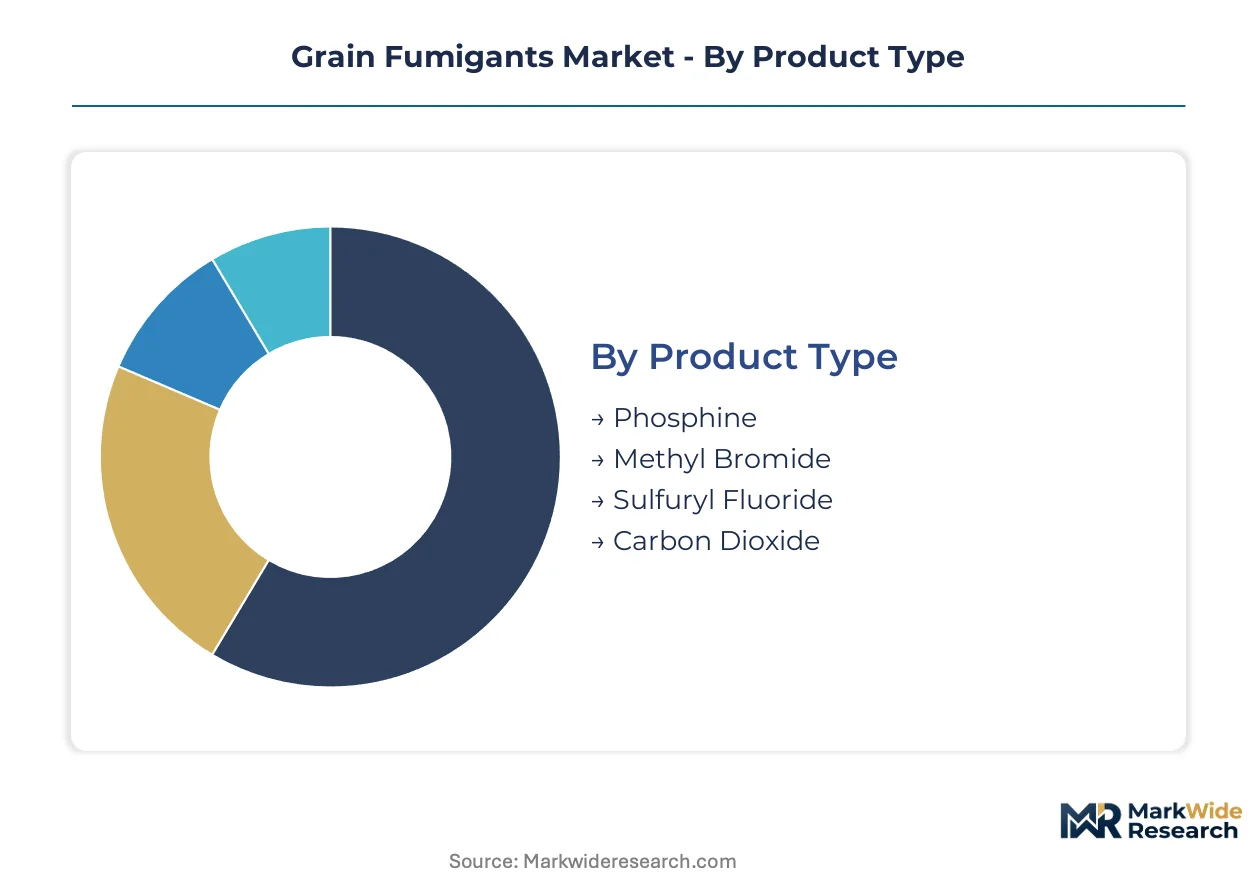
Grain fumigant procurement patterns diverge sharply between bulk commodity handlers and specialty crop operators, with formulation choices and application methods determining both regulatory compliance paths and operational cost structures across storage facility networks.
Product Type:
Margin pools concentrate in phosphine-based formulations where established efficacy against resistant pest populations commands premium positioning, while sulfuryl fluoride captures structural treatment premiums amid methyl bromide phase-down pressures.
- Phosphine:Aluminum and magnesium phosphide formulations generate gaseous hydrogen phosphide upon moisture contact, achieving lethal concentrations in sealed silo environments. Agricultural cooperatives across Illinois and Indiana deploy precision-dispensing systems for 21-day exposure cycles against phosphine-resistant beetle strains.
- Sulfuryl Fluoride:This colorless, odorless gas penetrates structural voids and wooden commodities without leaving surface residues, satisfying EPA tolerances for food-handling facility treatments. Port terminal operators along the Santos corridor specify sulfuryl fluoride for containerized export grain meeting ANVISA import standards.
- Methyl Bromide:Ozone-depleting properties trigger Montreal Protocol phase-down schedules; residual demand concentrates in quarantine pre-shipment treatments where alternatives lack registration.
- Carbon Dioxide:Inert gas systems displace oxygen in hermetic storage configurations, appealing to organic certification holders and carbon credit-seeking operators under EU Green Deal frameworks.
The dominant share belongs to phosphine formulations, while sulfuryl fluoride is closing the gap fastest.
Application:
Volume distribution tracks grain flow infrastructure, with warehouse and commodity storage commanding stable recurring revenue while structural and soil applications face steeper regulatory headwinds.
- Warehouse Treatment:Continuous pest management protocols in commercial grain elevators generate the most predictable revenue base, with automated tablet release systems reducing labor exposure across high-capacity silo complexes.
- Commodity Storage:Export-oriented facilities face multiplying quarantine certification requirements from USDA phytosanitary mandates and EU buyer residue documentation demands.
- Soil Fumigation:Pre-plant pest suppression in specialty crop production encounters tightening EPA buffer zone restrictions and township-level usage caps.
- Structural Fumigation:Food processing facility treatments require sulfuryl fluoride compatibility upgrades to concrete sealing and ventilation systems, straining regional distributor capital deployment.
Warehouse treatment captures the largest volume position, though commodity storage for export trade shows the steepest expansion trajectory.
End User:
Procurement authority is shifting from individual elevator managers toward centralized agricultural cooperative officers as third-party certification requirements displace informal supplier relationships.
- Agricultural Producers:Commercial grain storage facilities in the Corn Belt states of Kansas, Nebraska, and Iowa drive phosphine tablet demand through integrated cooperative networks.
- Exporters:Elevator operators serving international markets must maintain continuous fumigation coverage to satisfy USDA phytosanitary certification for grain shipments.
- Importers:Port terminal receiving operations face ANVISA, EFSA, and Health Canada PMRA residue limit compliance depending on destination market specifications.
- Food Processing Companies:Structural treatment requirements for milling and handling facilities redirect procurement toward sulfuryl fluoride alternatives approved under EPA FIFRA tolerances.
Agricultural producers command the dominant procurement volume, while exporters are gaining share fastest as quarantine standards multiply.
Formulation:
Physical state determines application equipment requirements, labor exposure profiles, and regulatory handling classifications across facility operator segments.
- Solid:Aluminum phosphide tablets and magnesium phosphide sachets enable precision dosing in automated dispensing systems, with controlled-release formulations extending exposure cycles for resistant pest management.
- Gas:Sulfuryl fluoride and phosphine gas cylinders require specialized applicator certification under EPA FIFRA mandates, creating capability scarcity relative to facility expansion timelines.
- Liquid:Limited penetration in grain protection due to residue adherence concerns; concentrates primarily in soil fumigation applications with buffer zone compliance requirements.
- Aerosol:Niche positioning for spot treatments and emergency response protocols in small-to-mid elevator operations lacking full fumigation infrastructure.
Solid formulations hold the dominant position, while gas formulations are climbing the fastest as structural treatment demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across storage facility tiers. Large-scale cooperatives in the United States Corn Belt negotiate volume contracts aggressively. Premium positioning concentrates in export terminals facing stringent residue documentation requirements.
United States
Commercial grain elevators across Kansas, Nebraska, and Iowa drive phosphine tablet procurement through integrated cooperative networks. EPA FIFRA mandates require certified applicator credentials that lag facility expansion timelines. Automated dispensing systems in high-capacity silo complexes reduce labor exposure while maintaining efficacy protocols.
Brazil
Port terminal expansion along the Santos corridor generates containerized fumigation demand meeting ANVISA import standards. The country's national agricultural regulator enforces residue limits that redirect procurement toward sulfuryl fluoride alternatives. São Paulo-based grain handlers invest in sealing infrastructure compatible with structural treatment requirements.
Germany
REACH authorization timelines under the EU Green Deal force formulators to submit complete toxicology dossiers for phosphine precursors by 2027. EFSA guidance on maximum residue limits shapes export documentation demanded by EU grain buyers. BASF SE leverages manufacturing scale in Ludwigshafen to sustain cost advantages in tablet production.
Canada
Prairie province grain handlers face Health Canada PMRA residue limits that compress tolerance thresholds faster than reformulation cycles accommodate. The regulator's phytosanitary protocols for export shipments compel continuous fumigation coverage. Manitoba and Saskatchewan elevator operators consolidate procurement authority through cooperative purchasing officers.
India
Domestic aluminum phosphide manufacturing concentrates in Gujarat and Maharashtra, supplying raw material to regional formulators. FSSAI food safety standards intersect with DGFT export requirements to shape product registration strategies. Mumbai port terminals require ANVISA-compliant documentation for grain shipments bound for Brazilian markets.
Grain Fumigants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in grain protection chemistry. The market structure consolidates around integrated multinational formulators with captive raw material access and specialized regional distributors with application expertise. Two strategic archetypes dominate: global manufacturers leveraging scale economies in phosphine production, and regional service providers bundling certification-driven applicator networks. Competitive moves concentrate on backward integration into aluminum phosphide precursors and geographic expansion through distributor acquisition.
Among the integrated multinational tier, BASF SE and Solvay occupy positions anchored by manufacturing scale and diversified chemical portfolios. Detia Degesch GmbH exemplifies the specialized formulator archetype, with organizational structure reflecting concentrated expertise in phosphine-based formulations. UPL Limited sits within the diversified agrochemical conglomerate category, competing across multiple geographies through portfolio breadth rather than category-specific depth.
| Leading Market Players |
|---|
| UPL Limited |
| Detia Degesch GmbH |
| Douglas Products |
| Solvay |
| Corteva Agriscience |
| ECOTEC Fumigation |
| BASF SE |
| Noble Crop Science |
| Cardinal Professional Products |
| Others |
Value Network & Pricing Analysis
Take-or-pay contracts between Corn Belt agricultural cooperatives and phosphine tablet manufacturers lock in multi-year supply access while capping price volatility exposure. These arrangements concentrate procurement authority with large-scale elevator operators who negotiate volume commitments against automated dispensing system installations.
Pricing Analysis
After-sales service contracts covering applicator certification renewal and automated system maintenance drive lifetime value for integrated formulators. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified precision-dispensing packages from basic tablet supply. Price differentiation hinges on certification grade and volume scale, with agricultural cooperatives commanding steepest discounts. Cost compression in standard-tier tablet supply is intensifying because Chinese aluminum phosphide manufacturers expand direct export channels. Small-to-mid elevators in Ohio and Missouri show highest price sensitivity, while export terminals facing ANVISA documentation requirements absorb premium positioning.
Supply Chain Analysis
Port congestion along the Shanghai-Ningbo corridor and container availability constraints on the Asia-North America trade lane elevate inbound logistics costs for aluminum phosphide precursor shipments. Raw material supply concentrates in China, India, and Germany, with Gujarat and Maharashtra facilities feeding regional formulators across South Asia. The chain draws from aluminum phosphide precursors, magnesium phosphide sachet substrates, and sulfuryl fluoride gas cylinder fabrication. Single-source vulnerability in Chinese precursor manufacturing exposes distributors to export license disruptions. Distribution runs through agricultural cooperative procurement officers who consolidate purchasing authority across Kansas, Nebraska, and Iowa elevator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where IoT sensor networks and automated tablet release systems enable outcome-based service contracts with indemnity guarantees, shifting value capture from product supply to integrated pest management platforms.
For Market Incumbents: Shield phosphine formulation margins by accelerating backward integration into aluminum phosphide precursor manufacturing before Chinese export channels consolidate further. Invest in EPA FIFRA certification infrastructure to capture applicator credential scarcity premiums across the Corn Belt. Priority defensive moves center on automated dispensing system deployment and magnesium phosphide sachet line expansion for 21-day exposure cycle demand. For New Entrants and Emerging Players: EPA FIFRA fast-track certification for sulfuryl fluoride structural treatment applications opens white-space access in food processing facility segments where residue restrictions tighten fastest. Target port terminal operators along Brazilian Santos corridor expansion zones where ANVISA compliance documentation creates service bundling opportunities. Go-to-market positioning should emphasize containerized fumigation service contracts with remote monitoring integration. For Investors and Strategic Acquirers: Capital is best deployed toward specialized regional distributors with captive applicator networks and certification-driven procurement relationships. Long-term viability over the five-to-ten year window rests on positioning for phosphine resistance management protocols and combination-chemistry development pipelines. The critical signal to watch is EFSA maximum residue limit compression velocity relative to reformulation cycle timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captures cost advantages in aluminum phosphide supply chains dominated by Chinese and Indian producers. |
| Automated Dispensing System Deployment | Reduces labor exposure liability while locking in multi-year service contracts with Corn Belt cooperatives. |
| EPA FIFRA Certification Infrastructure Buildout | Addresses applicator credential scarcity constraining facility expansion across Kansas, Nebraska, and Iowa. |
| Remote Monitoring Platform Integration | Enables outcome-based service contracts with indemnity guarantees for phosphine-resistant pest management. |
| Magnesium Phosphide Sachet Line Expansion | Captures 21-day exposure cycle demand from Illinois and Indiana cooperatives managing resistant beetle strains. |
Research Methodology
A standing panel of grain elevator operations managers, agricultural cooperative procurement officers, EPA-certified fumigation applicators, and phosphine formulation technical directors provided ongoing calibration across primary research phases. Secondary validation drew from USDA phytosanitary certification databases, EPA FIFRA registration filings, Health Canada PMRA residue limit publications, and customs trade data tracking aluminum phosphide precursor flows. Bottom-up facility-level demand modeling triangulated against top-down chemical consumption estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented demand by formulation chemistry, application method, physical state, and end-user procurement authority structure. CAGRs were derived from fitted growth curves incorporating export quarantine mandate expansion, Montreal Protocol phase-down schedules, and phosphine resistance management protocol adoption rates. Industry-specific inputs included elevator capacity expansion timelines and certified applicator pipeline constraints.
Underlying assumptions cover regulatory approval continuity for phosphine-based formulations, with deviation risk concentrated in EFSA and Health Canada PMRA residue tolerance compression velocity. Forecasts reflect documented conditions regarding Montreal Protocol implementation schedules and EPA FIFRA credentialing expansion rates. Practitioners should keep alternative scenarios live as EU Green Deal REACH authorization timelines and Brazilian ANVISA import standard evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
South America Nematicides Market
Crop Protection
China Fungicide Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Tebuconazole Market
Crop Protection
US Insecticide Market
Crop Protection
South America Molluscicides Market
Crop Protection
Grain Protectant Market
Crop Protection
Pest Control Services Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Corn Preemergence Herbicide Market