
 Sustainable Crop Protection Chemicals Market | 2026-2036
Sustainable Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Crop Protection Chemicals Market Analytics
Biological active ingredient concentration tiers above 20 percent AI is rotating purchasing criteria away from legacy synthetic formulations. Bayer CropScience leverages its fermentation platform in Germany to sustain supply of high-purity spinosad variants. BASF SE anchors European distribution through backward integration into microbial strain libraries. Syngenta AG competes in emerging markets with localized production of Bacillus thuringiensis formulations.
Sustainable crop protection chemicals comprise biologically derived or nature-identical active substances formulated to manage agricultural pests, diseases, and weeds with reduced environmental load, typically requiring fermentation, extraction, or semi-synthesis to achieve specified purity thresholds above 85 percent. These agents serve commercial agriculture by suppressing pest pressure while preserving pollinator populations and soil microbiome integrity. Biopesticides command the deepest margin pools as farmer willingness-to-pay escalates for residue-compliant export crops. Bioinsecticides represent the fastest-expanding category as lepidopteran resistance to synthetic pyrethroids widens adoption windows in soybean and cotton systems. Natural herbicides remain structurally constrained by narrower weed spectrum and higher per-hectare application rates relative to glufosinate alternatives.
EPA biopesticide registration under FIFRA Section 3(c)(5) and EU Green Deal Farm-to-Fork pesticide reduction targets are converging to compress synthetic chemistry timelines while accelerating biological product dossier reviews. India's Central Insecticides Board mandates separate biopesticide efficacy protocols that extend market access timelines for foreign registrants. REACH compliance costs for imported microbial strains are reshaping European supply configurations toward domestic fermentation assets. Stakeholders must calibrate R&D portfolios against divergent regulatory clock speeds rather than harmonized global standards.
Market Dynamics
Biological active ingredient concentration thresholds above 20 percent AI are rotating procurement criteria away from legacy synthetic formulations across commercial agriculture. This technical specification shift is compressing supply chains toward fermentation-capable manufacturers while fragmenting distribution networks previously anchored by synthetic chemistry majors.
Growth Catalysts
- EPA biopesticide registration acceleration:FIFRA Section 3(c)(5) dossier reviews are compressing approval timelines for microbial strains, enabling faster market entry for fermentation-derived insecticides.
- Farmer cooperative IPM pilots:Brazil's soybean belt cooperatives are scaling bioinsecticide-biofungicide cocktail applications, demonstrating field efficacy at commercial scale.
- EU Green Deal Farm-to-Fork targets:Pesticide reduction mandates are forcing synthetic chemistry substitution with biological alternatives in export-oriented horticulture.
Market Restraints
- Fermentation feedstock cost volatility:Molasses and corn steep liquor prices fluctuate with commodity grain markets, compressing margin stability for microbial active ingredient producers.
- Strain library concentration:Proprietary Bacillus and Trichoderma strain collections concentrate among three German and Danish suppliers, creating supply vulnerability.
- India CIB efficacy protocol friction:Foreign registrants face extended field trial requirements that delay market access by 18-24 months versus domestic applicants.
Strategic Opportunities
- Punjab-Haryana rice-wheat corridor penetration:India's northwestern agricultural heartland remains underpenetrated by biological herbicides, offering first-mover positioning against glufosinate dominance.
- CRISPR-edited strain development:Precision genome editing of Bacillus thuringiensis variants is converging with automated fermentation control to yield novel toxicity profiles.
- Direct-to-farmer digital platforms:Agritech marketplaces are bypassing traditional agrochemical distributor networks, enabling biological product bundling with precision application services.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with GMP-compliant bioprocess experience command premium compensation, constraining mid-tier manufacturer expansion.
- REACH microbial strain compliance costs:European toxicity and environmental fate dossier requirements for imported strains are forcing supply chain reconfiguration toward domestic fermentation assets.
- Shelf-life stability under tropical storage:Bacillus-based formulations degrade rapidly above 35°C, requiring cold chain investments that clash with existing agrochemical distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Crop Protection Chemicals Market |
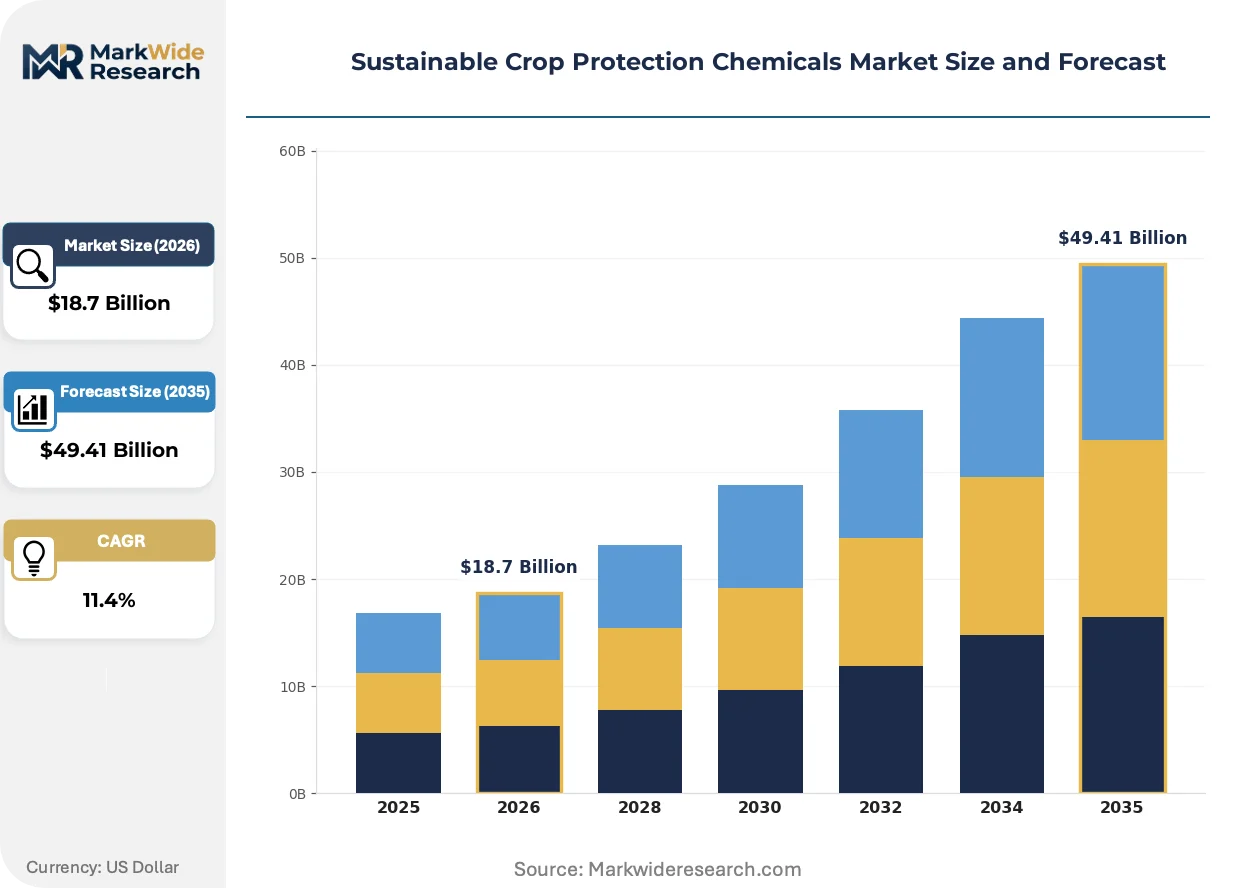
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofungicides, Biopesticides, Bioinsecticides, Natural Herbicides Application: Field Crops, Horticulture, Turf & Ornamental, Organic Farming End Use Industry: Agriculture, Organic Agriculture, Food Production, Commercial Farming Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Bayer CropScience, BASF SE, Syngenta AG, Corteva Agriscience, FMC Corporation, Marrone Bio Innovations, Valent BioSciences, Certis USA, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Crop Protection Chemicals Market Evolving Landscape
RNA interference and peptide-based modes of action are displacing conventional microbial fermentation as the frontier of biological pest control. These molecular platforms promise target specificity that preserves non-pest insect populations while meeting residue thresholds for premium export markets.
Precision fermentation of pheromone analogs is fragmenting the mating disruption segment previously dominated by synthetic chemistry. Orchard operators in Washington State and Catalonia are adopting these biodegradable formulations for codling moth management. The technology is fragmenting supplier power by enabling smaller biotech firms to achieve commercial scale without petrochemical infrastructure.
EU F-Gas Regulation phase-down schedules are accelerating investment in non-synthetic fumigation alternatives for stored grain protection. Warehouse operators face compliance deadlines that eliminate methyl bromide and phosphine options. Post-harvest biological treatments using diatomaceous earth and microbial antagonists are capturing share in Mediterranean port storage facilities.
Farmer willingness-to-pay for residue-compliant certification is compressing price sensitivity differentials between biological and synthetic alternatives. Export-oriented soybean producers in Mato Grosso are absorbing bioinsecticide premiums to secure EU and Japanese offtake agreements. This behavioral shift is most visible in contract farming arrangements where downstream buyers mandate active ingredient disclosure.
Sustainable Crop Protection Chemicals Market Segmentation
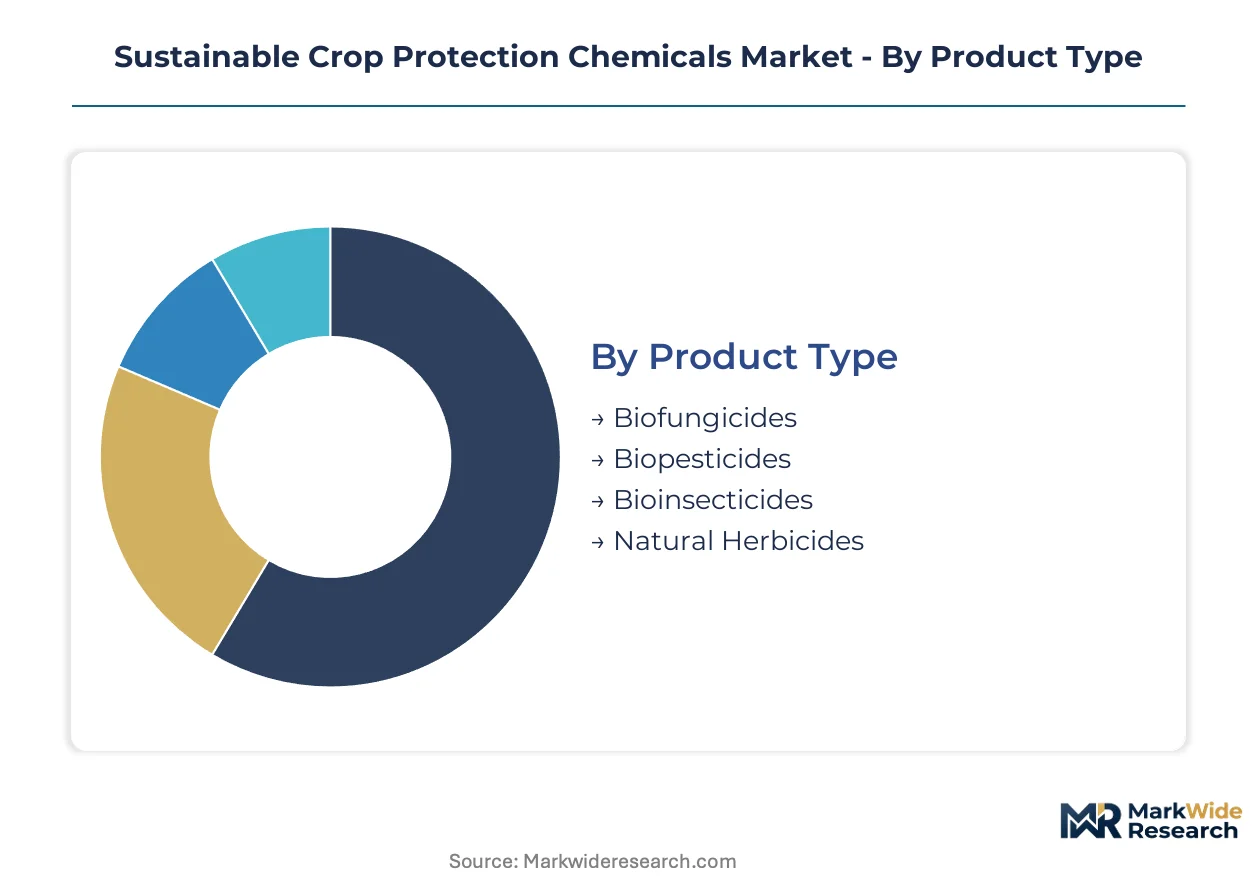
Sustainable crop protection chemicals fragment across multiple commercial axes, with regulatory pathways and farmer procurement behavior creating divergent margin profiles. Segmentation reveals where biological formulations command premium positioning versus commodity substitution pressure.
Product Type:
EPA biopesticide registration under FIFRA Section 3(c)(5) and EU Green Deal pesticide reduction targets are compressing synthetic chemistry timelines while accelerating biological dossier reviews, creating divergent market access speeds across product categories.
- Biopesticides:Fermentation-derived or nature-identical active substances with purity thresholds above 85 percent, encompassing microbial and biochemical pest management agents. Export-oriented soybean producers in Brazil's Mato Grosso absorb premiums to secure EU and Japanese offtake agreements under residue-compliant certification. Established volume favors biopesticides; emerging adoption favors bioinsecticides.
- Bioinsecticides:Target-specific agents derived from Bacillus thuringiensis, spinosad variants, and RNA interference platforms that suppress lepidopteran pests while preserving pollinator populations. Lepidopteran resistance to synthetic pyrethroids in soybean and cotton systems is expanding commercial adoption windows fastest.
- Biofungicides:Microbial antagonists and plant extract formulations managing fungal pathogens in high-value horticulture systems with reduced environmental load.
- Natural Herbicides:Botanically derived weed control agents constrained by narrower spectrum and higher per-hectare application rates versus glufosinate alternatives.
Margin concentration aligns with residue compliance requirements; biopesticides and bioinsecticides capture deepest pools while natural herbicides face structural cost disadvantages.
Application:
Farmer cooperative integrated pest management pilots are rotating procurement criteria across application segments, with commercial scale demonstrations in Brazil and India validating biological efficacy against synthetic benchmarks.
- Field Crops:Large-scale grain and oilseed production systems where bioinsecticide-biofungicide cocktails demonstrate field efficacy at commercial scale. Brazil's soybean belt cooperatives are scaling applications across millions of hectares, compressing price sensitivity differentials versus synthetic alternatives.
- Horticulture:High-value fruit and vegetable systems where EU Green Deal Farm-to-Fork targets force synthetic substitution fastest. Orchard operators in Washington State and Catalonia adopt precision-fermented pheromone analogs for codling moth management.
- Turf & Ornamental:Non-food agricultural applications with lower regulatory scrutiny but price-competitive synthetic alternatives.
- Organic Farming:Certified operations across North America and Western Europe expanding biological active ingredient procurement as EPA and EU frameworks tighten synthetic tolerances.
Commercial validation favors field crops; premium positioning favors horticulture.
End Use Industry:
Downstream buyer mandate patterns are fragmenting end-use demand, with contract farming arrangements increasingly requiring active ingredient disclosure and residue compliance certification.
- Agriculture:Conventional commercial farming operations transitioning biological agents into integrated pest management rotations. India's Punjab-Haryana rice-wheat corridor remains underpenetrated by biological herbicides, offering first-mover positioning against glufosinate dominance.
- Organic Agriculture:Certified operations commanding strict input compliance and willingness-to-pay premiums for export market access.
- Food Production:Vertically integrated agribusiness operations with downstream brand exposure mandating residue thresholds for consumer-facing products.
- Commercial Farming:Large-scale mechanized operations where digital agritech platforms enable direct-to-farmer biological product bundling with precision application services.
Input substitution favors agriculture; compliance premiums favor organic agriculture.
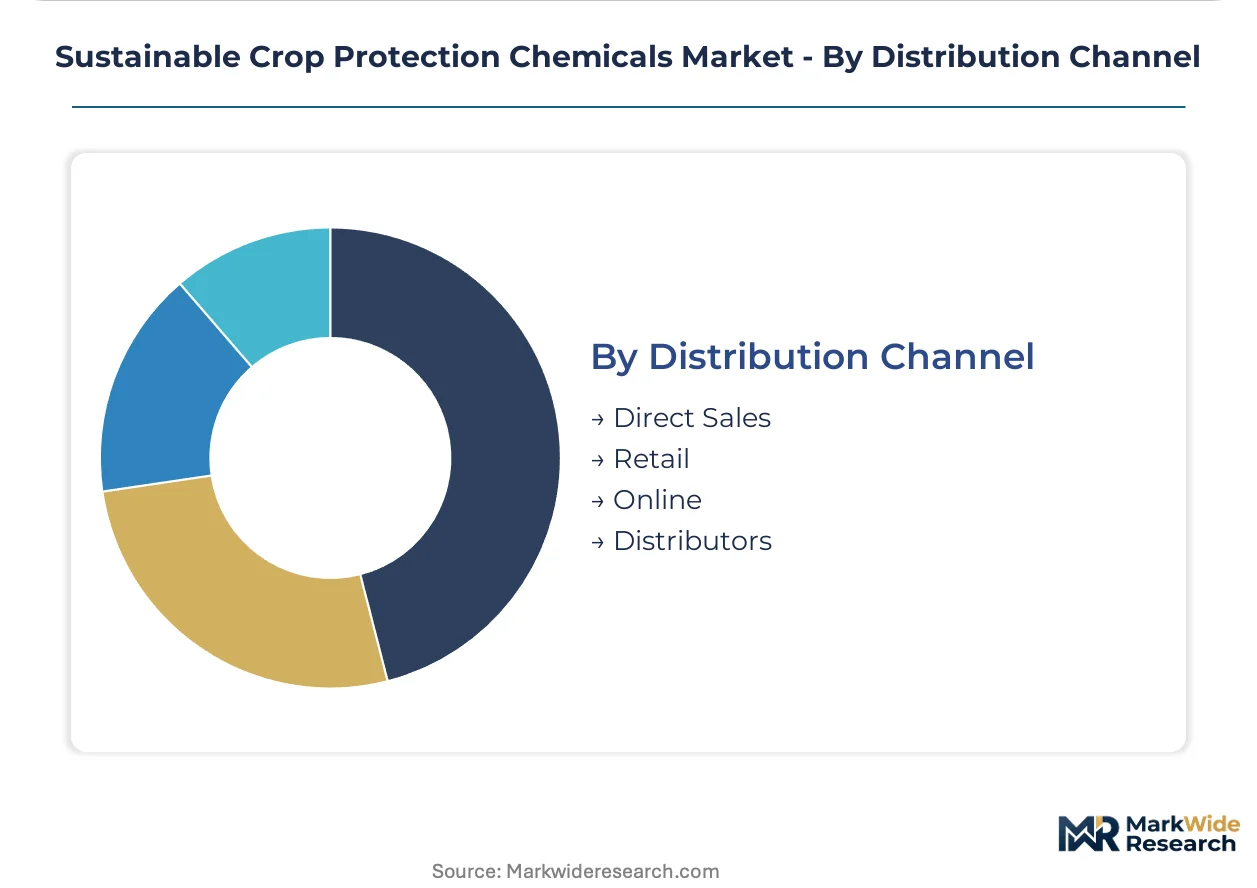
Distribution Channel:
Supply chain reconfiguration toward fermentation-capable manufacturers is fragmenting distribution networks previously anchored by synthetic chemistry majors, with digital platforms bypassing traditional agrochemical intermediaries.
- Direct Sales:Manufacturer-to-farmer relationships capturing margin pools in large-scale cooperative procurement. Agritech marketplaces enable biological product bundling with precision application services, displacing distributor markups.
- Distributors:Established agrochemical distribution networks facing cold chain investment requirements for Bacillus-based formulations degrading above 35°C, creating infrastructure friction against existing synthetic chemistry handling.
- Retail:Farm supply stores serving smaller-scale operations with limited biological product technical support capacity.
- Online:Emerging digital procurement channels with regulatory compliance documentation challenges for cross-border biological product shipments.
Relationship depth favors direct sales; reach expansion favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Brazilian soybean cooperatives absorb bioinsecticide premiums for EU export compliance, while Indian smallholders in the Punjab-Haryana corridor resist per-hectare cost increases against glufosinate benchmarks.
Brazil
Farmer cooperatives in Mato Grosso pilot bioinsecticide-biofungicide cocktails across millions of hectares. ANVISA registration pathways for microbial strains compress approval timelines versus synthetic alternatives. The Cerrado soybean belt anchors commercial-scale validation of biological efficacy at export-competitive costs.
United States
Orchard operators in Washington State adopt precision-fermented pheromone analogs for codling moth management. EPA biopesticide registration under FIFRA Section 3(c)(5) accelerates microbial strain dossier reviews. Midwest corn-soy systems remain price-sensitive, delaying biological herbicide substitution.
Germany
Bayer CropScience leverages domestic fermentation assets to sustain high-purity spinosad variant supply. EU Green Deal Farm-to-Fork pesticide reduction targets force synthetic chemistry substitution in export horticulture. Baden-Württemberg hosts concentrated microbial strain library infrastructure.
India
The Punjab-Haryana rice-wheat corridor remains underpenetrated by biological herbicides despite cooperative IPM pilots. Central Insecticides Board efficacy protocols extend foreign registrant timelines by 18-24 months versus domestic applicants. Maharashtra-based formulators struggle with tropical shelf-life stability above 35°C.
China
Yangtze River Delta fermentation capacity expands to serve domestic bioinsecticide demand. MEE environmental compliance frameworks tighten synthetic pesticide discharge tolerances. Shandong Province concentrates molasses feedstock supply for microbial active ingredient production.
Sustainable Crop Protection Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. The market structures around three tiers: integrated agrochemical majors with fermentation platforms, specialized microbial strain developers, and regional formulators serving price-sensitive geographies. Strategic moves concentrate on backward integration into strain libraries and geographic licensing partnerships to bypass extended registration timelines.
Among integrated majors, Bayer CropScience, BASF SE, and Syngenta AG occupy positions spanning fermentation assets to distribution networks. These players exemplify archetypes of platform-scale biological production versus synthetic chemistry legacy infrastructure. Their positioning reflects divergent bets on CRISPR-edited strain development versus automated fermentation control systems.
| Leading Market Players |
|---|
| Bayer CropScience |
| BASF SE |
| Syngenta AG |
| Corteva Agriscience |
| FMC Corporation |
| Marrone Bio Innovations |
| Valent BioSciences |
| Certis USA |
| Nufarm |
| Others |
Value Network & Pricing Analysis
EPA biopesticide registration under FIFRA Section 3(c)(5) and EU Green Deal Farm-to-Fork pesticide reduction targets simultaneously gate supplier qualification and enable price differentiation between residue-compliant biological formulations and synthetic alternatives. This dual-gating mechanism concentrates pricing power with fermentation-capable manufacturers while fragmenting procurement options for export-oriented growers.
Pricing Analysis
After-sales service contracts for precision application support and cold chain handling drive lifetime value beyond transactional product sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EU organic export certification commanding the widest premiums. Cost compression in standard-tier biopesticides is intensifying because Brazilian cooperatives negotiate collective procurement volumes. Smallholder operations in India's Punjab-Haryana corridor exhibit the highest price sensitivity, while Mato Grosso soybean exporters absorb premiums for Japanese offtake compliance.
Supply Chain Analysis
Just-in-time fermentation scheduling dominates microbial active ingredient production, though strategic stockpiling of molasses feedstock buffers commodity price spikes. Supply concentrates in Germany, Denmark, and China's Yangtze River Delta, where strain library infrastructure and fermentation capacity anchor production. Raw material dependencies include molasses, corn steep liquor, and proprietary Bacillus thuringiensis variants. Single-source vulnerability concentrates among three German and Danish strain library holders. Distribution runs through agricultural cooperatives and direct-to-farmer digital platforms that displace traditional agrochemical distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward farmer cooperatives and export-oriented contract farming arrangements that mandate active ingredient disclosure, consolidating procurement leverage previously fragmented across individual growers.
For Market Incumbents: Consolidate backward integration into microbial strain libraries to defend against CRISPR-edited strain developers eroding technical differentiation. Capture fermentation scale-up talent in Baden-Württemberg and Denmark through targeted compensation structures. Anchor distribution control through direct cooperative relationships that bypass legacy agrochemical intermediaries ill-equipped for cold chain requirements. For New Entrants and Emerging Players: Differentiate on tropical shelf-life stability formulations that address Maharashtra's 35°C storage degradation failures. Target India's Punjab-Haryana rice-wheat corridor biological herbicide white space before glufosinate incumbents adapt. Pursue digital marketplace bundling with precision application services as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial strain developers holding proprietary Trichoderma collections but lacking fermentation scale. Long-term viability hinges on regulatory clock speed arbitrage between EPA accelerated review and India CIB extended timelines. Watch for ANVISA registration pathway harmonization with EPA timelines as the inflection signal for Brazil market access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Libraries | Captures proprietary Bacillus and Trichoderma collections that concentrate among German and Danish suppliers. |
| Fermentation Capacity Expansion | Addresses industrial microbiologist talent scarcity constraining mid-tier manufacturer growth in EU markets. |
| Cold Chain Infrastructure Investment | Enables Bacillus-based formulation distribution above 35°C thresholds that degrade existing products. |
| Direct-to-Farmer Digital Platform Launch | Bypasses traditional agrochemical distributors through agritech marketplace bundling with precision services. |
| CRISPR-Edited Strain Development | Converges precision genome editing with automated fermentation control to yield novel toxicity profiles. |
Research Methodology
Desk research of EPA registration databases, EU Green Deal policy frameworks, and ANVISA approval records preceded structured interviews with fermentation plant managers, agricultural cooperative procurement leads, and microbial R&D directors. Primary fieldwork with distribution channel partners and regulatory affairs specialists validated secondary findings from customs trade data and agrochemical SEC filings. Bottom-up volume estimates triangulated against top-down market sizing across the projection horizon.
Variance decomposition across product type, application segment, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation with macroeconomic agricultural output projections. Modeled inputs included farmer willingness-to-pay elasticity for residue certification and fermentation feedstock cost indices.
The analysis sits within stated boundaries; outcomes outside EPA biopesticide registration acceleration or EU Farm-to-Fork target maintenance would require recalibration. Forecasts reflect assumptions about cooperative IPM pilot scaling and tropical shelf-life formulation breakthroughs. Revision becomes warranted when India CIB efficacy protocol timelines converge with domestic applicant pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Iprodione Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Dicamba Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Pest Control Products Market
Crop Protection
China Fungicide Market
Crop Protection
Tembotrione Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market