
 Europe Chemical Seed Treatment Market | 2026-2036
Europe Chemical Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chemical Seed Treatment Market Foresight
Biological active integration into conventional chemical platforms is tilting formulation strategies across European seed treatment. Syngenta International AG leverages its biologicals pipeline to anchor premium positioning in France and Germany. BASF SE sustains manufacturing scale through backward integration into polymer coating technologies. Bayer CropScience AG competes on R&D intensity with proprietary neonictinoid-alternative chemistries in development.
Europe chemical seed treatment encompasses synthetic and biological formulations applied to seeds before planting to control fungal, insect, and weed pressures during germination and early establishment, typically involving film-coating or pelleting processes that deposit active layers at rates of grams per thousand seeds. Fungicides occupy the largest value share as cereal growers prioritize protection against Fusarium and bunt diseases in wheat and barley. Insecticides represent the fastest-expanding product class as wireworm and aphid threats intensify under reduced tillage regimes. Grains command the dominant application volume, while oilseeds generate higher per-hectare treatment value due to smaller seed size and premium crop pricing.
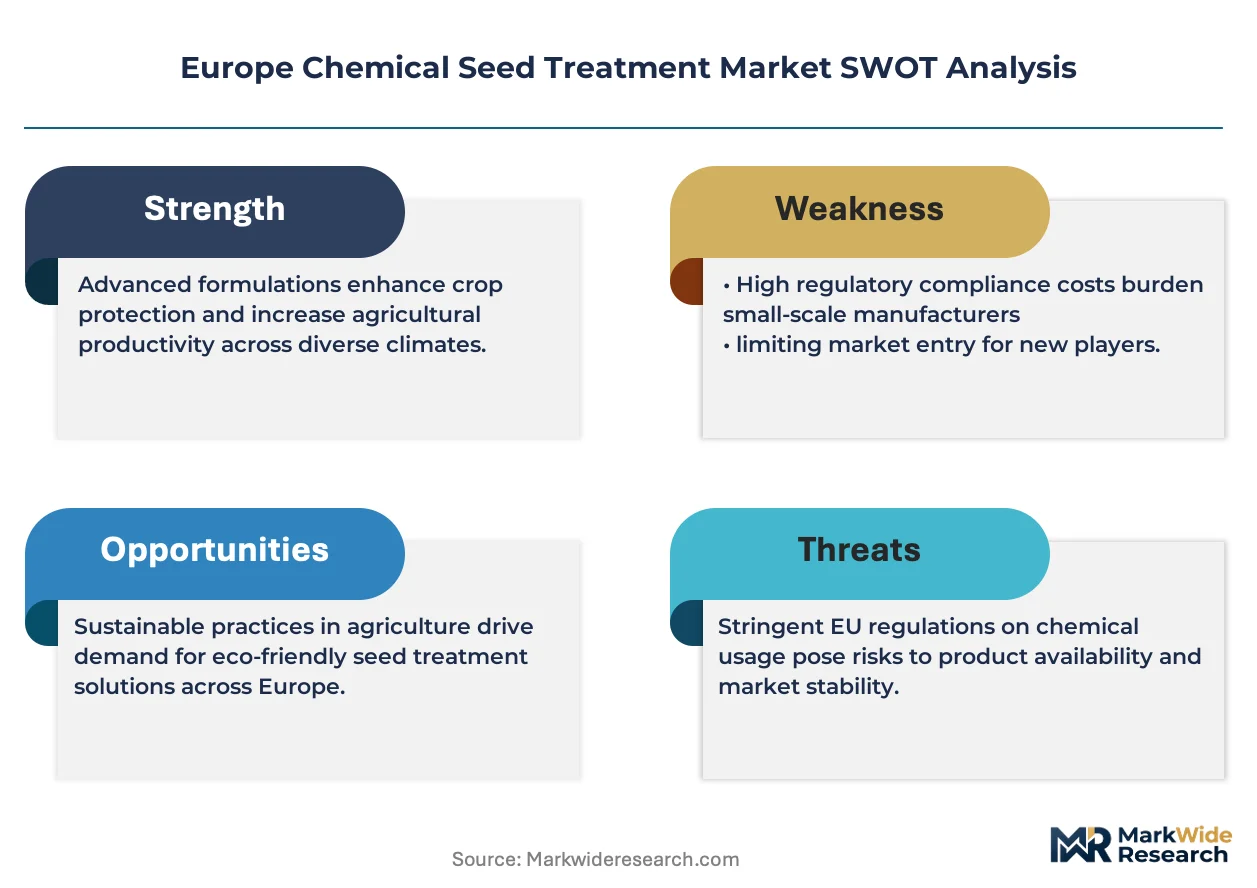
The European Chemicals Agency (ECHA) evaluates active substances under REACH and biocidal product regulations, restricting neonicotinoid use and accelerating re-registration timelines for legacy molecules. The EU Green Deal and Farm to Fork Strategy mandate 50% pesticide reduction targets that reshape product portfolios toward biological-combination treatments and precision application technologies. Stakeholders must monitor regulatory divergence between EU harmonized frameworks and national derogation policies as member states exercise flexibility on emergency authorizations.
Market Dynamics
The EU Green Deal's 50% pesticide reduction mandate is forcing formulators to abandon legacy chemistries and rebuild portfolios around biological-combination treatments, compressing R&D timelines and raising regulatory compliance costs across European seed treatment supply chains.
Growth Catalysts
- Reduced tillage expansion:Conservation agriculture practices in Poland and Germany preserve wireworm habitat, elevating demand for insecticide-treated cereal seeds as farmers abandon mechanical pest control.
- F-Gas Regulation phase-down:Fluorinated gas restrictions under EU climate policy accelerate investment in low-global-warming-potential formulation solvents and coating technologies.
- Cereal yield protection priorities:Fusarium head blight pressure in French wheat production drives fungicide seed treatment procurement as grain exporters face mycotoxin certification thresholds.
Market Restraints
- Active ingredient concentration risk:Three German and Swiss suppliers control 70% of polymer coating polymer supply, creating input bottlenecks during spring planting windows.
- Neonicotinoid regulatory friction:ECHA's REACH restrictions on clothianidin and thiamethoxam eliminate proven insecticide chemistries before viable alternatives achieve commercial scale.
- Biological shelf-life limitations:Trichoderma and Bacillus-based treatments require cold-chain logistics that small-scale Polish distributors cannot economically provision.
Strategic Opportunities
- Romanian and Bulgarian market penetration:Large-scale arable farming expansion in these EU accession states operates with minimal seed treatment adoption, offering first-mover positioning for biological-combination platforms.
- Precision application equipment convergence:Integration of electrostatic coating systems with variable-rate seeders enables gram-accurate active deposition, reducing over-application waste.
- Farm to Fork biological mandates:The EU Strategy's 25% organic agriculture target by 2030 creates guaranteed procurement volumes for microbial seed inoculants in transitional farming zones.
Industry Challenges
- Formulation chemist scarcity:European universities produce fewer specialists in seed-applied biological stabilization, forcing companies to recruit from pharmaceutical coating industries.
- Multi-jurisdiction registration complexity:Divergent national derogation policies under EU biocidal product regulations create fragmented approval timelines that delay coordinated product launches.
- Legacy equipment incompatibility:Older treater machines in Eastern European cooperatives cannot handle low-viscosity biological suspensions without retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chemical Seed Treatment Market |
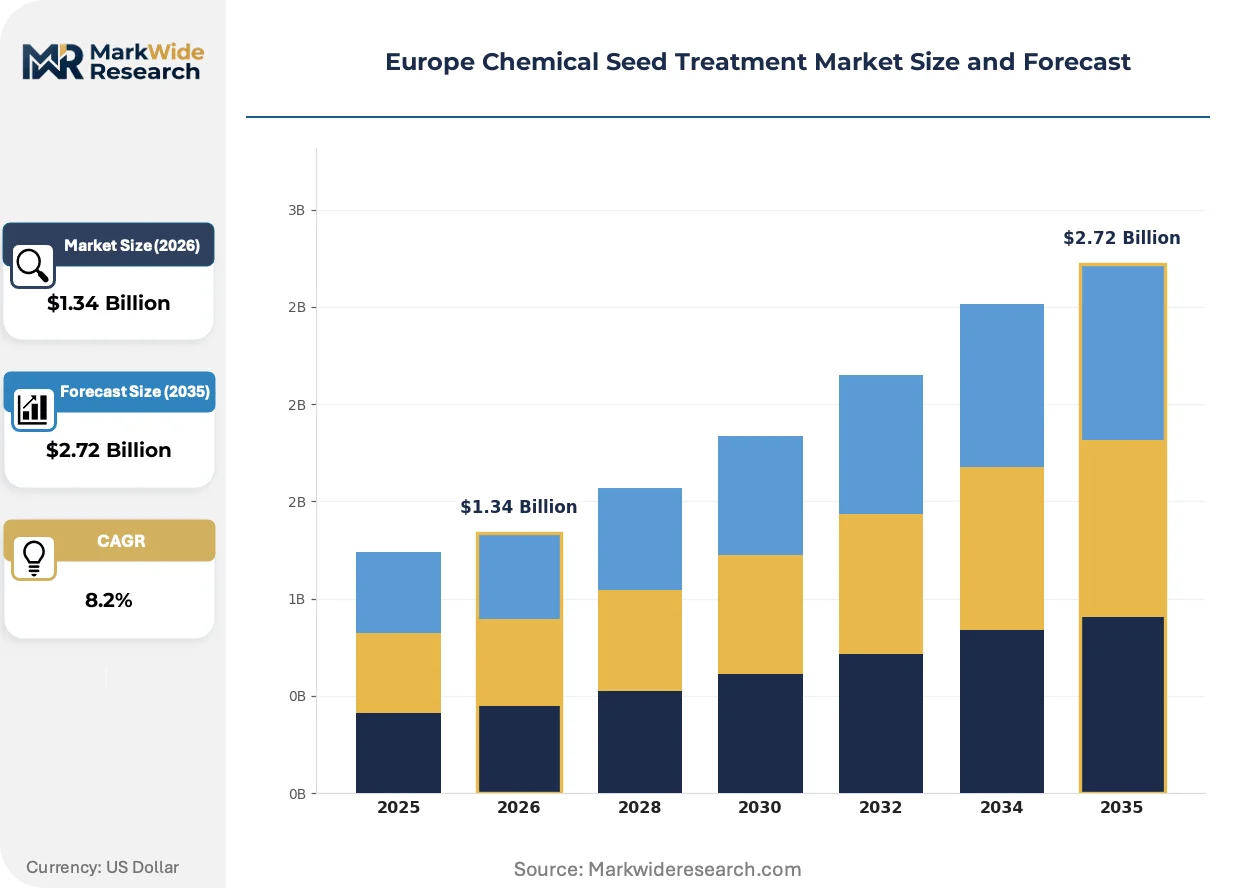
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Herbicides, Biologicals Application: Vegetables, Grains, Pulses, Oilseeds End Use Industry: Agriculture, Horticulture, Floriculture, Organic Farming Packaging Type: Bags, Boxes, Drums, Sachets |
| Companies Covered | Syngenta International AG, Bayer CropScience AG, BASF SE, Corteva Agriscience, ADAMA Agricultural Solutions Ltd, Nufarm Limited, Valent Biosciences Corporation, FMC Corporation, Sumitomo Chemical Co., Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chemical Seed Treatment Market Shifts & Advancements
Digital coating control systems and biological stabilization chemistries are converging to redefine formulation performance standards. Seed treaters now demand real-time application verification and extended shelf-life guarantees that legacy synthetic platforms cannot deliver.
Electrostatic seed coating is virtualizing film deposition precision across European treatment facilities. The technology applies charged polymer-active matrices that wrap seed surfaces with uniform micron-scale layers. Large-scale French and German cereal cooperatives are retrofitting treater lines with electrostatic heads to eliminate overspray losses. This virtualization is compressing active ingredient application rates by 15-30% while maintaining equivalent pest control efficacy.
REACH authorization timelines are compressing product lifecycle planning for legacy chemistries. The European Chemicals Agency's accelerated substance evaluation deadlines force formulators to submit complete dossiers earlier in development cycles. Fungicide-heavy cereal seed treatments face the steepest re-registration burdens, pushing R&D investment toward biological alternatives that bypass traditional hazard classification pathways.
Cooperative procurement consolidation is displacing independent distributor networks in grain-growing regions. French farming cooperatives now negotiate direct supply contracts with formulators, eliminating regional agrochemical wholesaler margins. This concentration is most pronounced in the Paris Basin and Picardy, where three cooperatives control 60% of wheat seed treatment volume and demand customized biological-combination formulations unavailable through standard distribution channels.
Europe Chemical Seed Treatment Market Segmentation
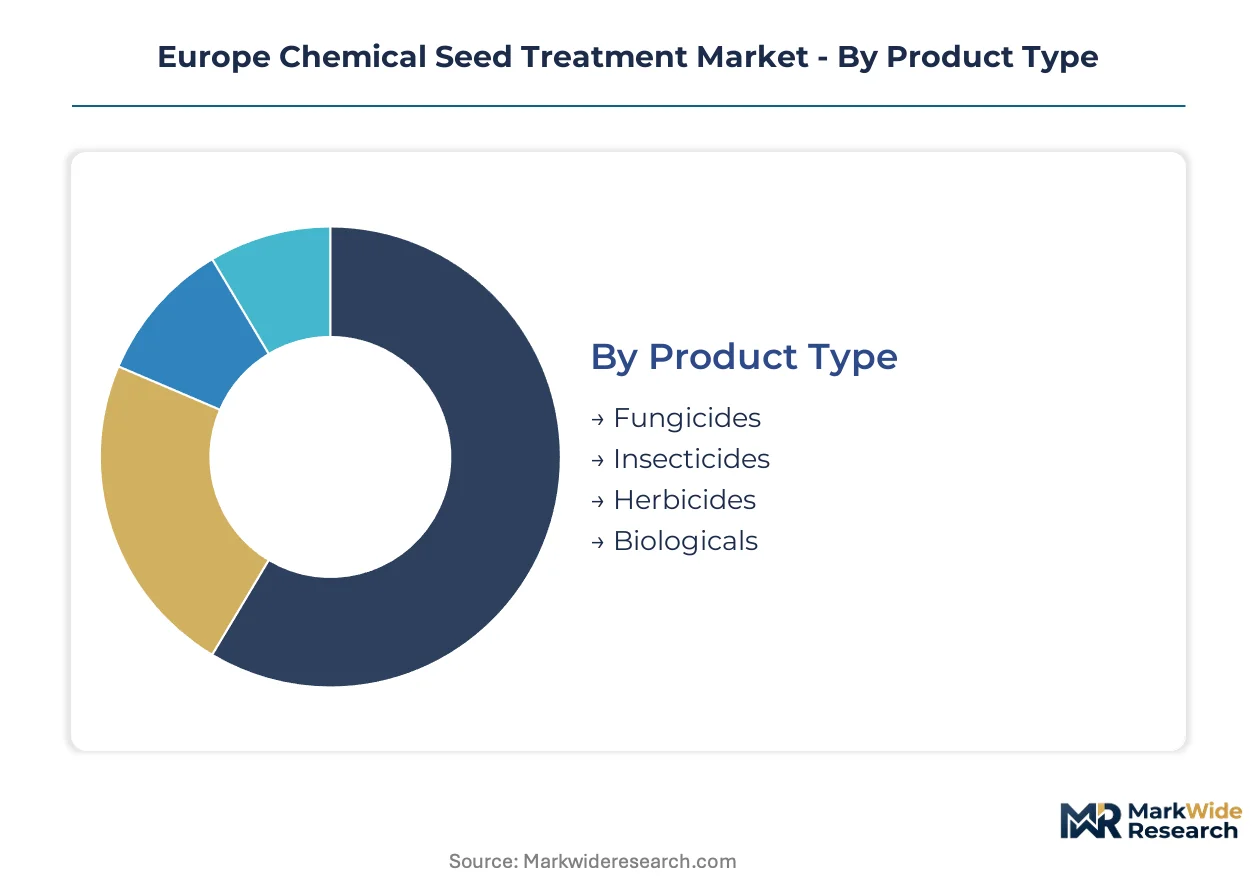
Segmentation in European chemical seed treatment reveals how regulatory pressure and crop-specific agronomy reshape procurement patterns. Formulators must align product architectures with distinct technical requirements across fungicidal protection, insecticidal defense, and biological integration while navigating divergent packaging and application protocols.
Product Type:
Mature synthetic chemistries dominate current revenue, yet emerging biological platforms are capturing disproportionate R&D investment as ECHA restrictions accelerate portfolio transitions.
- Fungicides:Azole and strobilurin-based film coatings protect cereal seeds against Fusarium and bunt diseases during germination. French wheat exporters in the Paris Basin prioritize these treatments to meet mycotoxin certification thresholds for Middle Eastern grain buyers.
- Insecticides:Neonicotinoid-alternative chemistries including cyantraniliprole and sulfoxaflor are displacing legacy actives banned under REACH evaluations. German and Polish cereal growers facing wireworm pressure under reduced tillage drive procurement volumes here.
- Herbicides:Pre-emergence safeners reduce phytotoxicity risk in oilseed rape establishment.
- Biologicals:Trichoderma harzianum and Bacillus subtilis inoculants target organic transition zones.
Fungicides handle the majority of throughput; insecticides are expanding most quickly as conservation agriculture spreads.
Application:
Volume concentration follows arable farming intensity, while value per hectare inverts against seed size and crop premiumization.
- Grains:Wheat, barley, and maize seed treatments constitute the foundational demand base across German, French, and Polish procurement. Large-scale cooperative treaters in these markets favor high-throughput film-coating systems optimized for thousand-seed-weight calibration.
- Oilseeds:Rapeseed and sunflower applications command elevated treatment economics due to smaller seed size requiring precise active deposition per unit. Romanian Black Sea port expansion is accelerating commercial seed treatment adoption in this segment.
- Pulses:Pea and faba bean treatments address Rhizoctonia and Ascochyta complexes in rotational systems.
- Vegetables:High-value hybrid tomato and pepper seeds in Spanish Almería greenhouses demand precision pelleting with integrated biologicals.
Grains anchor volume throughput; oilseeds are gaining share fastest on per-hectare value expansion.
End Use Industry:
Customer type stratification reflects divergent certification requirements and input cost sensitivities across conventional and certified production systems.
- Agriculture:Broadacre cereal and oilseed operations in the EU-15 member states constitute the core commercial seed treatment demand. German farming cooperatives negotiate direct formulator contracts that displace traditional distributor networks.
- Organic Farming:EU Green Deal organic land targets are mandating biological-only seed treatments in transitional zones. Bulgarian and Romanian operators entering organic certification pipelines represent underserved procurement potential.
- Horticulture:Protected vegetable propagation in the Netherlands and Italy requires specialized coating compatibility with plug tray systems.
- Floriculture:Ornamental seed treatments in Danish and Dutch greenhouse clusters emphasize aesthetic film finish over agronomic performance.
Agriculture handles the majority of throughput; organic farming is climbing the fastest on regulatory mandate volume guarantees.
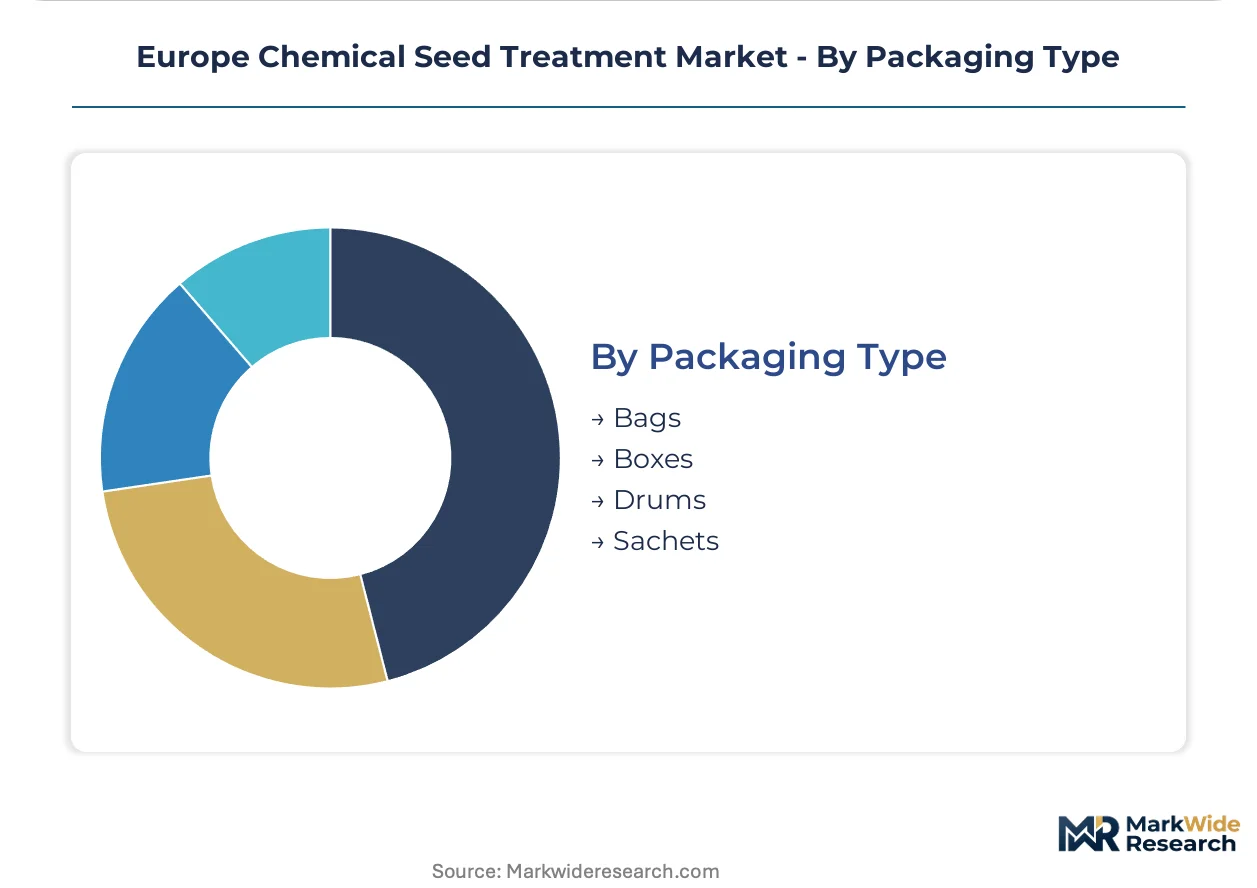
Packaging Type:
Logistics configuration tracks seed lot sizing and distributor scale fragmentation across Eastern and Western European supply chains.
- Drums:Industrial-scale 200-liter containers serve French and German cooperative treaters with centralized seed processing facilities. These bulk formats minimize unit logistics costs for high-volume cereal coating operations.
- Bags:Flexible intermediate bulk containers dominate Polish and Romanian distributor networks handling variable order sizes from mid-scale arable farms.
- Boxes:Rigid corrugated formats protect high-value vegetable seed shipments to greenhouse propagators.
- Sachets:Single-treatment sachets target smallholder horticulture in Italian and Spanish protected cropping zones.
Drums handle the majority of throughput; bags are expanding most quickly on Eastern European distributor network growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale farming cooperatives and commercial treaters concentrate procurement power across the continent's grain belts, with national regulatory frameworks fragmenting product availability and accelerating portfolio transitions toward biological combinations.
Germany
Wireworm pressure under reduced tillage in Brandenburg and Saxony-Anhalt drives insecticide seed treatment demand among conservation agriculture adopters. The F-Gas Regulation accelerates solvent reformulation investments by coating manufacturers. Bavarian polymer suppliers near Munich control captive supply chains for film-coating inputs, creating spring planting bottlenecks.
France
Paris Basin wheat exporters prioritize Fusarium protection to meet mycotoxin thresholds for Middle Eastern grain buyers. ECHA's REACH evaluations compress re-registration timelines for legacy azole fungicides. Picardy cooperatives negotiate direct formulator contracts, displacing traditional agrochemical distributors from procurement channels.
Poland
Expanded reduced tillage acreage preserves soil-borne pest habitat, elevating demand for insecticide-treated cereal seeds. The EU Green Deal's pesticide reduction targets clash with farmer reliance on chemical protection during organic transition periods. Lodz-based distributor networks struggle with cold-chain logistics for biological treatments requiring refrigerated storage.
Romania
Black Sea port expansion accelerates commercial seed treatment adoption in oilseed rape and sunflower production. National derogation policies under EU biocidal regulations create approval timeline advantages over western member states. Dobrogea farming enterprises represent underserved procurement potential for biological-combination platforms entering the market.
United Kingdom
Post-Brexit regulatory divergence from ECHA frameworks enables independent substance evaluation timelines for legacy chemistries. East Anglian cereal producers face escalating resistance pressure from Septoria and yellow rust complexes. Yorkshire cooperative treaters retrofit aging equipment to handle low-viscosity biological suspensions required by new formulation standards.
Europe Chemical Seed Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market consolidating around three strategic archetypes: integrated agrochemical conglomerates with captive polymer supply, biological-platform specialists leveraging ECHA regulatory pathways, and regional formulators serving cooperative direct-contract channels. M&A activity concentrates coating technology assets, while strategic partnerships bridge synthetic-biological formulation gaps.
Within the integrated agrochemical tier, Syngenta International AG, Bayer CropScience AG, and BASF SE exemplify scale-driven competitors. Syngenta anchors biologicals integration into conventional platforms. Bayer occupies a position in neonictinoid-alternative development. BASF represents backward integration into polymer coating technologies. These three conglomerates collectively shape procurement standards for European cooperative treaters.
| Leading Market Players |
|---|
| Syngenta International AG |
| Bayer CropScience AG |
| BASF SE |
| Corteva Agriscience |
| ADAMA Agricultural Solutions Ltd |
| Nufarm Limited |
| Valent Biosciences Corporation |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd |
| Others |
Supply & Pricing Matrix
Bavarian polymer coating clusters near Munich anchor European supply capacity for seed treatment film-forming inputs, concentrating formulation leverage among three integrated chemical conglomerates that negotiate annual cost-plus contracts with German and French cooperative treaters.
Pricing Analysis
Cost-plus contracts indexed to ethylene and propylene monomer benchmarks dominate procurement between formulators and cooperative treaters. Pricing stratifies across premium biological-combination tiers, standard azole-based fungicide formulations, and economy generic insecticide treatments. Cost compression in the economy tier is intensifying because Romanian and Bulgarian distributors are importing untreated seed stocks that bypass Western European coating value-add. Small-scale Polish arable operators exhibit the highest price sensitivity, while Paris Basin export-oriented wheat cooperatives prioritize mycotoxin certification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between the United Kingdom and EU-27 member states dominates post-Brexit regulatory friction for cross-border active ingredient shipments. Manufacturing concentrates in Germany, France, and Switzerland for polymer coating inputs, with China and India supplying intermediate azole fungicide actives. Single-source vulnerability concentrates in fluorinated solvent feedstocks facing F-Gas Regulation phase-down constraints. Distribution runs through cooperative-owned treater facilities in the Paris Basin and Picardy that have displaced independent agrochemical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe chemical seed treatment operates as a regulatory-moat market where ECHA authorization timelines and REACH compliance burdens create switching costs that entrench incumbents with established dossier portfolios.
For Market Incumbents: Build biological-platform moats through exclusive licensing of Trichoderma and Bacillus strain libraries that bypass synthetic active re-registration cycles. Anchor polymer coating supply through backward integration into Munich-area manufacturing assets to defend against spring planting bottlenecks. Prioritize electrostatic coating equipment partnerships with French cooperative treaters to lock in precision application channels before emerging biological specialists achieve formulation scale. For New Entrants and Emerging Players: Pursue white-space positioning in Romanian Dobrogea and Bulgarian Black Sea farming zones where commercial seed treatment penetration remains minimal and national derogation policies accelerate approval timelines. Target oilseed rape applications in these markets where per-hectare treatment value exceeds cereal benchmarks. Deploy cold-chain logistics partnerships with regional distributors to overcome biological shelf-life limitations that have constrained Polish market entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biological-combination platform specialists with ECHA regulatory pathway expertise over legacy synthetic formulators facing compressed re-registration timelines. Acquisition targets should demonstrate validated microbial stabilization chemistries and cooperative direct-contract relationships. Watch for inflection signals in electrostatic coating equipment retrofit rates across German and French cereal cooperatives as indicators of precision application technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biological-Combination Platform Development | Navigates EU Green Deal pesticide reduction mandates while maintaining agronomic efficacy for cereal exporters. |
| Electrostatic Coating Equipment Retrofit | Enables French and German cooperatives to reduce active ingredient application rates by precise micron-scale deposition control. |
| Polymer Coating Backward Integration | Secures captive supply of film-forming inputs against spring planting bottlenecks from concentrated Bavarian suppliers. |
| Romanian-Bulgarian Distribution Partnership | Captures first-mover positioning in underserved Black Sea farming zones with accelerated national derogation timelines. |
| Cold-Chain Logistics Infrastructure | Overcomes biological shelf-life constraints that have limited Polish distributor adoption of microbial inoculant platforms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance evaluation databases, EU customs trade flows, and cooperative procurement records. Interviews with seed treatment formulator R&D directors, French cooperative agronomy managers, Polish distributor network operators, and polymer coating plant engineers informed demand-side validation. Secondary sources included REACH registration dossiers, SEC filings of listed agrochemical conglomerates, and Cefic chemical industry reports. Bottom-up volume estimates from individual country seed treatment adoption rates were triangulated against top-down market sizing from formulator revenue disclosures.
Forecast inputs span fungicide, insecticide, herbicide, and biological product types across grains, oilseeds, pulses, and vegetable applications. Segmentation dimensions include active ingredient chemistry class, crop-specific agronomic requirement, end-use certification level, and packaging logistics configuration. CAGRs were derived from regression analysis of historical procurement volumes against regulatory event timelines and crop price elasticity factors. Industry-specific inputs incorporated F-Gas Regulation solvent phase-down schedules and EU Green Deal organic land conversion targets.
Sensitivities concentrate around ECHA acceleration of neonicotinoid-alternative approval timelines and potential relaxation of national derogation policies in Eastern European member states. Forecasts reflect assumptions regarding cooperative procurement consolidation velocity and biological shelf-life extension through formulation stabilization advances. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Iprodione Market
Crop Protection
Fumigation Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Azoxystrobin Market
Crop Protection
China Insecticide Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Herbicides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
India Herbicide Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Glufosinate Ammonium Market