
 Weapons Release System Market | 2026-2036
Weapons Release System Market Size, Share, and Industry Trends Forecast 2026-2036
Weapons Release System Market Analysis
Market Overview
United States production capacity is tilting toward software-intensive release architectures as Pentagon procurement prioritizes networked weapon stations. L3Harris Technologies leverages its avionics integration heritage to dominate electromechanical release programs for fixed-wing platforms. RTX Corporation sustains a broad portfolio spanning hydraulic and pneumatic actuation for rotary and unmanned systems. Lockheed Martin anchors demand through captive sourcing on the F-35, where release systems interface directly with its mission computer architecture.
Technical and Segment Dynamics
A weapons release system comprises the mechanical, electromechanical, and software-controlled mechanisms that secure, activate, and deploy ordnance from aerial, naval, or ground platforms, typically integrating MIL-STD-1760 aircraft-store electrical interfaces with redundant safety interlocks. Automated systems lead procurement volume as manned-unmanned teaming architectures require programmable release sequences with minimal pilot intervention. Software-controlled technology captures expanding margin pools where cybersecurity-hardened firmware and store recognition algorithms differentiate supplier offerings from legacy hydraulic alternatives.
Regulatory Environment
The US Department of Defense's MIL-STD-1760 and MIL-STD-1553 standards govern electrical and data bus interfaces, while the FAA regulates civil derivative platforms used in law enforcement and search and rescue configurations. Europe's CE marking and EU AI Act are beginning to shape requirements for autonomous release decision aids on exported platforms. Stakeholders must monitor how software certification timelines interact with platform upgrade cycles to avoid capability gaps.
Market Dynamics
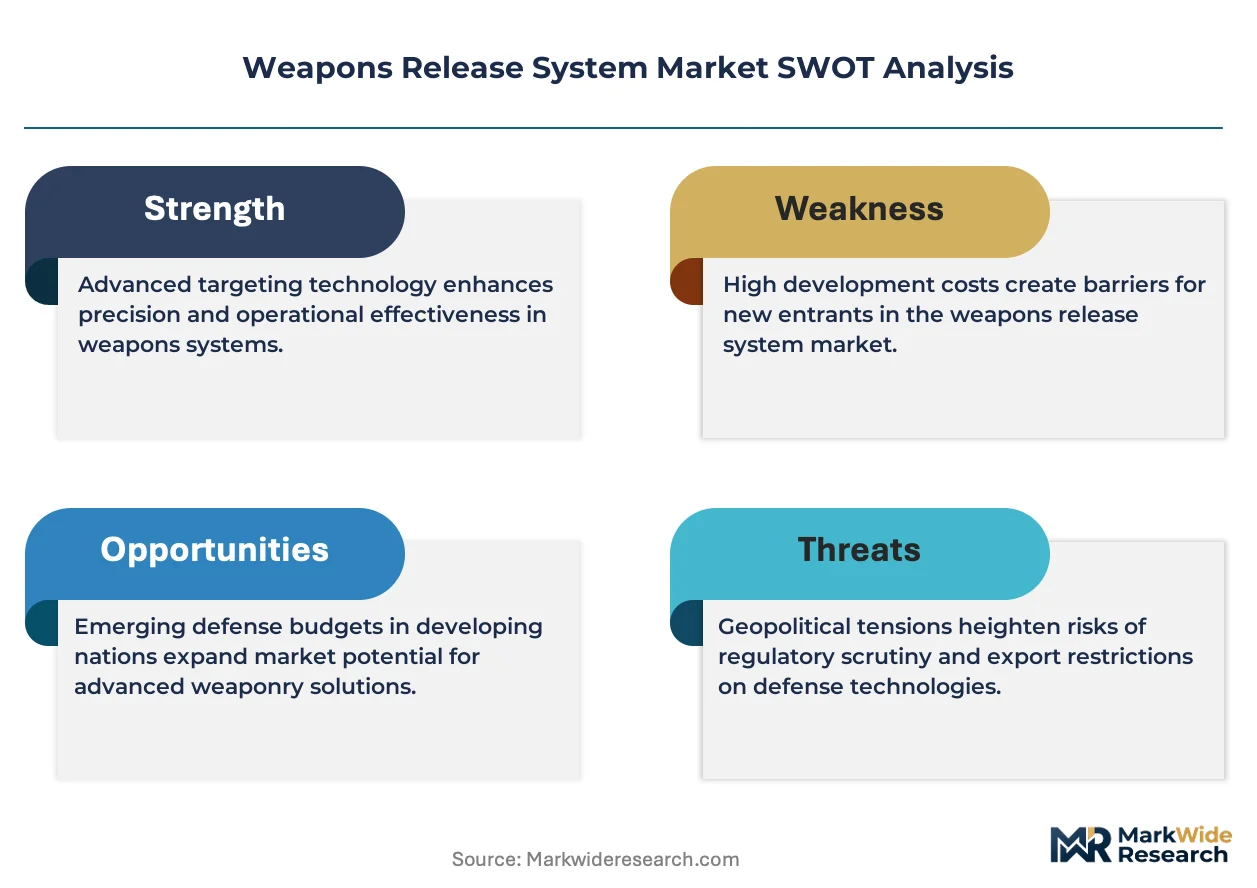
The Pentagon's software certification mandates for MIL-STD-1760 interfaces are compressing supplier timelines while simultaneously elevating technical barriers to entry, forcing release system architectures toward firmware-intensive designs that integrate directly with F-35 mission computers and next-generation bomber platforms.
Growth Catalysts
- Automated release architectures:Manned-unmanned teaming requirements across strike platforms demand programmable sequences with minimal pilot intervention, pulling electromechanical systems toward software-controlled alternatives.
- MIL-STD-1760 interface mandates:The US Department of Defense's tightening certification standards for aircraft-store electrical interfaces are locking in demand for compliant release systems on modernized fighter and bomber fleets.
- Rotary-wing modernization:Unmanned aerial system programs require hydraulic and pneumatic actuation systems with redundant safety interlocks, expanding addressable platform categories beyond fixed-wing strike aircraft.
Market Restraints
- Software certification timelines:Pentagon firmware validation protocols extend development cycles by 18-24 months, freezing supplier cash flow and delaying platform integration milestones.
- Titanium and high-grade aluminum volatility:Release mechanism housings depend on aerospace-grade alloys subject to defense-priority allocation constraints and spot price instability.
- Captive sourcing concentration:Lockheed Martin's vertical integration on F-35 release systems eliminates third-party supplier access to the program's core procurement volume.
Strategic Opportunities
- Search and rescue platform derivatives:FAA-regulated civil configurations of military release systems for law enforcement air wings remain underpenetrated relative to defense procurement intensity.
- Cybersecurity-hardened firmware:Store recognition algorithms and encrypted command protocols represent margin expansion potential as release systems integrate with networked weapon stations.
- EU AI Act compliance pathways:European autonomous release decision aids create a regulatory tailwind for suppliers capable of certifying algorithmic safety interlocks for exported platforms.
Industry Challenges
- MIL-STD-1553 legacy integration:New software-controlled architectures must maintain backward compatibility with existing aircraft data bus infrastructures, complicating firmware architecture decisions.
- Systems engineering talent scarcity:The intersection of ordnance safety engineering and embedded software development requires specialized skill sets concentrated at prime contractors and select defense universities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weapons Release System Market |
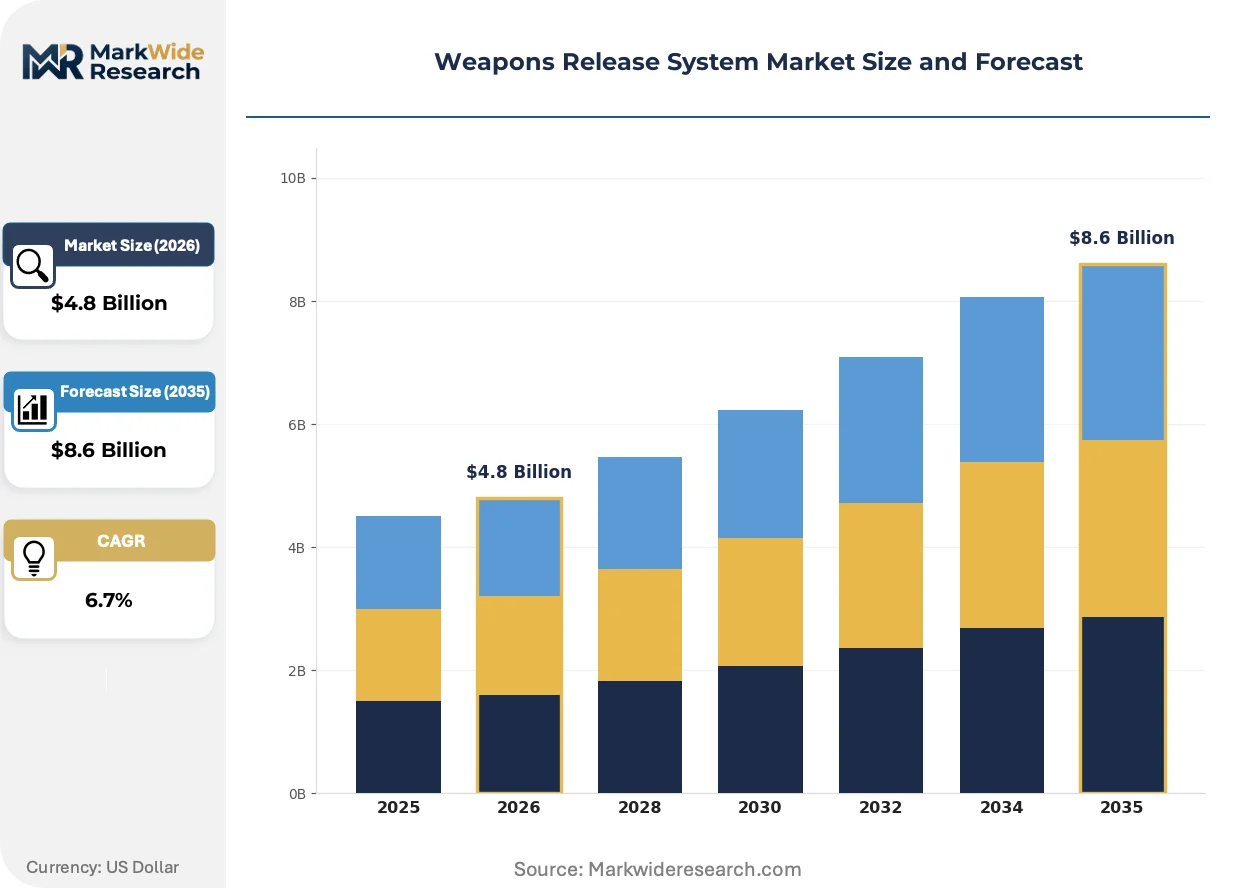
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Hybrid Systems, Smart Release Mechanisms Technology: Electromechanical, Hydraulic, Pneumatic, Software-Controlled Application: Military, Defense Contracting, Law Enforcement, Search and Rescue End User: Armed Forces, Special Operations, Security Agencies, Private Contractors |
| Companies Covered | L3Harris Technologies, RTX Corporation, Lockheed Martin, Moog Inc., The Marvin Group, Raytheon Technologies, Cobham, Marotta Controls, RUAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weapons Release System Market Emerging Trajectories
Weapons release technology is converging on firmware-centric architectures where store recognition, safety interlock logic, and pilot interface commands execute through hardened software rather than purely mechanical or hydraulic pathways.
Electromechanical release actuators with integrated position sensing and feedback loops are digitizing the pilot-to-ordnance command chain, replacing hydraulic pressure systems with servo-motor precision. Naval aviation programs and unmanned strike platforms are adopting these architectures fastest, compressing supplier differentiation toward cybersecurity certification and algorithm validation rather than mechanical reliability alone.
The EU AI Act's emerging requirements for autonomous decision aids are forcing European defense exporters to document algorithmic transparency in release sequence logic. This regulatory pressure is fragmenting certification pathways between US MIL-STD compliance and European AI governance frameworks, compelling suppliers to maintain dual-track firmware development.
Defense procurement offices are consolidating weapon station upgrades into platform-wide modernization contracts rather than component-level acquisitions. This bundling behavior concentrates supplier relationships with airframe primes, marginalizing standalone release system vendors unless they embed deeply into mission computer architectures or secure sole-source positions on unmanned platforms.
Weapons Release System Market Segmentation
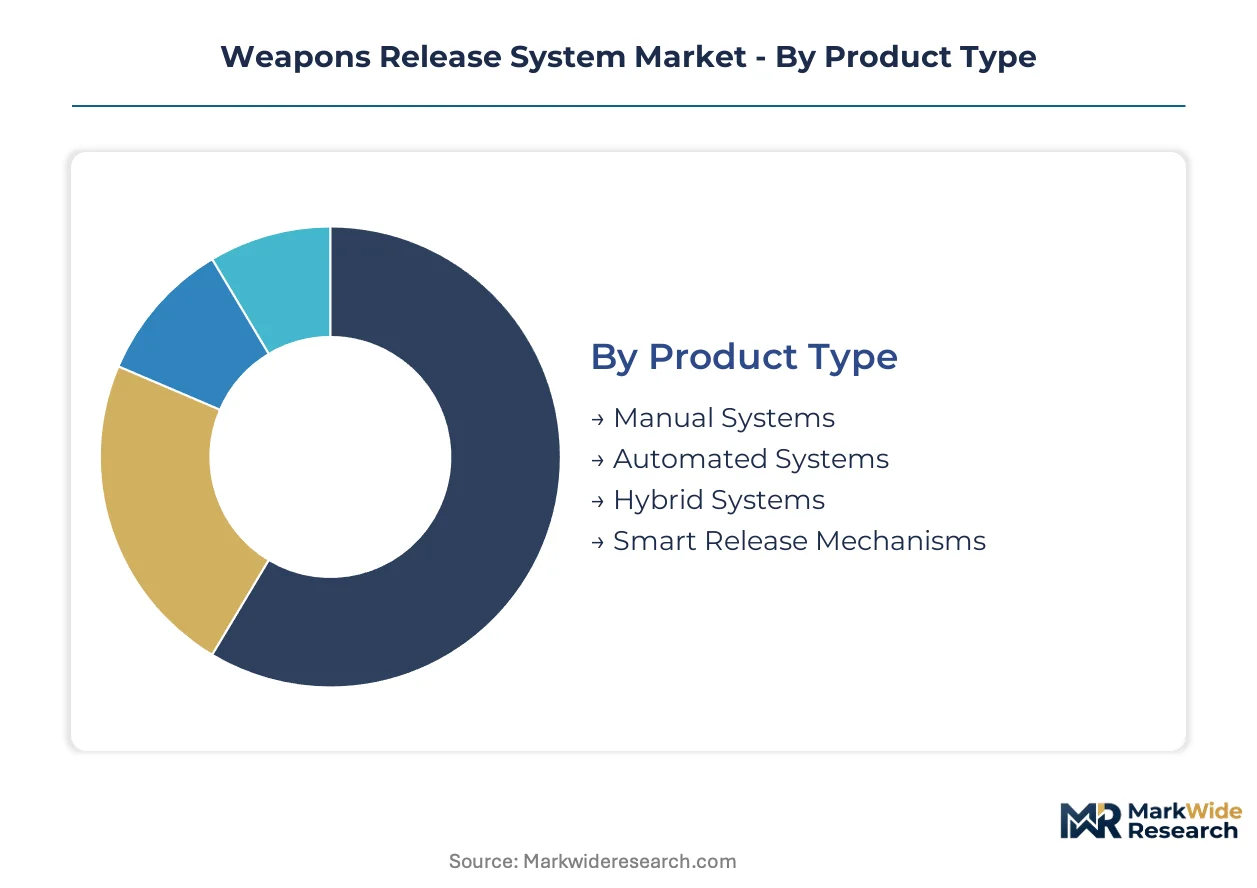
Weapons release system procurement fragments across four critical dimensions: product architecture, actuation technology, mission application, and end-user category. Each axis carries distinct certification requirements and margin profiles that reshape supplier positioning.
Product Type:
Cost tier stratification separates legacy mechanical architectures from firmware-intensive platforms commanding premium pricing.
- Automated Systems:Programmable release sequences execute through electromechanical actuators with redundant safety interlocks. Pentagon modernization of F-35 weapon stations and next-generation bomber programs concentrates procurement volume here, though MIL-STD-1760 certification timelines extend supplier cash cycles.
- Smart Release Mechanisms:Store recognition algorithms and encrypted command protocols enable autonomous ordnance selection in manned-unmanned teaming architectures. Naval aviation and unmanned strike platforms absorb initial production, with cybersecurity-hardened firmware differentiating supplier offerings.
- Manual Systems:Pilot-actuated mechanical releases persist on legacy rotary-wing and trainer platforms where upgrade budgets remain constrained.
- Hybrid Systems:Dual-mode architectures blend manual override with electromechanical precision for special operations requirements.
Automated systems command the established base. The steepest expansion runs through smart release mechanisms.
Technology:
Application context dictates actuation selection—fixed-wing strike platforms diverge sharply from rotary and unmanned system requirements.
- Software-Controlled:Firmware-centric architectures integrate MIL-STD-1760 aircraft-store interfaces with mission computer architectures. F-35 program upgrades and Pentagon software certification mandates concentrate demand, compressing differentiation toward algorithm validation and cybersecurity accreditation.
- Electromechanical:Servo-motor actuators with integrated position sensing digitize pilot-to-ordnance command chains. RTX Corporation sustains broad portfolio coverage here, spanning fixed-wing and rotary applications where hydraulic replacement cycles accelerate.
- Hydraulic:Pressure-based actuation retains dominance on heavy-lift rotary platforms and legacy bomber fleets.
- Pneumatic:Compressed gas systems serve specialized unmanned aerial system programs requiring minimal electromagnetic signature.
Software-controlled architectures are gaining share fastest. Electromechanical platforms anchor current procurement volume.
Application:
Mission profile severity determines specification intensity and regulatory oversight tier.
- Military:Strike platforms, strategic bombers, and tactical fighters impose MIL-STD-1760 and MIL-STD-1553 compliance with stringent ordnance safety engineering. United States Air Force and Navy modernization programs absorb the dominant procurement share.
- Defense Contracting:Prime contractor weapon station integration contracts bundle release systems into platform-wide upgrades, marginalizing standalone component vendors.
- Law Enforcement:FAA-regulated civil configurations for air wing operations remain underpenetrated relative to defense intensity.
- Search and Rescue:Derivative platforms for emergency response configurations offer alternative procurement channels.
Military applications dominate contract value. Defense contracting integration models are reshaping supplier access.
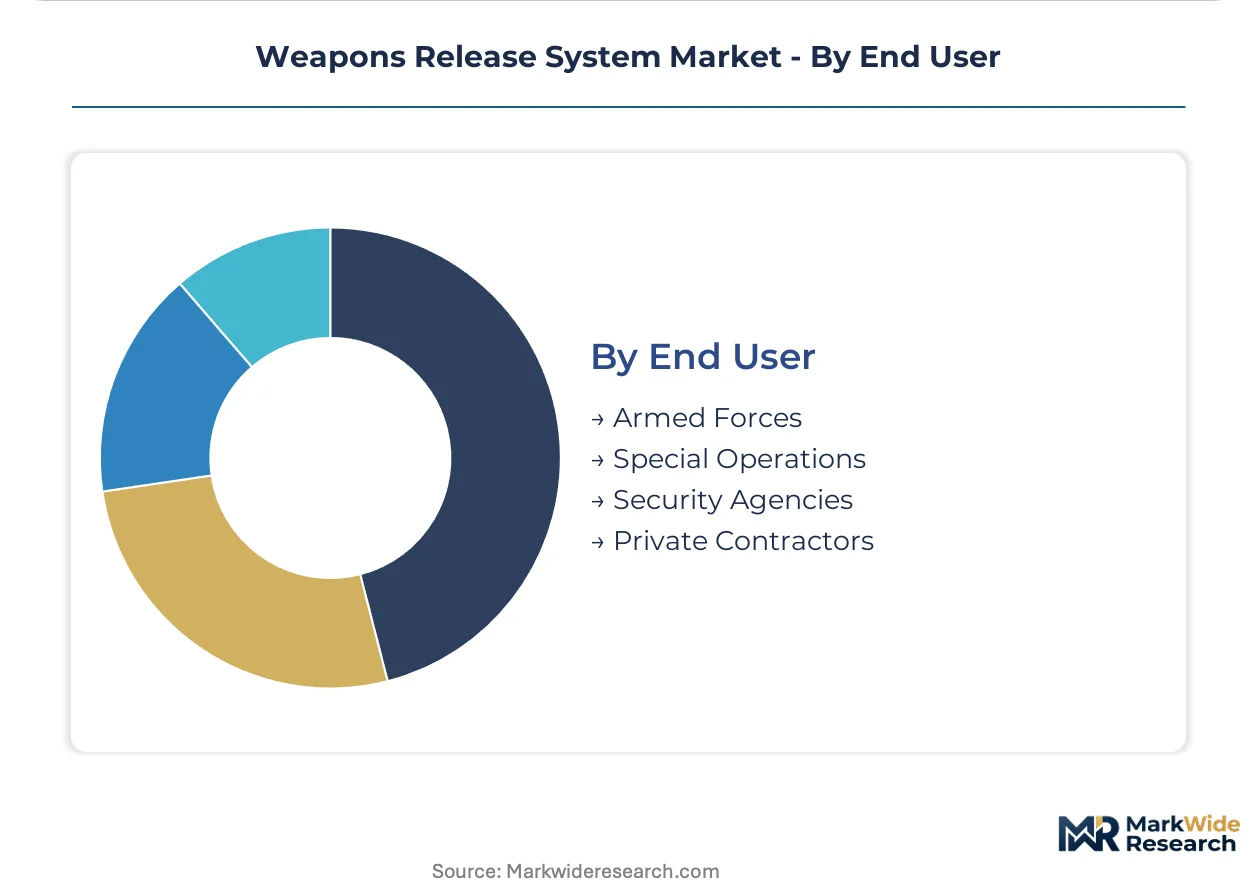
End User:
Customer type fragmentation reflects operational classification and procurement authority concentration.
- Armed Forces:Conventional service branches execute platform modernization through prime contractor relationships, with F-35 and next-generation bomber programs driving specification intensity.
- Special Operations:Distinct requirements for rapid reconfiguration and non-standard ordnance compatibility create niche demand for hybrid and manual override systems.
- Security Agencies:Border patrol and federal air wing operations source through modified military specifications with civil regulatory overlay.
- Private Contractors:Training, logistics, and surrogate threat simulation providers absorb surplus and refurbished equipment.
Armed Forces procurement anchors program viability. Special Operations requirements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense primes concentrate weapons release system engineering in aerospace clusters tied to Pentagon procurement hubs and allied military modernization programs. Supplier access fragments across national security barriers, with firmware certification requirements creating geographic moats around each defense industrial base.
United States
F-35 program upgrades and next-generation bomber development absorb the dominant procurement volume for MIL-STD-1760 compliant release architectures. The Department of Defense's software certification mandates for weapon interfaces compress supplier timelines while elevating technical barriers. Texas and California aerospace corridors host prime contractor integration facilities where release systems interface directly with mission computer architectures.
United Kingdom
Royal Air Force Tempest program and Typhoon fleet modernization sustain demand for electromechanical release systems with NATO interoperability requirements. The UK Ministry of Defence's procurement frameworks prioritize suppliers demonstrating cyber resilience accreditation. BAE Systems integration facilities in Lancashire and Bristol anchor regional engineering concentration for European fighter programs.
Germany
FCAS development and Tornado replacement initiatives drive specification intensity for software-controlled release mechanisms with Franco-German interoperability standards. The Federal Office of Bundeswehr Equipment mandates compliance with EU AI Act emerging requirements for autonomous decision aids. Bavarian and Baden-Württemberg aerospace clusters house subsystem suppliers serving Airbus Defence integration channels.
Israel
Indigenous fighter programs and unmanned strike platform exports sustain specialized demand for compact release systems with rapid reconfiguration capabilities. The Israeli Ministry of Defense prioritizes suppliers with proven manned-unmanned teaming integration experience. Tel Aviv and Haifa metropolitan areas concentrate engineering talent for embedded ordnance safety systems serving regional air forces.
Japan
F-X fighter development and F-15J modernization expand procurement for release systems compatible with US-Japan alliance interoperability protocols. The Ministry of Defense Acquisition, Technology and Logistics Agency tightens cybersecurity requirements for foreign-sourced weapon interfaces. Nagoya aerospace manufacturing corridors host Mitsubishi Heavy Industries integration facilities where domestic release system capabilities are advancing.
Weapons Release System Market Vendor Landscape
Avionics integrators and electromechanical specialists split the market between software-intensive architectures and precision actuation platforms. Prime contractor captive sourcing on flagship programs concentrates procurement authority while marginalizing standalone component vendors. Three archetypes dominate: mission system integrators with embedded release capabilities, electromechanical subsystem specialists serving multiple airframe programs, and hydraulic actuation incumbents defending rotary-wing positions. Competitive moves center on firmware certification pre-positioning and strategic embedding into platform-wide modernization contracts.
Among US-based defense primes, L3Harris Technologies, RTX Corporation, and Lockheed Martin occupy distinct positions within the supplier hierarchy. L3Harris represents the avionics heritage archetype, RTX exemplifies diversified electromechanical portfolio breadth, and Lockheed Martin anchors the vertical integration model through captive sourcing on the F-35 program. These three entities collectively illustrate how defense procurement consolidation has compressed third-party supplier access to core strike platform volumes.
| Leading Market Players |
|---|
| L3Harris Technologies |
| RTX Corporation |
| Lockheed Martin |
| Moog Inc. |
| The Marvin Group |
| Raytheon Technologies |
| Cobham |
| Marotta Controls |
| RUAG Group |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European firmware certification facilities is compressing supplier margins while concentrating pricing power with Pentagon-approved vendors who have cleared MIL-STD-1760 validation protocols. This utilization imbalance rewards incumbent defense primes with validated software architectures while forcing second-tier suppliers toward cost-absorbing partnerships.
Pricing Analysis
MIL-STD-1760 certification tiers dictate the pricing tier structure across release system procurement, separating validated firmware architectures from legacy electromechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity accreditation depth, with algorithm-hardened systems commanding substantial premiums over hydraulic replacements. Cost compression in standard-tier electromechanical platforms is intensifying because rotary-wing modernization programs are consolidating vendor relationships. Defense contracting offices exhibit the lowest price sensitivity due to mission-critical requirements, while law enforcement air wings demonstrate acute sensitivity to total ownership costs.
Supply Chain Analysis
ITAR and EAR export controls restrict firmware-intensive release architectures from flowing to non-allied defense industrial bases, fragmenting supplier networks along security-cleared boundaries. Production gravity centers on the United States, the United Kingdom, and Israel, with each jurisdiction maintaining captive certification pathways. The supply chain draws from aerospace-grade titanium suppliers in the US, precision servo-motor manufacturers in Japan, and embedded software engineering clusters in Tel Aviv and California. Single-source vulnerability concentrates around MIL-STD-1760 interface chipsets produced by cleared domestic foundries. Distribution runs through prime contractor weapon station integration contracts rather than standalone component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against commercial-off-the-shelf drone release mechanisms that threaten to commoditize precision ordnance deployment. Incumbents must differentiate through firmware certification moats and mission computer embedding.
For Market Incumbents: Harden cybersecurity accreditation positions by pre-clearing store recognition algorithms with Pentagon software validation offices before competitor submissions. Deepen backward integration into MIL-STD-1760 interface chipset supply through security-cleared domestic foundry partnerships, denying emerging players access to certified hardware substrates. Lockheed Martin's captive sourcing model demonstrates how upstream control over firmware validation timelines eliminates third-party supplier access to flagship programs. For New Entrants and Emerging Players: Pursue FAA-regulated civil configurations for law enforcement air wings and search and rescue derivatives where defense-grade certification requirements relax and procurement cycles shorten. The underpenetrated security agency segment offers the most accessible entry vector, with border patrol air wing operations seeking modified military specifications at reduced compliance costs. Position through aftermarket retrofit partnerships with regional helicopter modification centers rather than prime contractor channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-centric suppliers with Pentagon software certification pre-clearance and embedded positions in unmanned platform architectures. Long-term viability hinges on sustained defense modernization budgets and manned-unmanned teaming proliferation rather than cyclical procurement spikes. Target acquisition candidates with validated EU AI Act compliance pathways for autonomous release decision aids, as European export requirements fragment competitive positioning. Monitor Pentagon software certification queue lengths as the critical inflection signal—backlogs exceeding twenty-four months indicate supplier capacity constraints that favor incumbents with established validation relationships.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-1760 Firmware Pre-Certification | Pentagon validation queue positioning locks in multi-year supplier relationships before competitor entry. |
| Cybersecurity-Hardened Algorithm Development | Store recognition protocols with encrypted command chains differentiate offerings from legacy hydraulic systems. |
| Unmanned Platform Embedding | Direct integration with UAS mission computers bypasses prime contractor bundling that marginalizes standalone vendors. |
| EU AI Act Compliance Pathway Investment | Algorithmic transparency documentation for autonomous release decision aids opens European export channels. |
| Law Enforcement Air Wing Partnership | FAA-regulated civil configurations offer procurement volume outside defense contracting consolidation. |
Methodological Framework
A standing panel of weapons release system program managers, Pentagon software certification officers, avionics integration engineers, and prime contractor procurement directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against Department of Defense acquisition databases, FAA certification filings, SEC 10-K disclosures from listed defense primes, and EU defense export license records. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis across the analysis window.
Scenario bracketing anchored the forecast framework, with volume and value outputs reflecting triangulated approaches across product architecture, actuation technology, mission application, and end-user category dimensions. CAGRs derived from regression analysis of historical procurement patterns against platform modernization cycle timing. Modeled inputs included F-35 program upgrade schedules, next-generation bomber development milestones, and unmanned aerial system procurement trajectories without specifying calendar years.
Sensitivities concentrate around Pentagon software certification timeline extensions, titanium alloy defense-priority allocation disruptions, and EU AI Act implementation granularity affecting autonomous release decision aid exports. Forecasts reflect documented assumptions regarding sustained defense modernization funding and alliance interoperability protocol stability. Material shifts in export control regime stringency or platform-wide modernization contract bundling behavior would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Light Weapons Market