
 Sports Shotgun Market | 2026-2036
Sports Shotgun Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Shotgun Market Analytics
Modular choke tube systems and adjustable stock geometry is fragmenting traditional platform loyalty among competitive shooters. Fabbrica d'Armi Pietro Beretta S.p.A. leverages its vertically integrated barrel manufacturing in Gardone Val Trompia to control alloy sourcing. Armi Perazzi S.p.A. sustains dominance in Olympic trap and skeet disciplines through hand-fitted action engineering. Blaser GmbH competes with its linear-action F3 platform that reduces muzzle flip for rapid second shots.
A sports shotgun is a smoothbore long gun designed to fire shells containing multiple projectiles or single slugs, typically featuring barrel lengths between 26 and 32 inches, chamber pressures rated for 12, 20, 28 gauge or .410 bore, and interchangeable choke constrictions to control shot pattern spread for targets at varying distances. Its primary commercial purpose centers on organized clay target sports, hunting game birds and small mammals, and professional training protocols where rapid target acquisition and controlled recoil management determine performance outcomes. Over-Under configurations command premium pricing in competitive trap and skeet circles where balance and sight plane consistency justify elevated acquisition costs. Semi-Automatic platforms capture expanding demand among sporting clays enthusiasts seeking reduced felt recoil during extended course walks. Pump Action variants retain durable utility in hunting applications where reliability across adverse field conditions outweighs cycling speed advantages.
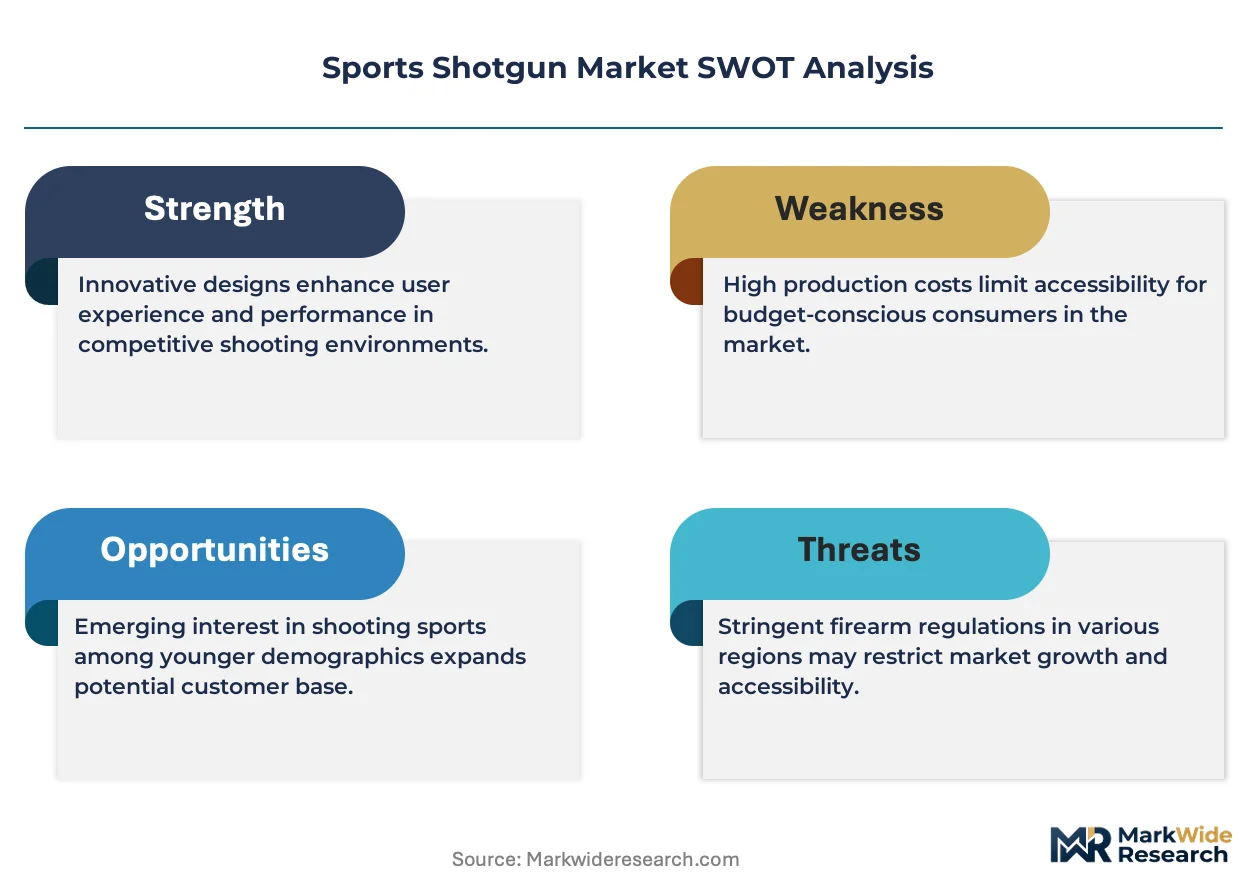
The US Bureau of Alcohol, Tobacco, Firearms and Explosives regulates commercial transfers through the National Instant Criminal Background Check System, creating procedural friction that specialty retailers navigate through extended inventory planning cycles. The European Union's Firearms Directive establishes minimum standards for civilian possession categories that member states transpose with varying stringency, directly shaping import eligibility for Turkish and American manufacturers. The International Shooting Sport Federation maintains equipment conformity protocols for Olympic disciplines that manufacturers must satisfy for competitive eligibility. Stakeholders must monitor evolving lead ammunition restrictions across multiple jurisdictions and assess alternative shot material viability before committing to long-term barrel and choke engineering roadmaps.
Market Dynamics
Modular choke systems and adjustable stock geometry are fragmenting traditional platform loyalty among competitive shooters, forcing manufacturers to engineer interoperability across aftermarket ecosystems rather than defend proprietary configurations.
Growth Catalysts
- Clay Target Club Expansion:Shooting clubs across the United States and Italy are upgrading equipment inventories and expanding membership rosters, creating pull-through demand for Over-Under and semi-automatic platforms.
- REACH Compliance Pathways:The European Chemicals Agency's lead ammunition restrictions are accelerating engineering investment in steel, bismuth, and tungsten composite shot materials compatible with existing barrel specifications.
- Olympic Equipment Conformity:The International Shooting Sport Federation maintains strict equipment protocols for trap and skeet disciplines that manufacturers must satisfy for competitive eligibility, creating certified-product premiums.
Market Restraints
- NICS Procedural Friction:The US Bureau of Alcohol, Tobacco, Firearms and Explosives maintains stringent background check protocols that extend procurement cycles and compress retailer inventory turns.
- Brescia-Gardone Supply Concentration:Italy's Val Trompia cluster controls concentrated barrel-forging and action-machining capacity, creating geographic single-point vulnerability for alloy sourcing.
- Choke Tube Standardization Limits:Thread pitch and taper inconsistencies across manufacturers prevent universal aftermarket compatibility, fragmenting accessory ecosystems.
Strategic Opportunities
- Turkish Manufacturing Scale:Ankara and Konya-based producers are capturing mid-market share through CNC machining investments that challenge Italian heritage positioning on price-performance metrics.
- Lead-Free Mandate Tailwinds:California's lead ammunition ban and pending EU-wide restrictions are creating first-mover advantages for manufacturers with validated alternative-shot barrel engineering.
- Direct-to-Consumer Channels:Specialty retailers and manufacturer-owned e-commerce platforms are disintermediating traditional distribution, capturing margin and customer data simultaneously.
Industry Challenges
- Action Fitting Skill Scarcity:Hand-fitted lockwork and trigger tuning require master gunsmiths with decade-long apprenticeships that cannot be replicated through automated production.
- Regulatory Compliance Timelines:ATF import approval and EU Firearms Directive category transposition create 12-18 month certification lags that mismatch against product development cycles.
- Legacy Platform Integration:Aftermarket choke tube and stock systems must maintain backward compatibility with 30-year-old receiver designs, constraining radical geometry innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Shotgun Market |
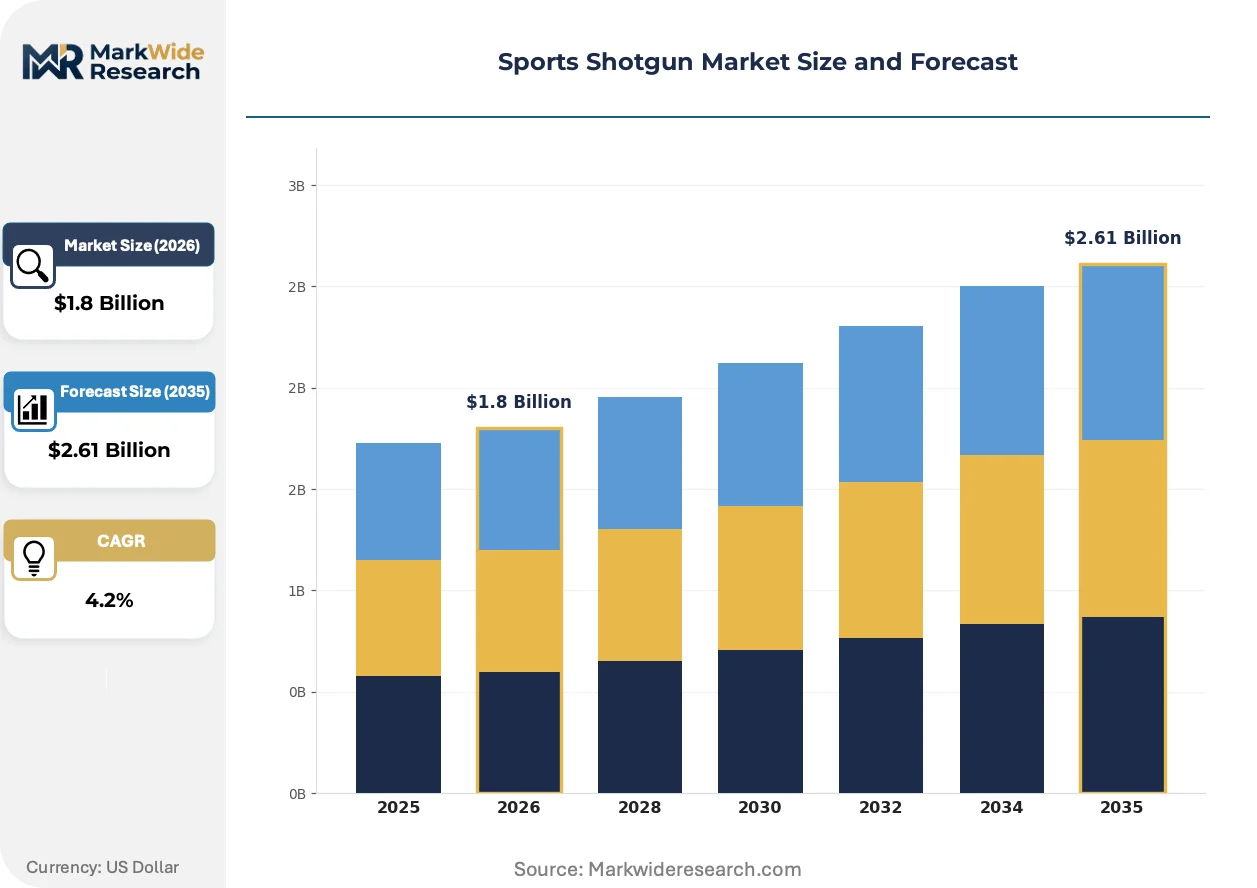
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Under, Side-by-Side, Pump Action, Semi-Automatic, Single Barrel Application: Clay Target Shooting, Hunting, Skeet Shooting, Trap Shooting, Sporting Clays End User: Professional Shooters, Sports Enthusiasts, Hunters, Shooting Clubs, Law Enforcement Training Distribution Channel: Specialty Sports Stores, Online Retailers, Gun Shows, Sporting Goods Dealers, Direct Manufacturer Sales |
| Companies Covered | Fabbrica d'Armi Pietro Beretta S.p.A., Armi Perazzi S.p.A., Blaser GmbH, H. Krieghoff GmbH, Caesar Guerini S.r.l., Browning Arms Company, Benelli Armi, O.F. Mossberg & Sons, Inc., Winchester Repeating Arms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Shotgun Market Evolving Landscape
Precision manufacturing and regulatory chemistry are converging to redefine barrel metallurgy and shot material viability, compressing traditional product lifecycles and forcing concurrent engineering across hardware and ammunition portfolios.
Carbon-fiber-wrapped barrel technology is rendering obsolete traditional steel-heavy configurations in competitive sporting clays circles. Elite shooters in the United States and Italy are adopting ported, tensioned barrels that reduce weight forward of the hinge pin by 35-40 percent. This shift is compressing demand for conventional monobloc steel barrels in premium Over-Under segments.
REACH Annex XVII restrictions on lead compounds in ammunition are forcing barrel manufacturers to redesign choke geometries and forcing cone profiles. The European Chemicals Agency's sunset dates for wetland shooting are accelerating R&D into steel-shot-compatible barrel steels with modified Brinell hardness ratings. Turkish and Italian manufacturers are responding with extended forcing cones and back-bored specifications optimized for non-toxic shot patterns.
Specialty retailers are unbundling after-sales fitting and maintenance from hardware transactions, creating recurring revenue streams separate from unit sales. This disintermediation of service from product is most visible in the United States, where independent gunsmiths and club armorers are capturing lifetime value through choke fitting, stock adjustment, and trigger tuning subscriptions rather than one-time retail margins.
Sports Shotgun Market Segmentation
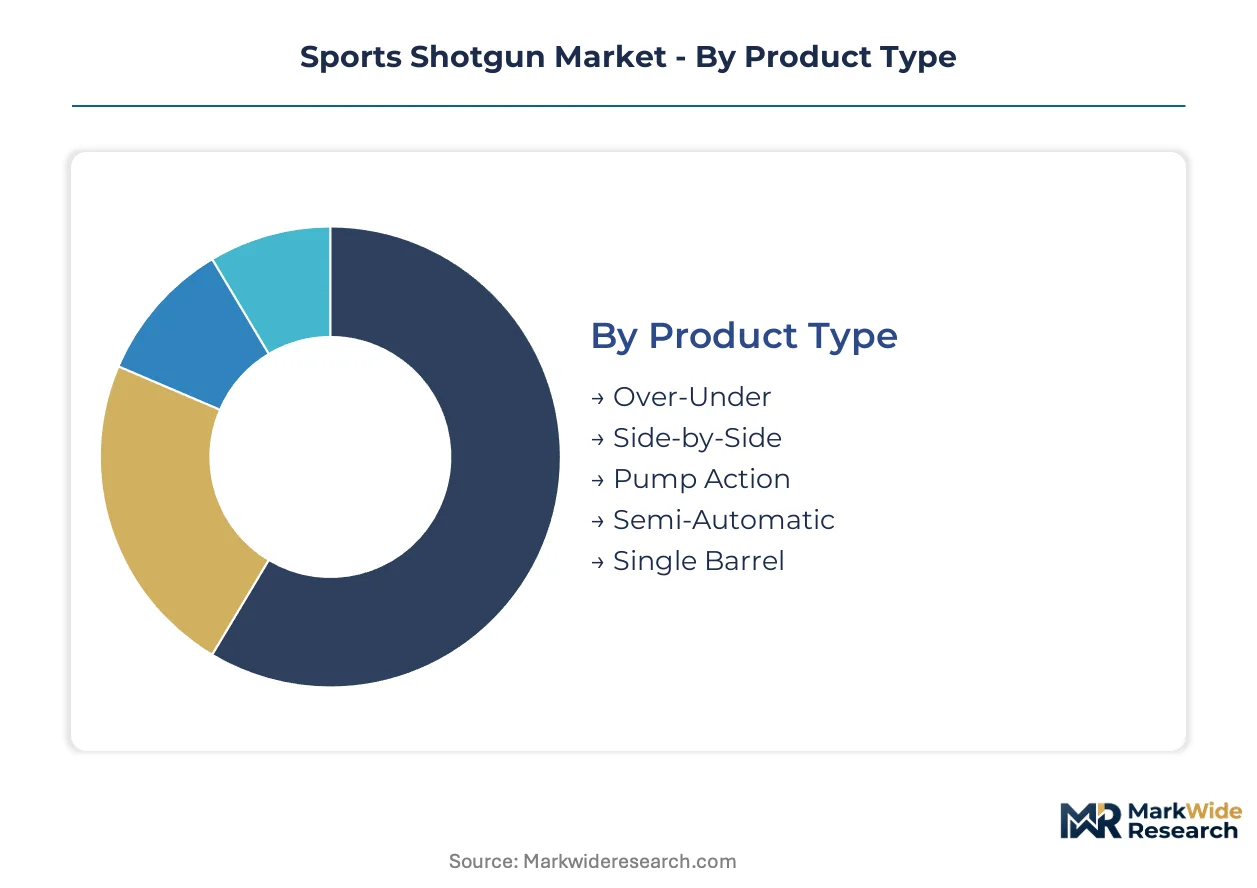
Sports shotgun procurement cycles vary dramatically across product configurations and user profiles, with competitive shooters replacing platforms every 3-5 years while hunting enthusiasts retain firearms for decades. Understanding these turnover differentials helps manufacturers align inventory planning against predictable replacement waves versus sporadic first-time purchases.
Product Type:
Over-Under configurations turn over fastest among competitive shooters seeking incremental balance refinements, while Pump Action variants persist longest in harsh field conditions where reliability outweighs technological obsolescence.
- Over-Under:Twin barrels arranged vertically deliver superior sight plane consistency and reduced muzzle flip for rapid second shots. Demand concentrates among ISSF-sanctioned trap and skeet competitors in Italy and the United States who prioritize balance precision over acquisition cost. The Brescia-Gardone Val Trompia cluster dominates premium forging capacity for this configuration.
- Semi-Automatic:Gas-operated or inertia-driven cycling systems attenuate felt recoil during extended sporting clays courses. Enthusiasts across American shooting clubs favor this platform for reduced shoulder fatigue over 100-target rounds, though ATF import approvals extend procurement timelines.
- Pump Action:Manual slide operation ensures functional reliability across temperature extremes and contamination exposure.
- Side-by-Side:Horizontal barrel arrangement persists in traditional upland hunting circles and historical shooting disciplines.
- Single Barrel:Simplified mechanics serve entry-level trap shooters and specialized turkey hunting applications.
Over-Under anchors the volume base while Semi-Automatic gains share at the steepest rate.
Application:
Pricing stratification across application types reflects equipment certification requirements rather than manufacturing cost differentials alone, with Olympic-eligible configurations commanding substantial premiums over recreational alternatives.
- Clay Target Shooting:Encompasses structured disciplines where standardized target presentations demand predictable shot pattern densities at measured distances. Concentrated demand flows through affiliated clubs in the United States and Italy that maintain standardized course layouts and equipment conformity protocols.
- Sporting Clays:Simulated field hunting presentations across varied terrain require adaptable choke configurations and swing dynamics. American enthusiasts drive expansion here, with facilities from Texas to Pennsylvania upgrading automated target delivery systems.
- Trap Shooting:Single-target emergence from below-ground bunkers emphasizes sustained lead technique and consistent gun mount.
- Skeet Shooting:Crossing target paths from fixed stations demand rapid barrel transition and precise timing.
- Hunting:Field applications prioritize weather sealing, sling attachment points, and durable finishes over competitive refinement.
Clay Target Shooting anchors the volume base while Sporting Clays climbs the fastest.
End User:
Customer lifetime value diverges sharply between institutional purchasers with standardized replacement schedules and individual enthusiasts whose acquisition patterns follow discretionary income cycles.
- Shooting Clubs:Institutional purchasers maintain fleet inventories for member rental and instructional programs. Italian and American clubs are expanding equipment rosters to accommodate membership growth, creating recurring demand for durable, standardized platforms.
- Professional Shooters:Sponsored athletes and coaching professionals require ISSF-certified equipment with documented conformity for international competition eligibility.
- Sports Enthusiasts:Recreational competitors pursue personal performance improvement through equipment upgrades without institutional procurement support.
- Hunters:Seasonal field practitioners prioritize reliability and weather resistance over competitive specifications.
- Law Enforcement Training:Agency programs require ruggedized platforms compatible with duty ammunition and tactical accessories.
Shooting Clubs anchors the volume base while Professional Shooters expands most quickly.
Distribution Channel:
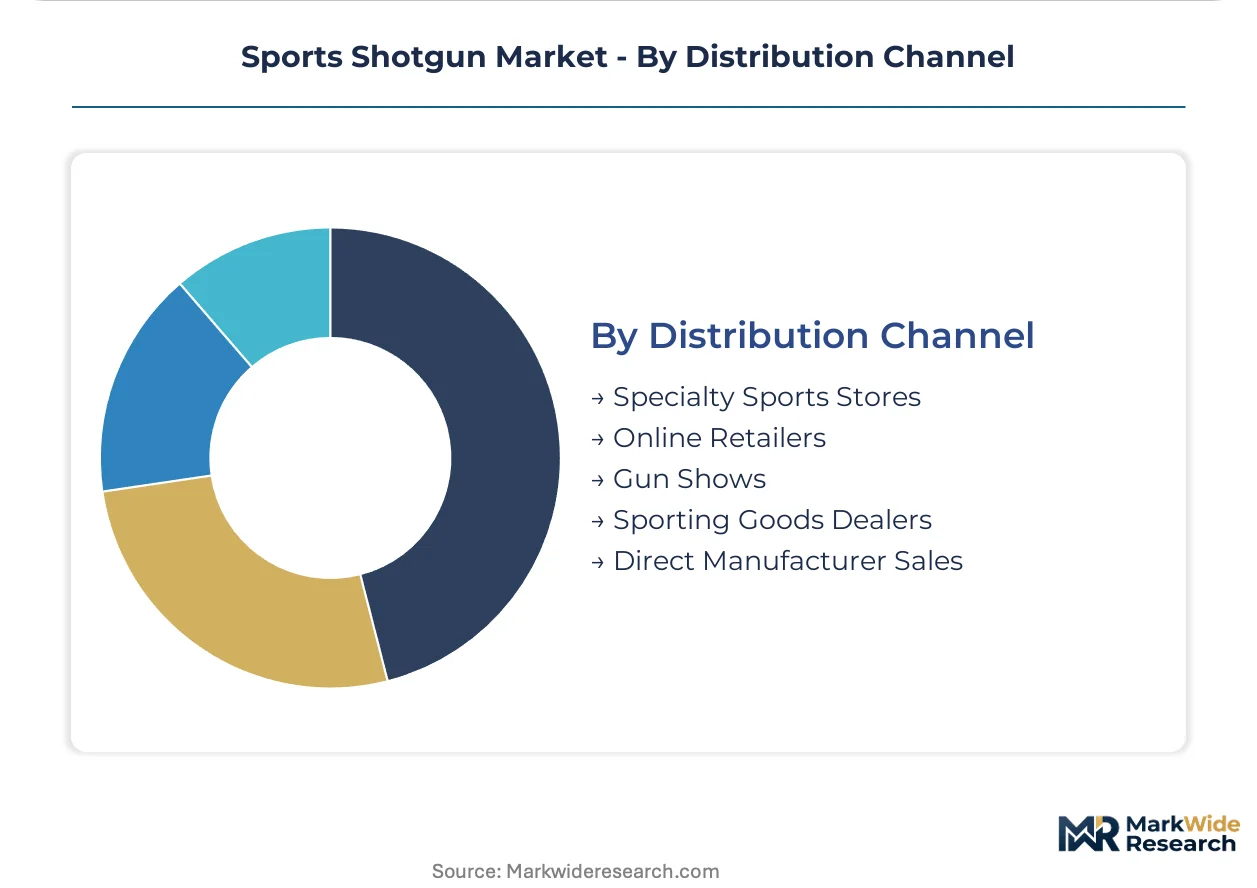
Channel economics reflect regulatory compliance burdens that favor specialized expertise over transactional efficiency, with background check procedures creating friction that generalist retailers avoid.
- Specialty Sports Stores:Licensed dealers with ATF Federal Firearms Licenses manage NICS background check protocols and maintain compliant transfer records. These establishments capture premium margins through fitting services and aftermarket accessory sales.
- Direct Manufacturer Sales:Beretta, Perazzi, and Blaser operate flagship showrooms and event-based direct channels that capture full margin and customer relationship data.
- Online Retailers:Digital platforms facilitate research and price comparison, though physical transfer through licensed dealers remains mandatory.
- Sporting Goods Dealers:Generalist retailers with firearms departments serve casual purchasers seeking convenience over expertise.
- Gun Shows:Temporary exhibition venues enable manufacturer demonstrations and immediate inventory liquidation.
Specialty Sports Stores anchors the volume base while Direct Manufacturer Sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian manufacturers in the Brescia-Gardone Val Trompia cluster export finished shotguns to the United States, Germany, and the United Kingdom, with clay target shooting clubs driving recurring procurement cycles across these destination markets.
United States
Specialty retailers with ATF Federal Firearms Licenses manage NICS background check protocols that extend procurement timelines for semi-automatic platforms. The Bureau of Alcohol, Tobacco, Firearms and Explosives regulates commercial transfers through mandatory screening procedures. Texas, Pennsylvania, and California shooting clubs are expanding automated target delivery systems and upgrading rental fleet inventories.
Italy
Olympic trap and skeet competitors sustain demand for hand-fitted Over-Under configurations with documented ISSF conformity. The European Union's Firearms Directive establishes minimum civilian possession standards that manufacturers must satisfy for intra-EU distribution. The Brescia-Gardone Val Trompia cluster maintains concentrated barrel-forging and action-machining capacity with vertically integrated alloy sourcing.
Germany
Precision engineering traditions support premium-tier hunting and competitive shooting equipment with emphasis on adjustable stock geometry. REACH Annex XVII restrictions on lead ammunition accelerate R&D investment in steel-shot-compatible barrel specifications. Bavarian and Baden-Württemberg fabricators specialize in linear-action platforms that reduce muzzle flip for rapid second shots.
Turkey
Ankara and Konya-based producers capture mid-market share through CNC machining investments that challenge Italian heritage positioning on price-performance metrics. The country's national firearms regulator oversees export certification timelines that match against product development cycles. Central Anatolian manufacturing zones are scaling output for North American and European distribution channels.
United Kingdom
Traditional upland hunting circles sustain demand for Side-by-Side configurations alongside Olympic-eligible trap and skeet equipment. The country's national firearms licensing authority maintains stringent possession category requirements that shape import eligibility. Southern England shooting estates and Scottish grouse moors drive seasonal replacement cycles for field-durable platforms.
Sports Shotgun Market Competitive Landscape
On the supply side, the industry is structured around heritage manufacturers with century-long craft traditions competing against scaled CNC producers from emerging manufacturing zones. Italian and German fabricators anchor the premium tier through hand-fitted engineering and Olympic certification dominance. Turkish producers occupy the mid-market through automated machining efficiency. Competitive moves center on barrel metallurgy R&D for lead-free ammunition compatibility and direct-to-consumer channel expansion that captures margin and customer data.
Within the heritage-manufacturer tier, Fabbrica d'Armi Pietro Beretta S.p.A. and Armi Perazzi S.p.A. exemplify vertically integrated Italian engineering with concentrated production in the Brescia-Gardone Val Trompia cluster. Blaser GmbH occupies a position among German precision fabricators specializing in linear-action configurations. These three entities represent distinct competitive archetypes: vertically integrated Italian heritage, Olympic-certified hand-craftsmanship, and German mechanical innovation.
| Leading Market Players |
|---|
| Fabbrica d'Armi Pietro Beretta S.p.A. |
| Armi Perazzi S.p.A. |
| Blaser GmbH |
| H. Krieghoff GmbH |
| Caesar Guerini S.r.l. |
| Browning Arms Company |
| Benelli Armi |
| O.F. Mossberg & Sons, Inc. |
| Winchester Repeating Arms |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Turkish semi-finished receivers entering the United States and European Union simultaneously compresses mid-market margins and accelerates sourcing diversification toward Ankara and Konya producers. This regulatory chokepoint widens pricing spreads between heritage Italian configurations and CNC-machined alternatives while reshaping inventory positioning across specialty retailers.
Pricing Analysis
Carbon-fiber-wrapped barrel technology commands substantial premiums over conventional steel monobloc configurations, while prior-generation steel-heavy platforms face accelerated depreciation. Three-tier pricing structure across premium hand-fitted, standard CNC-machined, and economy Turkish-produced levels reflects certification grade and Olympic eligibility status. Pricing pressure stems from REACH compliance costs for lead-free barrel engineering that manufacturers cannot fully pass to clay target clubs. Sports enthusiasts exhibit highest price sensitivity, whereas ISSF-certified professional shooters absorb premiums for documented conformity.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Ankara and Konya-based CNC specialists that challenge Italian heritage positioning on throughput metrics. Geographic supply concentration centers on Italy, Turkey, and Germany for finished platforms, with the Brescia-Gardone Val Trompia cluster controlling premium barrel-forging inputs. Raw material dependencies draw from nickel-chromium-molybdenum alloy steels, walnut stock blanks, and synthetic composite fibers. Single-source vulnerability persists in master gunsmith apprenticeship pipelines that cannot scale through automation. Distribution runs through ATF-licensed specialty retailers that manage NICS compliance friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular choke tube interoperability and adjustable stock ecosystems are transforming platform loyalty into attachment-rate economics, rewarding manufacturers that engineer across aftermarket ecosystems rather than defend proprietary configurations.
For Market Incumbents: Entrench position through captive supply of nickel-chromium-molybdenum alloys in the Val Trompia cluster and accelerated certification investment for ISSF Olympic eligibility. Turkish CNC producers threaten mid-market share through price-performance metrics that Italian heritage manufacturers cannot match on cost alone. Backward integration into barrel steel sourcing and direct-to-consumer channel expansion represent critical defensive levers against margin compression. For New Entrants and Emerging Players: American sporting clays enthusiasts in Texas and Pennsylvania represent underpenetrated demand for semi-automatic platforms with reduced recoil engineering. White-space targets include lead-free ammunition-compatible barrel specifications ahead of California's mandate expansion and EU-wide REACH sunset dates. A go-to-market angle through club armorers and independent gunsmith subscription services bypasses established specialty retail gatekeepers. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors manufacturers with validated alternative-shot barrel engineering and direct channel infrastructure. Long-term viability over the next decade hinges on lead-free mandate readiness and carbon-fiber manufacturing scale. Acquisition targets should demonstrate ISO-certified production and established ISSF conformity documentation. Quarterly tracking of ECHA restriction timelines and ATF import approval backlogs provides early inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Barrel Engineering Certification | REACH Annex XVII compliance creates first-mover advantage ahead of EU wetland shooting restrictions. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned platforms capture full margin and customer relationship data from ATF-licensed specialty retailers. |
| Carbon-Fiber Barrel Manufacturing Scale-Up | Weight reduction of 35-40 percent forward of the hinge pin displaces conventional steel monobloc demand. |
| Aftermarket Ecosystem Interoperability | Modular choke tube standardization fragments proprietary loyalty and shifts value toward attachment-rate economics. |
| Master Gunsmith Apprenticeship Pipeline | Hand-fitted lockwork scarcity constrains premium Over-Under output and defends Italian heritage pricing power. |
Research Methodology
Initial hypotheses were tested against primary input from Olympic shooting coaches, ATF-licensed specialty retailers, club armorers, and barrel metallurgy engineers and refined through secondary validation. Primary fieldwork encompassed structured discussions with competitive shooters, gunsmiths, and distribution channel managers across the United States, Italy, and Germany. Secondary sources drew from ATF transfer statistics, ECHA restriction timelines, ISSF equipment conformity protocols, and trade customs data. Bottom-up demand modeling triangulated against top-down production capacity estimates from the Brescia-Gardone Val Trompia cluster and Central Anatolian manufacturing zones.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for Over-Under, semi-automatic, and pump action configurations. Segmentation dimensions encompassed product type, application discipline, end-user category, and distribution channel regulatory burden. CAGRs were derived from replacement cycle analysis differentiated between competitive shooters and hunting enthusiasts, cross-referenced against club membership expansion rates and equipment inventory upgrade schedules. Industry-specific inputs included NICS procedural friction coefficients and REACH compliance cost pass-through assumptions.
Practitioners should monitor ECHA lead ammunition restriction enforcement, ATF import approval timeline volatility, and Turkish manufacturing capacity expansion for early signals of forecast revision. Quarterly review of club membership growth, alternative-shot barrel warranty claim rates, and carbon-fiber adoption curves among elite competitors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Small Arms Market