
 Cluster Munitions Market | 2026-2036
Cluster Munitions Market Size, Share, and Industry Trends Forecast 2026-2036
Cluster Munitions Market Outlook
Modular warhead packaging is realigning procurement preferences across defense ministries. Textron Systems leverages its integrated design-to-field architecture for air-delivered payloads. NORINCO sustains manufacturing scale across multiple caliber families for ground forces. Lockheed Martin dominates precision-guided dispenser integration with its established aerospace supply chain.
Cluster munitions are explosive weapons containing multiple submunitions dispersed over a target area, typically ranging from under one kilogram to several kilograms per bomblet, designed for area denial and anti-materiel effect against concentrated assets. Air-dropped configurations retain the largest value share given their integration with fixed-wing and rotary platforms, while ground-launched systems represent the fastest-expanding category due to multiple-launch rocket system modernization programs. Deployment mode selection increasingly favors automated systems as armed forces reduce personnel exposure during artillery preparation sequences.
The Convention on Cluster Munitions shapes export eligibility for signatory states, while the US Department of Defense maintains stockpile standards through its own unexploded-ordnance mitigation protocols. China's SAMR and military procurement channels enforce domestic content requirements that limit foreign supplier participation. Stakeholders must monitor evolving national ratification positions and submunition reliability benchmarks to anticipate contract accessibility shifts.
Market Dynamics
The Convention on Cluster Munitions and national stockpile modernization mandates are creating divergent procurement pathways, with signatory states pursuing retirement protocols while non-signatories accelerate reliability upgrades and automated deployment systems.
Growth Catalysts
- Multiple-Launch Rocket System Modernization:Armed forces across Eastern Europe and Southeast Asia are replacing legacy tube artillery with precision-guided rocket platforms that integrate cluster dispenser units for area denial missions.
- US Department of Defense Unexploded Ordnance Mitigation Protocols:Self-destruct fuze requirements and submunition reliability benchmarks above 99% are driving next-generation procurement specifications that favor advanced manufacturing capabilities.
- Territorial Defense Postures in the Asia-Pacific Theater:Island chain defense strategies and anti-access area denial doctrines are prioritizing ground-launched cluster systems for coastal saturation and airfield interdiction roles.
Market Restraints
- Input Cost Volatility in Precision Electronics:Miniaturized guidance components and programmable fuze systems face supply concentration in Taiwanese semiconductor foundries and Japanese specialty chemical suppliers.
- Regulatory Friction from the Convention on Cluster Munitions:The 112-state treaty network restricts technology transfer, joint development, and transit rights for non-signatory producers seeking access to European and Latin American defense markets.
- Technical Limitation in Submunition Footprint Reduction:Reliability engineering constraints prevent simultaneous achievement of smaller bomblet dispersion patterns and the 99%+ detonation rates mandated by modern stockpile standards.
Strategic Opportunities
- Underpenetrated Demand in the Middle East:Gulf Cooperation Council members are expanding indigenous munitions production partnerships to reduce dependence on external supply chains for rocket artillery systems.
- Technology Convergence of Cluster Dispensers and Loitering Munitions:Integration of air-delivered submunition carriers with autonomous terminal guidance is creating hybrid weapon categories for time-sensitive target engagement.
- China's Military-Civil Fusion Procurement Channels:SAMR and state defense conglomerates are opening dual-use manufacturing partnerships for precision fuze technologies previously restricted to state-owned enterprises.
Industry Challenges
- Skill Gap in Reliability Engineering:The specialized workforce for statistical failure analysis and accelerated life testing of submunition fuzes is concentrated among aging cohorts at US and Russian defense laboratories.
- Capex Intensity in Automated Assembly Lines:Cleanroom manufacturing environments for electro-explosive device integration require capital commitments that exceed mid-tier defense contractor balance sheet capacity.
- Certification Timeline Compression:National military acceptance testing for new cluster munition variants extends 48-60 months, creating mismatch with rapid procurement cycles demanded by contingency stockpiling programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cluster Munitions Market |
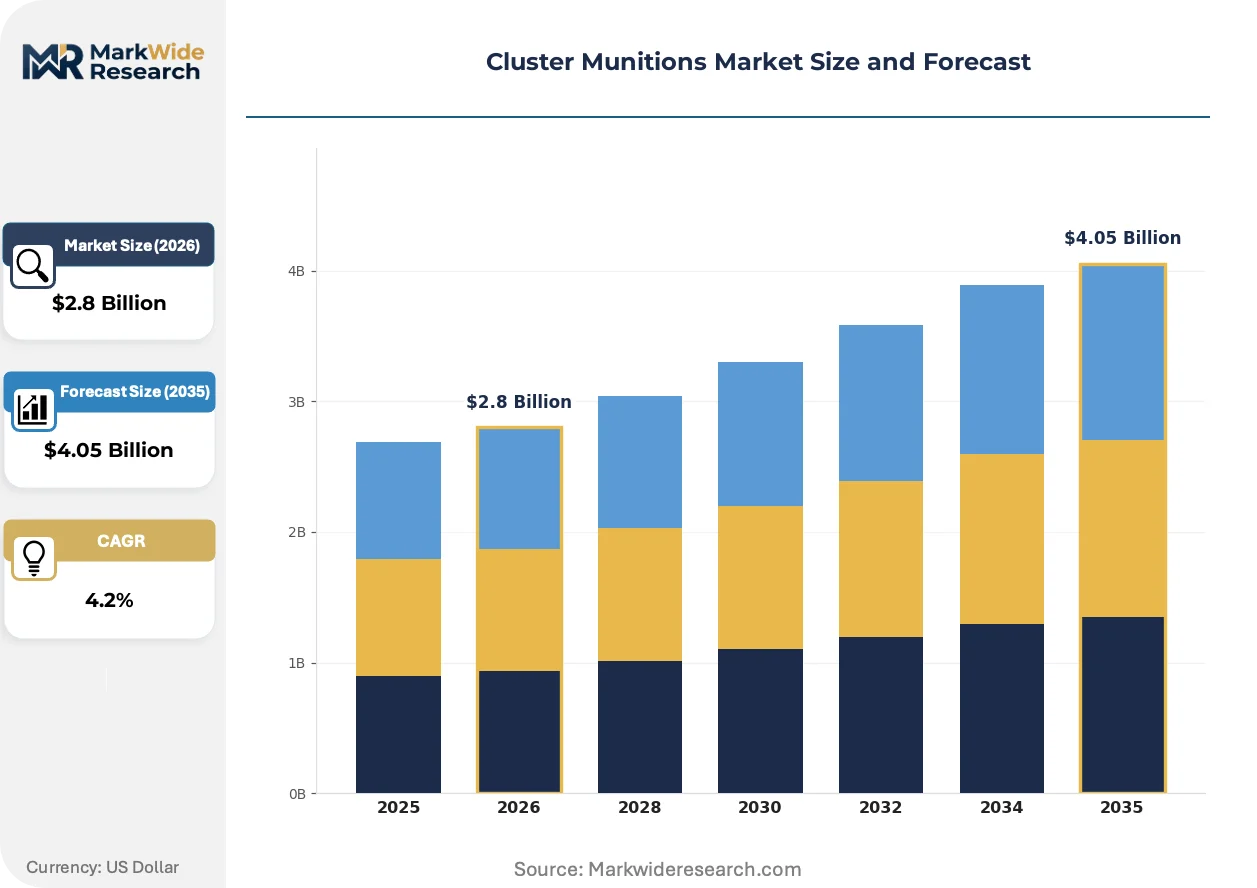
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Dropped, Ground-Launched, Sea-Launched, Naval Approaches Application: Military Operations, Humanitarian Missions, Peacekeeping, Emergency Response End User: Armed Forces, Government Organizations, NGOs, Defense Contractors Deployment Mode: Manual Deployment, Automated Systems, Aerial Deployment, Tracked Systems |
| Companies Covered | Textron Systems, NORINCO, Lockheed Martin, China Aerospace Science and Industry, Hanwha, Poongsan, Avibras, Bharat Dynamics Limited, LIG Nex1, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cluster Munitions Market Strategic Shifts
Modular payload architectures and programmable dispersion patterns are displacing fixed-configuration cluster systems, enabling mission-specific loadouts without platform modification.
Self-destruct and self-neutralizing fuze technologies is consolidating supplier capabilities around integrated safety-arming systems that eliminate unexploded ordnance risk. Defense ministries in Poland, South Korea, and Turkey are mandating these mechanisms for all new rocket artillery acquisitions. The technology is consolidating procurement decisions toward vendors with captive fuze production rather than subsystem integrators.
REACH restrictions on lead styphnate and mercury fulminate priming compounds are forcing reformulation of electro-explosive device chemistry across European supply chains. German and French ordnance producers face 2026 deadlines for green energetic material transition. Ground-launched cluster systems with high round consumption rates are experiencing the steepest cost adjustments as alternative primers require redesigned ignition trains.
Buyer concentration around national armament directorates is compressing negotiation leverage for component suppliers. South Korea's DAPA and Poland's Armament Agency now bundle cluster munition procurement with platform acquisition contracts, eliminating standalone subsystem competitions. This pattern is most visible in NATO's eastern flank, where territorial defense spending consolidates through government-to-government agreements rather than open tenders.
Cluster Munitions Market Segmentation
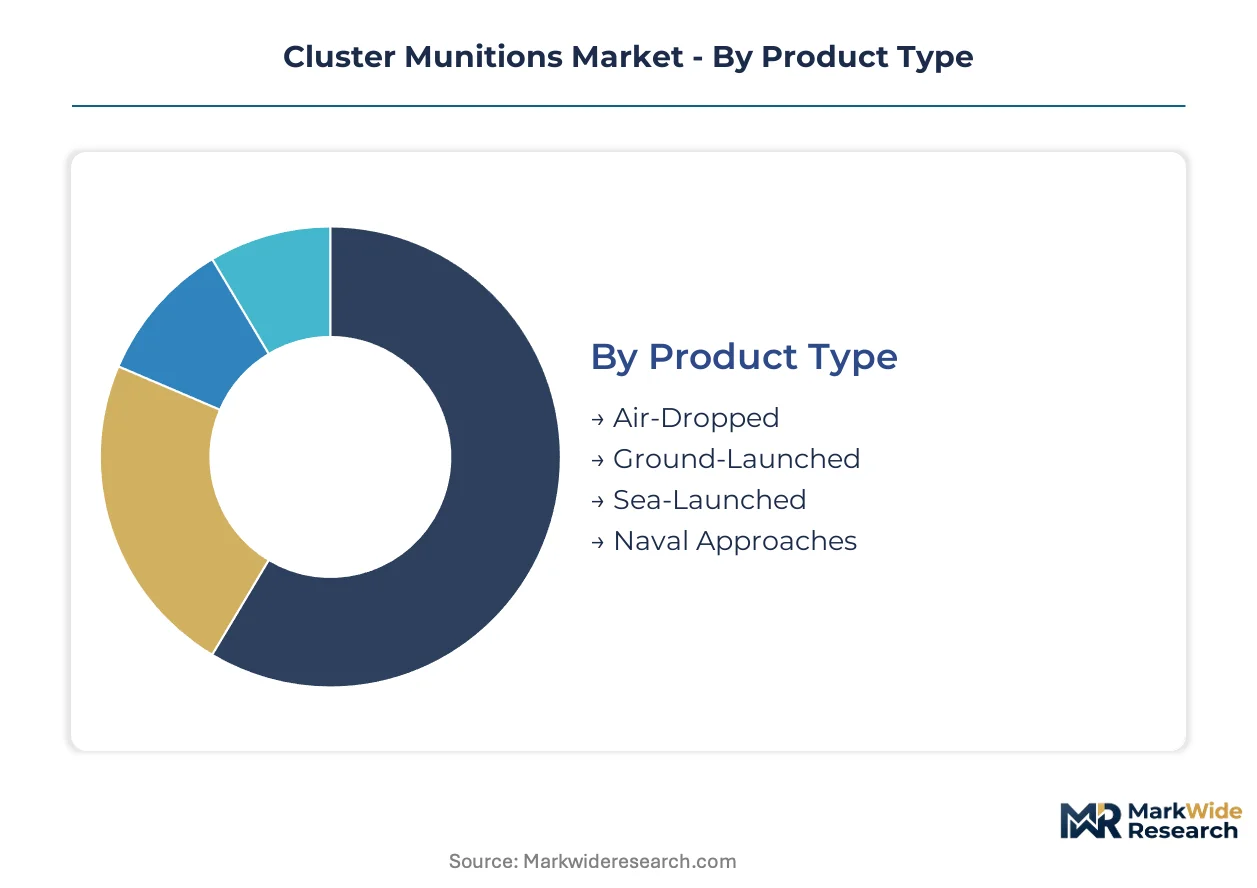
Cluster munition procurement channels fragment across platform integration requirements, end-use certification protocols, and national stockpile standards. Segment boundaries shift as defense ministries bundle dispenser systems with launcher platforms, compressing standalone subsystem markets.
Product Type:
US Department of Defense unexploded ordnance mitigation protocols mandate 99% reliability benchmarks for air-delivered systems, while ground-launched categories face divergent national acceptance testing timelines.
- Air-Dropped:Fixed-wing and rotary platform integration dominates procurement value, with dispenser units engineered for programmable dispersion patterns and self-destruct fuze compliance. Demand concentrates in US Air Force and allied NATO inventory modernization programs driven by area denial doctrine requirements.
- Ground-Launched:Multiple-launch rocket system modernization across Poland, South Korea, and Turkey is accelerating procurement of precision-guided cluster dispenser units. These systems face the steepest cost adjustments from REACH-mandated green energetic material transitions in European supply chains.
- Sea-Launched:Naval surface fire support applications require corrosion-resistant dispenser architectures.
- Naval Approaches:Coastal saturation missions integrate with littoral combat platform magazines.
Leading the category by volume: Air-Dropped. Growing fastest: Ground-Launched.
Application:
Defense procurement authorization tiers separate military operations from restricted humanitarian access, with Convention on Cluster Munitions signatory states blocking certain application categories entirely.
- Military Operations:Area denial and anti-materiel missions against concentrated assets constitute the core demand driver, with mission planning software now integrating collateral damage estimation modules for legal compliance documentation.
- Peacekeeping:Restricted to non-signatory state contributions under UN mandate protocols.
- Humanitarian Missions:Convention treaty networks prohibit cluster munition use in disaster response.
- Emergency Response:No operational deployment recorded; category exists for legislative contingency framing only.
Dominant application: Military Operations. Most restricted: Humanitarian Missions.
End User:
Budget authorization thresholds and technology transfer classification levels segment procurement access, with defense contractors requiring end-user certificates for subsystem component sales.
- Armed Forces:National armament directorates in South Korea's DAPA and Poland's Armament Agency bundle cluster munition procurement with platform acquisition contracts, eliminating standalone subsystem competitions for tube artillery and rocket launcher programs.
- Defense Contractors:Prime integrators face consolidation pressure as buyer concentration compresses negotiation leverage for fuze and dispenser subsystems.
- Government Organizations:Civil defense stockpiles operate under separate reliability testing protocols.
- NGOs:Convention advocacy groups monitor stockpile transparency; no procurement authorization.
Primary procurement authority: Armed Forces. Fastest contract velocity: Defense Contractors.
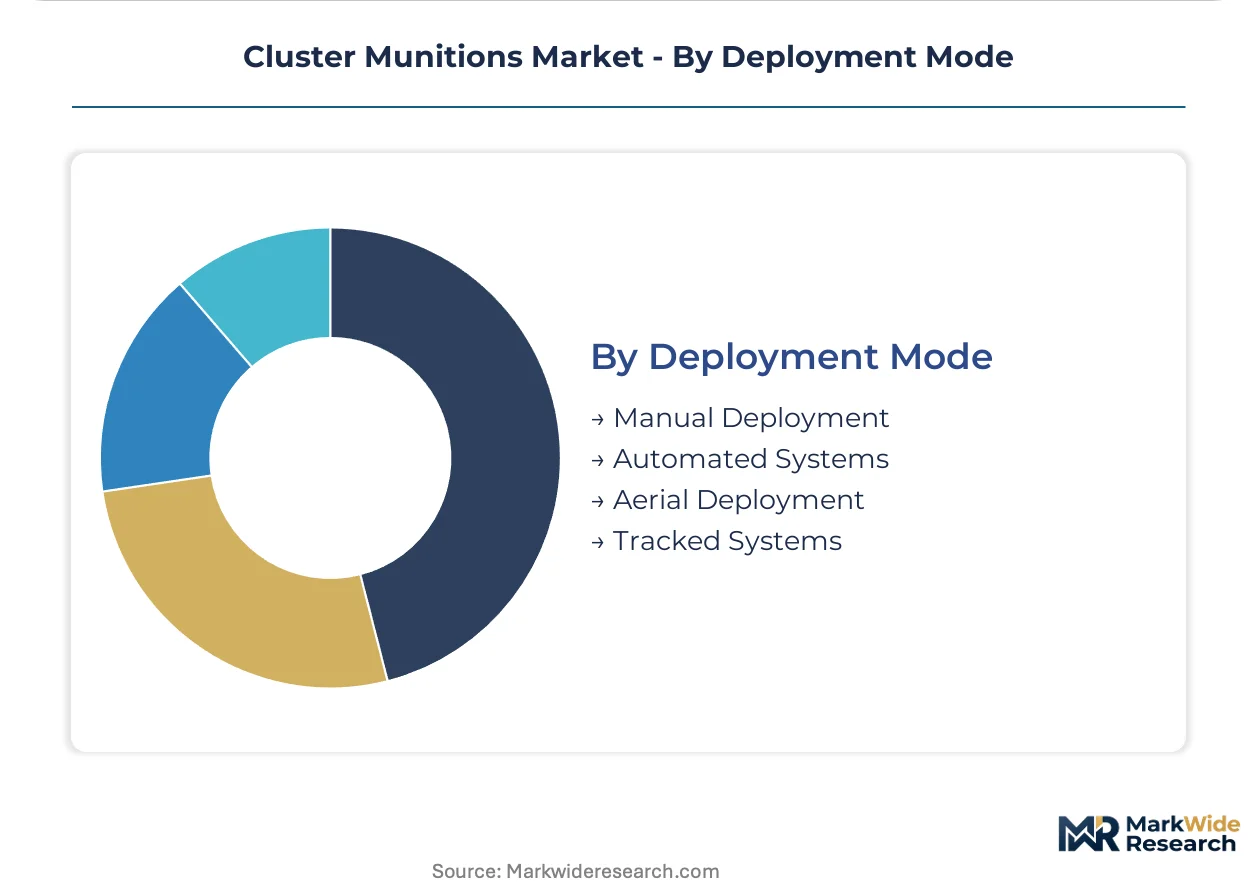
Deployment Mode:
Personnel exposure reduction mandates are shifting procurement specifications toward automated systems, with manual deployment modes restricted to legacy stockpile drawdown operations.
- Automated Systems:Fire-control integration with multiple-launch rocket platforms enables programmable ripple salvo patterns without crew exposure during artillery preparation sequences, meeting modern force protection doctrine requirements.
- Aerial Deployment:Remotely piloted aircraft integration is displacing manned platform delivery for time-sensitive target engagement missions.
- Manual Deployment:Legacy artillery crews retain authorization for emergency firing procedures only.
- Tracked Systems:Self-propelled launcher mobility supports shoot-and-scatter tactics against counter-battery radar.
Standard configuration: Automated Systems. Steepest procurement decline: Manual Deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones in South Korea and Poland are accelerating cluster munition procurement through government-to-government agreements. Special economic zones in China's Sichuan-Chongqing corridor sustain manufacturing scale for precision fuze technologies. Turkey's defense technology parks are integrating automated deployment systems for multiple-launch rocket platforms.
United States
The US Department of Defense maintains stockpile modernization through unexploded ordnance mitigation protocols mandating 99% submunition reliability. Congressional defense authorization acts fund next-generation dispenser integration with fixed-wing platforms. Textron Systems leverages its integrated design-to-field architecture from facilities in Rhode Island and Louisiana.
South Korea
DAPA bundles cluster munition procurement with K239 Chunmoo rocket launcher acquisition contracts. The Defense Acquisition Program Administration enforces domestic content requirements that limit foreign subsystem participation. Hanwha Aerospace and LIG Nex1 operate manufacturing clusters in Changwon and Daejeon-Sejong for precision-guided dispenser units.
Poland
The Armament Agency consolidates territorial defense spending through government-to-government agreements with South Korean suppliers. NATO's eastern flank posture prioritizes ground-launched cluster systems for coastal saturation missions. WB Electronics and local defense primes are establishing assembly partnerships in the Łódź Voivodeship.
China
SAMR and military procurement channels enforce domestic content requirements through the military-civil fusion framework. State defense conglomerates open dual-use manufacturing partnerships for precision fuze technologies. NORINCO and China Aerospace Science and Industry sustain manufacturing scale across Sichuan and Beijing-Tianjin-Hebei corridors.
Turkey
Roketsan and state defense primes are expanding indigenous production for TRG-300 and Khan multiple-launch rocket systems. The Presidency of Defense Industries mandates self-destruct fuze compliance for all new artillery acquisitions. Defense technology parks in Ankara and Konya host automated assembly lines for electro-explosive device integration.
Cluster Munitions Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement channels. The vendor base organizes into three tiers: aerospace primes with captive dispenser design capabilities, state-owned defense conglomerates with integrated manufacturing scale, and regional subsystem integrators serving national armament directorates. Market entry barriers concentrate around certification timelines extending 48-60 months and capital intensity in cleanroom manufacturing environments. Competitive positioning depends on backward integration into fuze production and established relationships with national procurement authorities.
Among US-based aerospace primes, Lockheed Martin exemplifies the dispenser integration archetype through established aerospace supply chain relationships. Textron Systems occupies a position within the air-delivered payload segment, leveraging integrated design-to-field architectures. State-owned Asian conglomerates including NORINCO and China Aerospace Science and Industry represent manufacturing-scale archetypes with domestic market protection through SAMR procurement channels. South Korean specialists Hanwha and LIG Nex1 sit within the regional subsystem integrator tier, capturing contracts from DAPA's bundled procurement programs.
| Leading Market Players |
|---|
| Textron Systems |
| NORINCO |
| Lockheed Martin |
| China Aerospace Science and Industry |
| Hanwha |
| Poongsan |
| Avibras |
| Bharat Dynamics Limited |
| LIG Nex1 |
| Others |
Value Chain & Pricing Dynamics
Specialty chemical feedstock indices for energetic materials cascade through three-tier pricing structures across premium, standard, and economy levels, with REACH-mandated green primer transitions forcing cost absorption decisions at German and French ordnance producers.
Pricing Analysis
Margin tightening in ground-launched systems reflects reformulation costs for lead-free electro-explosive devices. Contract-based long-term offtake dominates procurement, with price differentiation hinging on certification grade against US Department of Defense 99% reliability protocols and volume scale for bundled platform acquisitions. Cost-down pressure on European supply chains accelerates because SAMR domestic content requirements exclude foreign subsystem bidders from Chinese military procurement channels. Defense contractors exhibit highest price sensitivity due to compressed negotiation leverage, while national armament directorates leverage bundled contracts for standard-tier sourcing.
Supply Chain Analysis
Precision fuze manufacturing rests on Taiwanese semiconductor foundries for miniaturized guidance components, Japanese specialty chemical suppliers for energetic materials, and German cleanroom facilities for electro-explosive device integration. Raw material dependencies span rare earth elements for magnetic components, high-purity aluminum for casing alloys, and specialty polymers for insulation systems. Single-source vulnerability concentrates in Taiwanese wafer fabrication for programmable fuzes. Distribution runs through national armament directorates with government-to-government agreements displacing open tender channels across NATO's eastern flank.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive fuze production represents the decisive competitive lever as certification timelines and cleanroom capital intensity erect barriers against subsystem integrators.
For Market Incumbents: Cement procurement relationships with South Korea's DAPA and Poland's Armament Agency through co-development agreements for K239 Chunmoo and Homar rocket launcher programs. Acquire distressed precision fuze capabilities in Germany's Saxony region before REACH transition deadlines eliminate mid-tier competitors. Counter emerging threat from China's military-civil fusion procurement channels by accelerating self-destruct fuze compliance roadmaps. For New Entrants and Emerging Players: The premium-to-economy price gap in ground-launched cluster systems opens white-space entry through green energetic material reformulation services for legacy European stockpiles. Target underpenetrated demand in Gulf Cooperation Council indigenous production partnerships, particularly Saudi and UAE rocket artillery localization programs. Pursue dual-use manufacturing credentials through SAMR channels for precision fuze subsystem supply to Chinese state defense conglomerates. For Investors and Strategic Acquirers: Distressed-cycle entries favor cleanroom manufacturing assets in Germany and France facing 2026 energetic material transition deadlines. Long-term viability frames around 5-10 year modernization cycles for multiple-launch rocket systems across Eastern Europe and Southeast Asia. Acquisition target archetype: mid-tier fuze specialists with statistical failure analysis capabilities concentrated at aging US and Russian defense laboratories. Monitor ratification shifts in the Convention on Cluster Munitions as inflection indicator for export market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuze Production | Eliminates supplier concentration risk from Japanese and Taiwanese specialty component producers. |
| Green Energetic Material Transition | Positions European ordnance producers ahead of REACH-mandated 2026 deadlines for lead-free primers. |
| Government-to-Government Agreement Expansion | Secures bundled procurement access through South Korea's DAPA and Poland's Armament Agency channel consolidation. |
| Dual-Use Manufacturing Partnership | Opens SAMR procurement channels for precision fuze technologies under China's military-civil fusion framework. |
| Self-Destruct Fuze Certification Investment | Meets US Department of Defense unexploded ordnance mitigation protocols for 99% reliability compliance. |
Study Parameters
Document review covered defense procurement authorization acts, national stockpile transparency reports, and Convention on Cluster Munitions state party declarations, complemented by interviews with program managers at national armament directorates, reliability engineering leads at US and Russian defense laboratories, procurement officers at prime aerospace integrators, and regulatory affairs specialists tracking SAMR and REACH implementation. Secondary validation drew from customs trade data for energetic materials, SEC 10-K filings for defense contractor segments, and national military acceptance testing records. Bottom-up platform procurement forecasts were triangulated against top-down defense budget authorization trends.
Cross-referencing historical modernization cycle patterns with expert panel input on territorial defense posture shifts shaped the analytical framework across the analysis window. Segmentation modeling incorporated deployment mode automation levels, platform integration requirements for fixed-wing versus rotary versus rocket launcher systems, and national ratification status under the Convention on Cluster Munitions. CAGRs were derived from procurement authorization trajectories and stockpile replacement schedules. Industry-specific forecast inputs included multiple-launch rocket system modernization program announcements and unexploded ordnance mitigation protocol adoption timelines.
Underlying measurement precision varies by segment; air-dropped systems with established US Air Force inventory data carry tighter precision than emerging sea-launched categories with limited operational deployment records. Forecasts reflect assumptions around defense budget authorization continuity, certification timeline compression, and supply chain concentration in Taiwanese semiconductor foundries. A small set of triggers warrants ongoing watch: Convention on Cluster Munitions ratification reversals, REACH energetic material deadline extensions, and military-civil fusion procurement channel openings in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Weapon Mounts Market