
 Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market | 2026-2036
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market Insights
Software-defined ballistic calculation and weapon-integrated fire-control subscription layers is expanding what defense customers purchase beyond hardware. Singapore Technologies Engineering Ltd leverages vertical integration across precision engineering and systems integration to dominate Southeast Asian procurement cycles. PT Pindad anchors Indonesian self-sufficiency goals through captive manufacturing of NATO-standard rifles and ammunition lines. Elbit Systems Ltd specializes in electro-optical and fire-control add-ons that convert conventional small arms into digitally networked soldier-system nodes.
Small arms and ammunition encompasses portable firearms firing projectiles up to 20mm caliber, with cartridge construction involving brass casings, propellant loads, and priming systems manufactured through cold forging, metal injection molding, and progressive die stamping processes designed for individual soldier engagement and close-quarters security operations. The military end-user segment commands the largest volume commitment across the geography, with long-term framework agreements insulating suppliers from budget volatility. Rifles lead product-type revenue due to platform modernization cycles replacing aging battle carbines with modular, multi-caliber systems. Small-caliber ammunition sustains the highest throughput volumes, though medium-caliber linked rounds for squad automatic weapons are capturing margin pools as NATO-standardization pressures mount.
The UAE's Tawazun Council and Saudi Arabia's General Authority for Military Industries impose local-content thresholds that reshape supplier qualification and joint-venture requirements across the Middle East. Indonesia's Ministry of Defense offsets directives and South Africa's National Conventional Arms Control Committee export-control protocols further fragment market-access pathways. BIS certification requirements for Indian-origin components and Israel's Ministry of Defense procurement secrecy standards add compliance complexity for cross-border tenders. Stakeholders must monitor how Gulf localization deadlines interact with ASEAN indigenous-development timelines to anticipate where manufacturing partnerships will crystallize first.
Market Dynamics
Localization mandates from Saudi Arabia's General Authority for Military Industries and the UAE's Tawazun Council are restructuring supplier relationships across the Middle East, forcing foreign manufacturers into joint-venture arrangements that transfer production know-how to domestic entities.
Growth Catalysts
- Modular rifle platform modernization:ASEAN defense forces are retiring aging battle carbines for multi-caliber systems that reduce logistics burdens and extend service life cycles.
- Tawazun Council localization thresholds:The UAE's mandatory domestic-content requirements redirect supply chains toward in-country manufacturing partnerships and technology transfer agreements.
- SAMI in-house capacity scaling:Saudi Arabia's state-owned defense conglomerate is expanding captive small-arms production lines to reduce import dependency for military end-users.
Market Restraints
- Brass and propellant input cost volatility:Raw material price swings for cartridge casings and nitrocellulose propellants compress ammunition margins and destabilize long-term contract pricing.
- Supply concentration in precision forging equipment:Cold-forging machinery for barrel production remains concentrated among European and East Asian vendors, creating single-source vulnerabilities.
- India BIS certification complexity:Bureau of Indian Standards component approval timelines extend procurement cycles for manufacturers sourcing Indian-origin subsystems.
Strategic Opportunities
- Vietnam defense modernization acceleration:Hanoi is expanding its defense budget allocation for individual soldier systems, creating demand for NATO-standard rifle and ammunition procurement.
- Software-defined fire-control convergence:Integration of ballistic calculation algorithms with electro-optical sights is expanding addressable revenue per weapon platform beyond hardware sales.
- South African export-control pathway optimization:The National Conventional Arms Control Committee is streamlining licensing protocols for ammunition exports to approved defense partners.
Industry Challenges
- Progressive die stamping skill scarcity:Southeast Asian and African manufacturing bases lack sufficient technicians trained in high-volume cartridge casing production.
- Cross-border tender compliance fragmentation:Divergent secrecy standards between Israel's Ministry of Defense and ASEAN offset directives force suppliers to maintain parallel certification systems.
- Legacy weapon system integration complexity:Digital fire-control retrofits for existing rifle fleets require bespoke mechanical adaptation, slowing upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market |
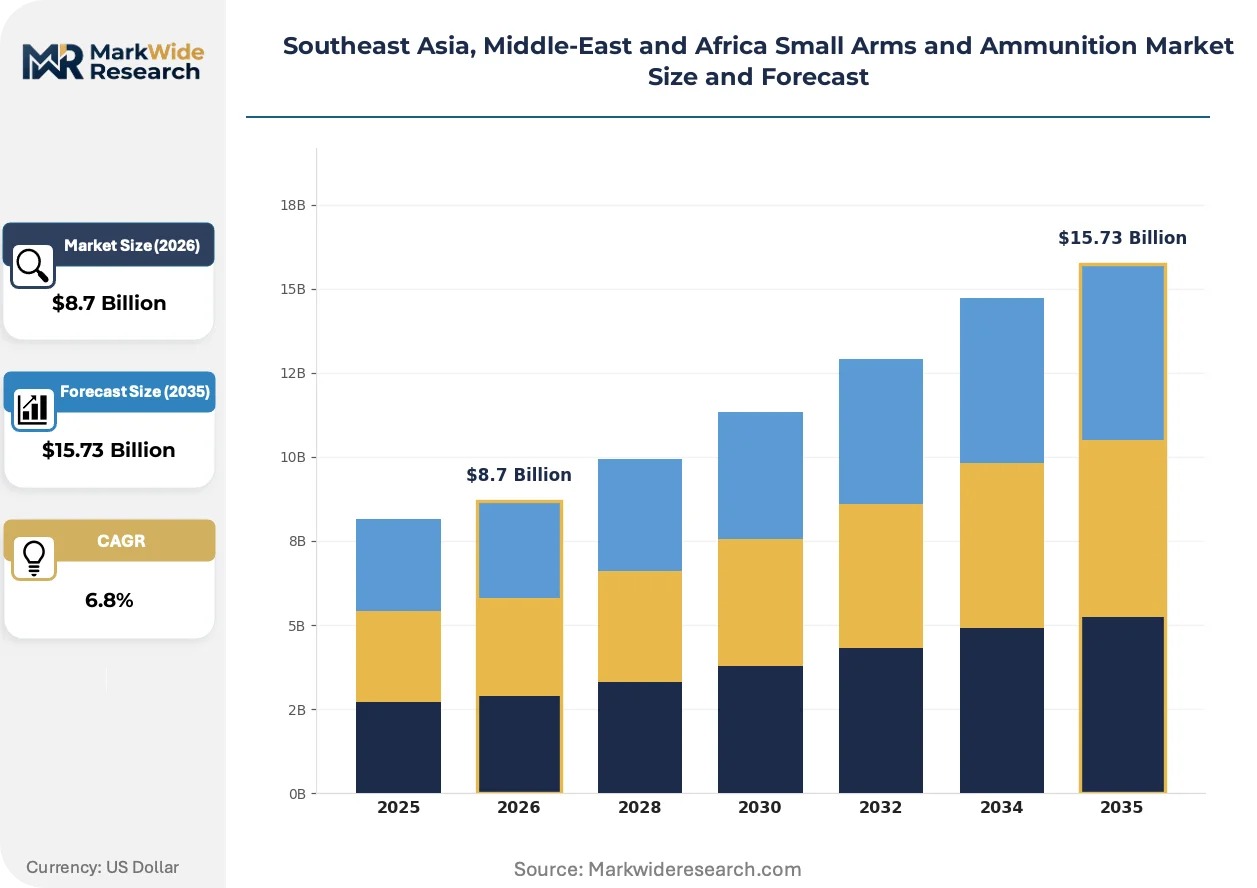
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rifles, Pistols, Shotguns, Machine Guns End User: Military, Law Enforcement, Civilian, Security Agencies Caliber Type: Small Caliber, Medium Caliber, Large Caliber, Others Distribution Channel: Retail, Online, Direct Sales, Wholesale |
| Companies Covered | Singapore Technologies Engineering Ltd, PT Pindad, Saudi Arabian Military Industries (SAMI), Israel Weapon Industries (IWI) Ltd, Elbit Systems Ltd, Rheinmetall AG, BAE Systems plc, General Dynamics Corporation, Kenya Ordnance Factories Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market Trends and Innovations
Weapon-integrated computing layers and ammunition manufacturing process digitization are expanding what defense customers procure, shifting value capture from physical hardware toward persistent software and service relationships.
Metal injection molding for receiver components is expanding into Southeast Asian supplier bases as Indonesian and Vietnamese manufacturers seek to bypass traditional machining capacity constraints. Defense procurement offices in Thailand and Malaysia are qualifying MIM-produced parts for non-stressed components, reducing unit costs and lead times. This process shift is expanding into adjacent fabrication categories as regional precision engineering capabilities mature.
Saudi Arabia's General Authority for Military Industries localization mandates now require 50 percent in-country value addition for small-arms contracts above specified thresholds. Foreign primes must establish joint ventures with SAMI subsidiaries or forfeit eligibility for framework agreements. Ammunition lines face the most compressed compliance timelines, with 2027 deadlines forcing rapid facility construction in Riyadh and Jeddah industrial zones.
Subscription-based ballistic calculation services are displacing standalone fire-control hardware purchases among advanced ASEAN military units. Singapore's defense technology agency pioneered software-defined sighting systems that receive over-the-air updates, and Philippine and Indonesian special operations commands are piloting similar arrangements. This consumption-pattern shift concentrates vendor relationships and extends contract durations beyond traditional acquisition cycles.
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market Segmentation
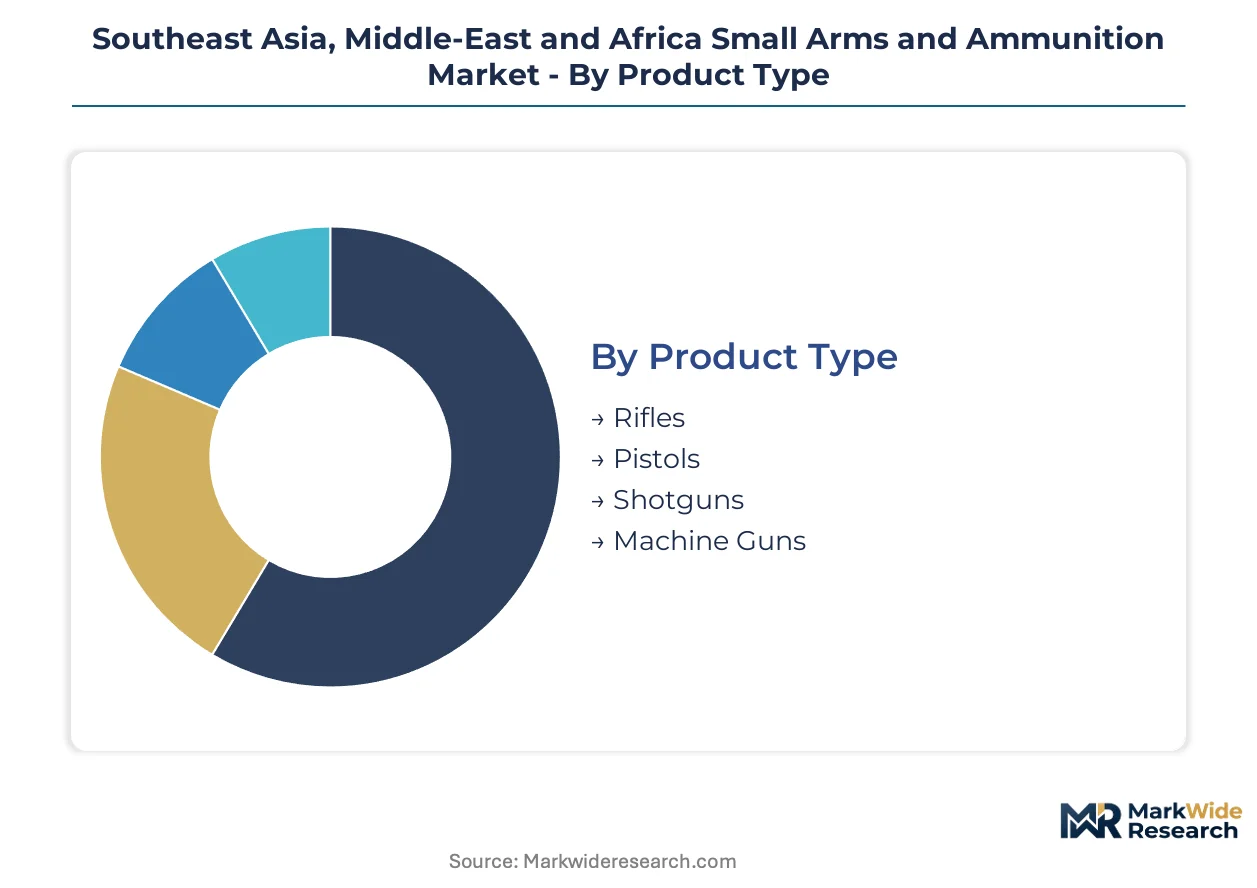
Segmentation in this market reveals how procurement patterns diverge across institutional buyers versus civilian channels, and how caliber standardization pressures reshape manufacturing priorities. Understanding these divides clarifies where localization mandates and technology transfer agreements will concentrate competitive positioning.
Product Type:
Modularity specifications and barrel interchangeability standards define competitive differentiation across weapon platforms.
- Rifles:Multi-caliber modular systems with quick-change barrel assemblies dominate ASEAN military modernization programs. Singapore, Indonesia, and Vietnam prioritize NATO-standard 5.56mm and 7.62mm configurations to simplify logistics chains and enable ammunition interoperability during joint exercises.
- Pistols:Polymer-frame striker-fired designs chambered in 9mm Parabellum capture law enforcement and security agency procurement across the Middle East. Saudi Arabia's SAMI and UAE's Tawazun-backed ventures target this segment for initial localization due to lower forging equipment barriers.
- Shotguns:Pump-action and semi-automatic 12-gauge variants serve riot control and door-breaching roles for African security services.
- Machine Guns:Belt-fed medium-caliber systems face concentrated demand from mechanized infantry units in Saudi Arabia and Algeria.
Mature deployment sits with Rifles. Newer deployment is concentrated in Pistols.
End User:
Procurement volume and contract duration vary sharply between sovereign defense budgets and commercial security spending.
- Military:Long-term framework agreements spanning 5-10 years insulate suppliers from budget volatility. Saudi Arabia's General Authority for Military Industries and Indonesia's Ministry of Defense drive the largest volume commitments through offset-mandated tenders.
- Law Enforcement:National police forces in Thailand, Malaysia, and South Africa standardize on sidearm platforms with centralized procurement. Ammunition throughput runs lower than military but replacement cycles compress due to training intensity.
- Civilian:Hunting and sport shooting demand concentrates in South Africa and select Gulf states with licensed ownership frameworks.
- Security Agencies:Private military contractors and facility protection services in Iraq, Nigeria, and Somalia drive demand for non-standard calibers outside formal defense channels.
Volume concentration rests with Military. Margin expansion is concentrated in Security Agencies.
Caliber Type:
Standardization pressures and logistics interoperability dictate procurement specifications across defense forces.
- Small Caliber:5.56mm NATO and 7.62x39mm cartridges sustain the highest production throughput globally. Southeast Asian manufacturers in Indonesia and Vietnam are expanding brass casing and propellant loading capacity to capture this volume.
- Medium Caliber:7.62mm NATO linked ammunition for squad automatic weapons and general-purpose machine guns is climbing the fastest as mechanized units modernize across Saudi Arabia and Algeria.
- Large Caliber:12.7mm and 14.5mm heavy machine gun rounds serve vehicle-mounted and anti-materiel roles with limited but stable demand.
- Others:Specialized subsonic and frangible formulations support special operations requirements in Israel and Singapore.
Production scale sits with Small Caliber. Technology transfer urgency is concentrated in Medium Caliber.
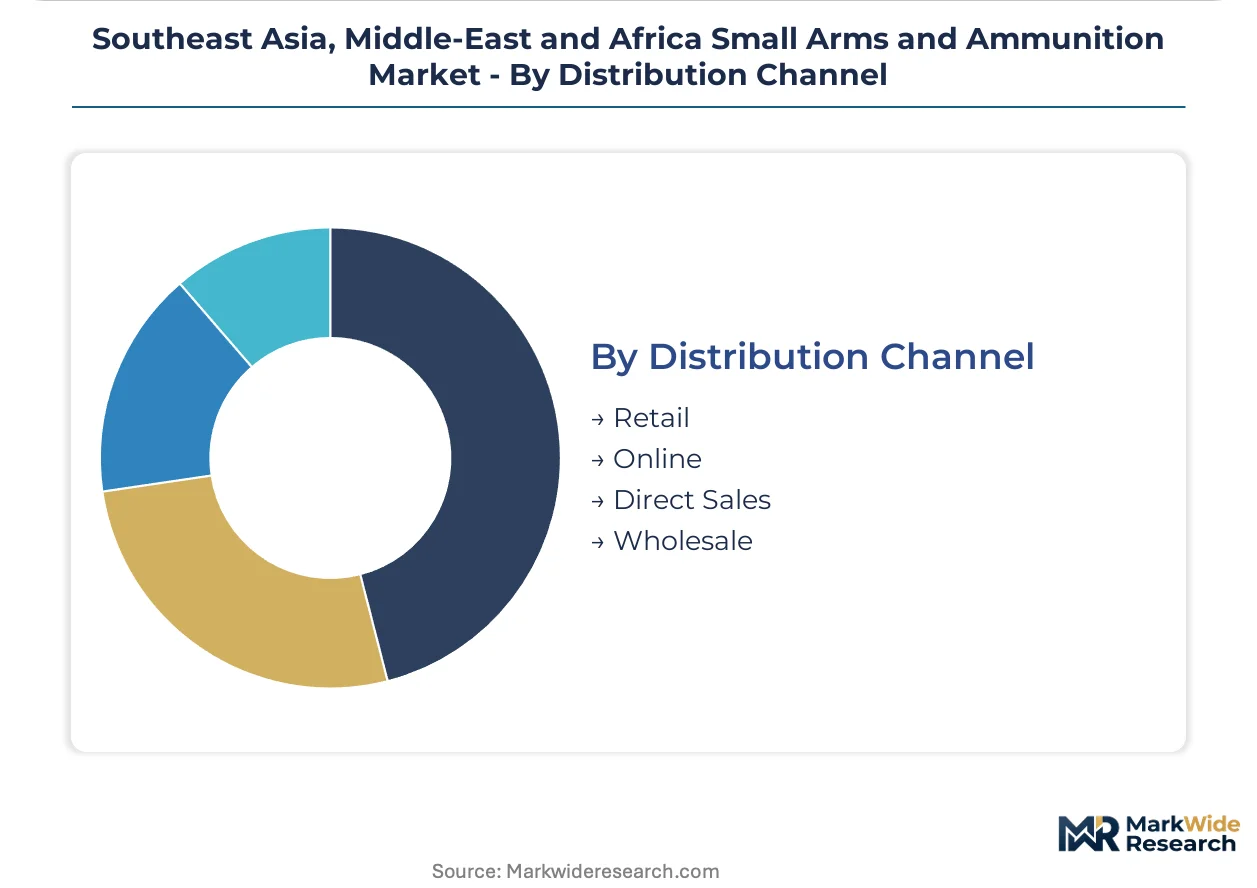
Distribution Channel:
Regulatory oversight and traceability requirements fragment channel access across the geography.
- Direct Sales:Government-to-government agreements and national defense procurement offices in Saudi Arabia, UAE, and Singapore dominate high-volume transactions. These channels bypass import licensing complexity for sovereign buyers.
- Wholesale:Regional distributors serving multiple African defense ministries aggregate demand to meet minimum order quantities for European and Asian manufacturers.
- Retail:Licensed firearms dealers in South Africa and Gulf states with civilian ownership laws serve sport shooting and hunting segments under strict end-user verification.
- Online:Digital platforms for accessories and non-controlled components operate in Thailand and Malaysia under BIS and national customs oversight.
Transaction volume sits with Direct Sales. Channel development is concentrated in Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Saudi Arabia and the UAE while consumption spreads across ASEAN defense modernization programs and African security services. Domestic manufacturing mandates are compressing import dependency ratios in Gulf states. Southeast Asian procurement offices prioritize NATO-standard interoperability over indigenous platform development.
Saudi Arabia
Mechanized infantry modernization and border security operations drive demand for medium-caliber linked ammunition and modular rifle platforms. The General Authority for Military Industries imposes 50 percent local-content thresholds on contracts above specified value thresholds, forcing joint-venture structures with SAMI subsidiaries. Industrial zones in Riyadh and Jeddah host rapid facility construction to meet 2027 ammunition line compliance deadlines.
United Arab Emirates
Special operations forces procurement and federal security agency modernization sustain demand for precision small arms and electro-optical fire-control systems. The Tawazun Council mandates domestic-content requirements that redirect supply chains toward in-country manufacturing partnerships and technology transfer agreements. Tawazun Precision Industries in Abu Dhabi anchors localization efforts through captive forging and machining capacity.
Indonesia
Army rifle replacement programs and naval infantry expansion drive NATO-standard 5.56mm and 7.62mm platform procurement. The Ministry of Defense offsets directives require foreign suppliers to establish co-production arrangements with PT Pindad for cartridge casing and propellant loading capacity. Bandung industrial complexes host captive manufacturing lines for brass casings and progressive die stamping operations.
South Africa
Police service standardization and regional peacekeeping commitments sustain demand for sidearm platforms and small-caliber training ammunition. The National Conventional Arms Control Committee regulates export licensing protocols while streamlining approval pathways for ammunition shipments to approved defense partners. Pretoria-Witwatersrand-Vereeniging manufacturing corridors concentrate precision forging and metal injection molding capabilities.
Vietnam
Individual soldier system modernization and maritime security force expansion accelerate defense budget allocation for NATO-standard rifle procurement. The Ministry of National Defense prioritizes interoperability with ASEAN joint exercise frameworks over legacy Warsaw Pact caliber retention. Hanoi-Haiphong industrial zones attract foreign precision engineering investment for barrel cold-forging equipment installation.
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across this geography. State-owned defense conglomerates in Saudi Arabia and Singapore anchor production capacity while European and Israeli specialists supply fire-control and electro-optical subsystems. The vendor base stratifies into three archetypes: integrated national champions, subsystem specialists, and foreign primes operating through joint-venture shells. Dominant competitive moves involve forced localization partnerships in Gulf markets and subscription-based software layers that extend contract durations beyond hardware replacement cycles.
Among Singapore-based integrated defense groups, Singapore Technologies Engineering Ltd occupies a position exemplifying vertical control across precision engineering and systems integration. PT Pindad represents the national champion archetype, anchoring Indonesian self-sufficiency goals through captive manufacturing arrangements. Elbit Systems Ltd sits within the subsystem specialist tier, supplying electro-optical and fire-control components that convert conventional platforms into digitally networked nodes.
| Leading Market Players |
|---|
| Singapore Technologies Engineering Ltd |
| PT Pindad |
| Saudi Arabian Military Industries (SAMI) |
| Israel Weapon Industries (IWI) Ltd |
| Elbit Systems Ltd |
| Rheinmetall AG |
| BAE Systems plc |
| General Dynamics Corporation |
| Kenya Ordnance Factories Corporation |
| Others |
Pricing and Supply Chain Analysis
Military procurement offices in Saudi Arabia and the UAE anchor pricing power through long-term framework agreements that compress supplier margins. Their localization mandates force foreign primes into joint-venture structures, transferring cost control to domestic entities while subscription-based fire-control software layers capture recurring revenue streams.
Pricing Analysis
Margin tightening in ammunition lines reflects brass and nitrocellulose propellant input cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified military-grade from commercial security and training rounds. Cost-down pressure on medium-caliber linked ammunition accelerates because SAMI's captive production scaling eliminates import premiums. Military end-users exhibit lowest price sensitivity due to sovereignty requirements; civilian hunting segments in South Africa show highest elasticity.
Supply Chain Analysis
BIS certification requirements for Indian-origin components and Israel's Ministry of Defense secrecy standards fragment supplier qualification pathways. Cold-forging machinery for barrel production concentrates in Germany, Japan, and South Korea; brass casing supply draws from Indonesian and Vietnamese progressive die stamping operations. Single-source vulnerability in precision forging equipment creates chokepoint exposure. Distribution runs through government-to-government direct sales channels and Tawazun-backed joint-venture shells.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around localization mandates that force technology transfer and squeeze independent foreign suppliers. SAMI's scaling captive capacity and Tawazun's domestic-content thresholds are accelerating exits among non-compliant primes.
For Market Incumbents: Acquire cold-forging equipment manufacturers and electro-optical subsystem specialists to lock in barrel production and fire-control integration capabilities. Defensive consolidation requires backward integration into brass casing supply and captive ammunition loading capacity in Riyadh industrial zones to meet GAMI's 50 percent local-content thresholds. Subscription-based software layers extend contract durations beyond hardware replacement cycles. For New Entrants and Emerging Players: South Africa's National Conventional Arms Control Committee streamlining of export licensing protocols opens a window for ammunition export specialization to approved African defense partners. White-space targets include Vietnam's individual soldier system modernization and Nigerian security agency procurement outside formal defense channels. Go-to-market through regional wholesale distributors aggregating minimum order quantities for European manufacturers. For Investors and Strategic Acquirers: The window for entry favors subsystem specialists with electro-optical and fire-control software assets. Long-term viability hinges on recurring revenue models displacing transactional hardware sales. Acquisition target archetype: Israeli or Singaporean firms with NATO-standard certification and software-defined sighting platforms. Watch SAMI's ammunition line completion as inflection signal for import displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | GAMI and Tawazun mandates force foreign primes into domestic manufacturing partnerships with SAMI subsidiaries. |
| Software-Defined Fire-Control Integration | Singapore's defense technology agency pioneered over-the-air update systems that extend contract durations beyond hardware cycles. |
| Backward Integration into Ammunition Components | PT Pindad's captive brass casing and propellant loading capacity anchors Indonesian self-sufficiency goals through Bandung industrial complexes. |
| Electro-Optical Subsystem Acquisition | Elbit Systems' fire-control add-ons convert conventional rifles into digitally networked soldier-system nodes for ASEAN special operations commands. |
| Regional Wholesale Distribution Expansion | African defense ministries aggregate demand through wholesale channels to meet European manufacturers' minimum order quantities. |
Research Methodology
Trade data from customs authorities, defense procurement registries, and BIS certification filings formed the secondary backbone for this analysis. Primary interviews with defense procurement officers at Indonesia's Ministry of Defense, SAMI subsidiary executives, and electro-optical subsystem engineers at Singaporean precision engineering groups combined with secondary validation. Bottom-up and top-down triangulation cross-checked production capacity announcements against import dependency ratios and framework agreement values.
Bottom-up modeling segmented volume and value across product type, end-user institution, caliber standardization tier, and geographic regulatory cluster. Rifle platform modernization cycles, ammunition throughput rates, and localization compliance timelines fed the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed procurement budgets and announced production capacity additions.
The model assumes a particular technology adoption path; alternative pathways for metal injection molding in Southeast Asian supplier bases would alter the outlook. Forecasts reflect assumptions about GAMI and Tawazun localization deadline adherence and ASEAN NATO-standard interoperability commitments. A model refresh is warranted upon material change in Saudi ammunition line completion timelines or Vietnamese defense budget allocation shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market