
 Ballistic Composite Market | 2026-2036
Ballistic Composite Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Composite Market Outlook
The EU Green Deal is realigning procurement criteria for defense and law enforcement agencies across Europe, favoring composite suppliers with verified lifecycle assessments and reduced carbon footprints in fiber production. DuPont leverages its integrated aramid supply chain to meet these sustainability benchmarks while sustaining pricing power in North American military contracts. Teijin Limited anchors its position through advanced UHMWPE fiber capacity in Japan and expanded weaving operations in the Netherlands.
Ballistic composites are engineered fiber-reinforced materials combining high-strength aramid, ultra-high molecular weight polyethylene, or ceramic matrices with thermoset or thermoplastic binders, typically manufactured through autoclave curing, compression molding, or vacuum-assisted resin transfer to achieve areal densities below 4.5 kg/m² while defeating NIJ Level III threats. Their primary purpose is to absorb and dissipate kinetic energy from projectiles or blast fragments in personnel armor, vehicle panels, and aircraft structures. UHMWPE fibers command the fastest-expanding product segment due to their strength-to-weight superiority over aramid alternatives in maritime and airborne platforms. Defense end users concentrate the largest value pool, though law enforcement and sports equipment segments are diversifying application breadth.
The U.S. Department of Defense enforces Berry Amendment compliance and NIJ ballistic resistance standards, while the European Defence Agency coordinates harmonized STANAG testing protocols across member states. These frameworks dictate fiber qualification pathways, limit non-allied sourcing, and create multi-year certification barriers for new entrants. Stakeholders must monitor evolving sustainability-linked procurement rules and dual-use export control expansions that could reshape supplier eligibility faster than capacity investments can adapt.
Market Dynamics
Defense procurement agencies are consolidating orders around Berry Amendment-compliant domestic supply chains while EU REACH regulations force solvent-free resin transitions, compressing qualification timelines for non-U.S. fiber suppliers.
Growth Catalysts
- Domestic Sourcing Mandates:U.S. military contracts under Berry Amendment provisions require aramid and UHMWPE fibers to originate from domestic suppliers, locking in captive demand for qualified North American weavers and pre-preg manufacturers.
- Maritime Platform Modernization:Naval forces across NATO member states are replacing steel armor panels with UHMWPE-composite solutions to reduce vessel displacement and improve fuel efficiency in littoral combat ships.
- STANAG Harmonization:The European Defence Agency's coordinated ballistic testing protocols are eliminating redundant national certification barriers, accelerating cross-border supplier qualification for composite armor vendors.
Market Restraints
- Aramid Feedstock Concentration:Para-aramid polymer supply concentrates among three integrated chemical producers, exposing armor fabricators to price volatility in meta-phenylene diamine precursor chemicals.
- Autoclave Throughput Bottlenecks:Large-format vehicle armor panels require curing cycles exceeding eight hours in temperature-controlled pressure vessels, constraining capacity expansion without substantial capital deployment.
- Ceramic-Composite Substitution:Silicon carbide and boron carbide tile systems retain cost advantages against UHMWPE in heavy vehicle applications above NIJ Level IV threat specifications.
Strategic Opportunities
- Law Enforcement Modernization:Municipal police departments in Germany and France are replacing legacy Kevlar vests with next-generation polyethylene solutions, opening a civilian procurement channel outside defense budget cycles.
- Recyclable Thermoplastic Matrices:EU Green Deal procurement criteria now weight lifecycle carbon emissions in composite selection, rewarding suppliers with closed-loop fiber recovery capabilities and bio-based resin alternatives.
- Drone Platform Integration:Unmanned aerial vehicle manufacturers require areal densities below 2.5 kg/m² for payload-critical applications, creating specification gaps that hybrid ceramic-polyethylene laminates are uniquely positioned to fill.
Industry Challenges
- NIJ Certification Timelines:New fiber formulations require 18-24 months of ballistic testing and environmental conditioning before law enforcement agency approval, delaying revenue recognition for material innovations.
- Skilled Autoclave Operation Shortage:Vacuum-bag layup and cure-cycle monitoring demand technicians with composite manufacturing experience that vocational training programs have failed to replenish at replacement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Composite Market |
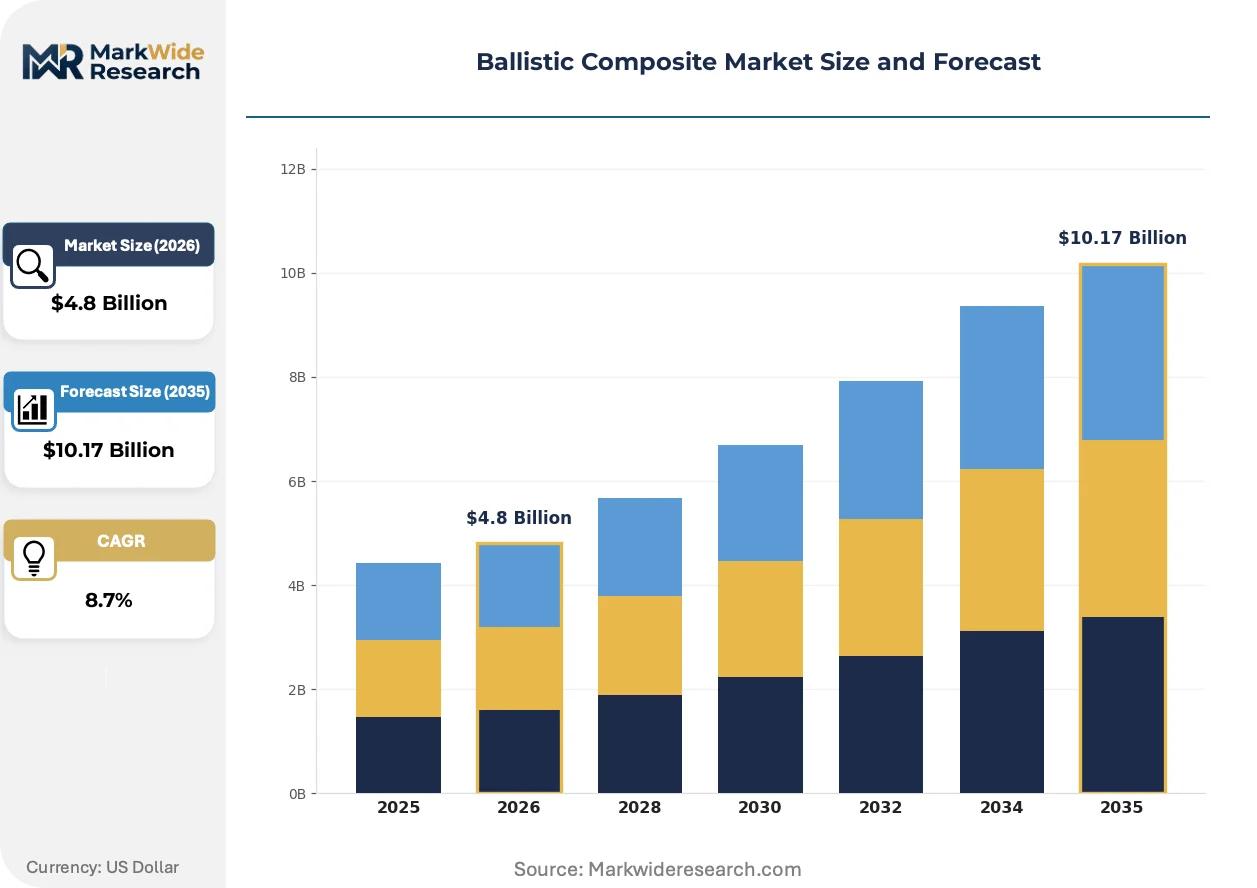
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aramid Fiber, UHMWPE, Carbon Fiber, Ceramic Fiber End User: Defense, Law Enforcement, Aerospace, Sports Equipment Form: Sheet, Fabric, Composite, Molding Installation: On-site, Pre-fabricated, Modular, Integrated |
| Companies Covered | Honeywell International Inc., DuPont, Teijin Limited, BAE Systems, DSM, TenCate Protective Fabrics, Morgan Advanced Materials, Avient Corporation, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Composite Market Strategic Shifts
Material science breakthroughs and procurement rule changes are compressing traditional supply hierarchies while opening entry paths for specialized composite converters.
Non-woven UHMWPE unidirectional tapes are rewriting strength-to-weight benchmarks in personal armor systems. Special forces units across NATO member states have accelerated fielding of helmets and plate carriers constructed from cross-plied polyethylene laminates, enabling threat protection at 30% lower mass than equivalent aramid solutions. This mass reduction is rewriting mobility requirements for dismounted infantry loadouts and helicopter-borne rapid response teams.
EU REACH chemical regulations are phasing out solvent-based pre-preg formulations by 2027, forcing resin suppliers to qualify waterborne and hot-melt alternatives. Armor manufacturers in the Netherlands and Germany have consolidated around two qualified epoxy systems, creating temporary supply concentration while testing protocols validate additional chemistries. Vehicle armor integrators face the steepest reformulation costs due to larger resin volumes and adhesion-critical multi-layer bonding requirements.
Defense agencies are consolidating multi-year framework agreements with single-source composite armor suppliers, displacing fragmented spot purchasing through prime contractors. Tier-one vehicle integrators in the United States and United Kingdom now specify qualified fiber weavers and pre-preg converters by name in platform subcontracts, compressing tier-two and tier-three supplier margins while locking in volume commitments. This specification tightening is most visible in ground vehicle underbody protection programs where STANAG 4569 certification validity depends on documented fiber batch traceability.
Ballistic Composite Market Segmentation
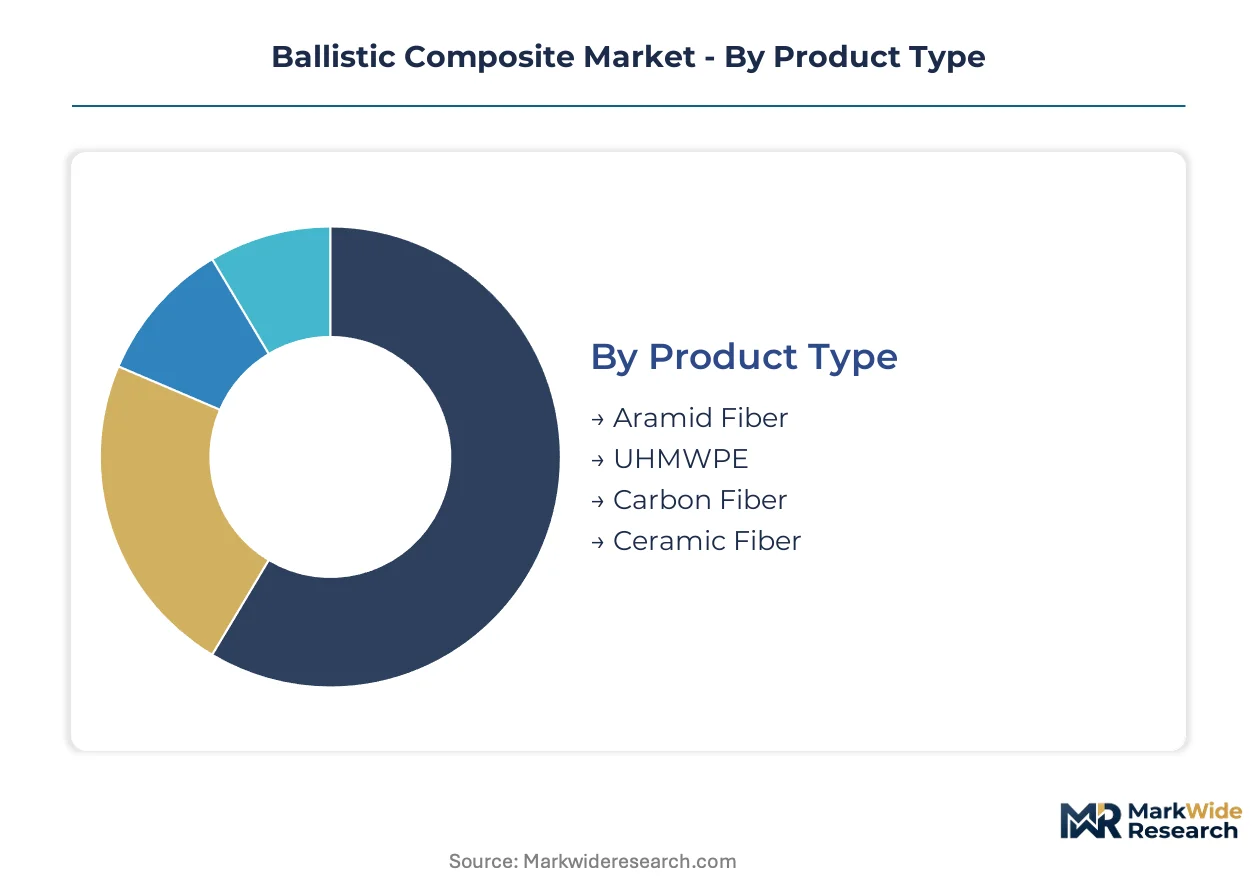
Ballistic composite procurement follows distinct technical specifications across fiber chemistry, end-use threat profiles, and manufacturing form factors. Upgrade cycles vary dramatically—defense platforms demand 15-20 year service intervals while law enforcement refreshes body armor every 5-7 years.
Product Type:
Replacement decisions increasingly pivot on strength-to-weight ratios and REACH-compliant resin compatibility rather than legacy supplier relationships.
- Aramid Fiber:Para-aramid polymers deliver flame resistance and thermal stability exceeding polyethylene alternatives. NATO ground vehicle programs in Germany and France specify aramid backing layers for spall containment in crew compartments.
- UHMWPE:Ultra-high molecular weight polyethylene achieves tensile strength 15x greater than steel at 40% lower density. Naval procurement in the United States and United Kingdom prioritizes UHMWPE for shipboard armor to reduce topside weight and improve stability margins.
- Carbon Fiber:Stiffness-critical structural armor applications leverage carbon-epoxy hybrids for aircraft hardening.
- Ceramic Fiber:Oxide ceramic reinforcements address extreme temperature environments in engine nacelle protection.
Aramid fiber sits at the top of the volume ranking, with UHMWPE climbing the fastest as maritime platform modernization accelerates.
End User:
Customer type determines certification burden, contract duration, and price sensitivity—with defense agencies tolerating 18-month qualification timelines that civilian buyers reject.
- Defense:Multi-year framework agreements lock in fiber batch traceability requirements from spinning through cure cycle. STANAG 4569 certification validity depends on documented supply chain custody for ground vehicle underbody protection.
- Law Enforcement:Municipal procurement cycles operate outside defense budget appropriations, enabling faster vendor switching. German and French police departments are replacing legacy vests with polyethylene solutions as NIJ Level IIIA standards tighten.
- Aerospace:FAA airworthiness directives govern armor integration in commercial and military aircraft structures.
- Sports Equipment:Recreational armor for motorsports and equestrian applications faces lighter regulatory scrutiny.
Defense absorbs the dominant share of procurement value, though law enforcement is gaining share fastest as civilian agency budgets decouple from military spending cycles.
Form:
Manufacturing format dictates processing equipment requirements and labor skill intensity—with implications for regional production placement.
- Sheet:Flat-panel laminates serve as feedstock for CNC-cut armor inserts. United States-based fabricators maintain Berry Amendment compliance through in-house prepreg cutting and kitting operations.
- Fabric:Woven textile forms enable complex-curve helmet draping and vest panel tailoring.
- Composite:Cured rigid panels deliver finished ballistic protection without secondary processing.
- Molding:Compression-molded shapes integrate mounting features and edge seals during single-cycle forming.
Sheet dominates current throughput, while molding formats are expanding most quickly as vehicle armor integrators seek reduced assembly labor.
Installation:
Deployment method shapes logistics burden and field modification flexibility—with tradeoffs between factory quality control and operational adaptability.
- On-site:Field-applied armor systems permit platform-specific customization without return-to-depot delays. United States Marine Corps expeditionary units specify on-site installable panel kits for rapid vehicle reconfiguration.
- Pre-fabricated:Factory-cured modules arrive with validated ballistic performance and adhesive bonding surfaces prepared.
- Modular:Interchangeable panel systems enable threat-level upgrades without platform retirement.
- Integrated:Structural armor designed into original equipment manufacturing delivers optimal weight distribution.
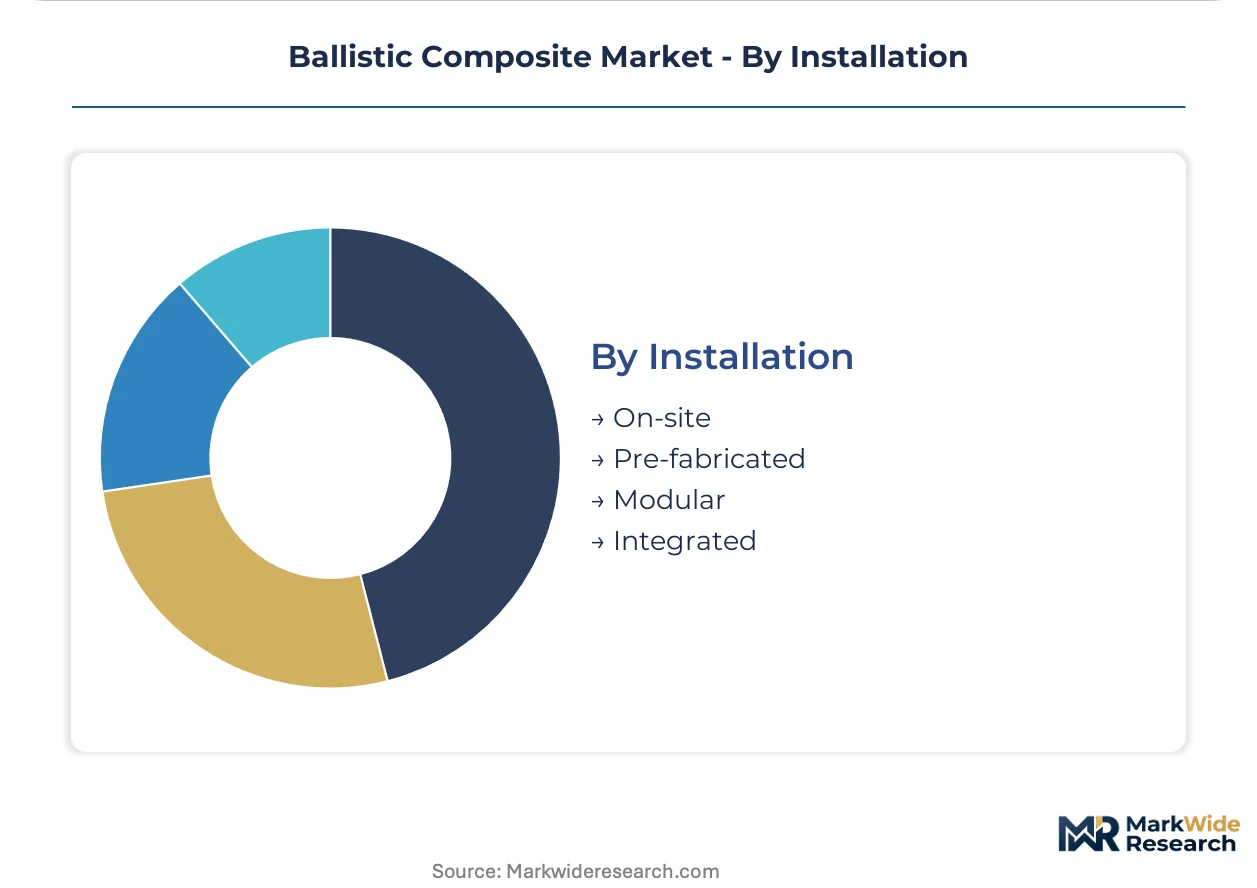
Pre-fabricated solutions command the largest installed base, with modular approaches showing the steepest adoption curve as multi-threat mission profiles proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ballistic composite manufacturing originated in the United States during the 1970s with para-aramid fiber commercialization, establishing North American supply chains that later expanded to Europe and Asia-Pacific through technology licensing and joint ventures.
United States
Defense procurement under the Berry Amendment mandates domestic fiber sourcing for military contracts, locking in demand for qualified aramid and UHMWPE weavers. The Department of Defense enforces NIJ ballistic resistance standards that dictate fiber qualification pathways. Industrial concentration centers on Virginia and South Carolina, where integrated pre-preg manufacturers serve vehicle armor programs for ground forces modernization.
Germany
Naval platform upgrades are replacing steel armor with lightweight composite panels to improve fuel efficiency in littoral combat vessels. ECHA REACH regulations are phasing out solvent-based resin formulations by 2027, forcing rapid qualification of waterborne alternatives. The Bavaria region hosts specialized autoclave operators supplying STANAG 4569-certified underbody protection to NATO vehicle integrators.
United Kingdom
Maritime modernization programs prioritize UHMWPE solutions for shipboard armor to reduce topside weight and improve vessel stability margins. The Ministry of Defence coordinates with the European Defence Agency on harmonized testing protocols. Scotland maintains composite manufacturing clusters serving aerospace and naval applications with documented fiber batch traceability.
Japan
Advanced UHMWPE fiber capacity expansion supports domestic defense procurement and export markets for maritime platforms. METI industrial policy encourages high-performance materials development through targeted R&D subsidies. The Chubu region around Nagoya anchors weaving operations that supply cross-plied polyethylene laminates to special forces helmet programs across Asia-Pacific.
Netherlands
EU Green Deal procurement criteria weight lifecycle carbon emissions in composite selection, rewarding suppliers with closed-loop fiber recovery capabilities. The European Defence Agency's STANAG harmonization eliminates redundant national certification barriers. Eindhoven-based converters specialize in recyclable thermoplastic matrices for law enforcement vest modernization programs.
Ballistic Composite Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and fiber integration levels, with the market consolidating around three integrated chemical producers controlling para-aramid polymer supply. The vendor base stratifies into fiber spinners, pre-preg converters, and finished armor integrators with limited overlap between tiers. Two strategic archetypes dominate: vertically integrated chemical-to-fabric suppliers and specialized composite converters with autoclave capacity. Competitive moves center on multi-year framework agreements with defense agencies and solvent-free resin qualification under EU REACH deadlines.
Among integrated chemical producers, DuPont and Teijin Limited exemplify the premium-tier archetype through captive fiber production, while DSM occupies a position bridging polymer supply and composite conversion. Honeywell International Inc. sits within the diversified industrial conglomerate tier, representing scale-driven participation across multiple defense material categories. These three named entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| DuPont |
| Teijin Limited |
| BAE Systems |
| DSM |
| TenCate Protective Fabrics |
| Morgan Advanced Materials |
| Avient Corporation |
| 3M |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap autoclave operators in Bavaria and Virginia anchor regional pricing discipline through captive relationships with defense primes, translating multi-year framework agreements into stable fiber offtake that resists spot-market volatility. Their ownership structure prioritizes long-term contract security over volume maximization, compressing margin competition among tier-two pre-preg converters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates STANAG-certified military grades from law enforcement NIJ tiers and commercial sports applications. Price differentiation rests on certification depth and fiber batch traceability rather than raw material cost. Pricing pressure stems from REACH-mandated solvent-free resin transitions that force reformulation investments without immediate pass-through elasticity. Law enforcement agencies exhibit highest price sensitivity due to municipal budget constraints, while defense procurement tolerates premium positioning for documented supply chain custody.
Supply Chain Analysis
Dual-sourcing requirements from NATO defense agencies mandate qualified fiber suppliers in at least two member states, locking in geographic diversification across the United States, Germany, and Japan. Raw material dependencies center on para-aramid polymer from integrated chemical producers, UHMWPE resin from specialized polymerization facilities, and epoxy hardeners subject to ECHA registration. Single-source vulnerability concentrates in meta-phenylene diamine precursor supply. Distribution runs through prime contractor tier-one integrators who specify qualified weavers and converters by name in platform subcontracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
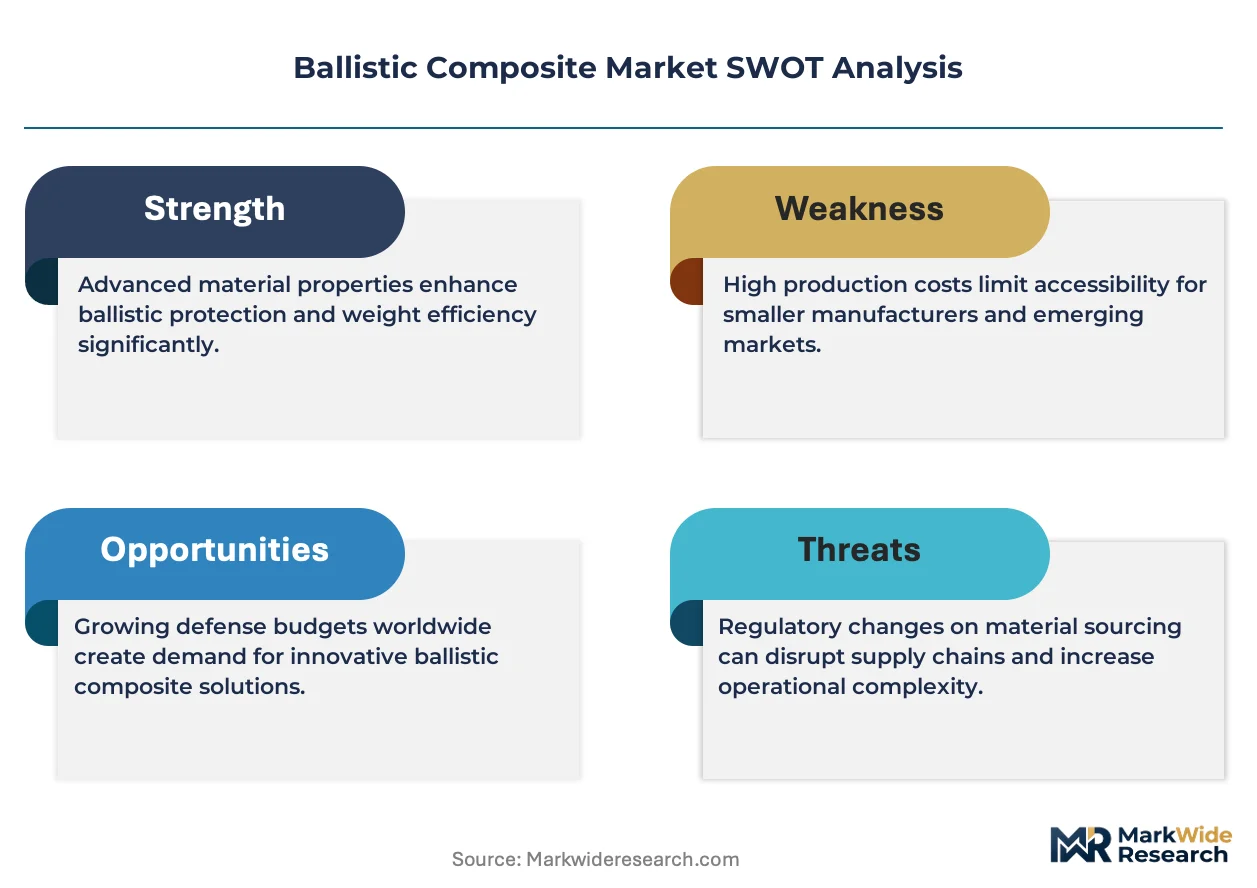
This market functions as a regulatory compounder where EU REACH solvent-phaseout deadlines and Berry Amendment domestic sourcing mandates create simultaneous demand pull and supply constraint.
For Market Incumbents: Hedge against ceramic-composite substitution in heavy vehicle applications by accelerating UHMWPE hybrid formulations for maritime and airborne platforms. Deepen backward integration into para-aramid polymerization or captive UHMWPE resin production to offset feedstock concentration risk among three chemical producers. Prioritize autoclave capacity expansion in South Carolina and Bavaria to capture ground vehicle modernization program volumes.
For New Entrants and Emerging Players: Municipal police departments in France and Germany represent the most penetrable buyer archetype outside defense procurement cycles, with NIJ Level IIIA vest replacement programs decoupled from military budget appropriations. Target recyclable thermoplastic matrix qualifications under EU Green Deal procurement weighting to bypass entrenched epoxy system incumbency. Pursue direct contracting with mid-size law enforcement agencies rather than prime contractor channels to compress 18-24 month certification timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized autoclave operators with STANAG 4569 certification but limited fiber integration, as defense consolidation favors qualified capacity over upstream chemical exposure. Five-to-ten year viability hinges on REACH-compliant resin qualification completion and drone platform armor specification capture. Monitor ECHA substance authorization timelines for epoxy hardener alternatives as the critical inflection signal for incumbent reformulation cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Resin Qualification | ECHA REACH compliance unlocks EU defense procurement eligibility before 2027 phaseout deadlines. |
| Backward Integration into Fiber Production | Captive UHMWPE resin supply secures Berry Amendment compliance and margin protection against polymer volatility. |
| Autoclave Capacity Expansion | Additional temperature-controlled pressure vessel throughput relieves eight-hour cure cycle bottlenecks in vehicle armor panel production. |
| Recyclable Thermoplastic Matrix Development | Closed-loop fiber recovery capabilities satisfy EU Green Deal lifecycle carbon emission weighting in composite selection. |
| Drone Platform Armor Specification | Areal densities below 2.5 kg/m² address unmanned aerial vehicle payload-critical requirements outside traditional defense platforms. |
Study Parameters
Coverage spans the United States, Germany, United Kingdom, Japan, and Netherlands, with primary inputs from each region combining interviews with defense procurement officers, pre-preg manufacturing plant managers, composite R&D directors, and law enforcement equipment purchasers. Secondary validation draws from ECHA substance registration databases, NIJ ballistic resistance standard publications, SEC 10-K filings from listed defense material suppliers, and NATO STANAG testing protocol documentation. Bottom-up fiber capacity and autoclave throughput estimates triangulate against top-down defense budget appropriation analysis.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by fiber chemistry, end-use threat profile, manufacturing form factor, and regional regulatory cluster. CAGRs derive from installed base replacement cycles—15-20 years for defense platforms, 5-7 years for law enforcement—cross-referenced with documented framework agreement award timelines. Forecast inputs incorporate REACH resin transition cost curves, Berry Amendment compliance qualification backlogs, and maritime platform displacement reduction specifications.
Underlying measurement precision varies by segment; defense procurement with multi-year framework agreements carries tighter precision than municipal law enforcement spot purchasing. Forecasts reflect assumptions regarding ECHA authorization timelines and NIJ certification queue durations. Deviation in para-aramid polymer supply concentration or autoclave technician labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Airborne Weapon System Market