
 Anti-Tank Missile System Market | 2026-2036
Anti-Tank Missile System Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Tank Missile System Market Analysis
Software-defined seeker upgrades is recalibrating what defense ministries purchase, shifting capital expenditure from complete system replacement to modular capability insertion. Lockheed Martin leverages captive production of imaging infrared focal-plane arrays to sustain margin control across its Javelin ecosystem. Raytheon Technologies anchors its franchise through semi-active laser guidance supply chains that span multiple NATO armament programs. MBDA Missile Systems differentiates via dual-mode seeker integration that occupies the boundary between fire-and-forget and precision-designation architectures.
An anti-tank missile system comprises a tube-launched, optically tracked or self-homing munition paired to a command launch unit, typically employing shaped-charge or tandem warhead configurations to defeat composite and reactive armor arrays. These systems serve ground forces by enabling dismounted or vehicle-mounted engagement of main battle tanks and fortified positions beyond the effective range of unguided rockets. Fire-and-forget technology leads procurement budgets due to reduced operator exposure during terminal engagement, while active radar homing represents the fastest-growing seeker category as millimeter-wave components shrink in cost and aperture size. Smart missiles concentrate margin pools where manufacturers combine inertial navigation with terminal infrared discrimination to defeat active protection systems.
The U.S. Department of Defense and NATO's Standardization Office shape demand through STANAG 4187 armor-defeat benchmarks and recurring live-fire qualification protocols that gate market access for non-aligned suppliers. Germany's KBA and France's DGA enforce national safety and transportability certifications that fragment procurement into bilateral industrial offsets rather than open competition. Stakeholders must monitor how ITAR reform discussions and emerging EU defense procurement directives redraw the boundary between allied interoperability and sovereign supply chain control.
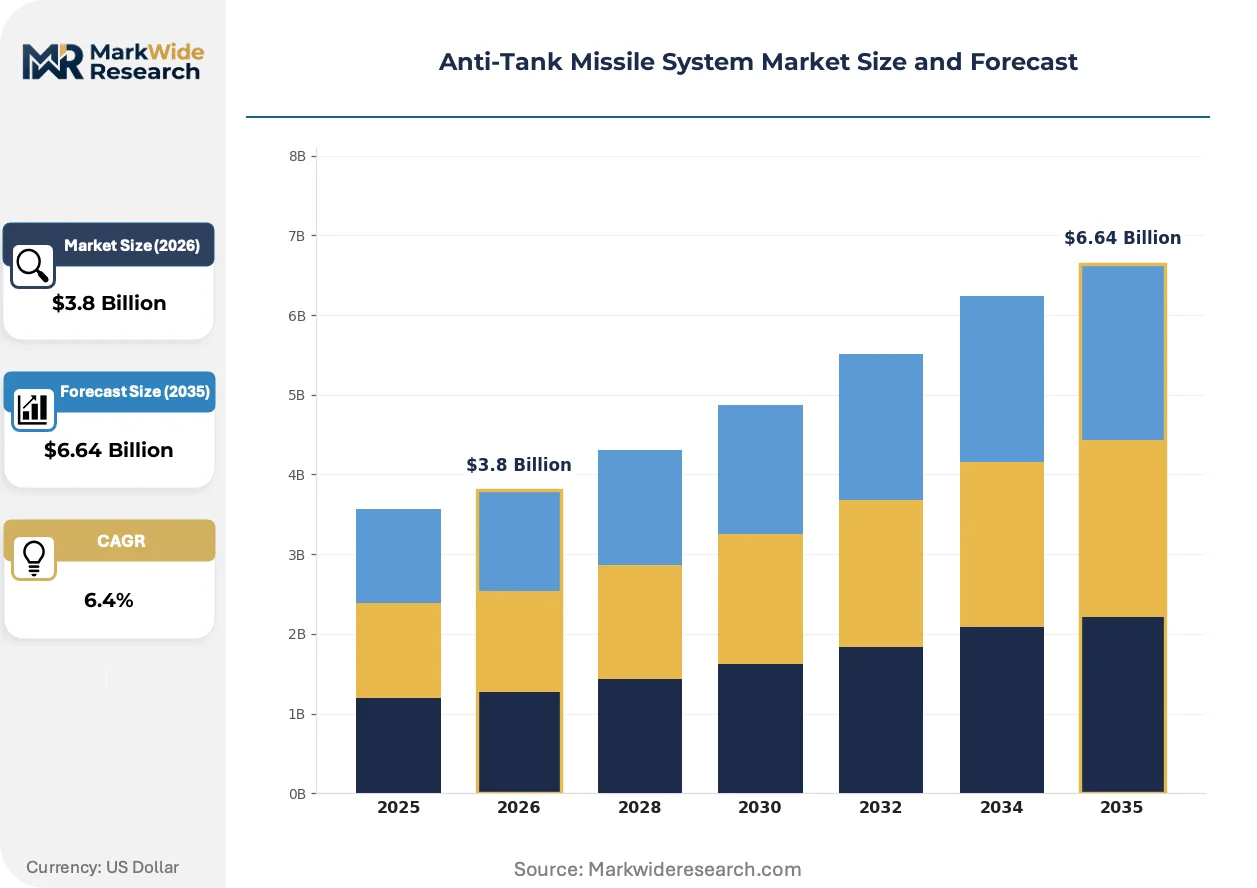
Market Dynamics
Fire-and-forget seeker architectures are recalibrating procurement priorities across NATO defense ministries, shifting capital allocation from platform-centric purchases to modular munition upgrades that reduce operator exposure during terminal engagement.
Growth Catalysts
- STANAG 4187 armor-defeat benchmarks:NATO's Standardization Office mandates recurring live-fire qualification protocols that gate market access, compelling allied nations to modernize inventories.
- Active protection system proliferation:Main battle tank upgrades with hard-kill defenses in Poland, Germany, and the United States are forcing munition makers to deploy tandem warheads and top-attack trajectories.
- Millimeter-wave component cost compression:Shrinking aperture sizes and falling sensor prices are accelerating active radar homing adoption beyond traditional infrared-guided franchises.
Market Restraints
- ITAR-controlled focal-plane array supply:U.S. export licensing for imaging infrared seekers constrains non-aligned suppliers from qualifying for NATO tenders.
- German KBA transportability certification:National safety protocols fragment procurement into bilateral industrial offsets rather than open competition.
- Command-guided system obsolescence:Legacy wire-guided architectures face rapid displacement, stranding maintenance infrastructure and operator training pipelines.
Strategic Opportunities
- Dual-mode seeker convergence:Integrating imaging infrared with millimeter-wave radar enables engagement through obscurants and electronic countermeasure environments.
- Software-defined seeker upgrades:Modular capability insertion allows defense ministries to extend system lifecycles without complete platform replacement.
- Semi-active laser guidance standardization:Raytheon's supply chain architecture spans multiple NATO armament programs, creating interoperability leverage.
Industry Challenges
- Operator training pipeline compression:Fire-and-forget systems reduce skill requirements but create dependency on complex seeker maintenance and field diagnostics.
- Dual-use component sourcing:Commercial infrared sensor markets compete for identical focal-plane arrays, creating allocation conflicts during surge demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Tank Missile System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Missiles, Non-Guided Missiles, Smart Missiles, Laser-Guided Missiles Technology: Fire-and-Forget, Semi-Active Homing, Guided, Active Radar Homing Application: Military, Defense, Training, Research End User: Armed Forces, Defense Contractors, Government Agencies, Private Security |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, MBDA Missile Systems, BAE Systems, Rafael Advanced Defense Systems Ltd., General Dynamics Corporation, Saab AB, Roketsan, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Tank Missile System Market Emerging Trajectories
Seeker technology trajectories are fragmenting procurement strategies as defense ministries weigh immediate capability against long-term upgrade paths. Modular architectures now dominate development roadmaps.
Imaging infrared focal-plane arrays paired with inertial navigation are overtaking pure infrared discrimination in smart missile configurations. Ground forces in Poland and Germany are prioritizing these systems to defeat active protection systems on modernized tank fleets. The convergence is compressing development cycles for legacy command-guided alternatives.
EU defense procurement directives are reshaping industrial offset requirements for cross-border armament programs. France's DGA and Germany's KBA are enforcing stricter national certification protocols that fragment standardization efforts. MBDA Missile Systems is responding with dual-mode architectures that bridge fire-and-forget and precision-designation categories.
Defense ministries are unbundling after-sales service from initial system acquisition, creating discrete revenue pools for seeker refurbishment and software updates. Vehicle-mounted launch units in the United States are leading this shift toward performance-based sustainment contracts. The model is spreading to dismounted infantry programs in NATO's eastern flank states.
Anti-Tank Missile System Market Segmentation
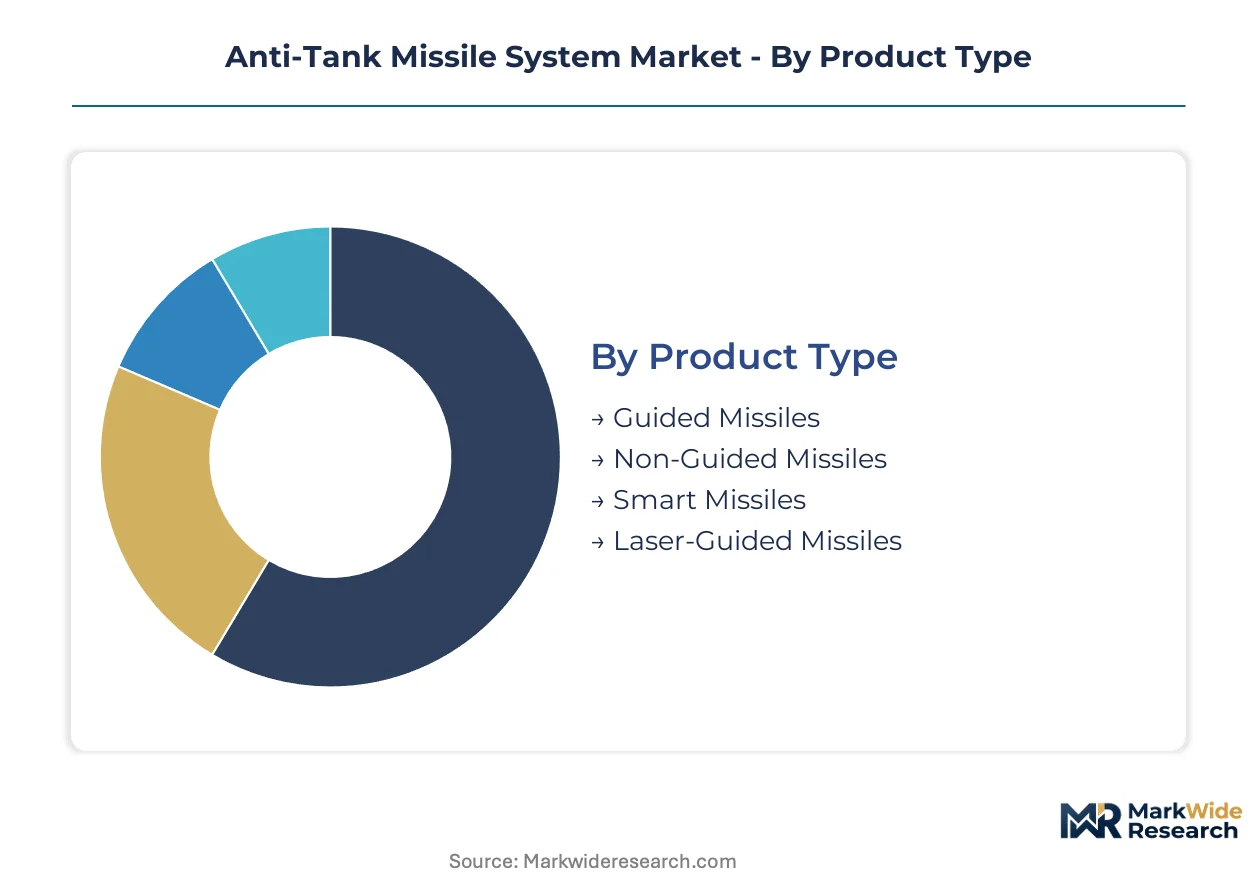
Defense procurement agencies segment anti-tank missile systems by capability tier and engagement mode to match munition specifications against evolving armor threats. Procurement cycles favor modular upgrades over platform replacement, concentrating investment in seeker architectures that defeat active protection systems.
Product Type:
Upgrade cycles concentrate capital in guided and smart configurations as NATO inventories shift from legacy stocks toward precision-engagement munitions.
- Guided Missiles:Command-guided or beam-riding architectures with wire or fiber-optic data links. Polish and German land forces prioritize these for cost-effective fleet modernization before transitioning to fire-and-forget systems.
- Smart Missiles:Imaging infrared focal-plane arrays paired with inertial navigation enable terminal discrimination against hard-kill active protection systems. United States Army procurement channels favor these for urban and complex terrain engagements where top-attack trajectories defeat composite armor arrays.
- Non-Guided Missiles:Unguided rocket-propelled munitions with shaped-charge warheads retain niche roles in suppression and area denial.
- Laser-Guided Missiles:Semi-active laser seekers require external designation but offer precision at reduced unit cost for defense contractors managing training inventories.
Guided Missiles sits at the top of the volume ranking, with Smart Missiles climbing the fastest.
Technology:
Cost compression in millimeter-wave components is redrawing the boundary between infrared and radar-guided franchises across NATO armament programs.
- Fire-and-Forget:Imaging infrared or millimeter-wave seekers with autonomous terminal guidance eliminate operator exposure during engagement. United States Marine Corps and Polish Territorial Defense Force procurement prioritizes these for dismounted infantry applications.
- Active Radar Homing:Millimeter-wave seekers with all-weather engagement capability and electronic countermeasure resistance. Shrinking aperture sizes and falling sensor prices accelerate adoption beyond traditional infrared franchises.
- Semi-Active Homing:Laser or radar designation dependent on external target illumination. Training and reserve force applications dominate demand.
- Guided:Command-guided architectures with operator-in-the-loop control face rapid displacement except in cost-constrained procurement channels.
Fire-and-Forget commands the largest procurement share, while Active Radar Homing expands most quickly as millimeter-wave production scales.
Application:
Mission profiles determine seeker complexity, with frontline combat applications absorbing premium-tier capabilities and support functions operating legacy stocks.
- Military:Frontline engagement of main battle tanks and fortified positions. United States Army and German Bundeswehr procurement concentrates here, requiring tandem warheads and top-attack discrimination against reactive armor.
- Defense:Static and area protection for critical infrastructure. Poland's eastern border fortification programs drive demand for vehicle-mounted launch units with extended-range seekers.
- Training:Reduced-range practice munitions and simulation systems. Defense contractors manage these inventories under performance-based sustainment contracts.
- Research:Seeker technology validation and countermeasure development. Government agencies fund these programs through DARPA and France's DGA research directorates.
Military application leads procurement volume, with Defense climbing fastest as NATO's eastern flank states accelerate border hardening.
End User:
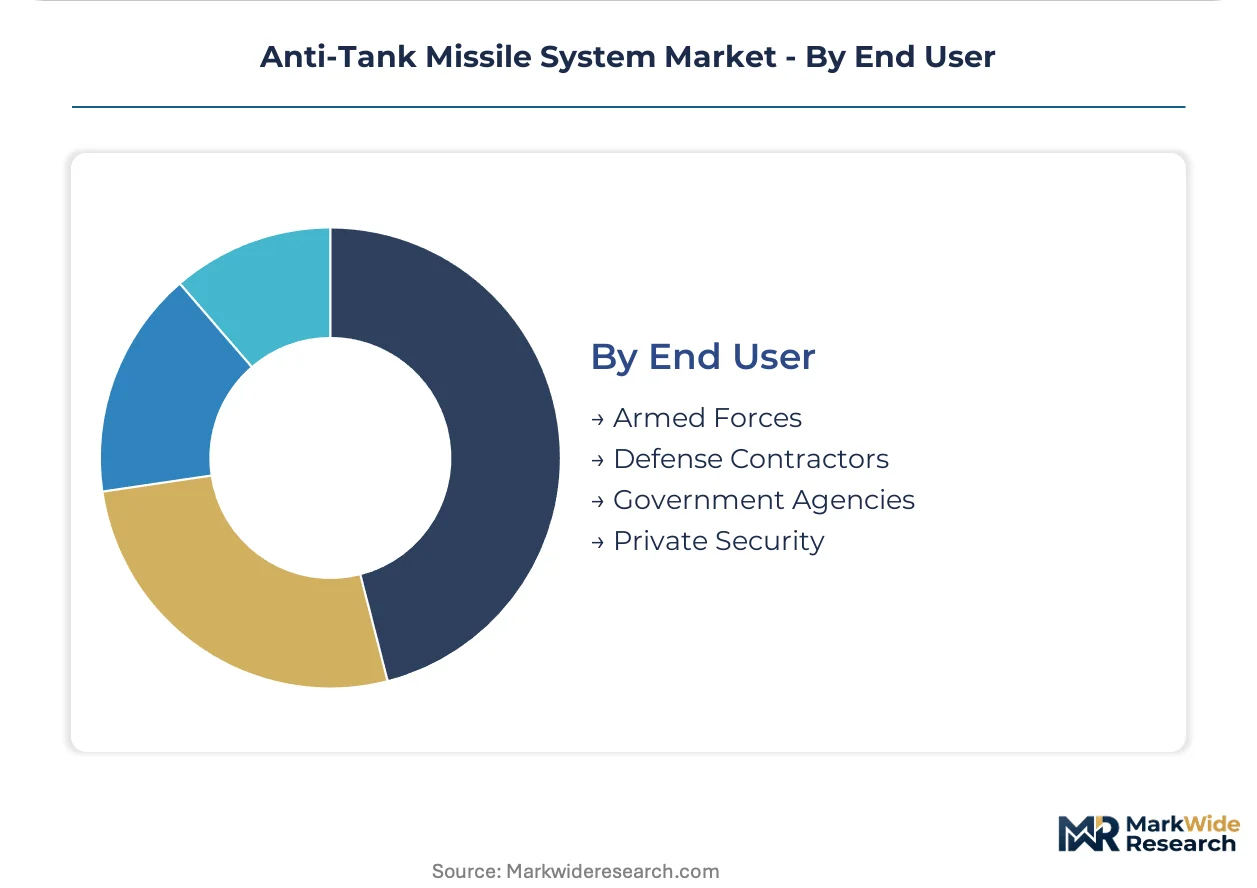
Customer type dictates acquisition scale and certification requirements, fragmenting procurement between sovereign defense ministries and industrial contractors.
- Armed Forces:National military services with STANAG 4187 qualification requirements. United States, Germany, and Poland represent the dominant demand concentration for fire-and-forget systems with software-defined upgrade paths.
- Defense Contractors:System integrators and subsystem suppliers managing NATO cross-border armament programs. MBDA and Raytheon supply chains serve this channel with dual-mode seeker architectures.
- Government Agencies:Research and development directorates plus export licensing authorities. ITAR-controlled focal-plane array supply constrains non-aligned supplier access to this channel.
- Private Security:Limited demand for static protection systems in high-threat environments, subject to national arms export controls.
Armed Forces dominates procurement scale, with Defense Contractors gaining share fastest as production consolidates under cross-border industrial offsets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA transportability certification creates stricter entry barriers than Poland's procurement acceleration, fragmenting NATO standardization efforts across the eastern flank.
United States
The Department of Defense channels procurement through STANAG 4187 qualification protocols that gate allied supplier access. ITAR-controlled focal-plane array licensing constrains non-aligned manufacturers from tender participation. Lockheed Martin's captive production in Orlando and Tucson secures margin control across the Javelin ecosystem.
Germany
The Bundeswehr prioritizes tandem warhead and top-attack discrimination against reactive armor on modernized tank fleets. KBA national safety certifications fragment procurement into bilateral industrial offsets rather than open competition. Rheinmetall's industrial cluster in Düsseldorf anchors cross-border armament program integration.
Poland
Territorial Defense Force procurement accelerates fire-and-forget system acquisition for dismounted infantry applications. Eastern border fortification programs drive demand for vehicle-mounted launch units with extended-range seekers. Wrocław's defense industrial base concentrates production consolidation under NATO interoperability mandates.
France
DGA research directorates fund seeker technology validation through dual-mode architecture development. Stricter national certification protocols under EU defense procurement directives reshape industrial offset requirements. MBDA's integration facilities in Le Plessis-Robinson bridge fire-and-forget and precision-designation categories.
United Kingdom
BAE Systems anchors domestic supply chains for semi-active laser guidance components serving multiple NATO programs. Defense procurement agencies unbundle after-sales service from initial system acquisition, creating discrete revenue pools for seeker refurbishment. Stevenage's missile systems cluster concentrates software-defined upgrade development.
Anti-Tank Missile System Market Vendor Landscape
Top-tier vendors anchor prime-contractor positions on major NATO armament programs, while mid-tier specialists occupy subsystem and component supply niches. The vendor base stratifies across three structural tiers: integrated system houses controlling seeker-to-launcher supply chains, subsystem specialists delivering guidance and propulsion modules, and component suppliers of focal-plane arrays and millimeter-wave sensors. Dominant competitive moves include captive production of imaging infrared arrays and backward integration into inertial navigation component supply.
Among U.S.-based integrated system houses, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the prime-contractor archetype through sustained control over seeker manufacturing and launcher integration. MBDA Missile Systems occupies a position bridging European consortium structures with dual-mode technology development. These three entities represent distinct competitive vectors: captive component supply, semi-active laser guidance standardization, and dual-mode seeker convergence.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| MBDA Missile Systems |
| BAE Systems |
| Rafael Advanced Defense Systems Ltd. |
| General Dynamics Corporation |
| Saab AB |
| Roketsan |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
STANAG 4187 qualification mandates from NATO procurement agencies are forcing suppliers to absorb certification costs upfront, compressing margins on initial contracts while creating pricing power for qualified incumbents on follow-on sustainment packages.
Pricing Analysis
Capacity additions in Poland and Germany are reshaping price floors for vehicle-mounted launch units as local production offsets reduce transport and certification premiums. Three-tier pricing structure across fire-and-forget, dual-mode, and command-guided capability levels reflects seeker complexity and software upgrade eligibility. Price differentiation hinges on STANAG qualification status and captive focal-plane array production, with ITAR-controlled suppliers commanding premiums over non-aligned competitors. Polish Territorial Defense Force procurement channels exhibit highest price sensitivity due to volume scaling constraints, while United States Army programs prioritize performance over unit cost.
Supply Chain Analysis
Specialized workforce availability in Tucson, Orlando, and Stevenage anchors imaging infrared seeker production clusters for prime contractors serving NATO armament programs. Supply concentrates in the United States, Germany, and France, with millimeter-wave sensor fabrication drawing from commercial automotive radar component streams. Raw material dependencies span indium antimonide for focal-plane arrays, precision-machined aluminum launch tubes, and solid propellant formulations. Single-source vulnerability in ITAR-controlled seeker electronics creates chokepoint exposure during surge demand periods. Distribution runs through defense ministry procurement offices and cross-border industrial offset agreements rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German KBA certification costs and Polish production subsidies create divergent entry economics for suppliers targeting NATO's eastern flank versus core European markets.
For Market Incumbents: Cement prime-contractor status by deepening backward integration into millimeter-wave sensor supply and securing performance-based sustainment contracts that lock out modular upgrade competitors. Active radar homing proliferation from non-aligned suppliers threatens infrared-guided franchises, making software-defined seeker architecture control the critical defensive lever. For New Entrants and Emerging Players: EU defense procurement directive harmonization efforts open a window for dual-mode seeker specialists to penetrate cross-border armament programs previously fragmented by national certification barriers. Vehicle-mounted launch units for Poland's eastern border fortification represent the most penetrable demand concentration, with industrial offset partnerships offering the viable go-to-market path. For Investors and Strategic Acquirers: Asymmetric upside sits with subsystem specialists holding captive millimeter-wave aperture technology and STANAG qualification track records. Long-term viability centers on software-defined upgrade revenue streams extending across multi-decade platform lifecycles. Watch Polish procurement acceleration rates as the inflection signal for eastern flank demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Seeker Convergence | MBDA's integration of imaging infrared with millimeter-wave radar bridges fire-and-forget and precision-designation categories for NATO interoperability. |
| Software-Defined Upgrade Path | Lockheed Martin's modular architecture extends Javelin system lifecycles without complete platform replacement, capturing sustainment revenue pools. |
| Captive Focal-Plane Array Production | Vertical integration into imaging infrared sensor supply insulates margin control from ITAR licensing delays and commercial market competition. |
| Performance-Based Sustainment Contracting | Unbundling after-sales service from initial acquisition creates discrete revenue streams for seeker refurbishment across United States Marine Corps programs. |
| Cross-Border Industrial Offset Partnership | Rheinmetall's Düsseldorf cluster anchors German-Polish procurement integration under NATO standardization mandates. |
Methodological Framework
Bottom-up armed forces procurement modeling reconciled against top-down defense contractor production tracking forms the analytical core of this study. Primary interviews with program managers at NATO procurement agencies, seeker subsystem engineers, military training pipeline officers, and export licensing administrators combined with secondary validation from STANAG qualification databases, national defense budget appropriations documents, and EU defense procurement directive filings. Cross-referencing focal-plane array supply disclosures against millimeter-wave sensor production capacity estimates enabled triangulation of supply-side constraints.
Input-output matrices mapped seeker technology adoption rates against armor threat evolution across the projection horizon. Segmentation dimensions modeled include product type tier, guidance architecture, application mission profile, and end-user procurement channel. CAGRs were derived from rolling qualification timelines and replacement cycle analysis. Forecast inputs incorporated active protection system proliferation curves and ITAR reform discussion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ITAR restriction tightening or accelerated EU defense procurement harmonization. Material deviation in Polish procurement acceleration rates or German KBA certification protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market