
 Martial Art Weapon Market | 2026-2036
Martial Art Weapon Market Size, Share, and Industry Trends Forecast 2026-2036
Martial Art Weapon Market Analytics
Certified weapon-craft instruction is bifurcating the supply base between artisan shops and scalable manufacturers. Century Martial Arts leverages vertical integration across foam-padded training weapons and protective gear to sustain bulk contracts with national dojo chains. SMAI anchors its position through Australian-designed competition-grade equipment that meets World Karate Federation specifications. Asian World of Martial Arts competes on breadth, stocking over eight hundred SKUs spanning traditional Okinawan weapons to modern training replicas.
Martial art weapons encompass purpose-built implements including swords, nunchaku, bo staffs, and sai, typically forged from wood, steel, bamboo, or engineered plastics with weight tolerances calibrated to kata and kumite standards. These instruments serve competitive regulation, demonstrative performance, and progressive skill acquisition across graded curricula. Wood and bamboo constructions dominate beginner and intermediate segments due to lower injury risk and favorable price positioning, while steel variants command premium placement in advanced and professional tiers where durability and authenticity determine selection. Training and competition usage types generate the highest volume throughput, though demonstration-grade weapons carry superior margins through custom finishing and ceremonial specifications.
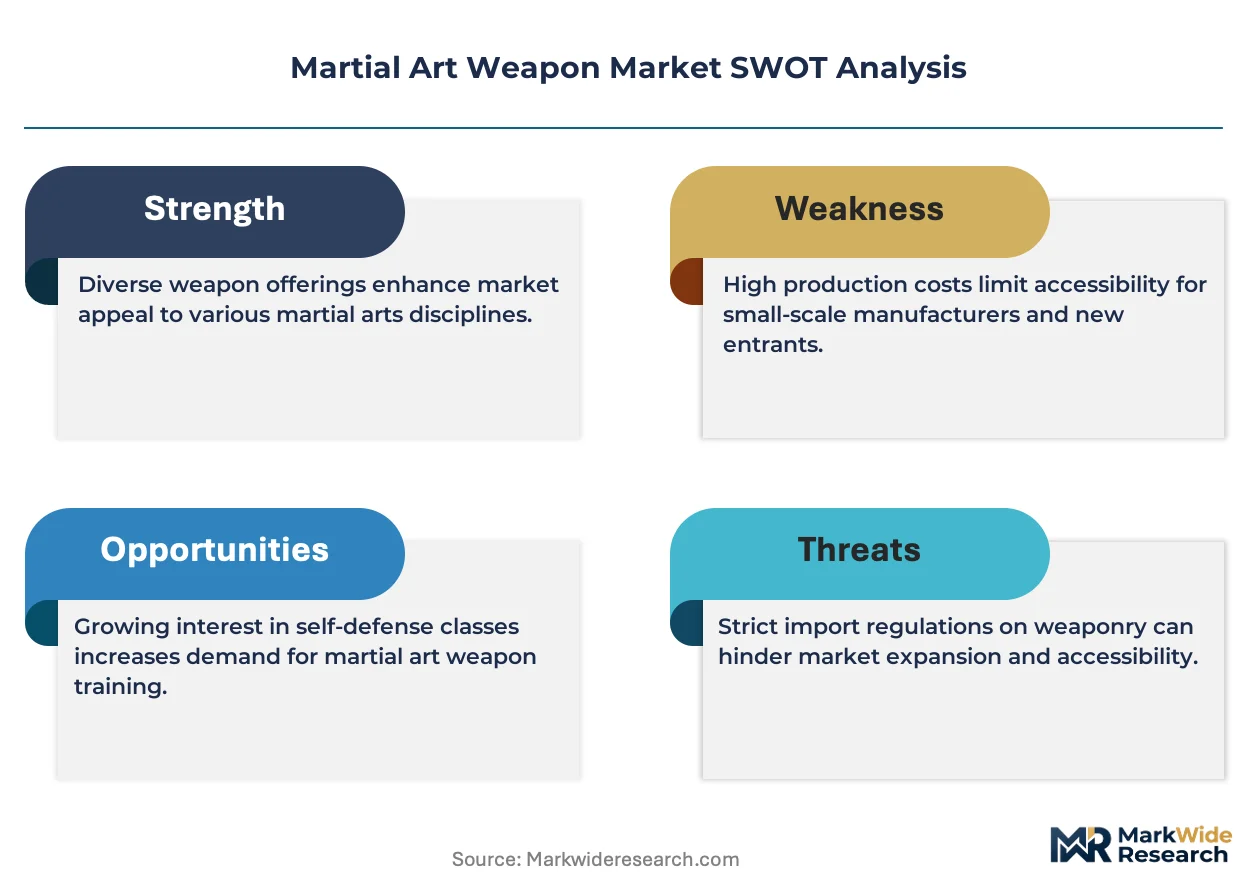
The Consumer Product Safety Commission enforces sharp-point and flammability standards on martial art weapons sold in the United States, while the EU REACH framework restricts heavy metal content in plated steel components and synthetic polymer treatments. Japan's Ministry of Economy, Trade and Industry maintains JIS standards for traditional blade geometry that constrain export-ready katana specifications. Stakeholders must monitor evolving national safety classifications that could reclassify training weapons as regulated sporting equipment, triggering compliance cost step-ups and channel redistribution.
Market Dynamics
Olympic recognition of karate and taekwondo is compressing procurement cycles for competition-grade equipment as national federations mandate standardized weapon specifications across affiliated academies.
Growth Catalysts
- REACH compliance migration:ECHA enforcement on heavy metal content in plated steel components is accelerating manufacturer adoption of certified bamboo and engineered polymer alternatives.
- Franchised dojo standardization:United States-based chains are consolidating weapon purchases across hundreds of locations, creating volume pull for bulk-certified SKU lines.
- World Karate Federation specifications:Competition-grade equipment mandates are elevating training standards and equipment replacement frequencies in professional academies.
Market Restraints
- Artisan supply concentration:Traditional Okinawan weapon craftsmanship remains concentrated in specialized Japanese workshops, limiting scalable output for international bulk contracts.
- Steel input volatility:Premium katana-grade steel pricing fluctuations compress margin stability for advanced-tier manufacturers.
- JIS geometry constraints:Japan's Ministry of Economy, Trade and Industry blade specifications restrict export-ready katana design flexibility, constraining product line breadth.
Strategic Opportunities
- E-commerce direct channels:Specialty retailers are bypassing traditional wholesale distributors to reach individual practitioners and small dojo operators.
- Composite material convergence:Engineered plastics and carbon fiber hybrids are opening performance-tier positioning between bamboo training tools and steel competition weapons.
- Australian federation alignment:SMAI-designed equipment meeting World Karate Federation specifications creates template demand across Commonwealth affiliate nations.
Industry Challenges
- Certified instructor scarcity:Weapon-craft teaching credentials required for liability insurance coverage are creating bottlenecks in academy expansion plans.
- Multi-jurisdiction compliance:Divergent CPSC sharp-point standards, EU REACH chemical restrictions, and JIS geometry rules force SKU fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Martial Art Weapon Market |
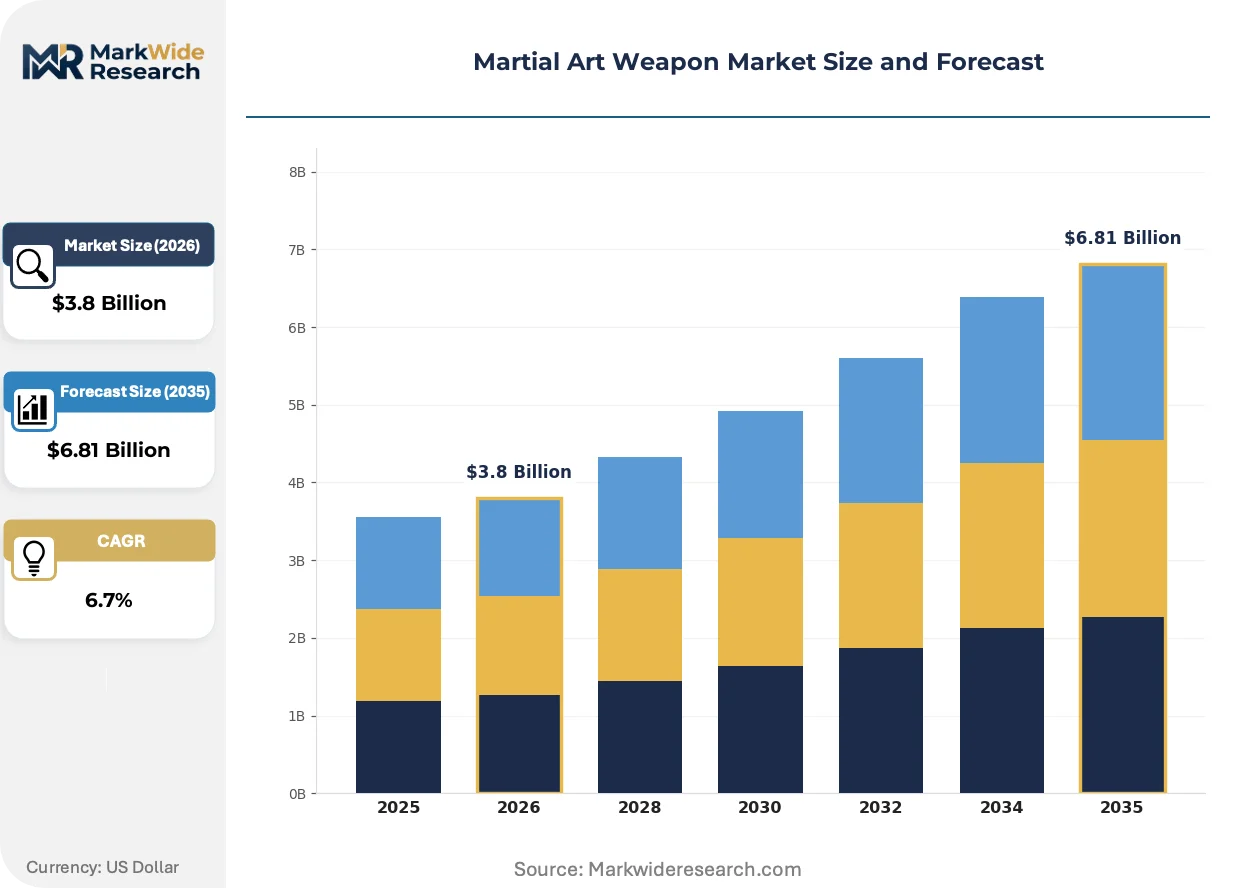
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Sword, Nunchaku, Bo Staff, Sai Material: Wood, Steel, Bamboo, Plastic Skill Level: Beginner, Intermediate, Advanced, Professional Usage Type: Training, Competition, Sparring, Demonstration |
| Companies Covered | Century Martial Arts, KarateMart Martial Arts Supplies, Martial Art Shop, Asian World of Martial Arts, SMAI, BrassK, Golden Tiger Martial Art, The Martial Arts Store, Century LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Martial Art Weapon Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing traditional supply hierarchies while elevating performance verification requirements across all price tiers.
Engineered polymer cores wrapped in impact-absorbing foam are displacing solid wood construction in beginner and intermediate training weapons. United States dojo chains are adopting these variants at accelerated pace to reduce injury liability exposure and extend equipment lifespan. This material shift is bifurcating the supply base between artisan wood-craft specialists and scalable injection-molding manufacturers capable of batch certification.
ECHA REACH enforcement on heavy metal content in plated steel components is forcing reformulation of traditional sai and kama finishing processes. Manufacturers serving EU markets are migrating toward electroless nickel and ceramic coating alternatives that maintain corrosion resistance without restricted substances. Competition-grade steel weapons bound for European distribution are most affected, with certification documentation now standard contract terms.
National federation procurement consolidation is compressing vendor diversity as standardized equipment lists reduce academy-level discretion. Bulk purchasing agreements between franchised chains and certified manufacturers are displacing fragmented local supplier relationships. This concentration is most visible across United States metropolitan markets where multi-location operators negotiate system-wide supply contracts.
Martial Art Weapon Market Segmentation
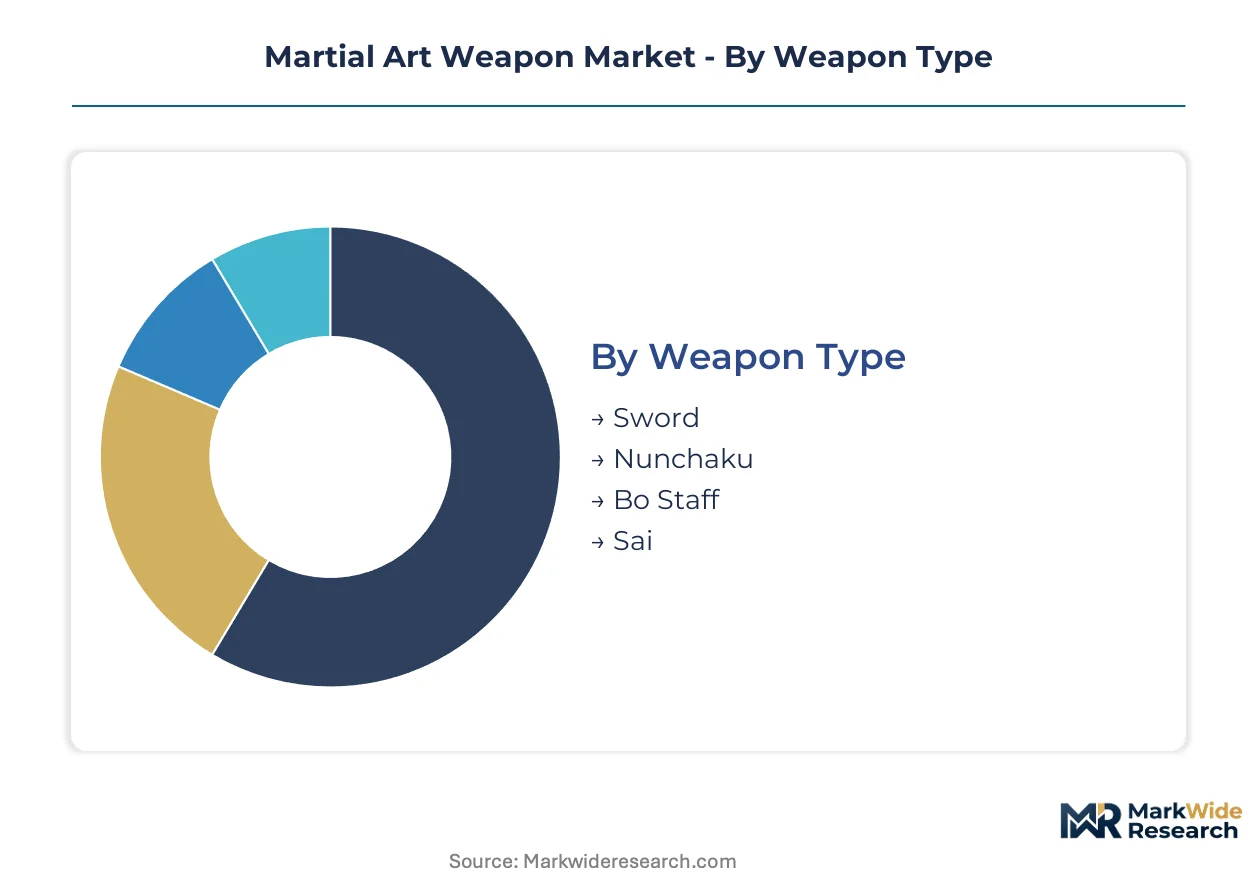
Martial art weapon procurement diverges sharply across training contexts, with substitution pressures from engineered materials reshaping traditional category boundaries. Equipment selection tracks liability exposure, federation compliance, and curriculum progression in interconnected ways that defy simple price-tier logic.
Weapon Type:
Composite training tools and foam-wrapped alternatives are displacing traditional wood and steel constructions in high-volume dojo contracts, pressuring legacy forging methods most acutely in beginner-oriented categories.
- Sword:Katana and bokken variants span bamboo training replicas through folded-steel competition blades. United States franchised chains standardize foam-padded bokken purchases across hundreds of locations to reduce injury liability and extend equipment lifespan.
- Bo Staff:Six-foot wooden staffs remain the foundational training implement across karate and kobudo curricula. Japanese workshops concentrate traditional white oak craftsmanship, limiting scalable output for international bulk contracts despite steady academy demand.
- Nunchaku:Foam-chain training versions dominate beginner instruction, while competition-grade hardwood and aluminum variants serve advanced kata performance.
- Sai:Three-pronged Okinawan implements face REACH compliance pressure on plated steel finishes, accelerating ceramic coating adoption for EU-bound shipments.
Bo Staff anchors the volume base while Sword gains share at the steepest rate through competition-grade specification upgrades.
Material:
Cost tier stratification separates premium steel from mass-market synthetics, with mid-position bamboo capturing federation sustainability preferences.
- Wood:Traditional white oak and red oak constructions dominate beginner instruction across North American and European academies. Lower injury risk and favorable price positioning sustain wood's share despite shorter replacement cycles.
- Steel:Folded and laminated blade constructions command premium placement in advanced and professional tiers. Japan's METI maintains JIS standards for traditional blade geometry that constrain export-ready katana specifications.
- Bamboo:Lightweight, splinter-resistant alternatives are displacing wood in youth and beginner segments. EU REACH alignment accelerates bamboo adoption as certified sustainable feedstock.
- Plastic:Engineered polymer cores wrapped in impact-absorbing foam are expanding fastest among United States dojo chains seeking liability reduction.
Wood retains the broadest installed base while engineered plastics climb the fastest through chain procurement consolidation.
Skill Level:
Curriculum progression requirements create discrete equipment upgrade moments that manufacturers target with tiered certification bundles.
- Beginner:Foam-padded and lightweight wood constructions predominate, with injury prevention driving procurement decisions. United States dojo insurance requirements mandate certified equipment for liability coverage.
- Intermediate:Standardized wood and bamboo implements bridge toward competition specifications. World Karate Federation equipment lists reduce academy-level discretion in federated programs.
- Advanced:Steel and hybrid constructions introduce authentic weight and balance characteristics. Certified instructor scarcity creates bottlenecks in academy expansion plans at this tier.
- Professional:Competition-grade steel and custom-finished demonstration weapons carry superior margins through ceremonial specifications and federation compliance documentation.
Beginner tier generates absolute volume while Professional commands the steepest margin expansion.
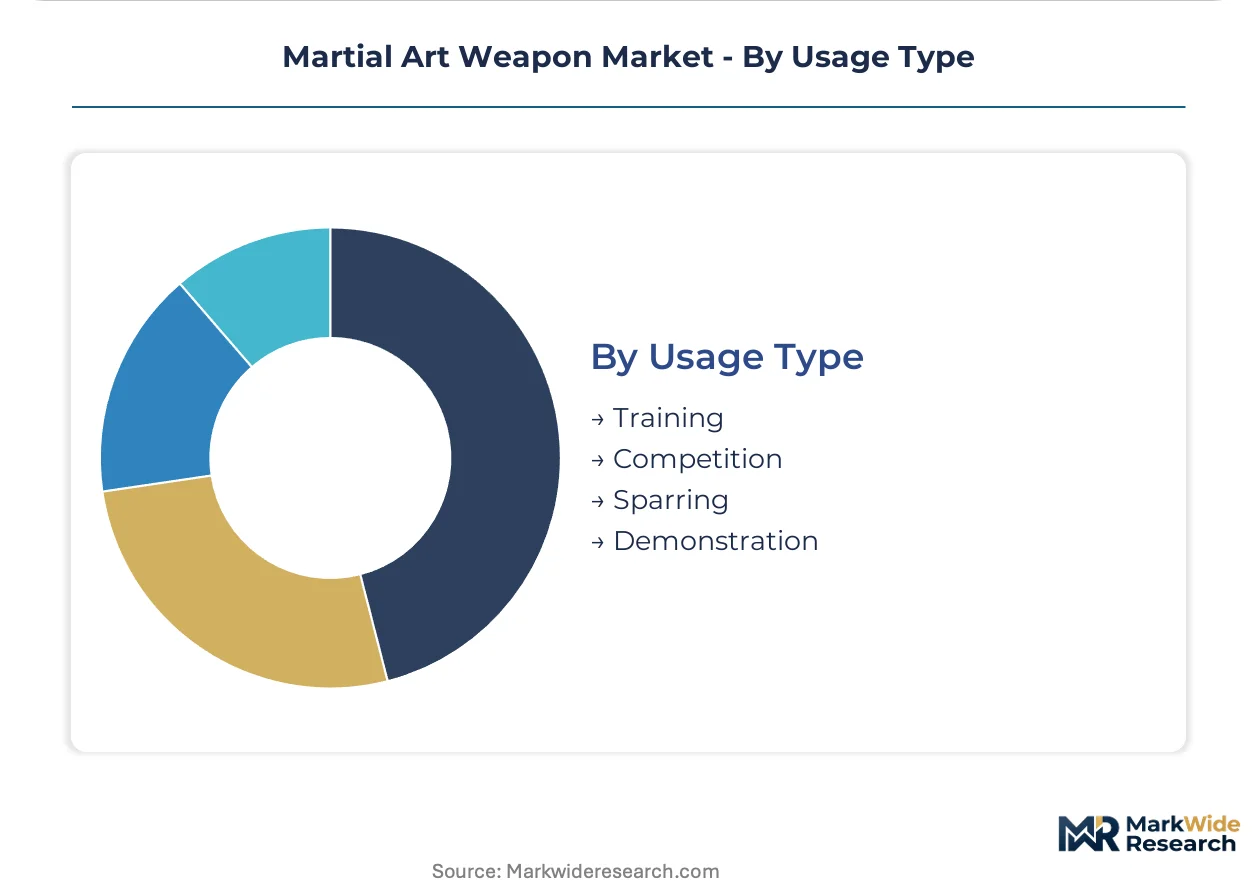
Usage Type:
Application context determines liability exposure, replacement frequency, and documentation requirements in divergent procurement patterns.
- Training:High-volume, high-wear implements dominate absolute unit shipments. Foam-wrapped and engineered polymer variants extend lifespan and reduce injury claims across United States metropolitan dojo chains.
- Competition:Federation-mandated specifications elevate equipment replacement frequencies and certification documentation requirements. World Karate Federation standardization compresses vendor diversity in affiliated programs.
- Sparring:Contact-rated padded weapons balance performance simulation with injury mitigation. ECHA REACH enforcement on heavy metal content affects plated steel component sourcing for EU-bound equipment.
- Demonstration:Custom finishing, ceremonial specifications, and presentation-grade materials carry superior margins. Artisan workshops concentrate output in this low-volume, high-margin category.
Training generates absolute throughput while Demonstration extracts the highest unit economics through customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Consumer Product Safety Commission anchors regulatory oversight in the United States, where franchised dojo chains drive standardization across metropolitan training networks. ECHA REACH compliance reshapes European procurement patterns, while Japan's METI maintains traditional blade geometry standards that constrain export specifications.
United States
Franchised dojo chains consolidate weapon purchases across hundreds of locations, creating volume pull for bulk-certified SKU lines. The Consumer Product Safety Commission enforces sharp-point and flammability standards on martial art weapons sold domestically. Metropolitan training networks in California, Texas, and Florida anchor equipment distribution density.
Japan
Traditional Okinawan weapon craftsmanship remains concentrated in specialized workshops serving authentic blade geometry requirements. The Ministry of Economy, Trade and Industry maintains JIS standards for traditional katana specifications that constrain export-ready designs. Osaka and Nagoya industrial clusters concentrate artisan forging capacity for international competition-grade equipment.
Germany
ECHA REACH enforcement on heavy metal content accelerates manufacturer migration toward certified bamboo and engineered polymer alternatives. The EU regulatory framework restricts plated steel component treatments across sporting equipment categories. Bavarian and North Rhine-Westphalian distribution hubs channel compliant inventory into Central European academy networks.
Australia
Commonwealth federation alignment creates template demand for competition-grade equipment meeting World Karate Federation specifications. The Therapeutic Goods Administration and state-level consumer safety offices oversee sporting equipment classifications. Sydney and Melbourne metropolitan dojo density supports specialized retailer consolidation.
United Kingdom
Post-Brexit regulatory divergence creates dual-track compliance requirements for EU-exporting and domestic-focused manufacturers. Trading Standards and the Office for Product Safety and Standards enforce sharp-point classifications on martial art equipment. London and Southeast England training academy clusters drive premium-tier equipment procurement.
Martial Art Weapon Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration separating bulk-contract players from artisan workshops. The supply base bifurcates between scalable manufacturers capable of batch certification and traditional craft specialists concentrated in Japanese and Okinawan production clusters. Strategic archetypes include foam-padded training equipment integrators, federation-certified competition specialists, and breadth-oriented multi-SKU distributors. Competitive moves concentrate on e-commerce channel bypass of traditional wholesale networks and composite material convergence between bamboo training tools and steel competition weapons.
Among North American equipment suppliers, Century Martial Arts and KarateMart Martial Arts Supplies occupy positions within the integrated manufacturer tier, while SMAI represents the federation-aligned competition-grade specialist archetype. Asian World of Martial Arts exemplifies the breadth-focused distributor model spanning traditional Okinawan weapons to modern training replicas.
| Leading Market Players |
|---|
| Century Martial Arts |
| KarateMart Martial Arts Supplies |
| Martial Art Shop |
| Asian World of Martial Arts |
| SMAI |
| BrassK |
| Golden Tiger Martial Art |
| The Martial Arts Store |
| Century LLC |
| Others |
Value Network & Pricing Analysis
EU REACH certification gates supply qualification while simultaneously stratifying price tiers across the martial art weapon market. Manufacturers must absorb compliance documentation costs to access European distribution, creating tiered entry barriers that separate certified bamboo and engineered polymer suppliers from untreated wood and plated steel alternatives. This regulatory filter compresses margins for non-compliant producers while elevating premium positioning for documented sustainable feedstock lines.
Pricing Analysis
Japan-to-United States price spreads on folded-steel katana exceed threefold due to JIS geometry compliance costs and artisan workshop concentration. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with franchised dojo chains extracting bulk discounts on foam-padded training weapons. Cost compression in economy-tier wood constructions intensifies as engineered polymers displace solid oak in beginner segments. Small independent dojos exhibit highest price sensitivity, while national federation procurement shows least elasticity due to mandated specification compliance.
Supply Chain Analysis
Container availability constraints on transpacific lanes from Osaka and Nagoya ports elevate inbound logistics costs for United States distributors sourcing competition-grade steel weapons. Supply concentrates in Japan for traditional blade forging, China for engineered polymer injection molding, and United States for foam-wrapped training equipment assembly. Raw material dependencies span premium katana-grade steel, certified sustainable bamboo, and impact-absorbing polymer resins. Single-source vulnerability concentrates in specialized Okinawan white oak workshops. Distribution runs through franchised dojo chain direct contracts and specialty e-commerce platforms bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The martial art weapon market sits in early-cycle expansion as Olympic recognition of karate and taekwondo elevates training standards and equipment replacement frequencies across affiliated academies. Federation standardization creates predictable procurement pipelines that reward early positioning in certified supply tiers.
For Market Incumbents: Fortify federation certification portfolios against emerging composite material specialists by deepening backward integration into certified bamboo feedstock and captive foam-polymer production. Channel control through exclusive supply agreements with expanding United States metropolitan dojo chains defends margin position against direct-to-consumer e-commerce entrants. For New Entrants and Emerging Players: Differentiate on REACH-compliant ceramic coating technology for sai and kama exports to EU markets, where incumbent plated steel finishing faces regulatory obsolescence. White-space concentration sits in Commonwealth federation alignment following SMAI's World Karate Federation specification template across Australia, Canada, and affiliate nations. Go-to-market leverage targets mid-tier independent dojos through e-commerce bypass of traditional wholesale markups. For Investors and Strategic Acquirers: ECHA enforcement milestones reshape the acquisition landscape toward certified sustainable feedstock capabilities and batch-certification manufacturing scale. Long-term viability centers on regulatory compliance infrastructure rather than artisan craft heritage. Acquisition target archetype: injection-molding specialists with existing sporting equipment certification and capacity for engineered polymer weapon cores. Signal to watch: national federation procurement consolidation announcements compressing vendor diversity in United States metropolitan markets.| Strategic Initiative | Industry Significance |
|---|---|
| Federation Certification Investment | World Karate Federation specification alignment unlocks national procurement pipeline access across affiliated academies. |
| Composite Material Convergence | Carbon fiber hybrid development bridges performance gaps between bamboo training tools and steel competition weapons. |
| E-commerce Channel Bypass | Direct-to-dojo platforms displace wholesale intermediaries and capture margin from fragmented independent academy procurement. |
| REACH Compliance Migration | Electroless nickel and ceramic coating adoption maintains EU market access as plated steel finishes face ECHA restriction. |
| Franchised Chain Consolidation | System-wide supply contracts with multi-location operators compress vendor diversity and secure volume throughput. |
Research Methodology
Initial hypotheses were tested against primary input from dojo operators, equipment procurement managers at franchised chains, federation compliance officers, and artisan workshop owners, then refined against secondary validation. Primary fieldwork combined structured interviews with secondary source triangulation across CPSC enforcement records, ECHA REACH substance restriction updates, METI JIS standard documentation, and World Karate Federation equipment specification releases. Bottom-up academy procurement surveys and top-down manufacturer shipment analysis were reconciled to establish market sizing.
Variance decomposition across weapon type, material composition, skill tier, and usage application anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation and cross-validation against federation expansion schedules and dojo chain opening plans. Modeled inputs incorporated Olympic program inclusion effects on training standard elevation, REACH compliance cost pass-through elasticity, and substitution rates from wood to engineered polymer constructions.
The analysis sits within stated boundaries; outcomes outside sustained federation standardization momentum, stable regulatory enforcement timelines, or continued franchised chain expansion would require recalibration. Forecasts reflect documented assumptions regarding certification adoption curves and material substitution elasticities. Specific risks that could revise projections include JIS specification amendments constraining export designs, ECHA substance restriction list expansion beyond current heavy metal targets, or liability insurance requirement shifts affecting academy equipment procurement budgets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Directed Energy Weapons Market