
 Missile Seekers Market | 2026-2036
Missile Seekers Market Size, Share, and Industry Trends Forecast 2026-2036
Missile Seekers Market Outlook
The gap between fifth-generation seekers with multi-spectral fusion and legacy single-band units is expanding across procurement portfolios. Northrop Grumman leverages in-house semiconductor foundry capacity to dominate infrared focal plane array production. Lockheed Martin anchors its position through captive supply chains for radar seeker front-ends. Raytheon Technologies differentiates via software-defined seeker architectures that reduce hardware refresh cycles.
Missile seekers are precision guidance subsystems that detect, track, and lock onto targets through electromagnetic sensing, typically operating across infrared, millimeter-wave, or laser wavelengths with micro-radian angular resolution. Their primary purpose is terminal homing accuracy for kinetic weapons in contested air and maritime environments. Infrared technology leads installed base volumes due to passive operation advantages, while imaging segments command premium pricing from target discrimination software requirements. Homing seekers represent the fastest-growing type category as hypersonic interceptors demand autonomous terminal engagement without external illumination.
ITAR compliance in the United States, REACH material restrictions in Europe, and China's GB standards for dual-use components collectively shape component sourcing and cross-border technology transfer protocols. The FAA and NHTSA do not regulate this sector; defense-specific agencies including the US Department of State Directorate of Defense Trade Controls and the EU's European Defence Agency establish market access thresholds. Stakeholders must monitor shifting semiconductor export controls and sovereign seeker development programs in multiple jurisdictions to anticipate supplier displacement risks.
Market Dynamics
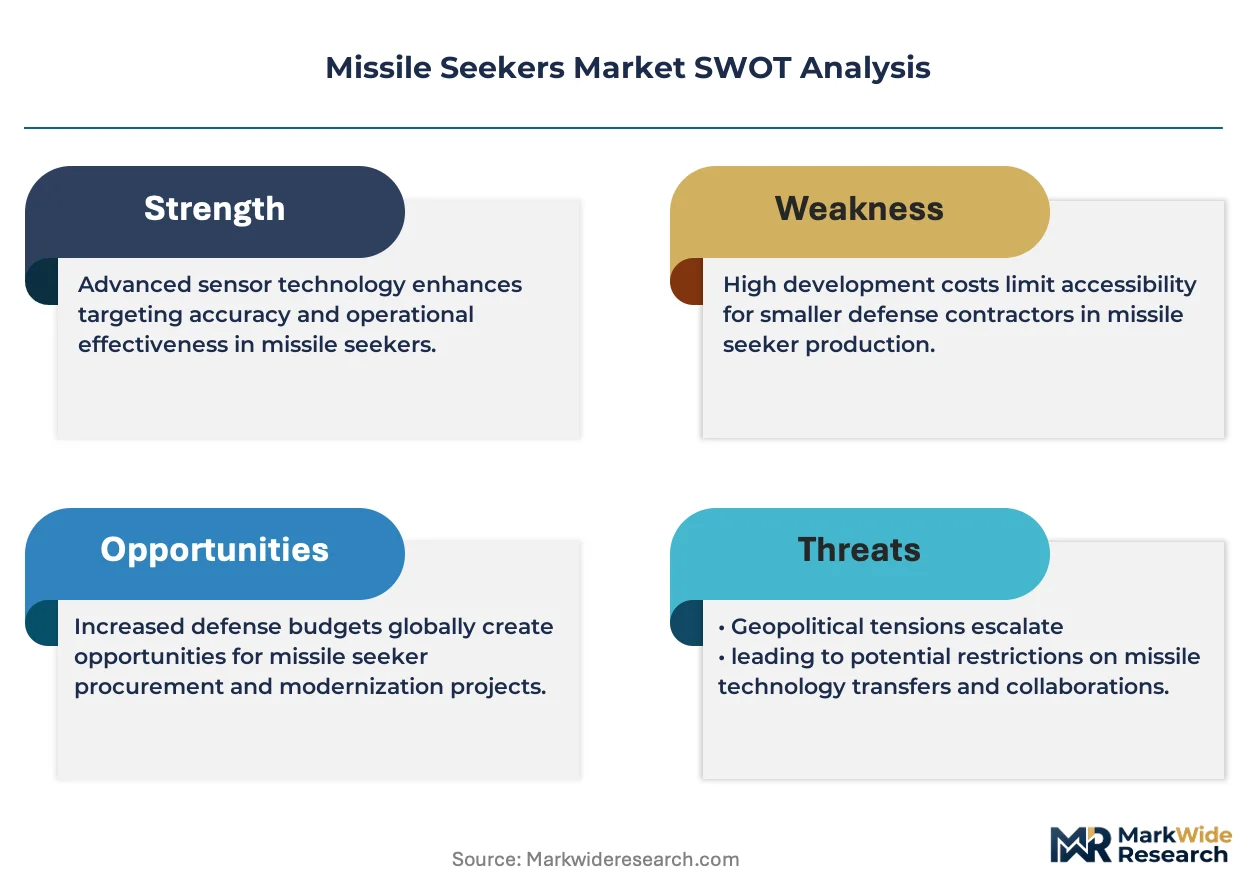
Semiconductor substrate innovations and ITAR export control tightening are bifurcating supplier qualification pathways, concentrating production among foundry-capable defense contractors while disqualifying legacy component vendors from next-generation programs.
Growth Catalysts
- Multi-spectral fusion architectures:NATO air dominance platforms demand seekers combining infrared, millimeter-wave, and laser wavelengths for contested electronic warfare environments.
- Hypersonic interceptor programs:Autonomous terminal engagement requirements for Mach 5+ weapons are accelerating homing seeker procurement across multiple defense agencies.
- Arizona-Texas manufacturing corridor expansion:Concentrated aerospace electronics infrastructure in these states reduces supply chain latency for focal plane array integration.
Market Restraints
- Indium antimonide and mercury cadmium telluride volatility:Critical infrared detector materials face price instability and limited non-Chinese refining capacity.
- ITAR-controlled semiconductor foundry concentration:Domestic U.S. trusted foundry capacity for radiation-hardened seeker processors remains restricted to three qualified facilities.
- Single-band legacy seeker obsolescence:Existing inventories of first-generation infrared units face accelerated depreciation against multi-spectral performance benchmarks.
Strategic Opportunities
- Software-defined seeker architectures:Algorithm-upgradable guidance systems reduce hardware refresh frequency and open recurring revenue streams.
- European sovereign seeker initiatives:EU member states are funding indigenous focal plane array development to reduce transatlantic dependency.
- Dual-use infrared sensor convergence:Automotive lidar and seeker focal plane array process overlaps create shared R&D cost pools.
Industry Challenges
- Cleared workforce scarcity:TS/SCI-cleared semiconductor process engineers and infrared physicists command premium compensation and extended recruitment timelines.
- ITAR compliance certification delays:New supplier qualification through the Directorate of Defense Trade Controls extends 18-24 months for foreign component integration.
- Legacy platform integration friction:Fourth-generation aircraft weapon buses require costly seeker interface adaptation for modern digital guidance outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missile Seekers Market |
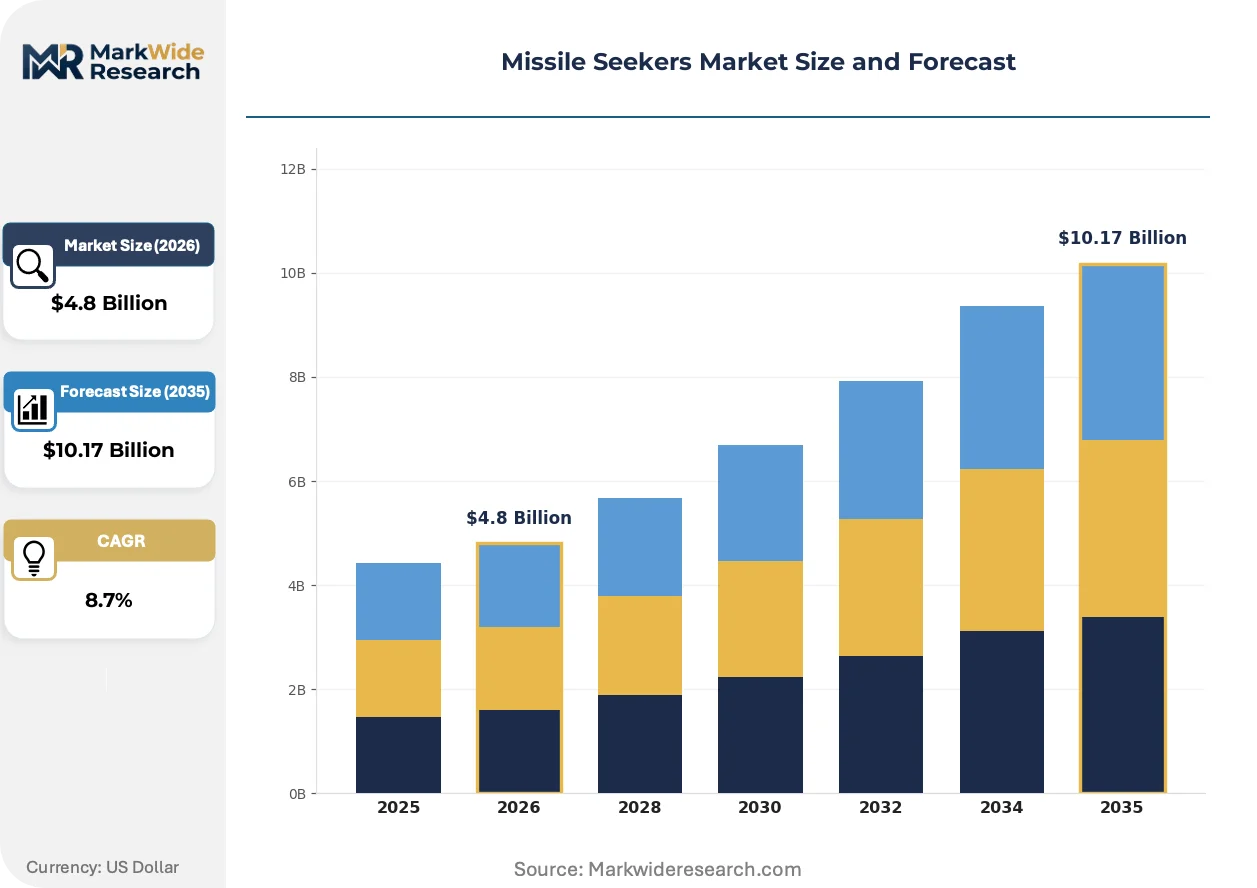
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Active, Passive, Semi-Active, Homing Technology: Infrared, Radar, Laser, Imaging Application: Air-to-Air, Air-to-Ground, Surface-to-Air, Anti-Ship End User: Military, Defense Contractors, Government Agencies, Private Security |
| Companies Covered | Northrop Grumman, Leonardo S.p.A., Lockheed Martin, Boeing, Safran Group, Raytheon Technologies, Thales Group, Elbit Systems, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missile Seekers Market Strategic Shifts
Seeker technology is pivoting from hardware-defined to software-upgradable architectures, compressing development cycles and altering how defense primes structure supplier relationships around algorithmic rather than physical performance.
Multi-spectral focal plane arrays are rewriting terminal homing accuracy standards by fusing simultaneous infrared and millimeter-wave target signatures. Naval strike missile programs are adopting these units fastest, with ship-launched requirements driving the procurement pace. The technology is compressing hardware refresh cycles from decade-long platforms to algorithmic update schedules.
REACH material restrictions in Europe are forcing substitution of traditional seeker coolants and detector substrate materials. German and French defense contractors now face mandatory supply chain audits for restricted substances in infrared detector manufacturing. Imaging seeker segments absorb the highest compliance costs, passing these through to national procurement budgets.
Defense agencies are consolidating prime contractor relationships around integrated seeker-to-missile system responsibility rather than component procurement. This unbundles legacy tiered supplier structures and concentrates risk with platform primes. The United States and United Kingdom exhibit this pattern most visibly, with multi-year system-level contracts displacing annual component orders.
Missile Seekers Market Segmentation
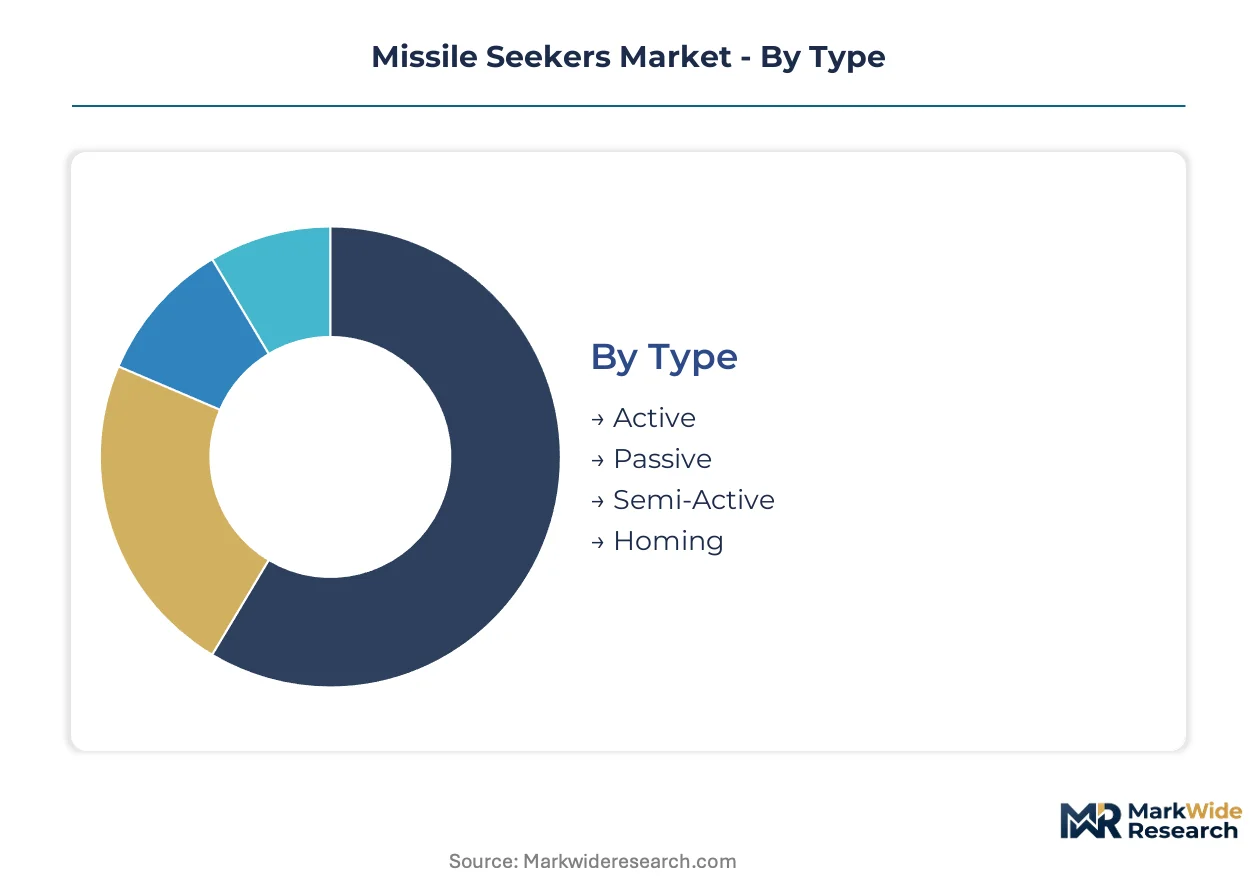
Missile seekers divide along functional, technological, and operational dimensions that determine integration complexity and procurement pathways. Each segmentation axis carries distinct qualification requirements and supply chain footprints that shape vendor selection.
Type:
Customization intensity spans from fully autonomous homing systems requiring minimal platform interface to semi-active designs demanding continuous illuminator support.
- Active:Self-contained emitters generate target illumination independent of external sources. Naval strike missile programs in the United States and United Kingdom concentrate procurement here for over-the-horizon engagements where platform radar exposure risks detection.
- Passive:Detectors rely solely on target-emitted or ambient electromagnetic signatures without active emission. Air-to-air interceptors across NATO member states favor this mode for reduced electromagnetic signature and launch-and-leave operational flexibility.
- Semi-Active:Requires continuous external illumination from launching platform or cooperative designator. Legacy surface-to-air batteries maintain substantial installed base, though new procurement favors autonomous alternatives.
- Homing:Terminal guidance autonomy enables kinetic intercept without post-launch platform support. Hypersonic defense programs in the United States and Japan drive steepest capacity expansion for Mach 5+ engagement requirements.
Most installed capacity flows through Passive seekers. Expansion is steepest in Homing.
Technology:
Performance tiering separates established single-band architectures from emerging multi-spectral fusion platforms commanding premium integration timelines.
- Infrared:Passive thermal detection across short-wave, mid-wave, and long-wave bands dominates volume production due to mature focal plane array manufacturing. Arizona and Texas manufacturing corridors concentrate detector integration for U.S. defense primes.
- Radar:Active millimeter-wave and microwave seekers provide all-weather performance against low-observable targets. European sovereign seeker initiatives in Germany and France prioritize indigenous radar front-end development to reduce transatlantic dependency.
- Laser:Semi-active laser designation enables precision strike against stationary and slow-moving surface targets. Air-to-ground munitions for close air support missions maintain steady procurement across U.S. and Israeli defense portfolios.
- Imaging:Two-dimensional focal plane arrays enable target discrimination through shape recognition algorithms. Software-defined architectures permitting algorithmic updates without hardware refresh distinguish premium procurement tiers.
Volume leadership sits with Infrared technology. Imaging commands the highest unit economics and steepest technology refresh rates.
Application:
Operational environment dictates seeker wavelength selection, with maritime and aerial domains imposing distinct atmospheric propagation and countermeasure resilience requirements.
- Air-to-Air:Short-range dogfight and beyond-visual-range interceptors demand rapid acquisition against maneuvering targets. Passive infrared and active radar seekers split procurement based on rules of engagement and electronic warfare threat density.
- Air-to-Ground:Precision strike against fortified and mobile surface targets requires target designation compatibility and clutter rejection. Semi-active laser and imaging infrared configurations dominate this segment with substantial U.S. and Israeli procurement concentration.
- Surface-to-Air:Area and point defense batteries prioritize all-weather engagement capability against saturation raids. Radar seekers with infrared backup channels represent the emerging standard for layered air defense architectures.
- Anti-Ship:Sea-skimming flight profiles and maritime clutter environments drive multi-spectral fusion adoption. Naval programs in the United States, United Kingdom, and Japan lead integration of combined infrared-millimeter-wave seekers for terminal homing.
Procurement volume concentrates in Air-to-Ground applications. Anti-Ship programs exhibit the most rapid technology upgrade cycles.
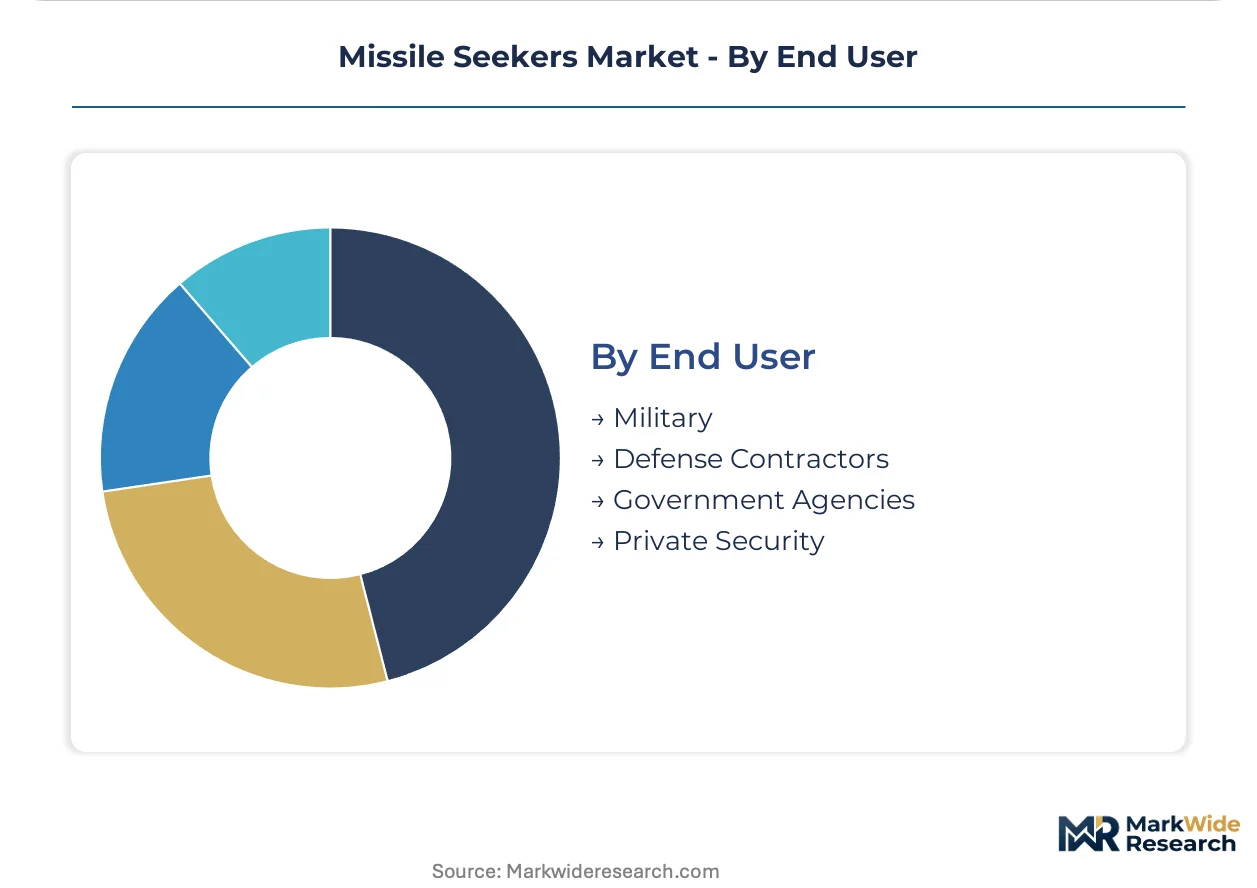
End User:
Contracting authority and security clearance infrastructure create distinct supplier access tiers, with national military procurement separated from subcontractor and agency channels by ITAR and comparable export control regimes.
- Military:National armed forces represent the primary procurement authority through program executive offices and defense acquisition commands. U.S. Department of Defense and UK Ministry of Defence establish seeker performance specifications that cascade through prime contractor supply chains.
- Defense Contractors:Prime and tier-one system integrators procure seeker subsystems for platform integration under government contracts. Northrop Grumman, Lockheed Martin, and Raytheon Technologies maintain captive or qualified supplier relationships for focal plane array and radar front-end sourcing.
- Government Agencies:Research and development organizations including DARPA and the European Defence Agency fund technology maturation programs that transition to production contracts. These channels emphasize algorithmic performance and multi-spectral fusion advancement.
- Private Security:Non-state demand remains negligible due to ITAR-controlled component restrictions and national ownership requirements for guided munitions. This channel captures minimal revenue share.
Contract flow concentrates through Military procurement authorities. Defense Contractors absorb the steepest supply chain qualification burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleared semiconductor process engineers and infrared physicists concentrate disproportionately in the Arizona-Texas aerospace corridor, creating a talent moat that shapes procurement geography across NATO defense programs.
United States
Hypersonic interceptor programs and next-generation air dominance platforms drive multi-spectral seeker procurement through the Department of Defense. ITAR controls administered by the Directorate of Defense Trade Controls restrict foreign component integration to qualified domestic foundries. The Arizona-Texas manufacturing corridor hosts concentrated focal plane array integration facilities serving prime defense contractors.
United Kingdom
Royal Navy anti-ship missile modernization and RAF beyond-visual-range air-to-air requirements sustain steady seeker subsystem demand. The UK Ministry of Defence consolidates contracting authority around system-level procurement rather than discrete component orders. Defense electronics clusters in Scotland and the English Midlands maintain legacy semi-active seeker support while transitioning to autonomous homing architectures.
Germany
European sovereign seeker initiatives prioritize indigenous focal plane array development to reduce transatlantic supply dependency. REACH material restrictions enforced by ECHA force substitution of traditional infrared detector coolants and substrate materials. Bavarian and Baden-Württemberg defense electronics clusters absorb compliance costs through national procurement budget adjustments.
France
Naval strike missile programs and Rafale fighter integration sustain demand for combined infrared-millimeter-wave seekers. The French defense procurement agency directs funding toward multi-spectral fusion maturation through European collaborative frameworks. Aerospace electronics concentration in the Île-de-France and Provence-Alpes-Côte d'Azur regions supports Thales and Safran seeker development pipelines.
Japan
Hypersonic defense programs in partnership with U.S. agencies accelerate homing seeker procurement for Mach 5+ engagement requirements. METI coordinates dual-use infrared sensor development leveraging automotive lidar process overlaps. Defense electronics manufacturing concentrates in the Nagoya-Chubu corridor and Kanto region surrounding Tokyo.
Missile Seekers Market Competitive Environment
Capital-heavy producers with captive semiconductor foundry capacity compete with asset-light designers dependent on qualified external fabrication. The market structure concentrates around three to five vertically integrated primes controlling focal plane array and radar front-end supply chains. Strategic archetypes separate into foundry-capable system integrators, software-defined architecture specialists, and European sovereign champions. Dominant competitive moves include backward integration into semiconductor processing and multi-year system-level contract consolidation displacing annual component procurement.
Among U.S.-based primes, Northrop Grumman, Lockheed Martin, and Raytheon Technologies occupy positions across the technology spectrum. Northrop Grumman exemplifies the foundry-integrated archetype through in-house semiconductor production capacity. Lockheed Martin anchors the captive supply chain model for radar seeker front-ends. Raytheon Technologies represents the software-defined seeker architecture approach that reduces hardware refresh frequency. European counterparts including Leonardo S.p.A., Thales Group, and Safran Group sit within the sovereign development tier, while Elbit Systems and BAE Systems occupy specialized positions in their respective national defense ecosystems.
| Leading Market Players |
|---|
| Northrop Grumman |
| Leonardo S.p.A. |
| Lockheed Martin |
| Boeing |
| Safran Group |
| Raytheon Technologies |
| Thales Group |
| Elbit Systems |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
Indium antimonide and mercury cadmium telluride feedstock costs cascade through three distinct pricing tiers for infrared focal plane arrays, with ITAR-controlled wafer processing premiums separating qualified U.S. foundry output from legacy single-band alternatives facing accelerated depreciation.
Pricing Analysis
Component-level procurement dominates legacy programs while system-level bundled contracts capture next-generation multi-spectral platforms. Price differentiation rests on ITAR certification tier and software-defined upgrade pathways. Cost compression in single-band legacy units is intensifying because defense primes consolidate around autonomous homing specifications. Tier-two defense contractors exhibit highest price sensitivity due to captive supply chain exclusion, whereas national program executive offices absorb premium multi-spectral fusion costs through multi-year appropriations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese refining capacity for mercury cadmium telluride substrates. Manufacturing concentration spans the United States, Germany, and Japan for qualified focal plane array integration. The supply chain draws from Arizona-Texas semiconductor corridors for detector packaging and European sovereign initiatives for radar front-end alternatives. Tariff exposure on critical infrared materials represents the dominant structural risk. Distribution runs through prime contractor captive supply chains rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITAR export control tightening functions as a regulatory compounder, with Directorate of Defense Trade Controls qualification timelines extending procurement cycles and concentrating supplier relationships among cleared domestic foundries.
For Market Incumbents: To counter European sovereign seeker initiatives eroding transatlantic dependency, Northrop Grumman and Lockheed Martin should deepen backward integration into compound semiconductor processing and expand Arizona-Texas focal plane array capacity. Captive wafer fabrication anchors pricing power against emerging indigenous European alternatives.
For New Entrants and Emerging Players: REACH material restrictions in Europe open a window for compliant coolant and substrate substitution technologies. White-space targets include German and French defense electronics clusters facing mandatory supply chain audits, plus dual-use automotive lidar convergence for shared R&D cost pools. A go-to-market angle through qualified subcontractor status bypasses prime contractor ITAR barriers.
For Investors and Strategic Acquirers: Roll-up economics work for software-defined seeker architecture specialists because algorithm-upgradable platforms reduce hardware refresh frequency and generate recurring revenue streams. Long-term viability centers on five-to-ten year defense procurement cycles shifting from component to system-level contracting. Acquisition targets should exhibit qualified foundry relationships or algorithmic discrimination software stacks. The signal to watch is European Defence Agency funding disbursements for indigenous focal plane array development.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Processing | Captive wafer fabrication insulates against ITAR-controlled foundry concentration and Chinese feedstock volatility. |
| Software-Defined Architecture Development | Algorithm-upgradable guidance compresses hardware refresh cycles and opens recurring revenue at Raytheon Technologies. |
| European Sovereign Seeker Initiative Participation | EU funding for indigenous focal plane arrays reduces transatlantic dependency for Thales and Safran. |
| Dual-Use Automotive Lidar Convergence | Shared R&D cost pools with METI-coordinated Japanese sensor programs lower infrared detector development burden. |
| Multi-Spectral Fusion Platform Integration | Combined infrared-millimeter-wave seekers meet Naval strike missile requirements across U.S., UK, and Japan. |
Study Parameters
Bottom-up defense procurement modeling reconciled against top-down prime contractor supply chain tracking forms the analytical core. Primary interviews with program executive officers, semiconductor process engineers, infrared physicists, and defense acquisition command procurement leads combine with secondary validation from Department of Defense budget justification materials, SEC 10-K filings, Directorate of Defense Trade Controls registration data, and European Defence Agency collaborative framework announcements. Triangulation between component-level production estimates and system-level contract awards ensures consistency across segmentation dimensions.
Input-output matrices connect seeker technology adoption curves to platform procurement schedules across the projection horizon. Segmentation dimensions modeled include seeker type, technology wavelength, application domain, and end-user contracting authority. CAGRs derive from fitted technology diffusion curves applied to defense appropriations trajectories. Industry-specific forecast inputs incorporate hypersonic interceptor program acceleration rates and ITAR qualification pipeline throughput.
Revisions become necessary when semiconductor export control designations expand, European sovereign seeker initiatives achieve production maturity, or critical infrared material supply disruptions materialize. Forecasts reflect documented assumptions about defense budget continuity and prime contractor consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Next-Generation Assault Rifles Market