
 Small Arms Market | 2026-2036
Small Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Small Arms Market Intelligence
Polymer composites are decoupling small arms from traditional steel-and-wood construction, cutting unit weight by a third while preserving barrel integrity. SIG SAUER, Inc. leverages this shift through its P320 modular handgun platform, which dominates US military and law enforcement contracts. Sturm, Ruger & Co., Inc. anchors the civilian market with vertically integrated polymer-frame production in Arizona and North Carolina. Glock Gesellschaft m.b.H. sustains its position through Austrian-engineered injection-molding tolerances that competitors struggle to replicate at scale.
Small arms denote portable, individual-operated weapons firing single-projectile or shot ammunition, typically chambered in calibers from .22 Long Rifle to 7.62x51mm NATO, with effective ranges under 800 meters and operating through controlled gas, recoil, or manual cycling systems. These weapons serve military infantry, law enforcement engagement, civilian hunting, and personal protection applications where maneuverability and rapid deployment outweigh crew-served firepower. Pistols command the largest revenue pool among product types due to concealed-carry permit expansion across US states and European personal defense licensing reforms. Semi-automatic technology leads unit volume while bolt-action rifles retain premium pricing in precision hunting and tactical segments where accuracy tolerances justify higher manufacturing costs.
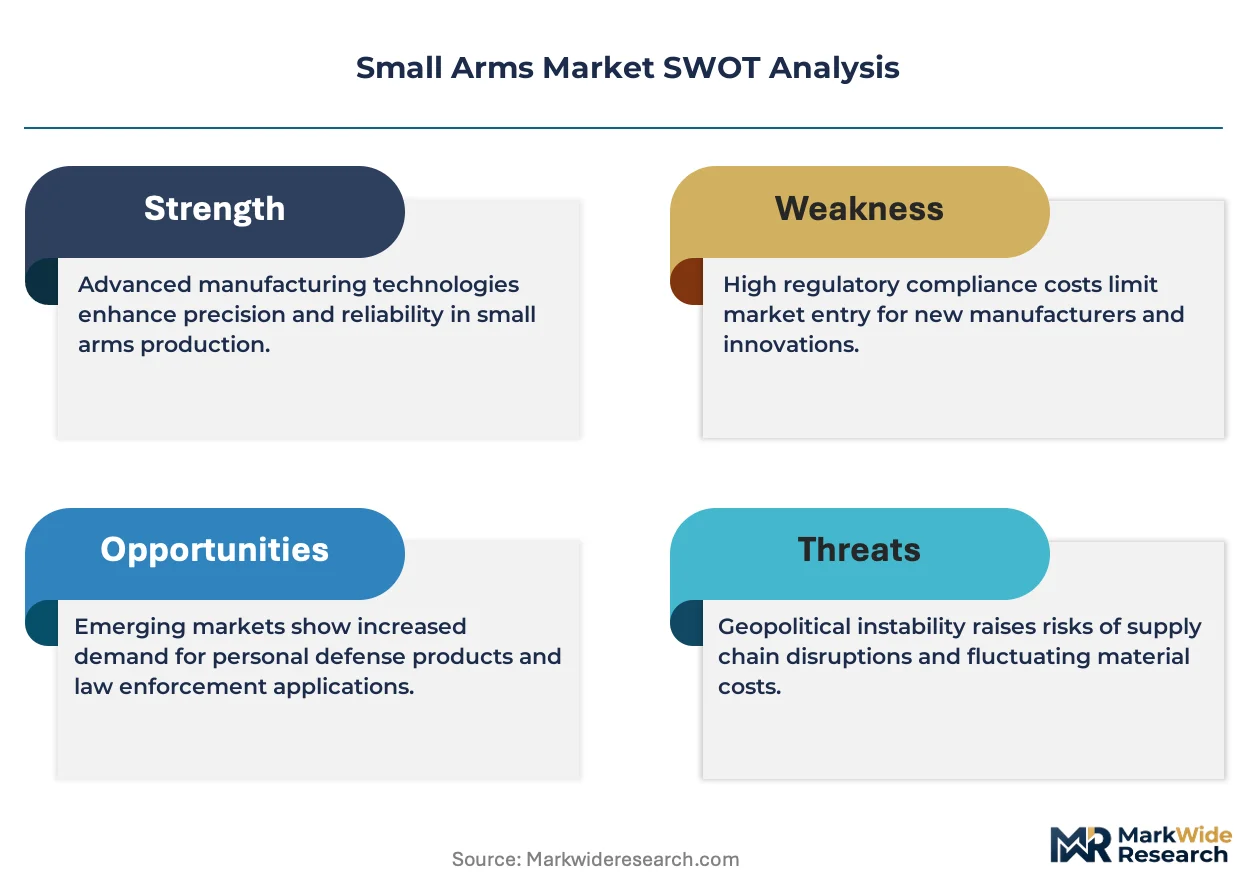
The US Bureau of Alcohol, Tobacco, Firearms and Explosives regulates civilian commerce through National Firearms Act serialization and background check mandates, while the EU Firearms Directive imposes category-based licensing across member states, restricting modern sporting rifle configurations in Germany and France. These frameworks fragment product portfolios, forcing manufacturers to maintain separate SKU lineups for compliant and restricted markets. Stakeholders must monitor pending US state-level magazine capacity legislation and EU review cycles for potential reclassification of semi-automatic platforms, as these decisions will determine factory allocation between civilian and institutional production lanes.
Market Dynamics
Modular weapon architecture is compressing product lifecycles as military procurement programs prioritize reconfigurable platforms over fixed-form systems, forcing manufacturers to retool for barrel-swappable, caliber-convertible designs.
Growth Catalysts
- Concealed-carry permit expansion:State-level licensing reforms across the United States are broadening the civilian buyer base for compact handguns. Law enforcement agencies are simultaneously refreshing sidearm inventories.
- REACH-compliant polymer formulations:Advanced composite materials meeting EU chemical safety standards are enabling lighter frame designs without sacrificing structural integrity under sustained fire.
- Gas-piston operating systems:Military end-users are specifying cleaner-running alternatives to direct-impingement mechanisms, reducing field maintenance burdens in adverse environments.
Market Restraints
- Nickel and chromium supply volatility:Barrel steel alloys depend on concentrated mining outputs from Russia and South Africa, exposing production costs to geopolitical disruption.
- EU Firearms Directive category restrictions:Semi-automatic rifle configurations face reclassification risks in Germany and France, fragmenting addressable civilian demand.
- Manual cycling persistence:Bolt-action mechanisms retain dominance in precision hunting segments, limiting addressable market for semi-automatic platform investments.
Strategic Opportunities
- Personal defense licensing liberalization:Czech Republic and Estonia are expanding civilian carry permissions, opening previously restricted Central European demand pools.
- Optics-integrated slide systems:Convergence of miniature red-dot sight technology with pistol slide machining is creating premium product tiers with expanded margins.
- Direct-to-consumer ammunition subscription:E-commerce fulfillment models are bypassing traditional retail distribution in states with permissive shipping regulations.
Industry Challenges
- Master machinist scarcity:Precision barrel rifling and slide-to-frame fitting require craft skills that vocational pipelines are failing to replenish.
- NFA serialization compliance timelines:US Bureau of Alcohol, Tobacco, Firearms and Explosives processing backlogs are extending inventory-to-market lead times for regulated items.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Arms Market |
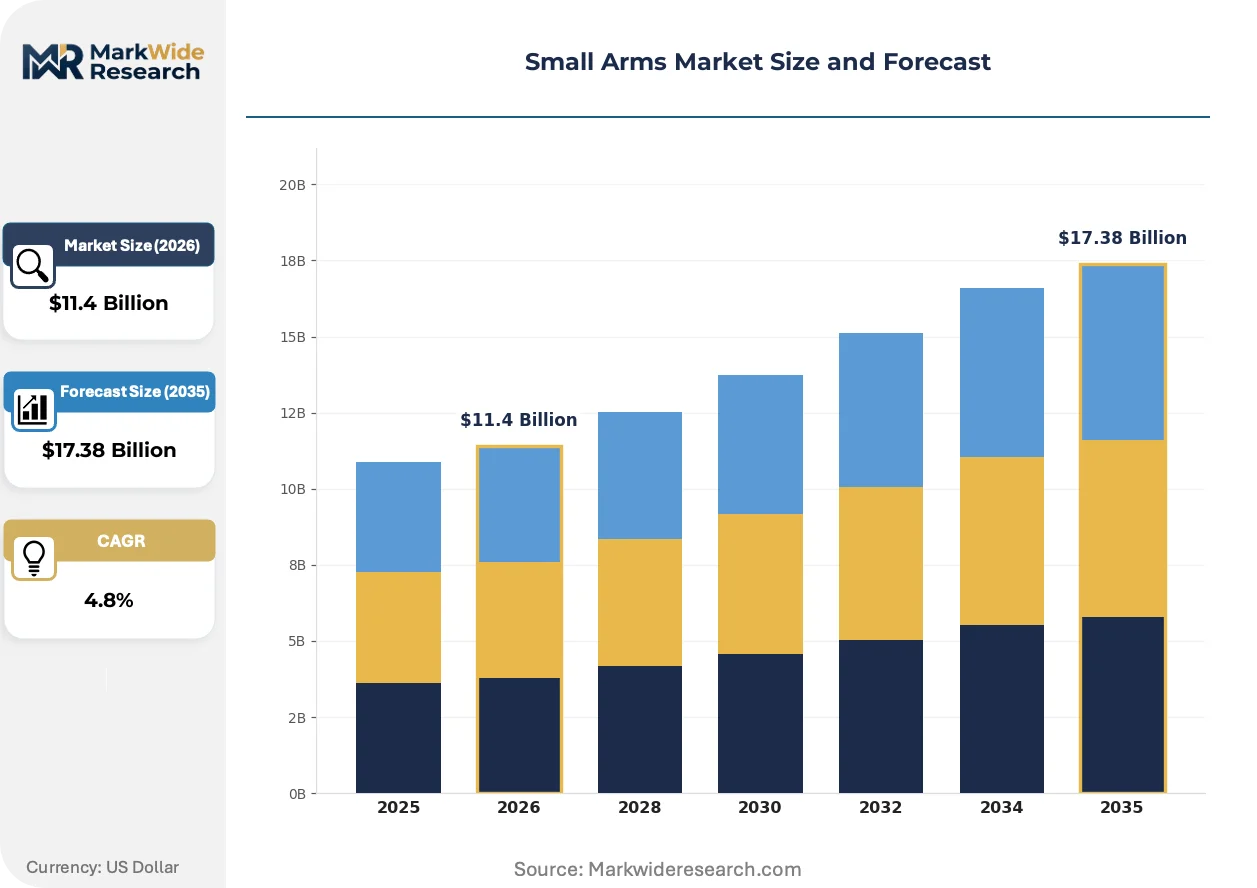
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pistols, Rifles, Submachine Guns, Shotguns, Revolvers, Carbines Technology: Semi-Automatic, Bolt-Action, Lever-Action, Full-Automatic, Break-Action, Double Barrel Application: Military, Law Enforcement, Personal Defense, Sports Shooting, Hunting, Security Services End User: Armed Forces, Police Agencies, Private Security Firms, Sports Shooters, Civilians |
| Companies Covered | Savage Arms, Henry Repeating Arms, Sturm, Ruger & Co., Inc., Glock Gesellschaft m.b.H., Mossberg, SIG SAUER, Inc., Palmetto State Armory, Anderson Manufacturing, Smith & Wesson Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Arms Market Strategic Shifts & Innovations
Active-shooter response doctrine is reshaping law enforcement equipment specifications, driving convergence between military and police procurement standards that previously operated on separate technical tracks.
Polymer-ceramic hybrid frame construction is expanding into duty-grade handgun production as manufacturers seek weight reduction without sacrificing drop-test durability. State police departments in Texas and Florida are adopting these platforms for all-day carry comfort. The technology is expanding into previously steel-dominated compact pistol segments where concealed-carry comfort now outweighs traditional durability assumptions.
The EU Firearms Directive review cycle is forcing manufacturers to maintain parallel SKU lineups for compliant and restricted market configurations. German and French distributors are demanding pre-certified modular components that can be assembled to local specifications rather than importing finished firearms. This regulatory fragmentation is compressing economies of scale for standardized production runs.
Law enforcement procurement consolidation is concentrating purchasing authority at state and federal levels, displacing the historical municipal autonomy that sustained diverse regional supplier relationships. The US Department of Defense's Modular Handgun System contract structure is now influencing state police bid specifications, favoring vendors with established institutional track records over emerging competitors. This buyer concentration is most visible in southeastern states where multi-agency purchasing cooperatives are aggregating demand.
Small Arms Market Segmentation
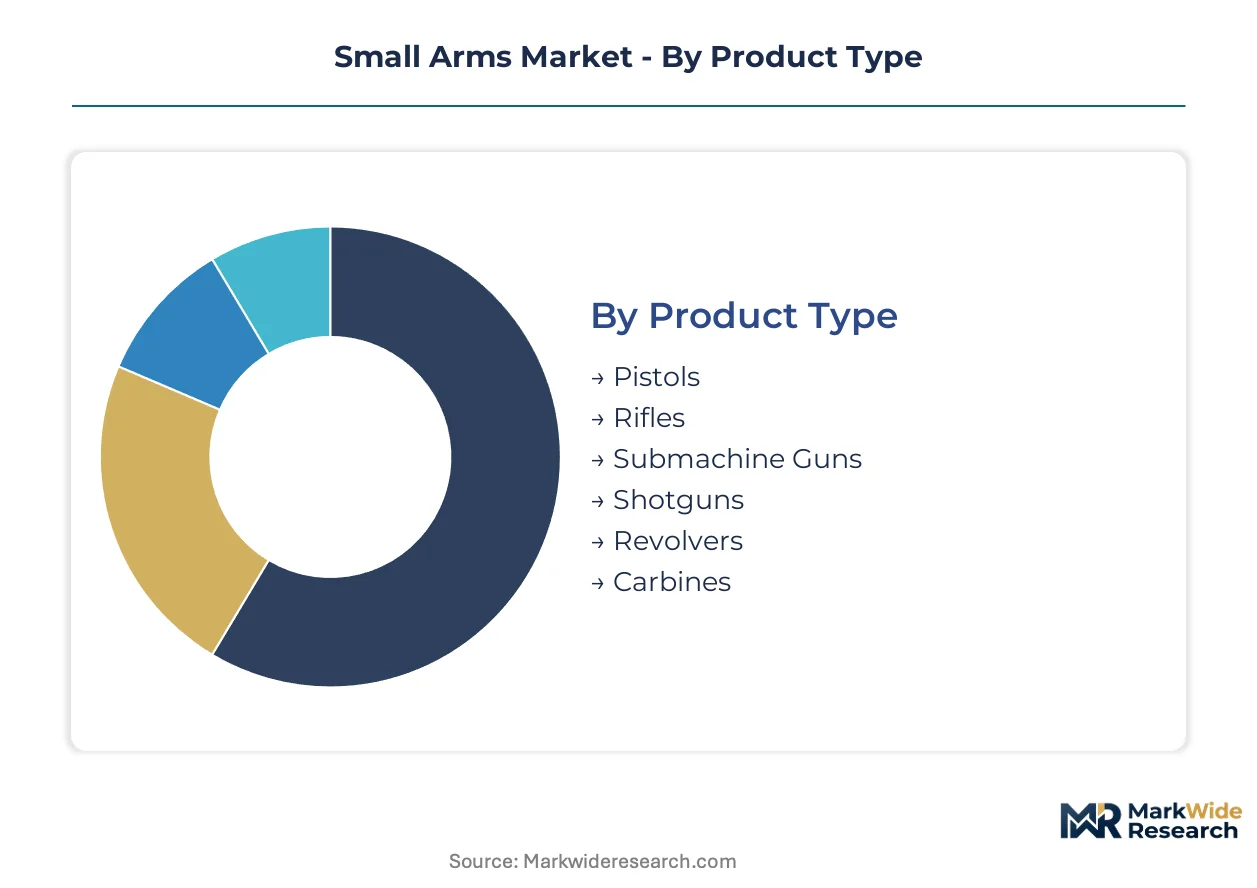
Small arms manufacturers navigate fragmented regulatory requirements across every product dimension. Certification burdens differ sharply between civilian sporting goods and military-grade platforms, forcing parallel production lanes and SKU proliferation.
Product Type:
Pistols and rifles carry distinct approval pathways under the US National Firearms Act serialization mandates, while submachine guns face EU Firearms Directive category restrictions that block civilian channels entirely.
- Pistols:Polymer-frame semi-automatic designs chambered in 9mm Parabellum and .45 ACP dominate institutional procurement. Demand concentrates in the United States civilian market where concealed-carry permit expansion drives compact and subcompact configurations.
- Rifles:Modular platforms with barrel-swappable, caliber-convertible architecture are displacing fixed-form systems in NATO military programs. Modern sporting rifle variants face state-level assault weapons bans that reshape product configurations for compliant markets.
- Submachine Guns:Select-fire compact weapons chambered in pistol calibers serve special operations and close-quarters combat roles. Restricted to military and law enforcement end-users under most national firearms frameworks.
- Shotguns:Pump-action and semi-automatic 12-gauge platforms retain dual-use flexibility across hunting and tactical applications.
- Revolvers:Double-action wheel guns persist in backup-duty roles and jurisdictions with restrictive semi-automatic regulations.
- Carbines:Short-barreled rifle variants bridge pistol maneuverability with rifle terminal ballistics, popular in personal defense and law enforcement patrol configurations.
Pistols sit at the top of the volume ranking, with carbines climbing the fastest as law enforcement agencies refresh patrol rifle inventories.
Technology:
Cost tiers separate precision-manufactured gas-piston systems from stamped-receiver alternatives, with bolt-action mechanisms commanding premium pricing in hunting segments where accuracy tolerances justify higher manufacturing investment.
- Semi-Automatic:Recoil-operated and gas-operated self-loading mechanisms lead unit volume across military, law enforcement, and civilian markets. Gas-piston variants are gaining preference over direct-impingement systems for reduced field maintenance burdens.
- Bolt-Action:Manually cycled rotating-bolt designs retain dominance in precision hunting and tactical sniper applications where single-shot accuracy outweighs rate-of-fire considerations. Premium barrel steel and hand-lapped rifling sustain elevated price points.
- Lever-Action:Tubular-magazine repeating rifles persist in North American hunting traditions and Cowboy Action Shooting competition circuits.
- Full-Automatic:Continuous-fire capability restricted to military and select law enforcement procurement under the US National Firearms Act and comparable frameworks.
- Break-Action:Hinged-frame single and double-barrel designs dominate shotgun segments for simplicity and reliability in adverse field conditions.
- Double Barrel:Side-by-side and over-under configurations serve sporting clays and upland bird hunting where aesthetic craftsmanship supports pricing premiums.
Semi-automatic technology captures the largest production volume, while gas-piston operating systems are expanding most quickly as military specifications prioritize reliability.
Application:
Customer type determines margin structure, with military procurement favoring lowest-qualified-bid pricing and personal defense segments supporting brand premiums through retail channels.
- Military:Infantry small arms procurement emphasizes modularity, interoperability, and supply chain security across NATO standardization agreements. Programs specify reconfigurable platforms compatible with optics, suppressors, and under-barrel accessories.
- Law Enforcement:Agency-level purchasing consolidation is concentrating authority at state and federal levels, displacing historical municipal autonomy. Active-shooter response doctrine drives convergence with military equipment specifications.
- Personal Defense:Concealed-carry licensing reforms across US states and European personal defense permitting expansions broaden the addressable buyer base for compact handguns.
- Sports Shooting:International Practical Shooting Confederation and Olympic discipline requirements sustain demand for precision-engineered competition platforms.
- Hunting:Bolt-action rifles and break-action shotguns retain preference where traditional ballistics and field reliability outweigh tactical features.
- Security Services:Private armed response contractors operate under less stringent equipment standards than sworn law enforcement, creating intermediate product tiers.
Law enforcement application sits at the top of the volume ranking, with personal defense climbing the fastest as licensing liberalization opens previously restricted demand pools.
End User:
Supply concentration varies by institutional scale, with armed forces procurement aggregating through centralized defense ministries while civilian sales fragment across thousands of federally licensed dealers.
- Armed Forces:National defense ministries specify modular handgun and rifle platforms through multi-year indefinite-delivery contracts. The US Department of Defense's Modular Handgun System structure influences allied procurement standards.
- Police Agencies:State and municipal departments refresh sidearm and patrol rifle inventories on accelerated cycles as duty-use durability standards tighten.
- Private Security Firms:Armed transport and facility protection contractors operate under commercial insurance and state licensing requirements distinct from sworn officer standards.
- Sports Shooters:Competitive and recreational users drive demand for precision-manufactured platforms with aftermarket customization compatibility.
- Civilians:Personal protection and hunting purchasers navigate state-level magazine capacity restrictions and assault weapons bans that fragment product availability.
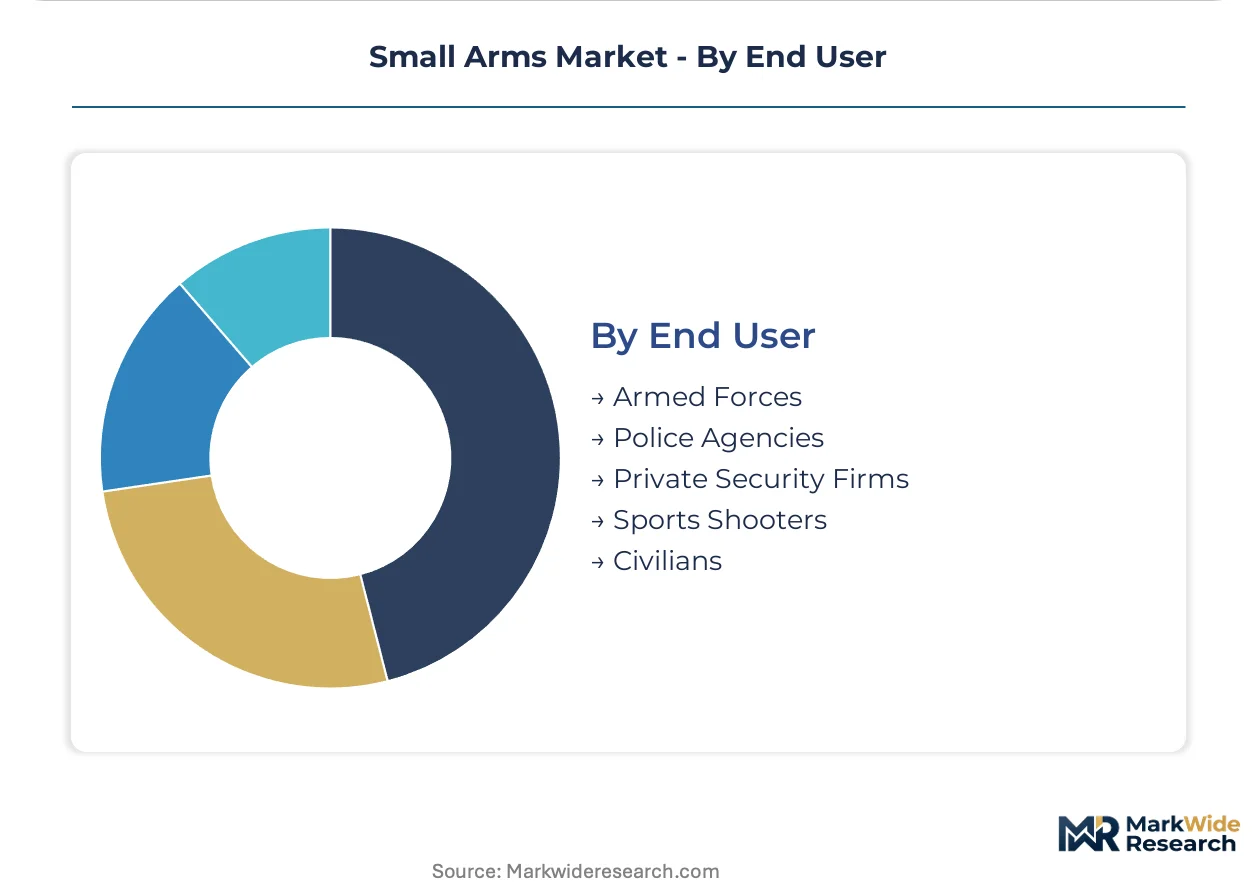
Armed Forces sit at the top of the volume ranking, with civilians climbing the fastest as concealed-carry permit expansion accelerates compact handgun demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Connecticut River Valley and surrounding New England manufacturing corridor retains historical concentration in precision machining for defense applications. Regional demand patterns diverge sharply between institutional procurement programs and civilian licensing frameworks. Regulatory fragmentation across national boundaries forces manufacturers to maintain parallel certification pathways.
United States
Concealed-carry permit expansion across southeastern and midwestern states drives compact handgun demand. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces National Firearms Act serialization mandates that extend inventory-to-market timelines. Arizona and North Carolina host vertically integrated polymer-frame production facilities serving both military and civilian channels.
Germany
EU Firearms Directive category restrictions compress civilian addressable demand for semi-automatic rifle platforms. The Federal Ministry of the Interior reviews semi-automatic reclassification risks that could shift factory allocation toward institutional production. Sauerland and Bavaria maintain precision barrel-forging clusters supplying NATO standardization agreements.
France
Personal defense licensing reforms under the 2016 Internal Security Code expanded civilian carry permissions. ANSM and interior ministry oversight requires pre-certified modular components rather than finished firearm imports. The Saint-Étienne historical manufacturing basin now specializes in optics-integrated slide machining for duty-grade platforms.
Czech Republic
Firearms Act amendments liberalized concealed-carry permitting beyond traditional sporting purposes. National security authority certification aligns with EU directive harmonization while preserving domestic manufacturer competitiveness. The Uherský Brod industrial cluster anchors Central European supply for modular rifle systems.
Italy
Beretta and legacy fabricators concentrate in the Val Trompia valley north of Brescia. Sporting and hunting traditions sustain break-action shotgun demand against semi-automatic encroachment. Regional guardia di finanza procurement specifications influence neighboring Mediterranean law enforcement standards.
Small Arms Market Key Industry Players
Global majors compete with regional champions across institutional contracting channels and civilian retail distribution. The vendor base separates into scale-driven defense contractors, polymer-specialist volume manufacturers, and precision-forging heritage houses. Three archetypes dominate: modular-platform integrators, vertically integrated polymer-frame producers, and barrel-forging specialists. Competitive moves concentrate on multi-year indefinite-delivery contract capture and state-level law enforcement cooperative purchasing aggregation.
Within the heritage-forging tier, Savage Arms and Henry Repeating Arms exemplify North American manufacturers leveraging traditional machining competencies against polymer-frame disruption. Sturm, Ruger & Co., Inc. occupies a position bridging vertical integration depth with civilian market breadth. Glock Gesellschaft m.b.H. and SIG SAUER, Inc. sit within the modular-platform archetype, with the latter representing defense-contractor scale and the former embodying injection-molding precision at volume.
| Leading Market Players |
|---|
| Savage Arms |
| Henry Repeating Arms |
| Sturm, Ruger & Co., Inc. |
| Glock Gesellschaft m.b.H. |
| Mossberg |
| SIG SAUER, Inc. |
| Palmetto State Armory |
| Anderson Manufacturing |
| Smith & Wesson Brands, Inc. |
| Others |
Cost & Logistics Intelligence
Captive polymer-frame production in Arizona and North Carolina anchors both supply security and pricing power for manufacturers serving the US civilian market. This backward integration shields against raw material volatility while enabling margin capture across concealed-carry and law enforcement segments.
Pricing Analysis
Input-cost pass-through from nickel and chromium alloy volatility runs through barrel steel pricing tiers. Three-tier pricing structure across premium match-grade, duty-certified, and economy training levels separates manufacturers by certification grade and accuracy tolerance. Pricing pressure stems from REACH-compliant polymer formulation costs as EU chemical safety standards tighten. Military procurement buyers exhibit lowest price sensitivity due to multi-year contract structures, while private security contractors face highest sensitivity due to commercial insurance requirements.
Supply Chain Analysis
Master machinist scarcity in the Connecticut River Valley and Sauerland precision-forging clusters constrains barrel rifling capacity expansion. Manufacturing concentrates in the United States, Germany, and the Czech Republic, with raw material dependencies on Russian and South African chromium outputs and Italian polymer resin formulations. Single-source vulnerability in nickel alloy supply exposes production costs to geopolitical disruption. Distribution runs through federally licensed dealers in civilian channels and defense ministry procurement offices in institutional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between permissive US state concealed-carry regimes and restrictive EU Firearms Directive jurisdictions creates manufacturing cost differentials favoring North American production allocation.
For Market Incumbents: Anticipate EU Firearms Directive reclassification risks by accelerating modular component certification for German and French assembly requirements. Backward integration into polymer resin formulation secures margin against REACH compliance cost escalation. Lock in multi-year law enforcement cooperative purchasing agreements before state-level consolidation displaces municipal autonomy.
For New Entrants and Emerging Players: Begin with Czech Republic and Estonian personal defense licensing liberalization as the most penetrable demand pools outside saturated US channels. Target optics-integrated slide machining as a premium tier with expanded margins and limited incumbent specialization. Pursue direct-to-consumer ammunition subscription models in states with permissive shipping regulations.
For Investors and Strategic Acquirers: Roll-up economics work for barrel-forging specialists because master machinist scarcity concentrates craft skills in legacy manufacturing clusters. Five-to-ten year viability hinges on NATO standardization agreement alignment. Monitor US state-level magazine capacity legislation as the inflection signal determining factory allocation between civilian and institutional production lanes.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Certification | EU Firearms Directive compliance unlocks German and French institutional procurement channels. |
| Polymer Resin Backward Integration | Arizona and North Carolina captive production shields REACH formulation cost volatility. |
| Optics-Integrated Slide Machining | Saint-Étienne precision clusters enable premium tier differentiation in law enforcement segments. |
| Multi-Agency Purchasing Cooperative | Southeastern state aggregation concentrates demand for vendors with established institutional track records. |
| Direct-to-Consumer Ammition Fulfillment | E-commerce bypasses traditional retail distribution in states with permissive ATF shipping oversight. |
Research Approach
Multiple input streams — defense procurement officers, polymer manufacturing engineers, federally licensed firearms dealers, and ATF compliance specialists — were reconciled against customs records, NATO standardization agreement filings, and state-level concealed-carry permit data. Bottom-up unit volume estimates from manufacturer production disclosures were triangulated with top-down addressable demand calculations across military, law enforcement, and civilian segments.
Data-stream reconciliation across product type, technology mechanism, application purpose, and end-user institutional scale generated volume and value outputs across the projection horizon. CAGRs were derived from regression analysis of historical procurement cycles and regulatory review timelines. Industry-specific forecast inputs incorporated polymer composite adoption curves and gas-piston operating system specification shifts in NATO programs.
Several conditions sit outside the modeled scope, including pending US state-level assault weapons ban litigation outcomes and EU Firearms Directive semi-automatic reclassification proceedings. Forecasts assume stable chromium and nickel alloy supply from existing mining jurisdictions. Material deviation in NATO procurement budget allocations or REACH polymer formulation standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Ammunition Handling Systems Market