
 Recoilless Rifle Market | 2026-2036
Recoilless Rifle Market Size, Share, and Industry Trends Forecast 2026-2036
Recoilless Rifle Market Insights
Lightweight aluminum construction is bifurcating the recoilless rifle landscape into expeditionary and mechanized tiers. General Dynamics Corporation leverages its vertical integration in precision forging to dominate the vehicle-mounted segment. BAE Systems sustains its position through specialized ceramic composite R&D for infantry support platforms. Saab AB differentiates via geographic concentration in Nordic and Baltic defense contracts.
A recoilless rifle is a smoothbore or rifled shoulder-fired or crew-served weapon that vents propellant gases rearward to neutralize recoil, enabling firing from lightweight platforms without heavy mounting systems; typical systems achieve muzzle velocities of 250–400 m/s with projectile masses of 2–9 kg for anti-armor and bunker-defeat missions. Man-portable configurations anchor procurement volumes among special operations units seeking dismounted mobility, while vehicle-mounted systems capture margin pools through integrated fire-control electronics. Carbon fiber technology is accelerating as manufacturers reduce tube weight below 10 kg for single-soldier transport.
The US Department of Defense and NATO standardization agencies shape demand through STANAG interoperability requirements and lightweight munitions directives that restrict non-certified suppliers from alliance tenders. India's Defence Research and Development Organisation and the country's national ordnance quality assurance regulator enforce indigenous content thresholds that complicate foreign OEM market access. Stakeholders must monitor how ITAR relaxation debates and allied industrial base expansion programs reshape supplier eligibility across procurement blocs.
Market Dynamics
Lightweight munitions directives from the US Department of Defense are compressing development cycles and forcing manufacturers to prioritize single-soldier transportability over crew-served configurations.
Growth Catalysts
- STANAG interoperability requirements:NATO standardization agencies mandate certified suppliers for alliance tenders, creating procurement lock-in for qualified manufacturers across Poland and the Baltic states.
- Carbon fiber tube construction:Manufacturers are reducing weapon system weight below 10 kg, enabling dismounted mobility for special operations units previously restricted to vehicle-mounted platforms.
- Frontier defense modernization:Infantry support units in Estonia, Latvia, and Lithuania are expanding man-portable system procurement amid territorial security priorities.
Market Restraints
- ITAR export controls:US State Department restrictions on defense articles create licensing friction for cross-border component transfers and foreign military sales.
- Indigenous content thresholds:India's Defence Research and Development Organisation enforces local sourcing minimums that complicate foreign OEM market access.
- Tungsten alloy supply concentration:Precision forging feedstock relies on limited supplier bases in China and Russia, exposing production to geopolitical disruption.
Strategic Opportunities
- Ukraine reconstruction demand:Post-conflict security assistance programs will require substantial replenishment of infantry anti-armor inventories.
- Integrated fire-control electronics:Convergence of ballistic computers with lightweight recoilless platforms enables precision targeting previously limited to guided missiles.
- Allied industrial base expansion:NATO's European Deterrence Initiative is creating new supplier eligibility pathways for non-US manufacturers.
Industry Challenges
- Ballistician talent scarcity:Specialized expertise in low-pressure propellant chemistry and vented breech mechanics is concentrated among retiring defense-sector veterans.
- Qualification timeline compression:NATO's updated lightweight munitions directive accelerates certification cycles without reducing safety verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recoilless Rifle Market |
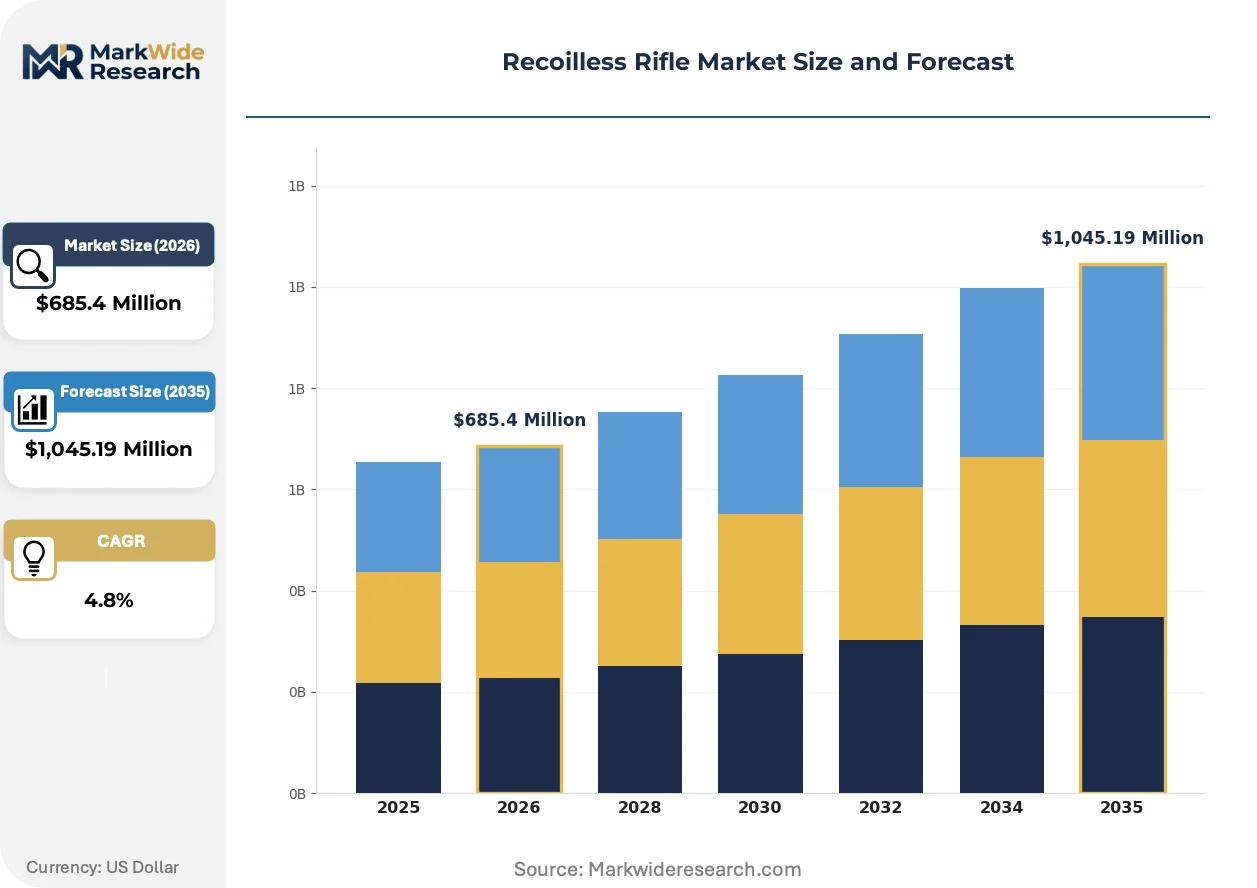
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Man-Portable, Vehicle-Mounted, Towed, Airborne, Naval Technology: Ceramic Composite, Steel Alloy, Carbon Fiber, Lightweight Aluminum, High-Tensile Steel Application: Infantry Support, Anti-Tank Operations, Fortification Destruction, Amphibious Assaults, Reconnaissance Missions End User: Defense Forces, Paramilitary Organizations, Special Operations Units, Military Contractors, Peacekeeping Troops |
| Companies Covered | General Dynamics Corporation, BAE Systems, Raytheon Technologies Corporation, Leonardo S.p.A., Thales Group, Lockheed Martin Corporation, Northrop Grumman Corporation, Saab AB, China North Industries Group Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recoilless Rifle Market Trends and Innovations
Material science advances and regulatory pressure are reshaping competitive positioning across expeditionary and mechanized system tiers. Manufacturers must now balance single-soldier portability against integrated electronics complexity.
Ceramic composite liners are replacing traditional steel alloy tubes in infantry support variants. Polish and Baltic procurement agencies are specifying these configurations for dismounted border defense units. This substitution is bifurcating the market into lightweight expeditionary tiers and heavier vehicle-mounted platforms with divergent supply chains.
REACH chemical safety regulations in Europe are restricting traditional propellant formulations containing specific nitrocellulose stabilizers. Manufacturers serving NATO member states are reformulating charge compositions to maintain export eligibility. Infantry support platforms face the tightest compliance timelines due to higher per-unit propellant volumes.
Buyers are unbundling after-sales service contracts from initial system procurement. Nordic defense ministries now separately tender for depot-level maintenance, creating new revenue pools for specialized technical service providers. This restructuring is most visible in Sweden and Finland, where Saab's established presence faces independent maintenance contractor competition.
Recoilless Rifle Market Segmentation
Recoilless rifle procurement channels diverge sharply between expeditionary and mechanized force structures. Defense ministries unbundle platform specifications from integrated fire-control electronics, creating distinct commercial pathways for tube manufacturers and systems integrators.
Product Type:
Man-portable systems flow through special operations procurement channels, while vehicle-mounted variants integrate into armored platform prime contracts.
- Man-Portable:Single-soldier transportable systems under 10 kg with carbon fiber tube construction. Polish and Baltic frontier defense units are expanding procurement amid dismounted border patrol requirements. REACH chemical compliance pressures are accelerating propellant reformulation timelines for these high-volume platforms.
- Vehicle-Mounted:Crew-served configurations integrated with fire-control electronics on light tactical vehicles. NATO standardization agencies mandate STANAG interoperability certification, restricting tender eligibility to qualified suppliers with precision forging capabilities.
- Towed:Expeditionary artillery support platforms requiring rapid emplacement. Demand concentrates in rapid reaction force structures.
- Airborne:Helicopter-portable systems for air assault units. Weight reduction drives carbon fiber adoption.
- Naval:Shipboard close-in defense and amphibious fire support. Limited procurement volumes reflect specialized mission profiles.
By volume, Man-Portable leads. By growth pace, Vehicle-Mounted is climbing the fastest.
Technology:
Material selection stratifies across cost tiers, with ceramic composite and carbon fiber commanding premium positioning against steel alloy baseline configurations.
- Ceramic Composite:BAE Systems specializes in ceramic liner R&D for infantry support platforms. Nordic defense ministries specify these configurations for reduced thermal signature and extended barrel life.
- Steel Alloy:Traditional construction dominates legacy system sustainment and cost-constrained procurement.
- Carbon Fiber:Tube weight reduction below 10 kg enables single-soldier transportability previously restricted to heavier crew-served weapons. US Department of Defense lightweight munitions directives are compressing development cycles for these platforms.
- Lightweight Aluminum:General Dynamics leverages vertical integration in precision forging for expeditionary vehicle-mounted systems.
- High-Tensile Steel:Mechanized tier platforms prioritize durability over weight reduction for sustained fire missions.
By installed base, Steel Alloy dominates. By substitution momentum, Carbon Fiber is gaining share fastest.
Application:
Mission type determines electronics integration depth and procurement authority level within defense ministry hierarchies.
- Infantry Support:General-purpose direct fire against fortified positions and light armor. Estonia, Latvia, and Lithuania are expanding procurement amid territorial security priorities.
- Anti-Tank Operations:Dedicated armor defeat with shaped charge or kinetic penetrator warheads. STANAG interoperability requirements create procurement lock-in for certified suppliers.
- Fortification Destruction:Bunker-defeat missions using high-explosive or thermobaric munitions. Special operations units drive demand for man-portable configurations.
- Amphibious Assaults:Naval infantry and marine expeditionary force requirements. Limited procurement volumes reflect specialized service branch structures.
- Reconnaissance Missions:Dismounted scout and special forces employment. Weight minimization overrides firepower optimization.
By procurement volume, Infantry Support leads. By capability investment, Anti-Tank Operations shows steepest expansion trajectory.
End User:
Customer type shapes contract structure, with defense forces favoring multi-year framework agreements and special operations units requiring rapid acquisition pathways.
- Defense Forces:Conventional army and marine corps procurement through national armament directorates. India's Defence Research and Development Organisation enforces indigenous content thresholds complicating foreign OEM access.
- Paramilitary Organizations:Border guard and coast guard units with limited armor defeat requirements. Procurement follows interior ministry rather than defense ministry channels.
- Special Operations Units:Discretionary acquisition authority for man-portable systems. US SOCOM and NATO special forces components prioritize weight reduction over standardization.
- Military Contractors:Private security and training organization procurement. ITAR export controls create licensing friction for cross-border transfers.
- Peacekeeping Troops:UN and regional organization contingent equipment. Standardization pressures favor interoperable NATO-certified systems.
By contract value, Defense Forces lead. By specification intensity, Special Operations Units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision forging capacity clusters in the United States, Germany, and Sweden, with allied defense procurement creating secondary demand nodes in Poland and the Baltic states. National armament directorates enforce divergent certification timelines that fragment supplier access across procurement blocs.
United States
The Department of Defense's lightweight munitions directive compresses development cycles for single-soldier transportable systems. ITAR export controls administered by the State Department create licensing friction for cross-border component transfers. General Dynamics Corporation anchors precision forging capacity in St. Louis, Missouri, supplying vehicle-mounted configurations to NATO standardization programs.
Germany
Rheinmetall and Krauss-Maffei Wegmann drive demand for integrated fire-control electronics on mechanized platforms. Germany's national armament regulator enforces stringent STANAG interoperability certification timelines. The Bavarian industrial corridor around Munich hosts specialized ballistics R&D facilities serving NATO expeditionary requirements.
Poland
Frontier defense modernization programs expand procurement of man-portable systems for dismounted border patrol units. Poland's national ordnance quality assurance protocols align with NATO standardization agency requirements. The Łódź-Świętoszów defense manufacturing cluster concentrates tube fabrication capacity for Baltic state exports.
Sweden
Saab AB leverages geographic concentration in Nordic defense contracts for ceramic composite infantry support platforms. REACH chemical safety regulations from ECHA restrict traditional propellant formulations containing specific nitrocellulose stabilizers. The Linköping aerospace and defense cluster houses specialized vented breech mechanics expertise for low-pressure propellant systems.
India
The Defence Research and Development Organisation enforces indigenous content thresholds that complicate foreign OEM market access. India's national ordnance quality assurance regulator mandates local sourcing minimums for defense procurement. The Pune-Ordnance Factory Board industrial complex develops domestic recoilless rifle variants with limited foreign component integration.
Recoilless Rifle Market Competitive Landscape
Concentration sits with vertically integrated defense primes possessing precision forging capabilities and STANAG certification authority. The vendor base stratifies between expeditionary system specialists and mechanized platform integrators. Three archetypes dominate: carbon fiber tube fabricators serving special operations procurement, ceramic composite R&D houses supplying infantry support variants, and fire-control electronics integrators capturing vehicle-mounted margins. Competitive moves center on backward integration into tungsten alloy feedstock and strategic partnerships with Baltic state armament directorates.
Among US-based defense primes, General Dynamics Corporation and Raytheon Technologies Corporation exemplify the vertically integrated archetype with precision forging and systems integration capabilities. BAE Systems represents the ceramic composite specialization vector for infantry support platforms. Saab AB anchors the Nordic geographic concentration archetype, while China North Industries Group Corporation Limited occupies a position within the non-NATO supplier tier subject to divergent certification protocols.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems |
| Raytheon Technologies Corporation |
| Leonardo S.p.A. |
| Thales Group |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Saab AB |
| China North Industries Group Corporation Limited |
| Others |
Pricing and Supply Chain Analysis
Precision forging capacity utilization above 85 percent in Missouri and Bavaria creates dual price floors for STANAG-certified tube manufacturers while compressing margins for non-integrated assemblers sourcing from third-party forgers. This scale concentration simultaneously elevates entry barriers for emerging carbon fiber fabricators and reinforces incumbent pricing power across NATO procurement channels.
Pricing Analysis
STANAG interoperability requirements dictate the pricing tier structure across alliance tenders, separating STANAG-certified suppliers commanding premium positioning from uncertified competitors limited to national-only contracts. Price differentiation hinges on certification grade and after-sales service bundling, with Nordic defense ministries unbundling maintenance contracts to reduce upfront capital outlays. Cost compression in carbon fiber tube tiers is intensifying as REACH chemical compliance adds reformulation expense. Paramilitary organizations exhibit highest price sensitivity due to interior ministry budget constraints, while special operations units prioritize weight reduction over unit cost.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes from Chinese tungsten alloy suppliers are extending inbound logistics timelines for precision forging feedstock. Manufacturing concentrates in the United States, Germany, and Sweden, with secondary fabrication clusters in Poland drawing from Bavarian component flows. Raw material dependencies rest on tungsten alloys, nitrocellulose propellant precursors, and carbon fiber prepregs. Single-source vulnerability in Chinese tungsten concentrate exposes production to geopolitical disruption. Distribution runs through national armament directorates with multi-year framework agreements dominating downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recoilless rifle market rewards possession of scarce ballistician expertise in vented breech mechanics and low-pressure propellant chemistry, with retiring defense-sector veterans concentrating this capability among a shrinking qualified supplier base.
For Market Incumbents: Consolidate precision forging capacity in the Missouri industrial corridor to capture carbon fiber tube demand from US SOCOM and NATO special forces components. Deepen captive supply of tungsten alloy feedstock through partnerships with alternative concentrate sources outside China to mitigate single-source exposure. STANAG certification authority remains the priority defensive asset against emerging ceramic composite specialists. For New Entrants and Emerging Players: Anchor in Baltic state frontier defense modernization programs where Poland's Łódź-Świętoszów cluster creates regional supplier eligibility pathways outside established US-German-Swedish concentration. Target paramilitary border guard procurement channels that follow interior ministry rather than defense ministry tender protocols, reducing STANAG certification barriers. Pursue independent depot-level maintenance contracts in Sweden and Finland where Saab's established presence faces unbundling pressure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fire-control electronics integrators capturing vehicle-mounted platform margins through multi-year service contracts. Long-term viability over the coming decade favors acquisition targets possessing both STANAG certification authority and backward integration into precision forging. Monitor ITAR relaxation debates as the signal indicating expanded supplier eligibility for non-US manufacturers across NATO procurement blocs.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Certification Investment | Unlocks NATO alliance tender eligibility across Poland and Baltic defense modernization programs. |
| Carbon Fiber Tube Scale-Up | Enables single-soldier transportability compliance with US Department of Defense lightweight munitions directives. |
| Ceramic Composite R&D Partnership | Addresses Nordic defense ministry specifications for reduced thermal signature infantry support platforms. |
| Tungsten Alloy Supply Diversification | Mitigates geopolitical risk from Chinese and Russian concentrate concentration in precision forging feedstock. |
| After-Sales Service Unbundling | Captures recurring revenue pools as Nordic ministries separate maintenance from initial system procurement. |
Research Methodology
Cross-validation between primary interviews with defense procurement officers, ballistic R&D directors, and national armament regulator officials and secondary validation through NATO standardization agency documentation, US State Department ITAR filings, and ECHA REACH chemical safety registrations anchors the qualitative findings. Bottom-up segment sizing triangulates against top-down defense budget allocation analysis across member state armament directorates.
Sensitivity analysis around propellant reformulation cost curves and tungsten alloy price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material technology, mission application, and end-user procurement authority. CAGRs derive from installed base replacement cycles, frontier defense modernization program announcements, and special operations discretionary acquisition patterns. Ukraine reconstruction security assistance timelines and allied industrial base expansion program disbursements constitute industry-specific forecast inputs.
Material uncertainties — ITAR regulatory relaxation outcomes, REACH chemical restriction scope expansion, and tungsten supply chain disruption events — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding NATO standardization continuity and US lightweight munitions directive implementation pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Precision Guided Munition Market