
 Manned Anti-Tank Guided Missile System Market | 2026-2036
Manned Anti-Tank Guided Missile System Market Size, Share, and Industry Trends Forecast 2026-2036
Manned Anti-Tank Guided Missile System Market Analysis
Platform upgrade cycles is rewriting margin distribution across the manned anti-tank guided missile ecosystem. Raytheon Company leverages its Javelin production infrastructure to sustain recurring refurbishment contracts with US Army arsenals. Rafael Advanced Defense Systems anchors Israeli supply chains while extending Spike-family integration across European NATO inventories. MBDA competes through dual-mode seeker development that occupies the Franco-German-Italian procurement corridor.
A manned anti-tank guided missile system comprises a tube-launched, optically tracked, wire- or wireless-guided munition with tandem shaped-charge or top-attack warheads designed to defeat reactive armor at ranges from 2.5 to 8 kilometers. These systems serve as dismounted infantry and vehicle-mounted precision-strike weapons against hardened ground targets. Fire-and-Forget platforms lead procurement volumes due to reduced operator exposure, while Laser-Guided variants retain niche demand for rules-of-engagement flexibility in combined-arms environments. Ground Vehicles installation dominates platform integration as mechanized brigades prioritize turret-mounted launchers over dismounted configurations.
US Army acquisition directives under NGCV and FMS export frameworks shape product standards, while EDA cooperative procurement mechanisms harmonize cross-border NATO interoperability requirements. The EU Green Deal defense-industry nexus and emerging CSRD supply-chain disclosure rules will pressure prime contractors to document environmental footprints across rare-earth magnet and thermal-battery sourcing. Stakeholders must monitor how ITAR relaxation debates and European Strategic Autonomy funding reallocations reshape transatlantic component flows without assuming continuity in current licensing architectures.
Market Dynamics
Platform upgrade cycles are rewriting margin distribution across the manned anti-tank guided missile ecosystem, as defense ministries prioritize fire-and-forget architectures over legacy wire-guided systems.
Growth Catalysts
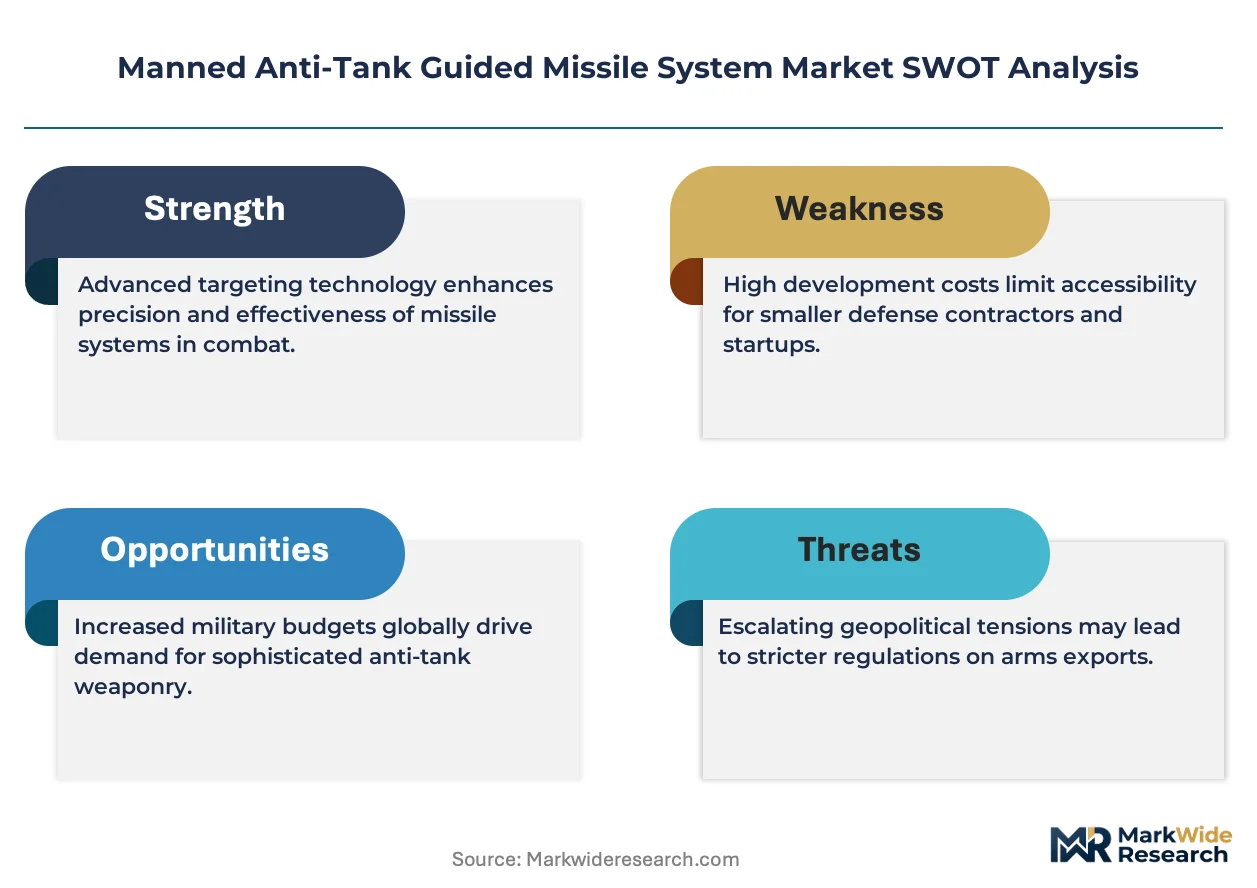
- NGCV Modernization Directives:The US Army's Next Generation Combat Vehicle framework mandates turret-integrated precision munitions, accelerating procurement timelines for mechanized brigades.
- Reactive Armor Proliferation:Tandem shaped-charge warhead development responds to explosive reactive armor fielding by near-peer adversaries, driving replacement demand across NATO inventories.
- Baltic Deterrence Posture:Poland, Estonia, and Latvia are expanding man-portable anti-tank allocations as frontline states, creating concentrated demand corridors for shoulder-fired systems.
Market Restraints
- Rare-Earth Magnet Supply Concentration:Guidance system actuators depend on neodymium-iron-boron magnets sourced predominantly from Chinese processing facilities, exposing prime contractors to export control volatility.
- ITAR Licensing Architecture:US International Traffic in Arms Regulations create transatlantic friction for component transfers, delaying European integration programs by 12-18 months on average.
- Thermal Battery Cost Structure:Lithium-thionyl chloride power cells for launch tube electronics represent 15-20% of unit production cost, with limited qualified suppliers maintaining pricing power.
Strategic Opportunities
- Spike-NLOS Integration:Rafael's non-line-of-sight variant offers networked multi-platform targeting, opening naval and rotary-wing applications beyond traditional ground force roles.
- EDA Cooperative Procurement:European Defence Agency pooled acquisition mechanisms reduce unit costs for smaller NATO members, creating volume aggregation opportunities for compliant vendors.
- Top-Attack Algorithm Convergence:Millimeter-wave radar and imaging infrared fusion enables autonomous target discrimination, reducing operator training burdens for conscript-heavy forces.
Industry Challenges
- Seeker Calibration Expertise Gap:Dual-mode electro-optical/infrared sensor alignment requires specialized technicians, with military depots competing against commercial semiconductor fabs for talent.
- CSRD Supply-Chain Disclosure:EU Corporate Sustainability Reporting Directive mandates documented environmental footprints across rare-earth and thermal-battery sourcing, forcing prime contractors to requalify sub-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manned Anti-Tank Guided Missile System Market |
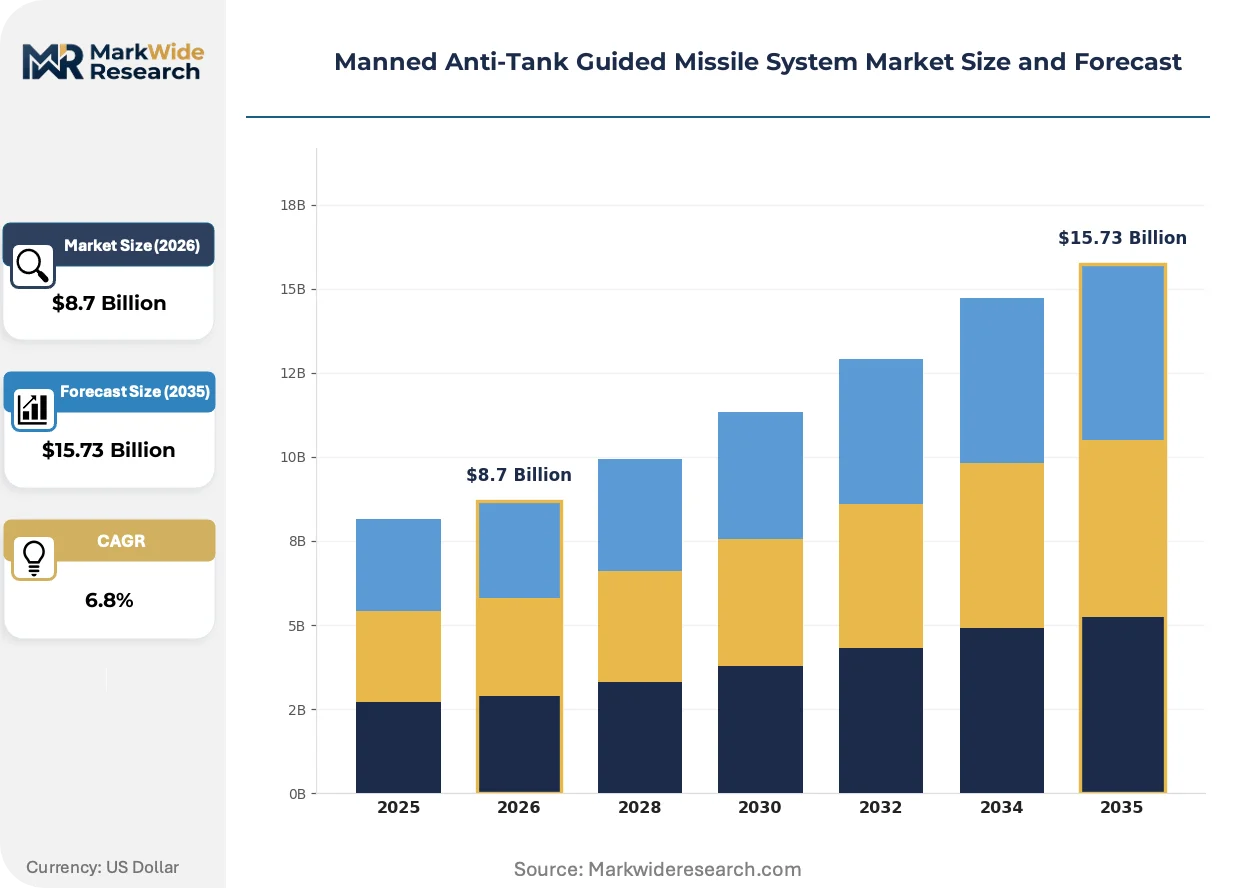
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Military, Defense, Law Enforcement, Surveillance Product Type: Fire-and-Forget, Semi-Active, Laser-Guided, Wire-Guided End User: Armed Forces, Special Operations, Private Contractors, Government Agencies Installation: Ground Vehicles, Naval Platforms, Aerial Systems, Mobile Launchers |
| Companies Covered | General Dynamics Corporation, BAE Systems, Lockheed Martin Corporation, Denel Dynamics, Elbit Systems Ltd, Raytheon Company, Rafael Advanced Defense Systems, KBP Instrument Design Bureau, MBDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manned Anti-Tank Guided Missile System Market Emerging Trajectories
Active seeker architectures are displacing command-to-line-of-sight guidance across procurement portfolios, compressing engagement timelines while expanding beyond-visual-range capabilities.
Imaging infrared focal plane arrays are digitizing target acquisition workflows for dismounted infantry. Polish and German mechanized units are fielding clip-on thermal modules at brigade scale. This digitization is compressing sensor-to-shooter chains from minutes to seconds.
EU Green Deal defense-industry nexus rules are mandating lifecycle carbon accounting for munitions production. MBDA and Rheinmetall are reengineering propellant formulations to reduce per-unit emissions. Franco-German-Italian procurement corridors are prioritizing compliant bidders in competitive evaluations.
Bundled logistics contracts are unbundling from platform sales as defense ministries seek performance-based availability guarantees. Baltic states are piloting contractor-operated depot maintenance for Spike inventories. Poland's Terespol depot cluster exemplifies this operational model shift.
Manned Anti-Tank Guided Missile System Market Segmentation
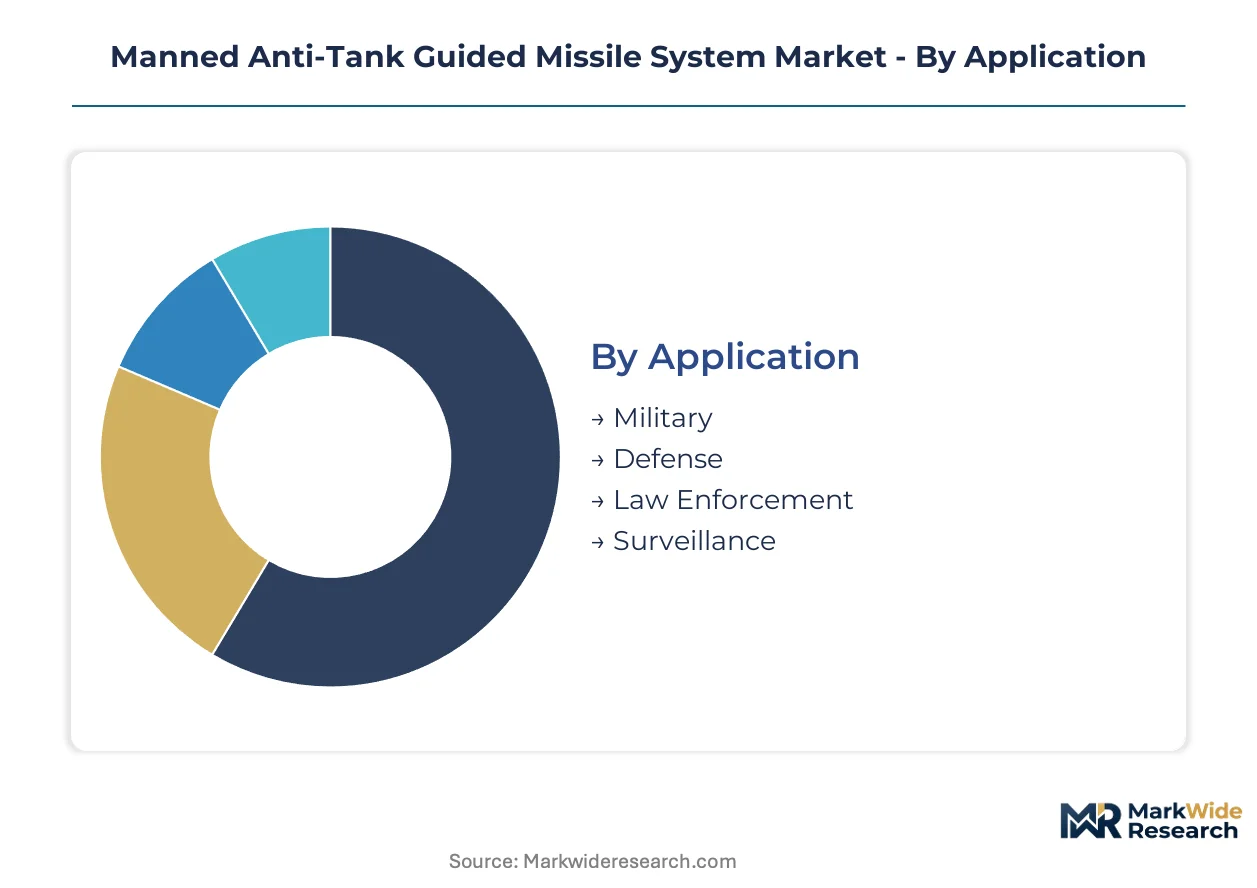
Segmentation in the manned anti-tank guided missile system market reveals how procurement priorities diverge across operational contexts. Defense ministries allocate budgets differently based on platform integration requirements, guidance architecture preferences, and end-user training profiles.
Application:
Mature operational domains dominate procurement volumes, while emerging use cases reshape capability specifications.
- Military:Mechanized brigades across NATO members drive procurement of turret-integrated systems with fire-and-forget architectures. Poland's Terespol depot cluster exemplifies concentrated demand for ground-force precision munitions under continental deterrence restructuring.
- Defense:National guard and territorial defense units prioritize man-portable configurations with reduced logistics footprints. Baltic states allocate shoulder-fired systems to conscript-heavy formations facing near-peer armor threats.
- Law Enforcement:Specialized counter-terror units employ reduced-range variants for urban engagement scenarios with strict rules-of-engagement protocols.
- Surveillance:Border security agencies integrate non-line-of-sight variants for standoff observation and interdiction across extended perimeters.
Military applications handle the majority of throughput; Surveillance is expanding most quickly on share as networked targeting architectures mature.
Product Type:
Cost tier stratification separates premium active-seeker systems from legacy command-guided alternatives.
- Fire-and-Forget:Imaging infrared focal plane arrays enable autonomous target acquisition without operator exposure during flight. US Army NGCV modernization directives accelerate turret-integrated procurement for mechanized brigades.
- Semi-Active:Operator-maintained laser designation balances cost constraints with precision requirements. European NATO inventories retain these systems for rules-of-engagement flexibility in combined-arms environments.
- Laser-Guided:Designator-dependent architectures occupy mid-tier procurement for forces with established forward-observer networks.
- Wire-Guided:Command-to-line-of-sight systems face replacement pressure as defense ministries prioritize reduced operator exposure.
Fire-and-Forget systems command the premium tier; Semi-Active variants are gaining share fastest as interoperability requirements intensify.
End User:
Customer type determines training investment levels and lifecycle support contract structures.
- Armed Forces:Conventional mechanized units require integrated logistics chains with depot-level maintenance capabilities. Polish and German brigade-scale fielding of clip-on thermal modules illustrates procurement concentration.
- Special Operations:Discreet transportability and reduced signature profiles drive demand for compact, multi-spectral capable variants.
- Private Contractors:Security firms operating in high-threat environments procure commercial-off-the-shelf configurations with limited technical support packages.
- Government Agencies:Border and critical infrastructure protection units prioritize extended-range standoff capabilities with networked targeting.
Armed Forces represent the dominant customer base; Special Operations are climbing the fastest as discretionary procurement expands.
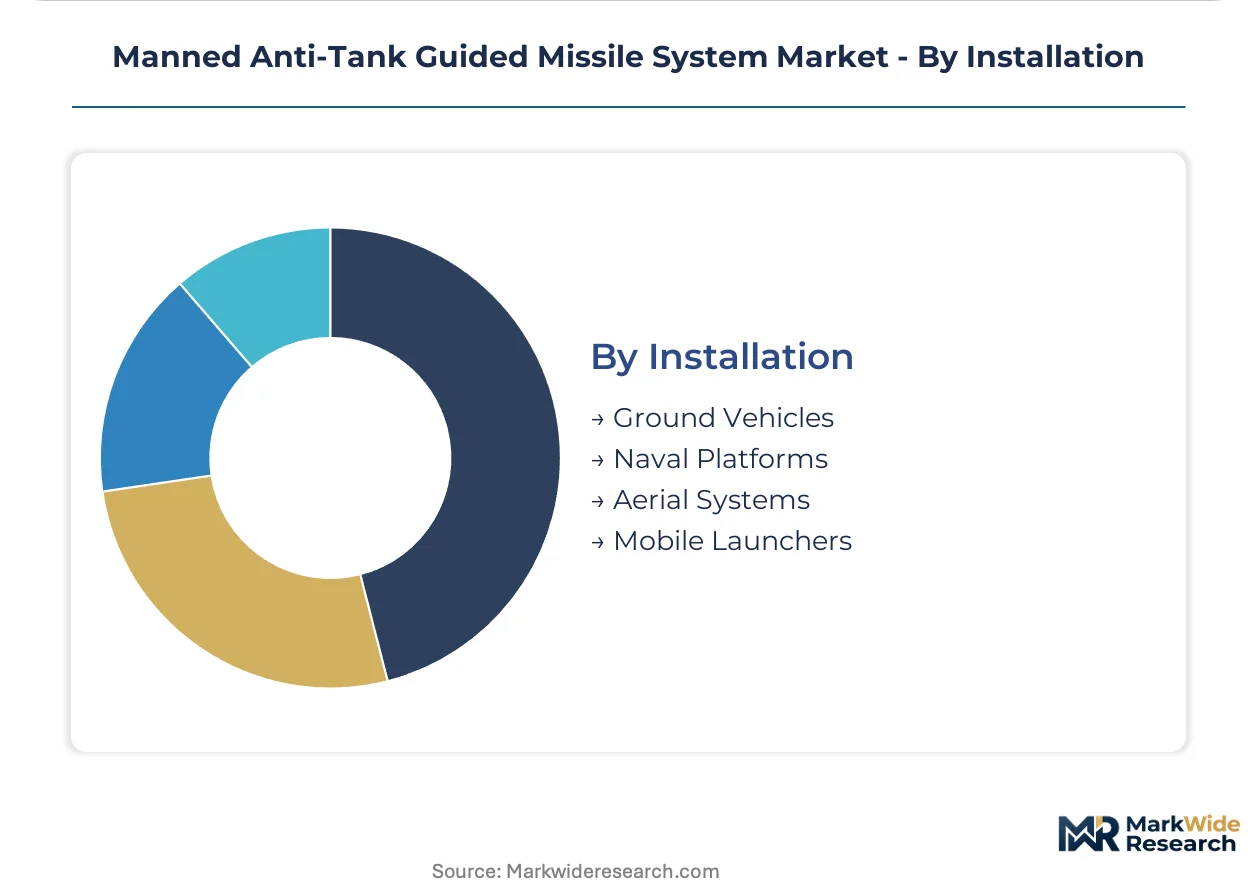
Installation:
Platform integration requirements dictate seeker calibration complexity and environmental hardening specifications.
- Ground Vehicles:Turret-mounted launchers with stabilized pintle mounts dominate mechanized brigade procurement. EDA cooperative procurement mechanisms aggregate volume for smaller NATO members seeking fleet-wide integration.
- Naval Platforms:Corvette and patrol vessel installations demand corrosion-resistant launch tubes with stabilized firing solutions against small-craft threats.
- Aerial Systems:Rotary-wing integration requires recoil mitigation and electromagnetic interference hardening for mast-mounted configurations.
- Mobile Launchers:Tripod and vehicle-towed systems serve rapid-deployment forces requiring air-transportable precision firepower.
Ground Vehicles absorb the largest procurement share; Naval Platforms are on the steepest expansion trajectory as littoral defense priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries in Poland and the Baltic states prioritize dismounted infantry configurations, while Germany and the United States concentrate procurement on vehicle-integrated turret systems. This divergence reflects continental deterrence postures versus expeditionary mechanized warfare doctrines.
United States
US Army modernization under NGCV directives accelerates turret-integrated precision munitions for mechanized brigades. ITAR licensing frameworks create transatlantic friction for component transfers to NATO allies. Raytheon Company leverages Javelin production infrastructure at Tucson, Arizona facilities to sustain recurring refurbishment contracts with Army arsenals.
Germany
Franco-German-Italian procurement corridors prioritize dual-mode seeker development for combined-arms interoperability. EU Green Deal defense-industry nexus rules mandate lifecycle carbon accounting for munitions production. Rheinmetall and MBDA coordinate propellant reengineering at Unterlüß and Schrobenhausen clusters to reduce per-unit emissions.
Poland
Polish mechanized brigades field clip-on thermal modules at scale under continental deterrence restructuring. EDA cooperative procurement mechanisms aggregate volume for fleet-wide Spike-family integration. The Terespol depot cluster exemplifies contractor-operated maintenance models for shoulder-fired inventories facing near-peer armor threats.
Israel
Rafael Advanced Defense Systems anchors domestic supply chains while extending Spike-family integration across European NATO inventories. Israeli defense procurement prioritizes networked multi-platform targeting for naval and rotary-wing applications. Government funding reallocations under strategic autonomy debates reshape component flows to European partners.
United Kingdom
BAE Systems coordinates cross-border component sourcing for guidance system actuators dependent on rare-earth magnet supply chains. UK defense procurement aligns with NATO interoperability requirements under EDA frameworks. Industrial concentration around Stevenage and Bolton facilities supports turret-integration programs for mechanized units.
Manned Anti-Tank Guided Missile System Market Vendor Landscape
Capability concentration sits with prime contractors possessing integrated seeker manufacturing; scale advantage sits with diversified defense conglomerates with multi-platform portfolios. The ecosystem structures around three tiers: established missile houses with full vertical control, subsystem specialists supplying guidance electronics, and government arsenals maintaining refurbishment capacity. Dominant competitive moves include strategic partnerships for EDA cooperative procurement compliance and portfolio diversification into naval and aerial platform integration.
Within the prime contractor tier, Raytheon Company and Rafael Advanced Defense Systems exemplify contrasting geographic anchoring strategies for NATO market access. Raytheon occupies a position tied to US Army NGCV modernization cycles and ITAR-constrained export frameworks. Rafael sits within Israeli supply chain architectures while extending Spike-family integration across Polish, German, and Baltic state inventories. MBDA represents the European consortium model, coordinating dual-mode seeker development across Franco-German-Italian procurement corridors.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems |
| Lockheed Martin Corporation |
| Denel Dynamics |
| Elbit Systems Ltd |
| Raytheon Company |
| Rafael Advanced Defense Systems |
| KBP Instrument Design Bureau |
| MBDA |
| Others |
Supply Flow & Price Mechanics
Tucson, Arizona's Javelin production cluster concentrates thermal-battery and seeker-calibration capacity, translating component scarcity into sustained pricing power for prime contractors serving US Army arsenals and NATO export frameworks. Chinese rare-earth processing dominance upstream feeds cost volatility through guidance-system actuator supply tiers, compressing margins for European integrators dependent on cross-border component flows.
Pricing Analysis
Long-term offtake contracts with defense ministries anchor revenue predictability for prime contractors, while spot procurement for thermal batteries and rare-earth magnets introduces cost volatility that stratifies pricing across Fire-and-Forget, Semi-Active, and Wire-Guided system tiers. Price differentiation hinges on seeker complexity and ITAR-compliance certification levels, with US-sourced imaging infrared arrays commanding premiums over European dual-mode alternatives. Cost compression in Wire-Guided refurbishment contracts is intensifying as Baltic states consolidate depot maintenance under contractor-operated models. National guard and territorial defense units exhibit highest price sensitivity, prioritizing man-portable configurations with reduced logistics footprints over turret-integrated precision munitions.
Supply Chain Analysis
Tariff exposure between China and NATO member states dominates supply chain risk calculus for guidance-system actuators dependent on neodymium-iron-boron magnet processing. Manufacturing concentrates in China, the United States, and Israel, with Israeli Spike-family production feeding European cooperative procurement mechanisms. Lithium-thionyl chloride thermal batteries and imaging infrared focal plane arrays represent critical input dependencies tethered to limited qualified supplier bases. Single-source vulnerability in rare-earth magnet sourcing exposes prime contractors to export control volatility. Distribution runs through government arsenals and contractor-operated depot clusters, with Poland's Terespol facility exemplifying the operational model shift toward performance-based availability guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire-and-forget seeker architectures are disrupting legacy command-guided procurement portfolios, with EU Green Deal lifecycle carbon accounting mandates forcing propellant reengineering investments that reshape competitive moats.
For Market Incumbents: Build captive supply chain moats through backward integration into rare-earth magnet recycling and thermal-battery qualification capacity, insulating against Chinese export control volatility. Anchor EDA cooperative procurement compliance to secure volume aggregation from Baltic and Polish mechanized brigades. Prioritize seeker calibration technician training pipelines to defend against commercial semiconductor fab talent competition. For New Entrants and Emerging Players: Establish a beachhead in naval platform integration for non-line-of-sight variants, where littoral defense priorities are intensifying demand faster than ground-force saturation. Target corrosion-resistant launch tube development for corvette and patrol vessel applications as the most penetrable segment. Pursue joint qualification pathways with European Defence Agency pooled acquisition mechanisms to bypass incumbent ITAR-constrained transatlantic networks. For Investors and Strategic Acquirers: Long-term, this sits as a dual-use technology convergence play because imaging infrared focal plane arrays digitizing military target acquisition share underlying sensor architectures with commercial autonomous systems. Acquisition targets should concentrate on subsystem specialists possessing electro-optical/infrared sensor alignment expertise and CSRD-compliant supply-chain documentation capabilities. Watch for ITAR relaxation debates and European Strategic Autonomy funding reallocations as inflection signals for transatlantic component flow restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Seeker Development | MBDA coordinates Franco-German-Italian procurement corridor interoperability for combined-arms environments. |
| Spike-NLOS Naval Integration | Rafael extends networked multi-platform targeting into corvette and rotary-wing applications beyond ground forces. |
| Propellant Reengineering Program | Rheinmetall reduces per-unit emissions at Unterlüß cluster to satisfy EU Green Deal defense-industry nexus mandates. |
| Contractor-Operated Depot Maintenance | Poland's Terespol cluster pilots performance-based availability guarantees for shoulder-fired inventories. |
| Thermal Module Brigade-Scale Fielding | Polish and German mechanized units compress sensor-to-shooter chains from minutes to seconds. |
Methodological Framework
Operator-level perspectives from program managers at defense ministries, procurement leads at prime contractors, depot maintenance supervisors, guidance-system calibration technicians, and EDA cooperative framework coordinators anchored the qualitative base for this analysis. Secondary validation drew from NATO acquisition directives, EU defence procurement databases, US Army NGCV modernization white papers, and CSRD supply-chain disclosure filings. Bottom-up unit procurement forecasts triangulated against top-down defense budget allocation patterns across the analysis window.
Scenario bracketing around ITAR relaxation timelines, rare-earth export control volatility, and EDA funding trajectory variations structured the forecast framework. Segmentation dimensions modeled include guidance architecture type, platform integration mode, end-user training profile, and regional deterrence posture cluster. CAGRs derived from weighted probability distributions across these scenarios, with inputs from thermal battery cost structure trajectories and seeker production yield rates at Israeli and US manufacturing clusters.
Sensitivities concentrate around Chinese rare-earth magnet export licensing shifts, EU Green Deal defense-industry nexus rule enforcement timing, and Baltic deterrence posture funding durability. Forecasts reflect documented assumptions regarding NATO interoperability requirement harmonization and ITAR framework continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Shotgun and Rifles Market