
 Military Trucks Market | 2026-2036
Military Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Military Trucks Market Intelligence
Armored specification tiers is redrawing competitive dynamics across the military trucks landscape. Oshkosh Corporation leverages its JLTV program experience to anchor Pentagon procurement cycles. Rheinmetall AG sustains European defense integration through its HX family production lines. Tata Motors Limited dominates indigenous Indian Army supply via its specialized high-mobility vehicle range.
Military trucks are wheeled or tracked automotive platforms engineered to gross vehicle weight ratings exceeding 10,000 pounds, designed for off-road torque multiplication and ballistic protection integration. Their primary purpose spans tactical logistics, weapon system transport, and battlefield command mobility under contested conditions. Heavy tactical configurations command the deepest margin pools due to armor integration complexity, while hybrid powertrain development represents the fastest-growing technology segment as militaries confront fuel convoy vulnerability. Logistic support applications retain the largest volume share across NATO end users.
The U.S. Department of Defense, Germany's BAAINBw, and India's MoD shape demand through localized content mandates and technical qualification protocols. EPA emissions standards and NATO STANAG ballistic protection levels filter market access for non-compliant suppliers. Stakeholders must monitor how battery-electric range constraints and armor weight trade-offs influence next-generation platform specifications.
Market Dynamics
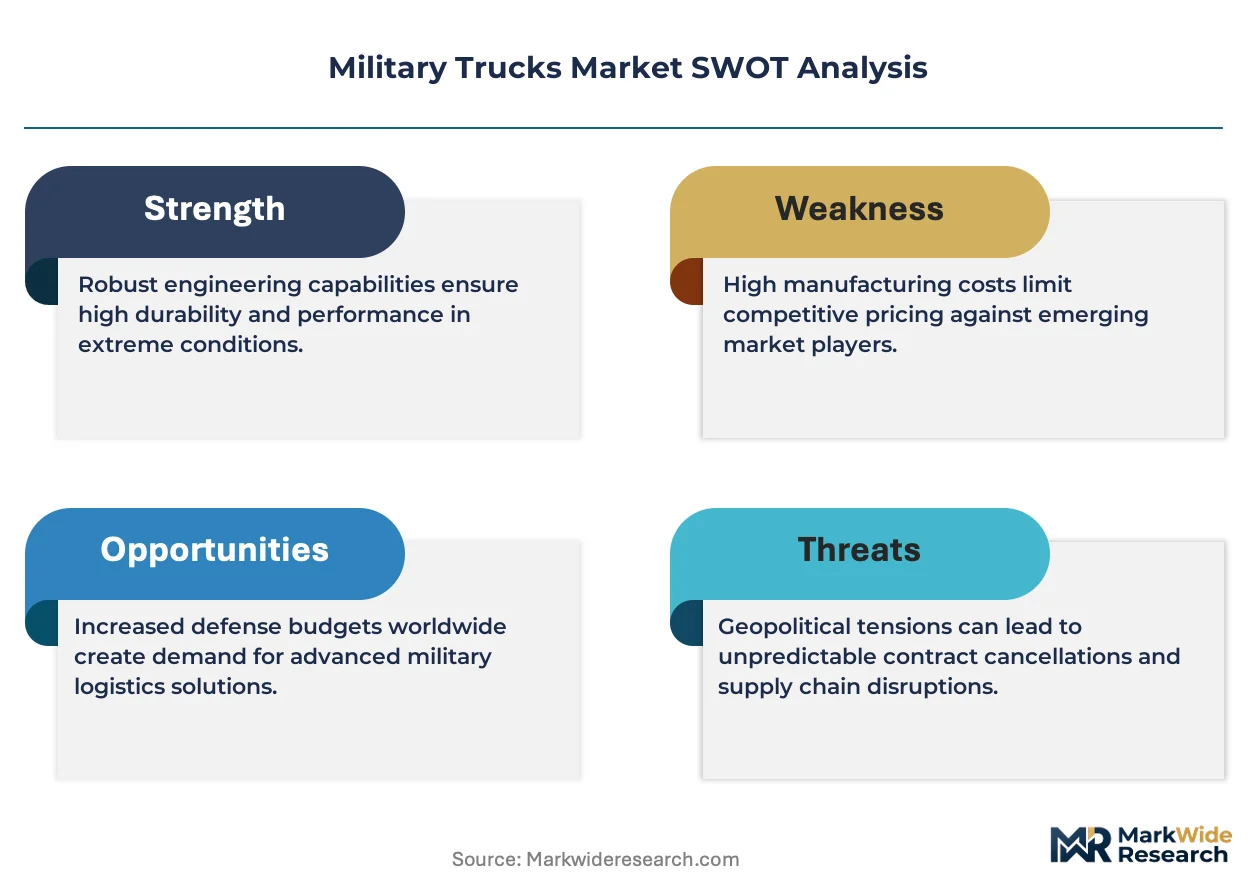
Armor weight penalties are forcing powertrain architects to rethink thermal management and torque distribution across NATO tactical vehicle programs. The Pentagon's JLTV specifications and Germany's BAAINBw technical mandates now embed electrification readiness as a non-negotiable platform requirement.
Growth Catalysts
- NATO STANAG ballistic protection mandates:Allied defense ministries are retiring unarmored Cold War-era fleets. This creates sustained replacement demand for mine-resistant configurations across European member states.
- Fuel convoy vulnerability reduction:Hybrid-electric architectures are displacing pure diesel powertrains. Forward operating base energy security now drives specification priorities in U.S. Central Command theaters.
- India's indigenization push:The Ministry of Defence's negative import lists and domestic content thresholds are redirecting procurement toward local assembly partnerships for high-mobility vehicle families.
Market Restraints
- Specialized armor steel supply concentration:Ballistic-grade plate production clusters in a handful of integrated mills. Disruption to any single source cascades through multiple OEM final assembly lines.
- EPA Tier 4 Final and Euro VI emissions compliance:Aftertreatment system bulk and thermal load compete directly with underbody blast protection packaging. Engineering trade-offs extend development cycles.
- Tracked platform substitution in heavy payload segments:Main battle tank derivatives and dedicated artillery tractors retain mobility advantages in contested terrain. Wheeled logistics trucks face displacement risk above 15-ton payload classes.
Strategic Opportunities
- Unmanned ground vehicle mothership architectures:Crewed tactical trucks are converging with drone launch and recovery systems. This creates new specification categories for payload-agnostic flatbed modules.
- Battery-electric range extension for garrison logistics:Fixed-base supply routes under 150 kilometers suit pure electric powertrains. India's cantonment networks and Germany's consolidated depot structure offer early deployment environments.
- Swappable mission module standards:NATO's drive for platform commonality across cargo, ambulance, and command post variants rewards suppliers with modular interface expertise.
Industry Challenges
- Ballistic welding certification scarcity:Qualified armor fabricators operate below program ramp requirements. Training pipelines for penetrant testing and stress-relieving procedures lag procurement timelines.
- Legacy vehicle fleet integration complexity:New digital backbone architectures must interoperate with analog-era maintenance infrastructure. Field repair depot software stacks require expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Trucks Market |
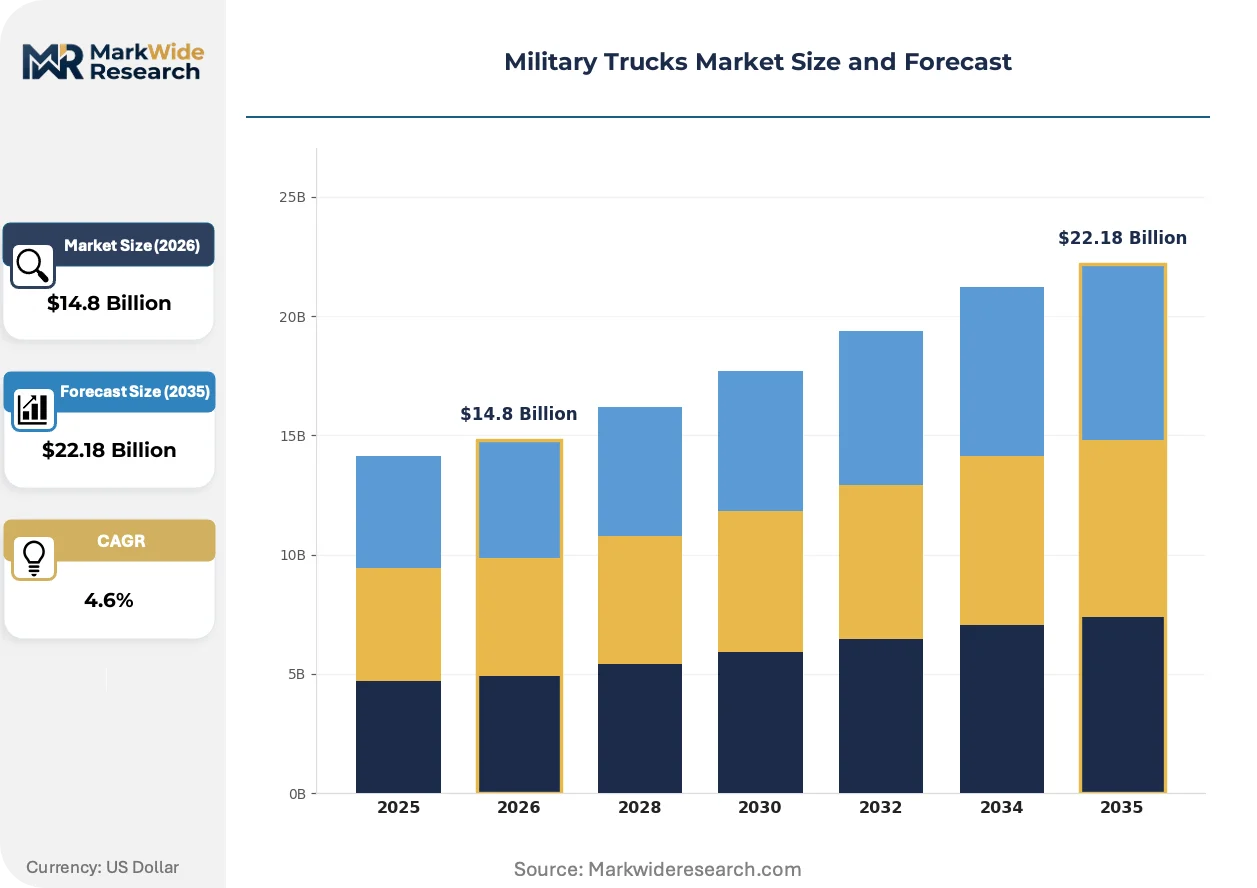
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Tactical, Heavy Tactical, Logistic Support, Command & Control Technology: Armored, Unarmored, Hybrid Powertrain, Diesel Engine Application: Combat Support, Reconnaissance, Troop Transport, Equipment Hauling, Engineering Support End User: Army, Special Forces, Paramilitary, Peacekeeping Units |
| Companies Covered | Mercedes-Benz Group AG, IVECO S.p.A., Oshkosh Corporation, Mack Trucks Inc., AM General LLC, Rheinmetall AG, BAE Systems, Tata Motors Limited, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Trucks Market Strategic Shifts & Innovations
Active protection systems and distributed power architectures are compressing traditional platform lifecycles. Defense procurement offices now treat software-defined capabilities as primary differentiators alongside mechanical reliability.
Silicon carbide power electronics are miniaturizing inverter footprints for hybrid military trucks. The U.S. Army's Ground Vehicle Systems Center is validating 800-volt architectures for silent watch and export power functions. This voltage step-change is miniaturizing thermal management hardware, freeing underhood volume for armor integration that previously required hull elongation.
REACH chemical registration and the EU Green Deal's embedded carbon tracking are filtering supplier eligibility for European defense contracts. BAAINBw now requires material passport documentation for steel and aluminum inputs. German and Dutch procurement offices are disqualifying bidders unable to demonstrate supply chain chemical compliance through the full vehicle lifecycle.
Performance-based logistics contracts are displacing traditional spares-and-maintenance purchasing. NATO Support and Procurement Agency frameworks now tie contractor payments to operational availability metrics rather than parts delivery. This shift concentrates risk with OEMs and is most visible in British Army medium truck fleet renewals, where Babcock and Rheinmetall compete on through-life cost guarantees rather than unit acquisition price.
Military Trucks Market Segmentation
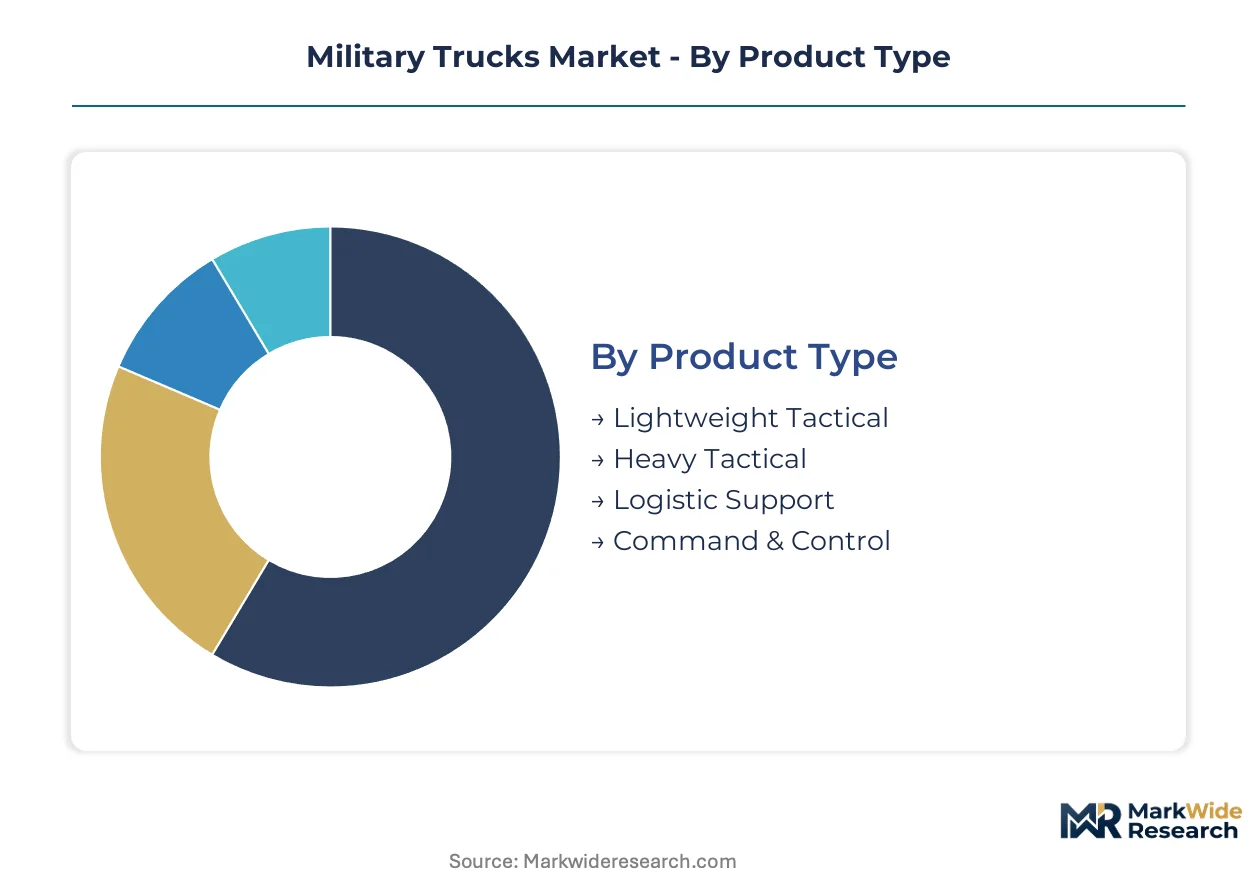
Segmentation in military trucks reveals how procurement offices trade payload capacity against survivability specifications. Platform architects must reconcile armor weight penalties with mobility requirements across divergent mission profiles.
Product Type:
Substitution pressure from tracked platforms intensifies above specific weight thresholds, reshaping wheeled vehicle procurement ceilings.
- Heavy Tactical:These platforms integrate underbody blast protection and add-on armor kits to gross vehicle weights exceeding 15 tons. The U.S. Army's Ground Vehicle Systems Center drives specification evolution through its next-generation combat vehicle programs. Ballistic-grade steel supply constraints extend delivery timelines for this category.
- Logistic Support:Unarmored or lightly protected cargo configurations dominate NATO theater resupply missions. Germany's BAAINBw and India's Ministry of Defence concentrate bulk procurement here for depot-to-forward-base distribution networks. Fuel convoy vulnerability reduction mandates are accelerating hybrid powertrain adoption in this segment.
- Lightweight Tactical:Air-transportable platforms prioritize strategic deployability over protection levels.
- Command & Control:Mobile headquarters variants integrate hardened communications suites and electromagnetic shielding.
Logistic Support retains volume leadership; Heavy Tactical holds the steepest expansion curve.
Technology:
Cost tier stratification separates developmental powertrains from mature propulsion architectures in current procurement cycles.
- Armored:STANAG 4569 ballistic protection levels dictate hull geometry and material selection across NATO member states. Welding certification scarcity for high-hardness steels constrains supplier base expansion. The Pentagon's JLTV program established performance benchmarks now referenced by multiple defense ministries.
- Hybrid Powertrain:Silent watch capability and export power functions drive 800-volt architecture development at the U.S. Army's Ground Vehicle Systems Center. Forward operating base energy security requirements in U.S. Central Command theaters validate operational concepts. Battery thermal management competes with underbody blast protection for hull volume.
- Unarmored:Garrison logistics and rear-echelon transport applications sustain diesel-dominant procurement.
- Diesel Engine:EPA Tier 4 Final and Euro VI compliance costs filter supplier participation in Western defense markets.
Diesel Engine retains volume leadership; Hybrid Powertrain is climbing the fastest.
Application:
Customer type differentiation separates frontline combat formations from support echelons in specification requirements.
- Combat Support:Ammunition resupply and forward medical evacuation platforms integrate active protection systems and remote weapon stations. The British Army's medium truck fleet renewals emphasize through-life cost guarantees over acquisition price. Performance-based logistics contracts concentrate operational risk with OEMs.
- Troop Transport:Mine-resistant ambush-protected configurations retain procurement priority for asymmetric threat environments. India's negative import lists redirect demand toward local assembly partnerships. Crew survivability specifications now exceed Cold War-era platform capabilities by multiple protection levels.
- Reconnaissance:Unmanned ground vehicle mothership architectures are converging with crewed platform specifications.
- Equipment Hauling:Heavy artillery tractors face displacement risk from tracked platform derivatives in contested terrain.
- Engineering Support:Bridge-launching and obstacle-clearance variants require specialized chassis modifications.
Troop Transport retains volume leadership; Combat Support shows the steepest expansion trajectory.
End User:
Supply concentration in armor fabrication capacity constrains expansion into specialized user categories with divergent qualification timelines.
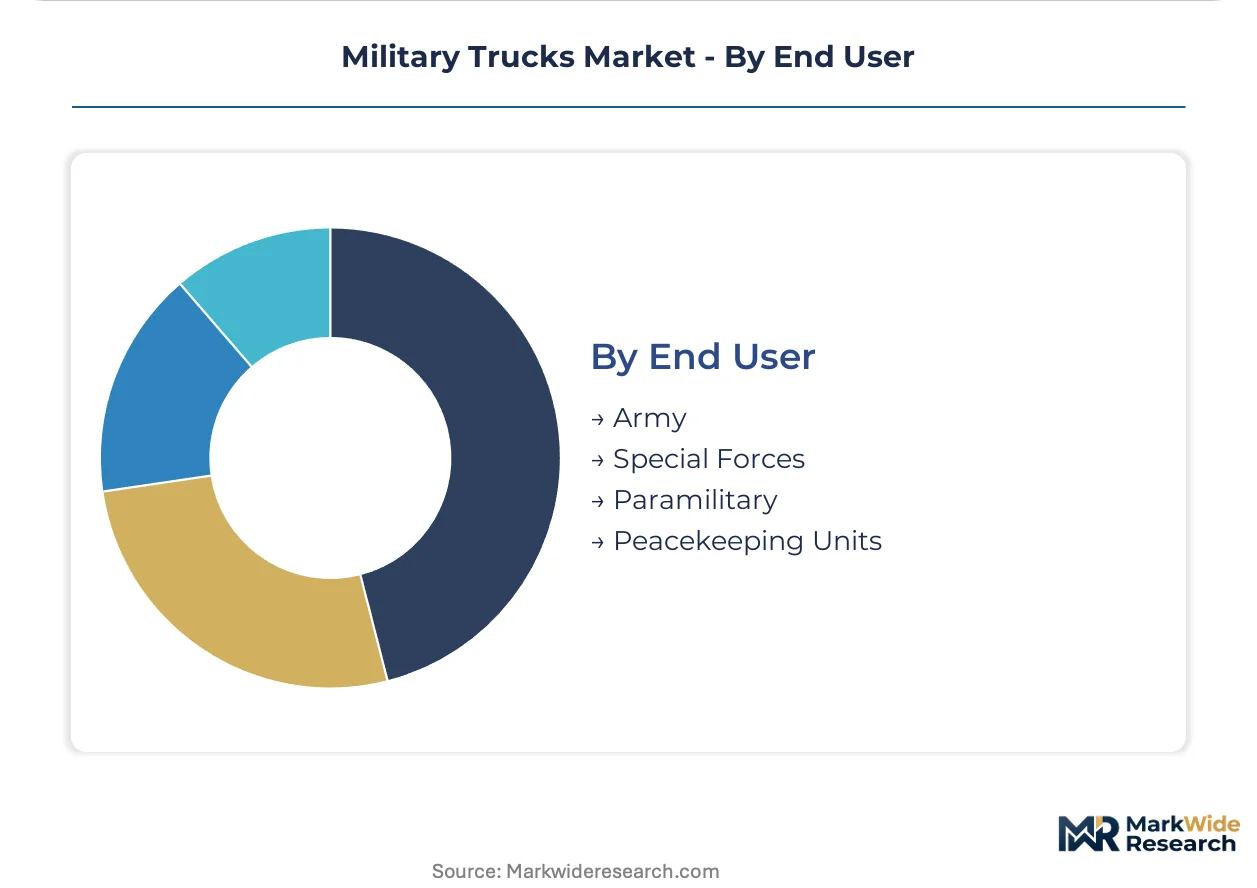
- Army:Conventional ground forces account for the preponderance of tactical vehicle procurement across NATO and Indo-Pacific defense ministries. Fleet modernization cycles replace Cold War-era platforms with standardized modular architectures. India's indigenization push redirects army procurement toward domestic content thresholds.
- Special Forces:Rapid infiltration requirements drive demand for air-droppable and helicopter-slingable configurations. Low-observable signatures and suppressed acoustic profiles differentiate specifications from conventional army platforms. Procurement volumes remain constrained by force structure limitations.
- Paramilitary:Border security and internal defense missions sustain demand for cost-optimized configurations.
- Peacekeeping Units:United Nations and regional stabilization missions generate episodic procurement through NATO Support and Procurement Agency frameworks.
Army retains volume leadership; Special Forces gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in military trucks reveal persistent trade imbalances as armor-grade steel and powertrain components flow from industrialized suppliers toward assembly hubs in emerging defense markets. Procurement localization mandates are compressing cross-border finished vehicle shipments while amplifying component trade intensity.
United States
The Pentagon's JLTV program and Ground Vehicle Systems Center specifications drive sustained demand for heavy tactical configurations. EPA Tier 4 Final emissions standards filter supplier participation through aftertreatment compliance requirements. Detroit's automotive engineering cluster hosts validation facilities for 800-volt hybrid architectures targeting forward operating base applications.
Germany
BAAINBw technical mandates embed electrification readiness as platform requirements across Bundeswehr fleet renewals. REACH chemical registration and EU Green Deal embedded carbon tracking disqualify non-compliant armor steel suppliers. The Düsseldorf-Ruhr industrial corridor concentrates ballistic-grade plate fabrication capacity serving multiple NATO member programs.
India
The Ministry of Defence's negative import lists and domestic content thresholds redirect procurement toward local assembly partnerships for high-mobility vehicle families. DGFT licensing frameworks constrain direct import of complete tactical platforms. Pune and Jamshedpur anchor indigenous production clusters where Tata Motors Limited scales armored variant output for army modernization cycles.
United Kingdom
Performance-based logistics contracts through the British Army's medium truck fleet renewals tie contractor payments to operational availability metrics. BAAINBw-influenced NATO STANAG ballistic protection levels shape specification requirements for mine-resistant configurations. The Midlands defense manufacturing belt hosts subsystem integration facilities supporting through-life cost guarantee competitions.
France
ANSM and CNIL data protection frameworks intersect with military platform cybersecurity requirements for command and control variants. ECHA REACH compliance filters armor steel supplier eligibility for domestic and export contracts. The Île-de-France region hosts procurement coordination for episodic United Nations peacekeeping vehicle contributions through NATO Support and Procurement Agency frameworks.
Military Trucks Market Key Industry Players
Listed leaders compete with private specialists across program scale and qualification depth, creating tiered competitive dynamics where public company balance sheet capacity meets private firm agility in niche armor applications. The vendor base clusters around three strategic archetypes: diversified automotive conglomerates with defense divisions, pure-play tactical vehicle specialists, and state-affiliated industrial champions serving domestic indigenization mandates. Consolidation pressure concentrates in ballistic welding certification capacity, while technology licensing agreements proliferate around hybrid powertrain architectures.
Among diversified automotive conglomerates, Mercedes-Benz Group AG and Tata Motors Limited exemplify the dual-use manufacturing model, leveraging civilian truck platforms for military variant derivation. Rheinmetall AG occupies a position within the European pure-play specialist tier, anchoring NATO member state procurement through modular platform architectures. These three entities represent distinct competitive positioning vectors: automotive scale, regional defense integration, and indigenous supply chain capture.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| IVECO S.p.A. |
| Oshkosh Corporation |
| Mack Trucks Inc. |
| AM General LLC |
| Rheinmetall AG |
| BAE Systems |
| Tata Motors Limited |
| General Dynamics Corporation |
| Others |
Cost & Logistics Intelligence
Performance-based logistics contracts lock in multi-year operational availability commitments between NATO procurement offices and tactical vehicle OEMs, binding price visibility to armor fabrication capacity reservations and powertrain component allocation schedules. This contract structure concentrates margin risk with manufacturers while insulating defense ministries from spot-market volatility in ballistic-grade steel and silicon carbide power electronics.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in military truck procurement. Premium tiers command substantial markups for STANAG 4569 Level 4+ ballistic protection and 800-volt hybrid architectures, while standard configurations compete on through-life cost guarantees rather than acquisition price. Cost compression in economy-tier unarmored logistics trucks is intensifying because India's domestic content mandates and Germany's REACH compliance requirements filter supplier participation. Border security agencies exhibit the highest price sensitivity, whereas special forces procurement prioritizes capability over unit cost.
Supply Chain Analysis
Extended order-to-delivery cycles for ballistic-grade plate now stretch 18-24 months, forcing OEMs to pre-position armor steel inventories ahead of contract awards. Production clusters in Germany, the United States, and India dominate final assembly, while South Korean and Japanese suppliers feed critical powertrain electronics and battery thermal management systems. The supply chain rests on concentrated high-hardness steel mill capacity in the Düsseldorf-Ruhr corridor and Jamshedpur region. Single-source vulnerability in qualified armor fabricators creates cascading disruption risk across multiple NATO programs. Distribution runs through government-to-government foreign military sales channels and domestic defense procurement offices rather than commercial dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military truck procurement is entering a cyclical upswing driven by NATO member states retiring Cold War-era platforms under accelerated fleet modernization schedules. Defense ministries are consolidating fragmented supplier bases around modular platform architectures with electrification readiness.
For Market Incumbents: Shield program positions by securing captive supply of ballistic-grade steel through backward integration into European and Indian mill partnerships. Accelerate certification pipelines for 800-volt hybrid architectures before EPA Tier 4 Final and Euro VI emissions deadlines filter competitor participation. Lock in performance-based logistics contract renewals with through-life cost guarantees that embed proprietary digital maintenance platforms.
For New Entrants and Emerging Players: NATO STANAG 4569 welding certification fast-tracks offer the most penetrable entry pathway for specialized armor fabricators lacking legacy platform heritage. Target India's high-mobility vehicle segment where negative import lists and domestic content thresholds redirect procurement toward local assembly partnerships. Pursue technology licensing agreements with established powertrain suppliers rather than greenfield R&D investment.
For Investors and Strategic Acquirers: Pure-play tactical vehicle specialists with modular platform expertise and existing NATO qualification represent the most attractive acquisition targets in this consolidation phase. Long-term viability hinges on exposure to Indo-Pacific defense modernization cycles and European fleet replacement programs rather than episodic Middle Eastern procurement. Watch for battery-electric range breakthroughs in garrison logistics applications as the inflection signal for next-generation platform specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | British Army and BAAINBw frameworks now tie contractor payments to operational availability metrics rather than spares delivery. |
| Hybrid Powertrain Architecture Investment | U.S. Army Ground Vehicle Systems Center validation of 800-volt systems creates specification precedent across NATO procurement offices. |
| Ballistic Welding Certification Expansion | Qualified armor fabricator scarcity constrains program ramp rates for mine-resistant platform deliveries. |
| Domestic Content Partnership Structuring | India's Ministry of Defence negative import lists redirect foreign OEMs toward local assembly joint ventures. |
| Active Protection Systems Integration | Remote weapon stations and crewed-unmanned teaming capabilities compress traditional platform lifecycles. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, platform engineering directors, and armor fabrication specialists; and secondary validation against NATO STANAG documentation, EPA emissions filings, and defense ministry budget appropriations. Primary fieldwork encompassed program managers at the Pentagon's Joint Program Office, BAAINBw technical staff, and Tata Motors Limited military vehicle division leadership. Secondary sources included U.S. Army Ground Vehicle Systems Center technical reports, EU REACH chemical registration databases, and Indian DGFT licensing records. Bottom-up segment sizing triangulated against top-down defense expenditure forecasts.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type, technology tier, application mission profile, and end-user force structure. CAGRs were derived from historical procurement cycle analysis and projected fleet replacement schedules. Key inputs included NATO member state defense budget trajectories, indigenization policy implementation timelines, and powertrain technology readiness levels for hybrid-electric architectures.
Underlying assumptions cover sustained NATO defense expenditure commitment, stable ballistic-grade steel supply from integrated mill capacity, and incremental rather than disruptive electrification adoption, with deviation risk concentrated in program delay cascades from welding certification bottlenecks and battery thermal management integration challenges. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Russia Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Destroyers Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Japan Defense Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Iran Defense Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Combat Support Vehicle Market