
 Small and Medium Caliber Ammunition Market | 2026-2036
Small and Medium Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Small and Medium Caliber Ammunition Market Intelligence
Defense procurement is decoupling from legacy single-source relationships as military buyers fragment orders across qualified suppliers to mitigate supply chain risk. General Dynamics Corporation leverages its Lake City Army Ammunition Plant contract to sustain high-volume 5.56mm and 7.62mm production for the US military. Rheinmetall AG anchors European NATO supply through its new factory in Hungary, while Nammo AS specializes in lead-free and specialty munitions for environmentally restricted training environments.
Small and medium caliber ammunition encompasses metallic-cased cartridges from .22 LR through 7.62mm NATO, manufactured through brass drawing, primer seating, propellant loading, and projectile crimping processes for portable firearms. The product category serves military operations, law enforcement engagement, and civilian marksmanship where terminal ballistics, reliability, and lot consistency determine operational outcomes. Cartridge and shell formats dominate military procurement volumes, while 9mm and 5.56mm caliber sizes capture the largest share of law enforcement and armed forces demand respectively. Training applications represent the fastest-growing segment as NATO allies expand live-fire exercise tempo and replace depleted strategic reserves.
The US Army's Next Generation Squad Weapon program, EPA lead-free mandates, and NATO standardization agreements (STANAG) collectively constrain projectile composition while demanding enhanced lethality. BIS certification requirements in India and DGFT export licensing in that market further complicate cross-border supply for non-aligned buyers. Stakeholders must monitor how ammunition traceability regulations and green chemistry standards reshape acceptable primers and propellants before committing to long-term capacity investments.
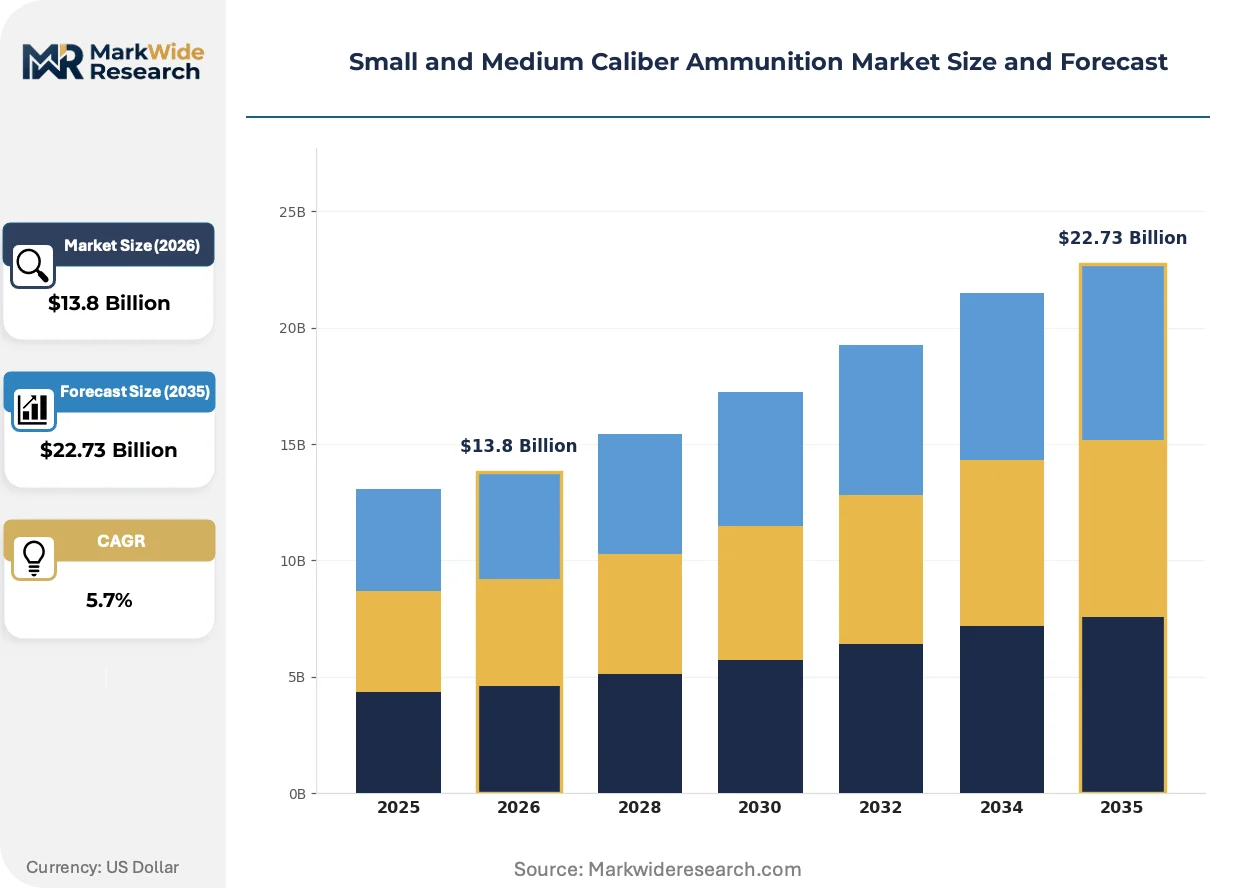
Market Dynamics
Defense procurement fragmentation across NATO member states is compressing contract tenures and dispersing volume commitments, forcing suppliers to absorb higher transition costs while maintaining surge capacity for contingency orders.
Growth Catalysts
- Next Generation Squad Weapon program:The US Army's fielding of 6.8mm weapons systems generates immediate demand for new cartridge families and associated production tooling investments.
- REACH lead restrictions:European ECHA regulations on toxic substances accelerate lead-free projectile adoption, opening specialty manufacturing niches for compliant suppliers.
- Training tempo expansion:NATO allies in Eastern Europe have tripled live-fire exercise frequency, depleting strategic reserves and triggering replenishment orders for 5.56mm and 7.62mm stocks.
Market Restraints
- Brass supply concentration:Primary brass sheet production clusters in Germany and the United States, creating single-source vulnerability for NATO cartridge casing feedstock.
- Propellant chemistry lock-in:Legacy nitrocellulose formulations face EPA emissions scrutiny while replacement energetics require decade-long qualification timelines.
- Indian import licensing:DGFT export controls and BIS certification requirements block rapid market access for non-aligned suppliers seeking defense contracts.
Strategic Opportunities
- Lead-free training rounds:EPA mandates and ECHA restrictions create captive demand for tungsten-composite and polymer-matrix projectiles in domestic ranges.
- Hungarian production hub:Rheinmetall's new facility positions suppliers to capture NATO eastern flank procurement as regional stockpiles rebuild.
- Digital lot traceability:Blockchain-enabled ammunition tracking meets emerging chain-of-custody requirements for law enforcement agencies.
Industry Challenges
- Skilled tool-and-die shortage:Precision cartridge drawing requires journeyman-level metalworking expertise that military suppliers struggle to recruit against commercial manufacturing wages.
- STANAG harmonization delays:NATO standardization agreements on 6.8mm interoperability remain unresolved, freezing procurement specifications and tooling commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small and Medium Caliber Ammunition Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartridge, Shell, Sniper Round, Submachine Gun Cartridge, Revolver Cartridge, Magnum Round Caliber Size: 5.56mm, 7.62mm, .22 LR, 9mm, .45 ACP, .308 Winchester Application: Military Operations, Law Enforcement, Civilian Hunting, Competitive Shooting, Personal Defense, Training End User: Armed Forces, Police Departments, Security Firms, Private Collectors, Shooting Ranges, Tactical Units |
| Companies Covered | Northrop Grumman Corporation, Elbit Systems Ltd., General Dynamics Corporation, Olin Corporation, Vista Outdoor, BAE Systems Inc., Rheinmetall AG, FN Herstal, Nammo AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small and Medium Caliber Ammunition Market Strategic Shifts & Innovations
Technical requirements for small arms ammunition are bifurcating between enhanced lethality specifications for combat loads and reduced-range constraints for training environments, forcing parallel product development tracks.
Polymer-cased cartridge technology is unifying weight reduction and corrosion resistance in a single platform. Special operations forces across NATO members are evaluating polymer 5.56mm and 7.62mm variants for dismounted load reduction. This materials shift is unifying supply chains previously segmented between brass and steel casing production, compressing supplier qualification pools.
EPA lead-free mandates and ECHA restrictions on toxic substances are forcing projectile metallurgy redesigns. Manufacturers must substitute tungsten, copper, or bismuth alloys for traditional lead cores while maintaining terminal ballistics. Law enforcement training facilities in California and European domestic ranges face the steepest compliance costs, accelerating demand for certified non-toxic alternatives.
Multi-vendor contract awards are fragmentizing historical sole-source relationships. US Army ammunition procurement now spreads Lake City output across competitive lots, while NATO allies replicate this risk-distribution model. Eastern European defense ministries exhibit the fastest adoption of split-award structures, using competitive tension to secure pricing leverage and surge guarantees.
Small and Medium Caliber Ammunition Market Segmentation
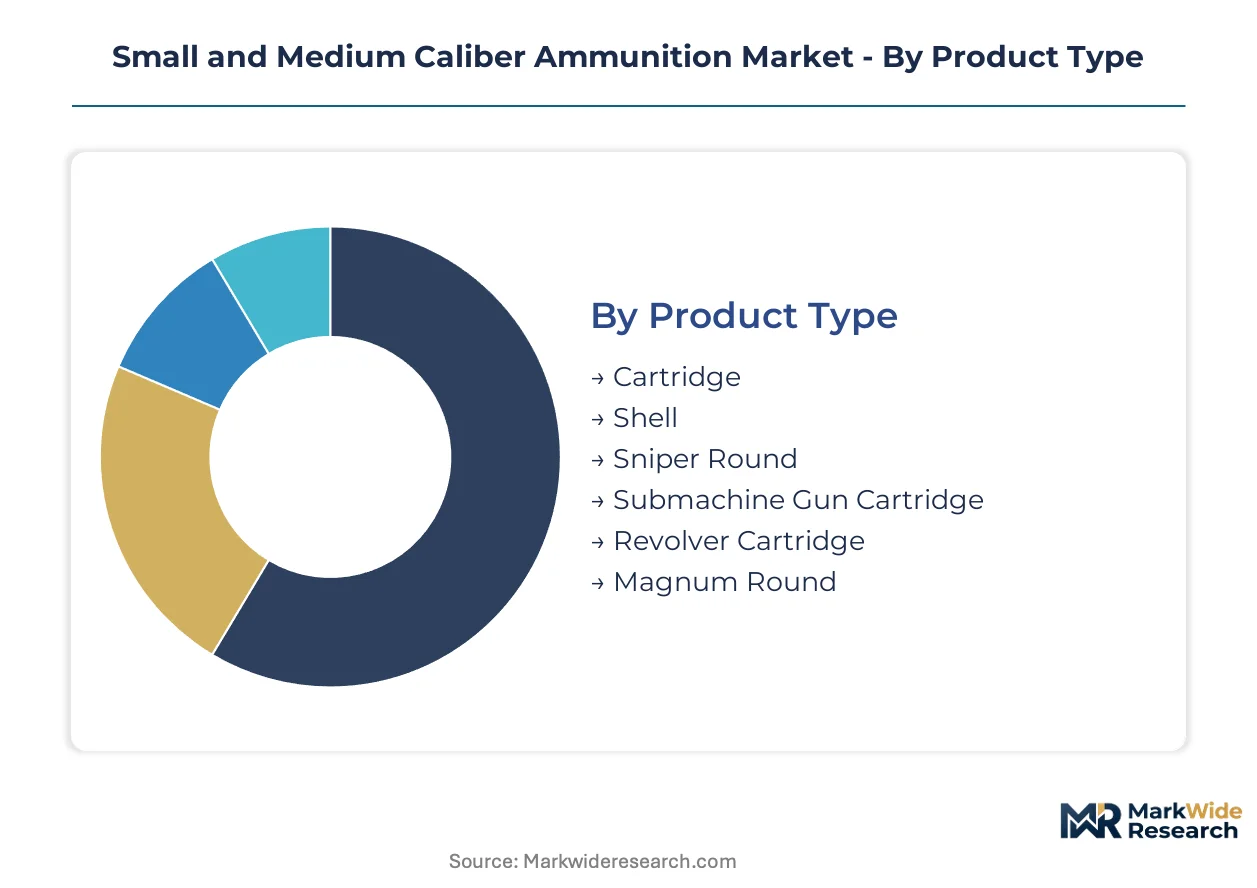
Segmentation in small and medium caliber ammunition reveals how procurement fragmentation and technical specialization split manufacturing capacity across incompatible tooling sets. Buyers prioritize different performance envelopes—terminal ballistics for combat loads versus cost efficiency for high-volume training—forcing suppliers to maintain parallel production lines.
Product Type:
Buyers differentiate by weapon platform compatibility and lot consistency requirements, with military contracts demanding traceable production runs that civilian markets rarely require.
- Cartridge:Standard metallic-cased rounds dominate procurement volumes through brass drawing and precision crimping processes. US Army modernization programs and NATO eastern flank replenishment orders concentrate demand for 5.56mm and 7.62mm variants at Lake City and Rheinmetall's Hungarian facility.
- Shell:Shotgun shells serve law enforcement breaching operations and civilian hunting with plastic or paper hulls loaded with lead or steel shot. EPA lead-free mandates in domestic US ranges and ECHA restrictions across European training facilities accelerate substitution toward tungsten-composite payloads.
- Sniper Round:Match-grade precision ammunition requires hand-inspected components and sub-MOA consistency for long-range engagement.
- Submachine Gun Cartridge:Compact pistol-caliber rounds optimized for suppressed fire and close-quarters combat.
- Revolver Cartridge:Rimmed designs serving law enforcement backup weapons and civilian personal defense.
- Magnum Round:High-pressure loadings for hunting and specialized tactical applications requiring enhanced terminal performance.
Cartridge formats lead volumes today; shell demand is gaining share fastest through law enforcement procurement expansion.
Caliber Size:
Platform standardization agreements and inventory compatibility drive caliber selection more than marginal ballistic improvement.
- 5.56mm:NATO standard intermediate cartridge balances controllable recoil with effective range for individual rifles. Training tempo expansion across Eastern European allies and US Army Next Generation Squad Weapon transition volumes sustain production at Lake City and allied facilities.
- 9mm:Pistol and submachine gun standard for law enforcement worldwide, with hollow-point and full-metal-jacket variants serving duty and training respectively. Police department procurement in the United States and security firm contracts across NATO member states absorb the majority of commercial output.
- 7.62mm:Full-power rifle cartridge for machine guns and designated marksman rifles, with linked belts and loose rounds serving distinct supply chains.
- .22 LR:Rimfire training and recreational round with minimal recoil and lowest per-round cost.
- .45 ACP:Subsonic pistol cartridge retained by select US military units and specialized law enforcement teams.
- .308 Winchester:Civilian hunting and precision shooting variant of 7.62mm NATO with slightly different chamber specifications.
5.56mm leads volumes today; 9mm is climbing the fastest through law enforcement standardization.
Application:
Operational environment dictates projectile composition, with indoor training ranges facing stricter environmental controls than open-field combat deployment.
- Military Operations:Combat-optimized loads prioritize terminal ballistics and barrier penetration over cost, with enhanced-performance projectiles replacing M855 and M80 ball ammunition. US Army fielding of 6.8mm weapons and NATO STANAG harmonization efforts reshape procurement specifications.
- Training:High-volume consumption with reduced-range or lead-free constraints for indoor facilities. Eastern European NATO allies have tripled live-fire exercise frequency, depleting strategic reserves and triggering replenishment orders for 5.56mm and 7.62mm stocks.
- Law Enforcement:Duty ammunition requires reliable expansion and penetration through intermediate barriers.
- Civilian Hunting:State-specific regulations on lead core restrictions and caliber minimums fragment product requirements.
- Competitive Shooting:Precision reloadable brass and consistent powder charges for accuracy-dependent disciplines.
- Personal Defense:Compact hollow-point designs optimized for short-barrel handguns.
Military operations lead volumes today; training is expanding most quickly through NATO readiness initiatives.
End User:
Contract structure and liability exposure separate institutional buyers from commercial channels, with armed forces demanding surge capacity guarantees unavailable to civilian markets.
- Armed Forces:National military establishments procure through multi-year indefinite-delivery contracts with domestic content requirements. US Army ammunition awards now split across competitive lots rather than sole-source arrangements, compressing margins while demanding maintained surge capacity.
- Police Departments:Municipal and federal law enforcement agencies procure duty and training ammunition through competitive bidding with certification requirements. California and European indoor ranges face steepest lead-free compliance costs, accelerating demand for certified non-toxic alternatives.
- Security Firms:Private contractors serving diplomatic and commercial protection with varying jurisdictional restrictions.
- Private Collectors:Enthusiast purchasers of historical and limited-production ammunition.
- Shooting Ranges:Commercial training facilities with bulk procurement and spent-casing reclamation programs.
- Tactical Units:Specialized law enforcement and military elements requiring match-grade and subsonic loadings.
Armed forces lead volumes today; police departments are gaining share fastest through municipal budget recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German output by a factor of three, yet both nations face identical pressure to diversify supplier bases beyond historical single-source arrangements. Each geography navigates distinct regulatory constraints while expanding domestic production footprints.
United States
Army modernization programs and Next Generation Squad Weapon fielding absorb growing 6.8mm cartridge volumes at Lake City Army Ammunition Plant. EPA lead-free mandates for training ranges accelerate tungsten-composite projectile adoption. Domestic brass drawing capacity concentrates in Missouri and Tennessee, where General Dynamics and Olin Corporation operate high-volume lines.
Germany
Rheinmetall AG anchors European NATO supply through precision manufacturing for allied defense ministries. ECHA REACH restrictions on toxic substances force lead-free projectile redesigns across Bundeswehr training facilities. Industrial clusters in Lower Saxony and Bavaria host specialized tool-and-die operations supporting cartridge casing production.
Hungary
Rheinmetall's new factory near Várpalota positions suppliers to capture NATO eastern flank procurement as regional stockpiles rebuild. EU defense fund allocations support capacity expansion for 5.56mm and 7.62mm standardization. The facility serves Polish, Romanian, and Czech defense ministries seeking reduced reliance on German supply chains.
India
BIS certification requirements and DGFT export licensing block rapid market access for non-aligned suppliers seeking defense contracts. Indigenous production mandates under Make in India policy drive Ordnance Factory Board modernization. Ammunition manufacturing clusters concentrate in Maharashtra and Tamil Nadu, where state-owned facilities face quality consistency challenges.
Norway
Nammo AS specializes in lead-free and specialty munitions for environmentally restricted training environments across Nordic defense ministries. ECHA compliance positions the manufacturer for Swedish and Finnish procurement expansion. Production facilities near Raufoss supply NATO allies with tungsten-matrix projectiles meeting range contamination standards.
Small and Medium Caliber Ammunition Market Key Industry Players
United States producers anchor one tier; European specialists hold adjacent positions through NATO standardization alignment. Market structure consolidates around five dominant defense contractors with sustained government relationships, while mid-tier regional fabricators capture national procurement outside alliance frameworks. Two strategic archetypes predominate: integrated prime contractors operating government-owned facilities, and specialty manufacturers focused on environmental compliance. Competitive moves center on capacity expansion in Eastern European production hubs and polymer-cased cartridge technology licensing.
Among US-based integrated primes, General Dynamics Corporation and Northrop Grumman Corporation exemplify the government-facility operator archetype through sustained Army ammunition plant contracts. Olin Corporation represents the commercial-defense hybrid model with scaled brass manufacturing capabilities. European positioning concentrates with Rheinmetall AG and Nammo AS, each occupying distinct specialization vectors within NATO supply chains.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Elbit Systems Ltd. |
| General Dynamics Corporation |
| Olin Corporation |
| Vista Outdoor |
| BAE Systems Inc. |
| Rheinmetall AG |
| FN Herstal |
| Nammo AS |
| Others |
Cost & Logistics Intelligence
US Army multi-vendor procurement contracts anchor pricing power in this market, compressing margins through competitive lot awards while demanding maintained surge capacity. Brass feedstock concentration in Germany and the United States shapes cost structures, with EPA lead-free mandates adding compliance premiums to training round specifications.
Pricing Analysis
Capacity additions in Hungary are reshaping price floors for NATO eastern flank procurement, introducing competitive tension previously absent from German-dominated supply. Three-tier pricing structure across match-grade precision, standard military ball, and reduced-range training levels differentiates by terminal performance and lot traceability. Cost compression in standard 5.56mm and 7.62mm lines is intensifying because of split-award contract structures. Police departments exhibit highest price sensitivity due to municipal budget constraints; special operations units show lowest sensitivity given mission-critical reliability requirements.
Supply Chain Analysis
Domestic-content mandates under Make in India policy and US Berry Amendment provisions are reshaping sourcing patterns, forcing non-aligned suppliers to establish local joint ventures. Brass sheet production draws from Germany, the United States, and South Korea; nitrocellulose propellant supply rests on Russian and Chinese precursor exports now subject to trade restrictions. Single-source vulnerability in primer compound chemistry poses structural risk given decade-long qualification timelines for alternative energetics. Distribution runs through government-owned contractor-operated facilities and national ordnance depots rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through sustained defense modernization cycles, with NATO eastern flank replenishment and lead-free mandate compliance generating predictable procurement windows.
For Market Incumbents: Hedge against polymer-cased cartridge displacement by securing licensing agreements with materials specialists before platform standardization freezes. Lock in brass supply through backward integration into primary metal production or long-term offtake contracts with German and US sheet mills. Counter skilled tool-and-die labor scarcity with apprenticeship pipelines tied to community college machining programs in Missouri and Tennessee. For New Entrants and Emerging Players: Launch via subcontractor relationships to prime contractors holding Lake City or Rheinmetall Hungary capacity, bypassing decade-long facility qualification timelines. Target Indian domestic production mandates as the most penetrable geography, partnering with Ordnance Factory Board entities to satisfy BIS certification and DGFT licensing requirements. Pursue lead-free training round specialization as the fastest-qualified entry path, leveraging EPA and ECHA compliance gaps in incumbent product portfolios. For Investors and Strategic Acquirers: Defense contractors with government facility operating experience are the most active acquirer in this space, seeking specialty manufacturers with environmental compliance certifications. Five-to-ten-year viability hinges on 6.8mm NGSW program execution and polymer-casing technology maturation. Monitor STANAG harmonization progress as the critical inflection signal—resolution unlocks tooling investments and procurement volume visibility; continued delay traps capital in specification uncertainty.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Eastern European Hubs | Rheinmetall's Hungarian facility captures NATO eastern flank demand as Polish and Romanian stockpiles rebuild. |
| Lead-Free Projectile Redesign | EPA mandates and ECHA REACH restrictions force tungsten-composite metallurgy investments for range compliance. |
| Polymer-Casing Technology Licensing | Special operations evaluations of 5.56mm and 7.62mm polymer variants unify previously segmented supply chains. |
| Digital Lot Traceability Implementation | Blockchain-enabled tracking meets emerging chain-of-custody requirements for law enforcement agency procurement. |
| Skilled Workforce Pipeline Development | Journeyman-level tool-and-die expertise scarcity in military supply chains demands targeted recruitment against commercial manufacturing wages. |
Research Approach
Coverage spans the United States, Germany, Hungary, India, and Norway, with primary inputs from each defense procurement cluster. Army ammunition program managers, brass mill procurement directors, and ECHA regulatory compliance officers contributed structured interviews. Secondary validation drew from NATO STANAG documentation, EPA enforcement actions on range contamination, SEC 10-K filings from publicly traded defense contractors, and customs trade data on nitrocellulose precursor movements. Bottom-up volume modeling triangulated against top-down defense budget appropriation analysis.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, caliber size, application, and end user, with additional granularity on environmental compliance tier. CAGRs derived from weighted scenario analysis across procurement program timelines, regulatory implementation schedules, and platform transition assumptions. Forecast inputs incorporated US Army NGSW fielding pace, ECHA REACH restriction expansion scope, and NATO eastern flank exercise tempo sustainability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under STANAG harmonization failure or acute brass supply disruption scenarios. Assumptions reflect documented procurement program schedules and regulatory implementation timelines. Geopolitical trade restriction escalation or propellant chemistry breakthroughs could materially revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Smart Bullets Market