
 Global Tactical Headset Market | 2026-2036
Global Tactical Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tactical Headset Market Outlook
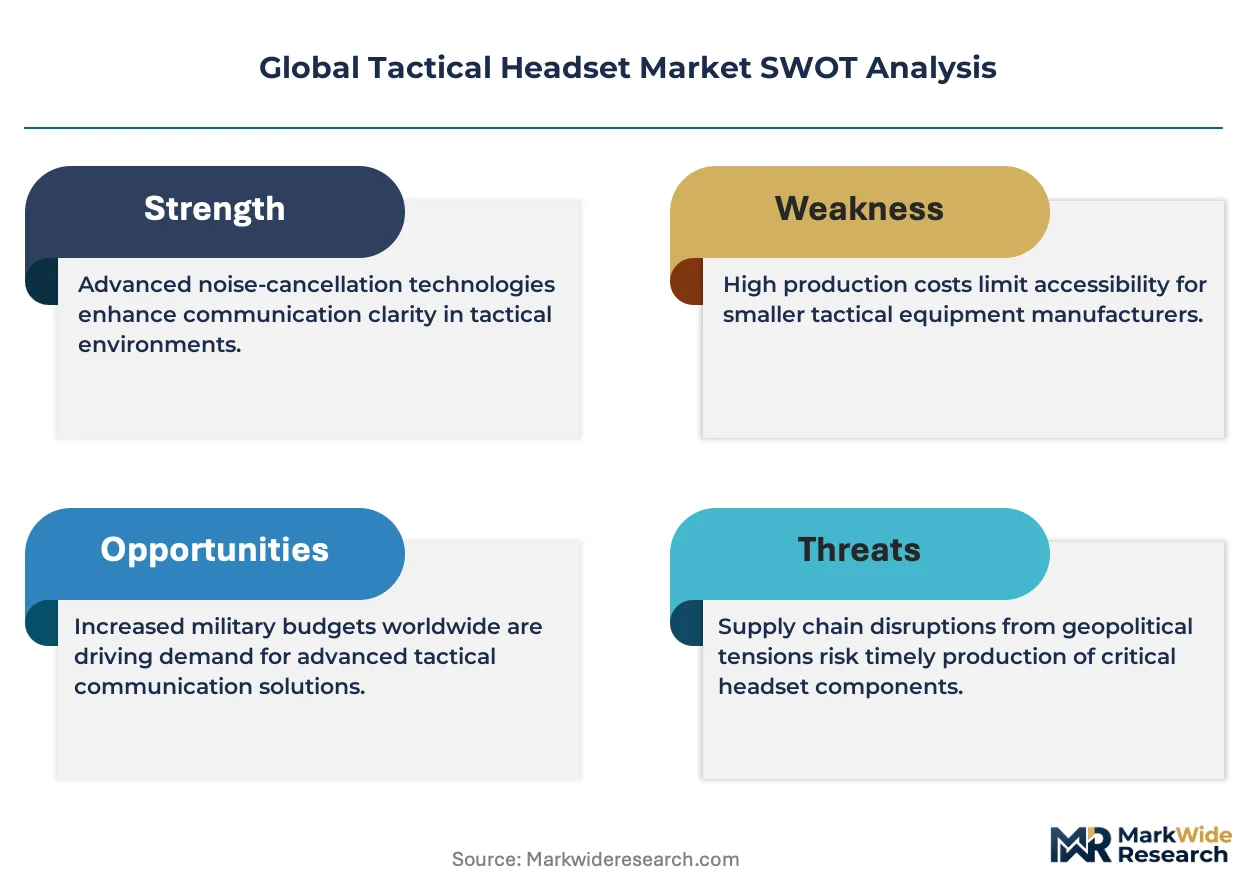
Modular headset configurations that separate the core audio processing unit from swappable earmuffs and boom microphones is pivoting procurement patterns across defense and security agencies. TEA Headsets leverages deep specialization in military communication systems to sustain long-term contracts with U.S. special operations units. INVISIO anchors its position through in-house bone conduction technology that dominates submarine and diving applications where traditional speakers fail. Bose competes on acoustic engineering heritage, extending its consumer audio R&D into tactical products with active noise reduction calibrated for gunfire impulse protection.
Tactical headsets integrate electret or dynamic microphones, sound localization sensors, and digital signal processors into hearing protection devices designed to preserve situational awareness while blocking hazardous acoustic impulses above 140 decibels. Noise-canceling product types lead procurement volumes due to mandatory hearing conservation mandates across military branches, while wireless technology segments capture the fastest expansion as forces replace cable-tethered systems with encrypted radio-linked configurations. The law enforcement end-user segment remains mature with stable replacement cycles, though margin pools concentrate in military applications where dual-channel digital architectures command premium positioning.
FCC equipment authorization rules govern tactical headset radio interfaces sold into U.S. agencies, while the EU's Radio Equipment Directive and CE marking requirements shape market access for European defense procurement. ISO 4869 acoustic testing standards and MIL-STD-810 environmental qualification protocols define minimum performance thresholds that filter out uncertified suppliers. Stakeholders must monitor how NATO's standardization agreements for soldier system interoperability reshape procurement specifications and determine which communication protocols achieve de facto adoption across allied forces.
Market Dynamics
Modular headset architectures are fragmenting supplier hierarchies as defense agencies unbundle audio processing cores from swappable earmuff and microphone subsystems, forcing incumbents to defend integration value against specialized component vendors.
Growth Catalysts
- MIL-STD-810 qualification mandates:U.S. Department of Defense environmental testing protocols now require thermal shock and humidity resistance for all field-deployed hearing protection, filtering out uncertified suppliers and consolidating procurement toward qualified vendors.
- Special Operations Command equipment refresh cycles:Tier-one special forces units across NATO member states are replacing legacy cable-tethered systems with encrypted radio-linked configurations, creating pull-through demand for compatible headset interfaces.
- Bone conduction transducer miniaturization:Advances in piezoelectric materials enable clear speech transmission through jawbone vibration without ear canal occlusion, opening submarine and diving applications where traditional acoustic drivers fail.
Market Restraints
- Neodymium magnet supply concentration:Rare-earth element processing for high-performance headphone drivers clusters in China's Jiangxi and Inner Mongolia provinces, exposing Western defense contractors to export control volatility and forced technology transfer risks.
- Dual-use export classification friction:U.S. International Traffic in Arms Regulations and EU dual-use goods controls impose licensing delays on tactical headsets with integrated encryption, extending sales cycles by 8-14 months for international customers.
- Electromagnetic compatibility testing costs:CE marking under the EU's Radio Equipment Directive requires third-party assessment of spurious emissions and immunity, adding certification expenses that disproportionately burden smaller suppliers.
Strategic Opportunities
- Indian defense modernization programs:The Ministry of Defence's negative import lists and Make in India procurement preferences create openings for local assembly partnerships serving army and paramilitary hearing protection requirements.
- Urban law enforcement wireless migration:Police departments in Germany, France, and the United Kingdom are replacing analog radio tethering with Bluetooth Low Energy and LTE-based push-to-talk, demanding interoperable headset ecosystems.
- ISO 4869-2 acoustic testing harmonization:Converging international standards for sound attenuation measurement reduce retesting burdens for multi-jurisdictional vendors and accelerate cross-border certification.
Industry Challenges
- Digital signal processing firmware talent scarcity:Real-time audio algorithm development for gunfire impulse detection and environmental noise suppression requires specialized acoustic engineering skills concentrated in Boston, Munich, and Tokyo metro areas.
- Legacy radio interface integration complexity:Defense forces maintain decades-old SINCGARS and HAVE QUICK encrypted voice systems, forcing headset manufacturers to maintain backward compatibility with obsolete connector standards and voltage levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tactical Headset Market |
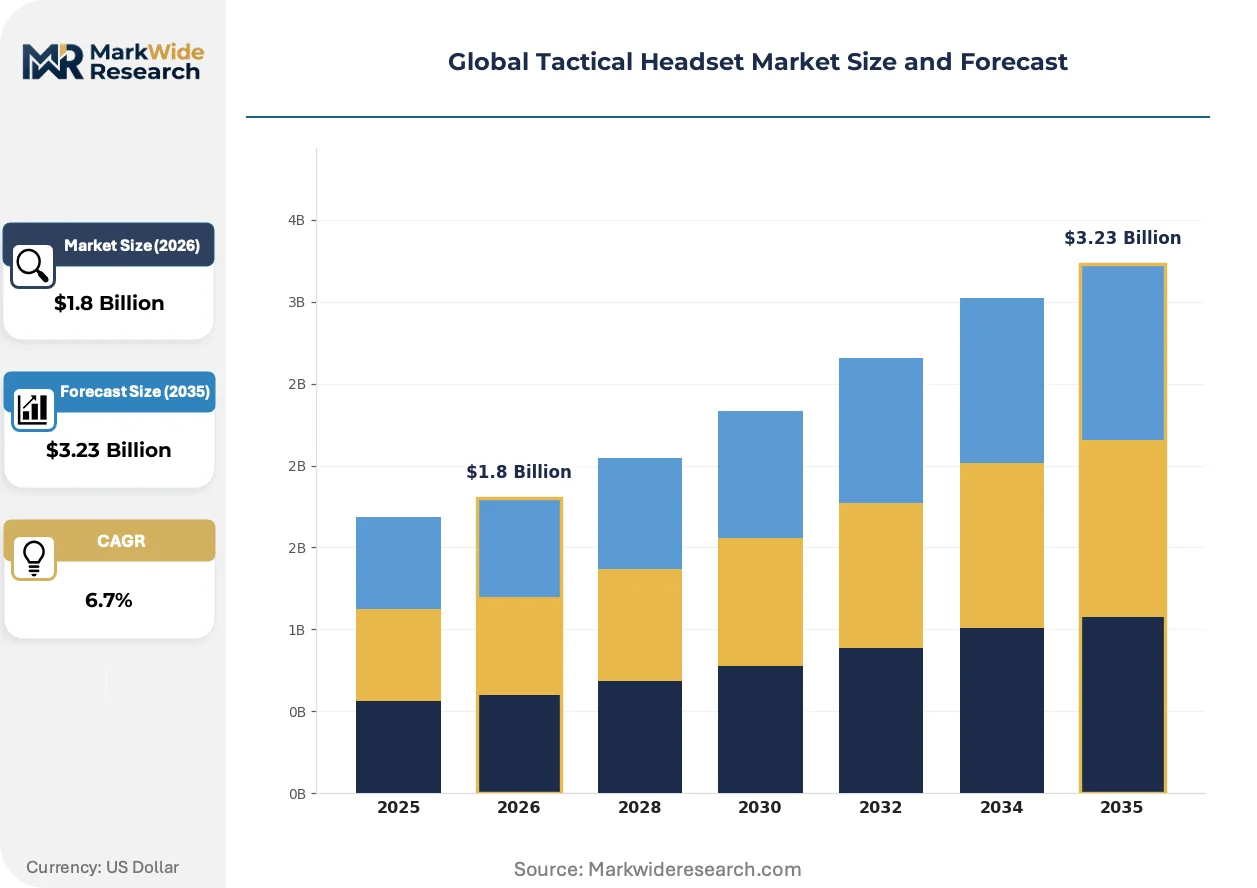
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Noise-Canceling, Communication, Directional Microphone, Bluetooth End User: Military, Law Enforcement, Security Personnel, Emergency Services Technology: Wireless, Analog, Digital, Hybrid Application: Tactical Operations, Training Exercises, Surveillance, Combat |
| Companies Covered | Safariland, TEA Headsets, 3M, Cobham, Honeywell International, INVISIO, Bose, Saab Group, David Clark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tactical Headset Market Strategic Shifts
Active noise reduction calibrated for impulse protection is displacing passive earmuff designs across military procurement, while wireless encryption protocols and AI-enhanced sound localization reshape how forces maintain situational awareness in contested electromagnetic environments.
Bone conduction technology is converging with submersible pressure vessel engineering to enable reliable underwater communication without compromising diver hearing protection. Naval special warfare units in the United States, United Kingdom, and Australia are field-testing integrated dive-mask systems that transmit through cheekbone vibration. This convergence is compressing the addressable market for conventional waterproof loudspeakers in maritime defense applications.
REACH substance restrictions and RoHS lead-free soldering mandates are forcing redesigns of printed circuit assemblies in headsets sold into European defense procurement. The European Chemicals Agency's candidate list of substances of very high concern now targets specific phthalates used in cable jacketing, compelling suppliers to qualify halogen-free alternatives. German and French prime contractors are responding by inserting green chemistry compliance clauses into tier-two supplier contracts.
Defense agencies are consolidating vendor relationships through multi-year enterprise agreements that bundle headset procurement with maintenance, training, and technology refresh guarantees. The United Kingdom's Ministry of Defence and Sweden's FMV procurement agency have shifted from transactional purchasing to performance-based contracts covering entire soldier system portfolios. This reconfiguration concentrates volume with integrators capable of delivering lifecycle support across dismounted soldier programs.
Global Tactical Headset Market Segmentation
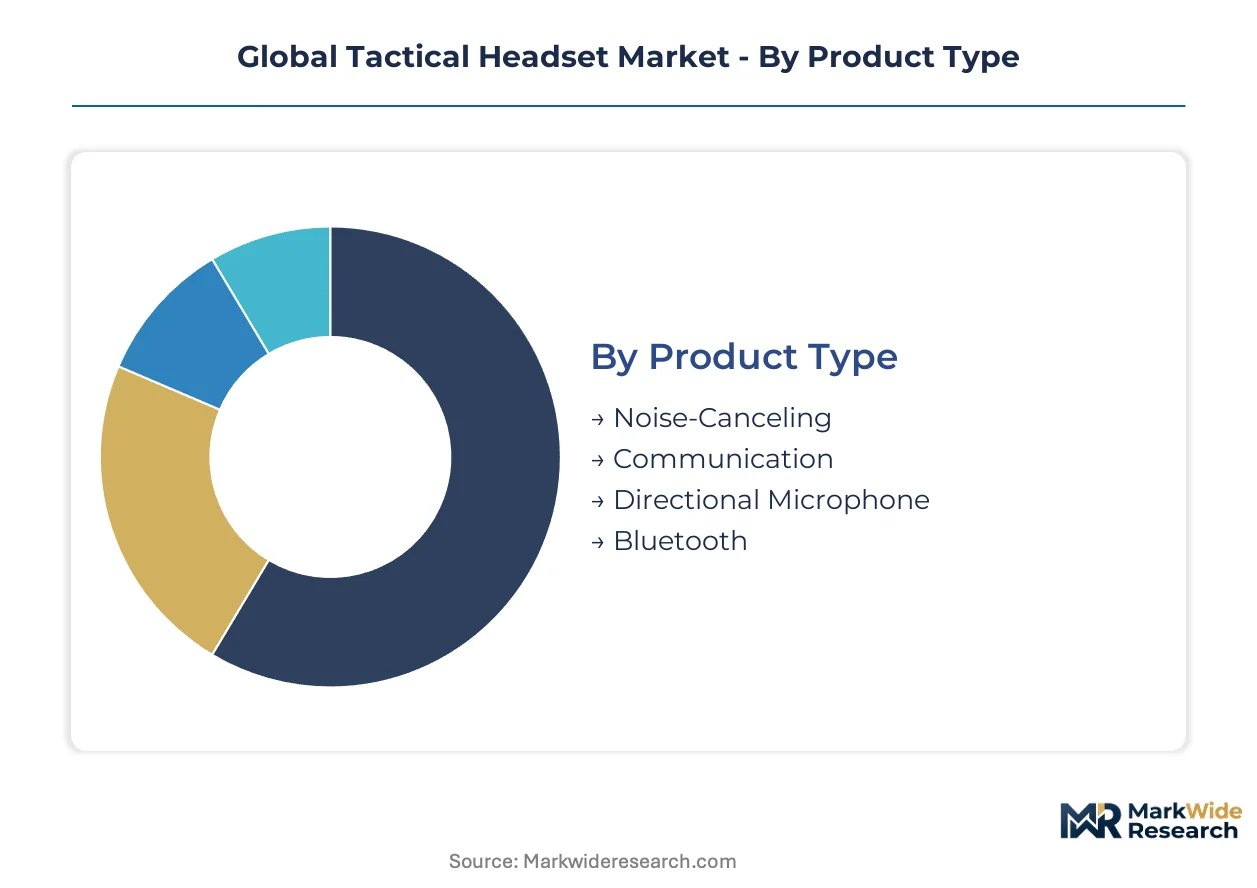
Tactical headset procurement divides sharply across certification regimes, with MIL-STD-810 and CE marking requirements filtering supplier participation differently by product architecture. Understanding these segment boundaries clarifies where margin pools concentrate versus where commodification pressures dominate.
Product Type:
Noise-canceling configurations require FCC equipment authorization for radio interfaces sold into U.S. agencies, while CE marking under the EU's Radio Equipment Directive governs European defense procurement access.
- Noise-Canceling:Active noise reduction systems integrate digital signal processors calibrated for gunfire impulse protection above 140 decibels. U.S. Department of Defense modernization initiatives and NATO hearing conservation mandates concentrate procurement volume here, with dual-channel architectures commanding premium positioning.
- Communication:Multi-band radio-linked headsets incorporate encrypted voice protocols compatible with SINCGARS and HAVE QUICK legacy systems. Special Operations Command equipment refresh cycles across NATO member states pull demand toward software-definable radio interfaces.
- Directional Microphone:Sound localization sensors preserve situational awareness in contested electromagnetic environments. These units face ISO 4869-2 acoustic testing harmonization requirements for cross-border certification.
- Bluetooth:Short-range wireless configurations enable tether-free mobility for urban law enforcement patrol units. German, French, and British police departments are migrating toward Bluetooth Low Energy ecosystems.
Leading the category by volume: Noise-Canceling. Expanding most quickly: Bluetooth as analog radio tethering phases out.
End User:
Defense procurement operates on multi-year enterprise agreements bundling lifecycle support, while security and emergency segments transact on shorter replacement cycles with lower integration complexity.
- Military:Integrated hearing protection and communication systems serve dismounted soldier programs across NATO standardization agreements. Bone conduction variants dominate submarine and diving applications where traditional acoustic drivers fail.
- Law Enforcement:Stable replacement cycles characterize mature procurement in Germany, France, and the United Kingdom. Margin compression here contrasts with military premium positioning.
- Security Personnel:Private sector demand concentrates in executive protection and critical infrastructure guarding. These users prioritize discreet form factors over battlefield ruggedization.
- Emergency Services:Fire and rescue units require intrinsically safe certifications for hazardous atmosphere operations. Urban search and rescue teams drive demand for modular earmuff configurations.
Military procurement commands the steepest expansion trajectory. Law Enforcement delivers the most predictable replacement revenue.
Technology:
Wireless segments absorb disproportionate firmware development investment, while analog and hybrid architectures maintain backward compatibility with decades-old radio infrastructure.
- Wireless:Encrypted radio-linked configurations replace cable-tethered systems across Tier-one special forces units. Electromagnetic compatibility testing under EU Radio Equipment Directive adds certification burden for smaller suppliers.
- Analog:Legacy connector standards and voltage levels persist in forces maintaining SINCGARS inventory. This segment contracts as digital migration accelerates.
- Digital:Dual-channel architectures with integrated DSP enable gunfire impulse detection and environmental noise suppression. Real-time audio algorithm talent concentrates in Boston, Munich, and Tokyo metro areas.
- Hybrid:Mixed-signal designs bridge analog radio infrastructure with digital processing cores. These configurations dominate transition-phase procurement during equipment refresh cycles.
Digital technology captures the fastest share gain. Analog faces steepest volume erosion.
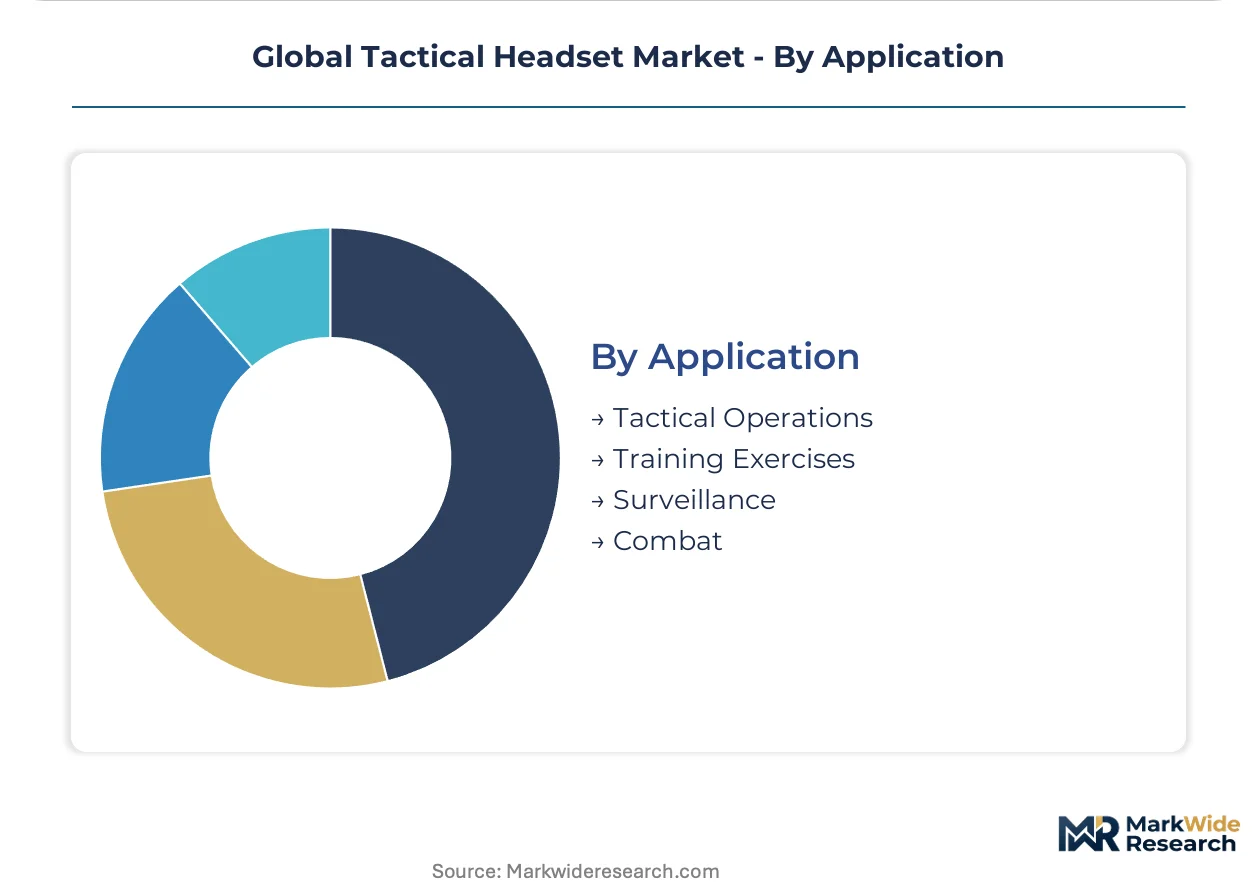
Application:
Tactical Operations and Combat applications demand full MIL-STD-810 environmental qualification, while Training Exercises and Surveillance accept reduced ruggedization tiers.
- Tactical Operations:Modular headset architectures separate audio processing cores from swappable earmuff subsystems. U.S. special operations units and British Ministry of Defence procurement favor this configurability.
- Training Exercises:Reduced-threat environments permit lighter passive earmuff designs. Volume here concentrates in domestic military training facilities and police academy programs.
- Surveillance:Covert audio collection requires miniature boom microphones and low-visibility profiles. Intelligence agency procurement drives specialized form factor development.
- Combat:Full-spectrum environmental qualification including thermal shock and humidity resistance filters out uncertified suppliers. Performance-based contracts from Sweden's FMV and UK Ministry of Defence consolidate volume with qualified integrators.
Combat applications lead by revenue concentration. Training Exercises show the shallowest growth slope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in defense industrial clusters across North America and Northern Europe, while consumption pulls from procurement programs spanning NATO member states and allied partner nations. Component sourcing for rare-earth magnets and acoustic transducers creates supply dependencies that shape regional competitive positioning.
United States
Department of Defense modernization initiatives and Special Operations Command equipment refresh cycles drive procurement volume. FCC equipment authorization rules govern radio interfaces sold into federal agencies. Boston metro area hosts concentrated DSP firmware development talent for real-time audio algorithms.
Germany
Bundeswehr hearing conservation mandates and NATO standardization agreements filter supplier participation toward qualified vendors. REACH substance restrictions and RoHS lead-free soldering mandates force PCB redesigns for European defense procurement. Bavaria anchors acoustic engineering clusters serving automotive and defense crossover applications.
United Kingdom
Ministry of Defence performance-based contracts bundle headset procurement with lifecycle support across dismounted soldier programs. CE marking under the EU's Radio Equipment Directive shapes market access despite post-Brexit regulatory divergence. Southeast England concentrates systems integration capabilities for special forces equipment.
France
DGA procurement preferences prioritize encrypted radio-linked configurations compatible with legacy SINCGARS infrastructure. ANSM and CNIL oversight extends to defense electronics certification where dual-use classifications apply. Auvergne-Rhône-Alpes region hosts specialized suppliers for bone conduction transducer miniaturization.
India
Ministry of Defence negative import lists and Make in India procurement preferences create openings for local assembly partnerships. BIS certification requirements and DGFT dual-use controls impose compliance layers on foreign suppliers. Maharashtra and Karnataka states develop defense electronics manufacturing corridors for army and paramilitary hearing protection.
Global Tactical Headset Market Competitive Environment
The competitive structure tilts toward specialized defense contractors with deep MIL-STD qualification heritage rather than diversified industrial conglomerates. Tier-one special forces procurement concentrates volume with vendors capable of delivering encrypted radio integration and environmental ruggedization. Three archetypes dominate: bone conduction specialists, active noise reduction engineers, and modular systems integrators. Consolidation pressure operates through multi-year enterprise agreements bundling maintenance and technology refresh guarantees, while smaller suppliers face disproportionate electromagnetic compatibility testing burdens.
Within the bone conduction and maritime specialization tier, INVISIO anchors positioning through in-house piezoelectric technology, while TEA Headsets occupies a position serving U.S. special operations units with modular configurations. Bose represents the acoustic engineering heritage archetype, extending consumer audio R&D into tactical products with calibrated impulse protection. These three exemplify how technical specialization in narrow domains—submersible pressure vessels, military communication protocols, or active noise reduction—sustains procurement relationships against generalized industrial competitors.
| Leading Market Players |
|---|
| Safariland |
| TEA Headsets |
| 3M |
| Cobham |
| Honeywell International |
| INVISIO |
| Bose |
| Saab Group |
| David Clark |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between MIL-STD-810 qualified systems and uncertified commercial alternatives manifests in both pricing power and supply chain configuration, with qualified vendors commanding premium positioning while rare-earth magnet concentration in China exposes Western contractors to input cost volatility.
Pricing Analysis
Margin tightening in law enforcement tiers traces to stable replacement cycles and procurement commoditization, while military applications sustain premium positioning through dual-channel digital architectures. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Cost compression in Bluetooth-enabled configurations accelerates because police departments in Germany, France, and the United Kingdom migrate toward interoperable wireless ecosystems. Security personnel segments show highest price sensitivity, prioritizing discreet form factors over battlefield ruggedization.
Supply Chain Analysis
Single-source vulnerability sits with China's Jiangxi and Inner Mongolia provinces for neodymium magnet processing, exposing Western defense contractors to export control volatility. Component sourcing draws from Taiwan for semiconductor fabrication, Japan for piezoelectric materials, and the United States for DSP firmware development. Forced technology transfer risks and tariff exposure concentrate in rare-earth element supply chains. Distribution runs through prime defense contractors bundling headset procurement with lifecycle support across dismounted soldier programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tightened MIL-STD-810 qualification mandates filter supplier participation toward certified vendors, constraining effective capacity and propping pricing power for qualified incumbents.
For Market Incumbents: Anticipate modular architecture unbundling by defending integration value through encrypted radio protocol expertise and multi-year enterprise agreements. Counter specialized component vendors by deepening backward integration into bone conduction transducer production and DSP firmware development. Channel control through direct relationships with Special Operations Command procurement offices remains critical. For New Entrants and Emerging Players: Direct-to-defense procurement platforms offer lower-friction entry paths than prime contractor channels, particularly for Indian defense modernization programs under Make in India preferences. Urban law enforcement wireless migration presents the most penetrable segment, with Bluetooth Low Energy ecosystem gaps in German and French police departments. Target modular earmuff subsystem supply to qualified integrators lacking in-house acoustic engineering. For Investors and Strategic Acquirers: Re-rating potential sits with bone conduction specialists given submarine and diving application expansion where traditional acoustic drivers fail. Long-term viability favors vendors with captive piezoelectric technology and submersible pressure vessel engineering. Monitor NATO standardization agreement progress for soldier system interoperability as inflection indicator for protocol adoption winners.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810 Qualification Investment | Filters uncertified competitors from U.S. Department of Defense procurement pools. |
| Backward Integration into Rare-Earth Magnet Supply | Reduces exposure to China's Jiangxi province export control volatility. |
| Encrypted Radio Protocol Development | Enables compatibility with SINCGARS and HAVE QUICK legacy systems. |
| Local Assembly Partnership in India | Aligns with Ministry of Defence negative import lists and Make in India preferences. |
| Halogen-Free Cable Jacketing Redesign | Addresses ECHA candidate list restrictions on phthalates for European defense procurement. |
Study Parameters
Document review covered defense procurement databases, FCC equipment authorization filings, and EU Radio Equipment Directive certification records, complemented by interviews with program managers at Special Operations Command, Bundeswehr procurement officers, and acoustic engineering directors at prime contractors. Secondary sources included NATO standardization agreement documentation, ISO 4869 acoustic testing protocols, and customs data on rare-earth element trade flows. Bottom-up vendor revenue estimates triangulated against top-down defense budget allocation analysis.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through structured modeling over the projection horizon. CAGRs derived from historical procurement cycle analysis and equipment refresh timing patterns. Key inputs included Special Operations Command modernization schedules, EU hearing conservation mandate implementation timelines, and bone conduction transducer miniaturization cost curves.
The model holds under stable NATO procurement coordination and continued rare-earth supply chain access; deviation in export control enforcement or electromagnetic compatibility testing burden shifts would revise volume trajectories. Forecasts reflect documented assumptions regarding equipment refresh cycle timing and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
High Frequency Military Communications Market