
 Middle East and North Africa Perforating Gun Market | 2026-2036
Middle East and North Africa Perforating Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and North Africa Perforating Gun Market Foresight
Shaped charge liner metallurgy is tilting toward higher-density powdered composites for deeper penetration in carbonate reservoirs. Weatherford International plc leverages integrated manufacturing to control liner supply chains across North African operations. NOV Inc anchors its position through coiled tubing perforating systems designed for extended-reach laterals in Saudi Arabia's unconventional plays. Schlumberger Ltd differentiates via real-time downhole telemetry that correlates shot timing with reservoir stress profiles.
A perforating gun is a specialized downhole tool assembly housing explosive shaped charges arranged to create controlled perforations in well casing, cement sheath, and formation rock; typical specifications include charge densities of 4 to 12 shots per foot and detonation pressures exceeding 200,000 psi to establish hydraulic communication between the wellbore and productive zone. Wireline-deployed guns retain dominant share in workover and recompletion campaigns across mature Egyptian fields, while tubing-conveyed systems capture expanding share in high-pressure high-temperature offshore completions where mechanical reliability overrides deployment speed. Hydraulic firing technology leads the technology split in conventional sandstone reservoirs, though hybrid electro-hydraulic systems are gaining traction in deep gas wells requiring precision depth correlation.
ADNOC's in-country value program and Saudi Aramco's IKTVA localization mandate reshape procurement criteria, requiring foreign suppliers to establish domestic manufacturing or joint ventures to maintain market access. Egypt's petroleum regulator enforces API RP 67 testing protocols for explosive tool integrity, while the UAE's civil defense authority governs transport and storage of shaped charge assemblies through port facilities. Stakeholders must weigh localization commitments against technology transfer limits when selecting partnership structures for long-term service contracts.
Market Dynamics
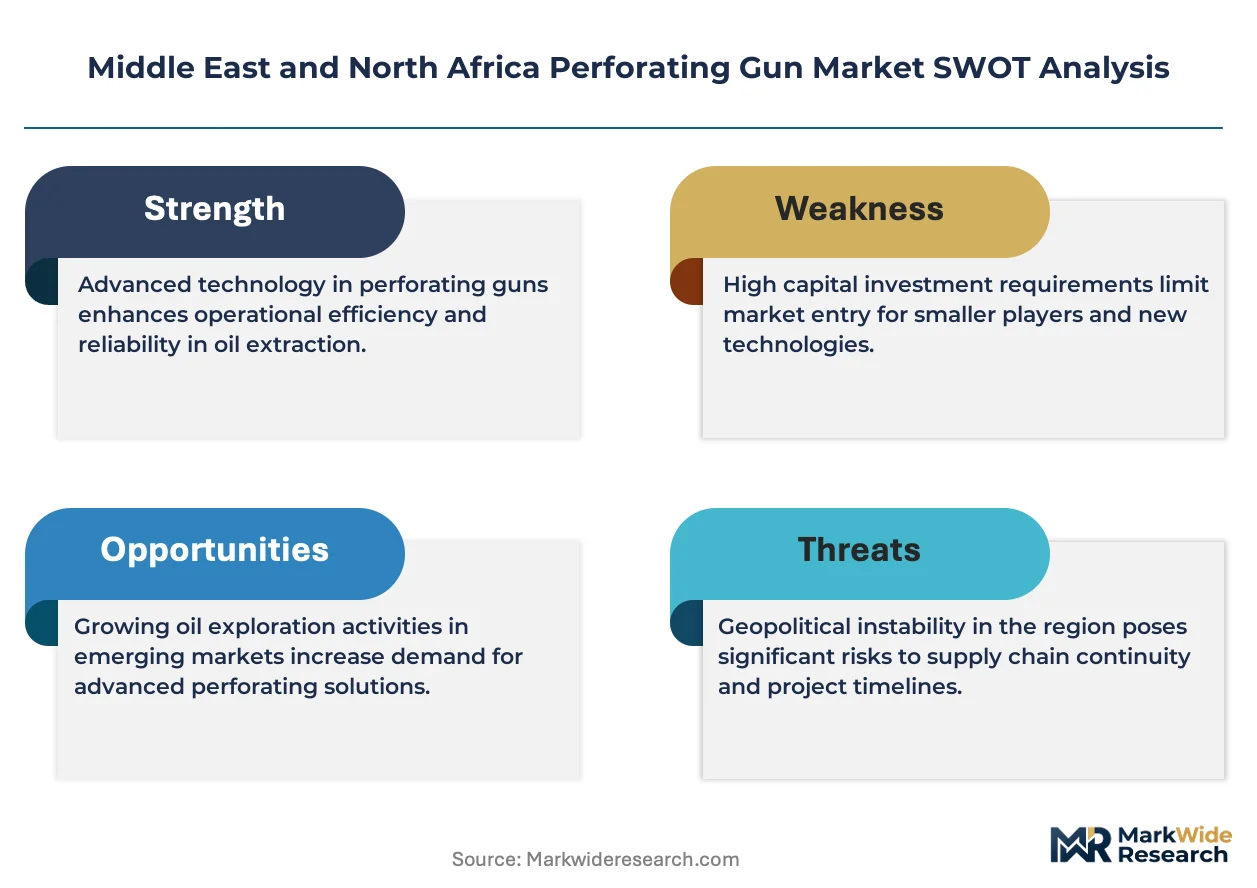
Localization mandates under Saudi Arabia's IKTVA program and ADNOC's in-country value requirements are restructuring supplier relationships, forcing foreign perforating gun manufacturers to surrender equity stakes in domestic joint ventures or forfeit long-term service contracts in the Gulf's largest offshore fields.
Growth Catalysts
- Deep Gas Development:The UAE's sour gas expansion at Shah and Hail fields drives demand for high-temperature perforating systems rated above 400°F. Operators specify tubing-conveyed guns with redundant firing mechanisms for these corrosive environments.
- Vision 2030 Localization:Saudi Aramco's domestic content thresholds redirect procurement toward Riyadh-based manufacturing partnerships. Foreign suppliers must transfer explosive charge assembly technology to maintain market access.
- Hydraulic Fracturing Adoption:Saudi Arabia's unconventional Jafurah basin development creates pull for extended-reach perforating configurations. Cluster spacing optimization requires precise depth correlation systems.
Market Restraints
- Explosive Raw Material Concentration:RDX and HMX precursor supply concentrates in a limited number of chemical processing facilities outside the Middle East. Freight costs and customs clearance timelines create input volatility for shaped charge manufacturers.
- API RP 67 Compliance Burden:Egypt's petroleum regulator mandates third-party destructive testing for every perforating gun batch. Certification delays extend lead times by 6-8 weeks for operators working the Western Desert.
- Wireline System Saturation:Mature Egyptian fields retain legacy cased-hole wireline infrastructure. Tubing-conveyed system penetration remains structurally capped where recompletion budgets prioritize speed over mechanical reliability.
Strategic Opportunities
- Libya Field Rehabilitation:Underinvested Sirte Basin assets require extensive perforating gun deployment as NOC restores pre-conflict production levels. Security-cleared service partnerships unlock this stranded demand.
- Real-Time Telemetry Integration:Downhole pressure monitoring during perforation events enables dynamic shot timing optimization. Convergence of MEMS sensors with wireless telemetry creates premium pricing tiers.
- Kuwait Heavy Oil Thermal Projects:Steam-assisted gravity drainage installations at Lower Fars field demand thermally stable charge carriers. Specialized gun metallurgy for cyclic steam injection represents an untapped specification niche.
Industry Challenges
- Shaped Charge Engineer Scarcity:Metallurgical expertise for powdered composite liner design concentrates among a handful of specialists. Training pipelines fail to match retirement rates in North African operations centers.
- Dual-Use Export Classification:Perforating charges fall under munitions licensing protocols. Bureaucratic review timelines for cross-border equipment transfers disrupt just-in-time logistics for Algerian Sahara drilling campaigns.
- Legacy Gun Compatibility:Older wellbore architectures in Egypt's Gulf of Suez constrain charge carrier diameter. Retrofit engineering costs erode margins on recompletion contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and North Africa Perforating Gun Market |
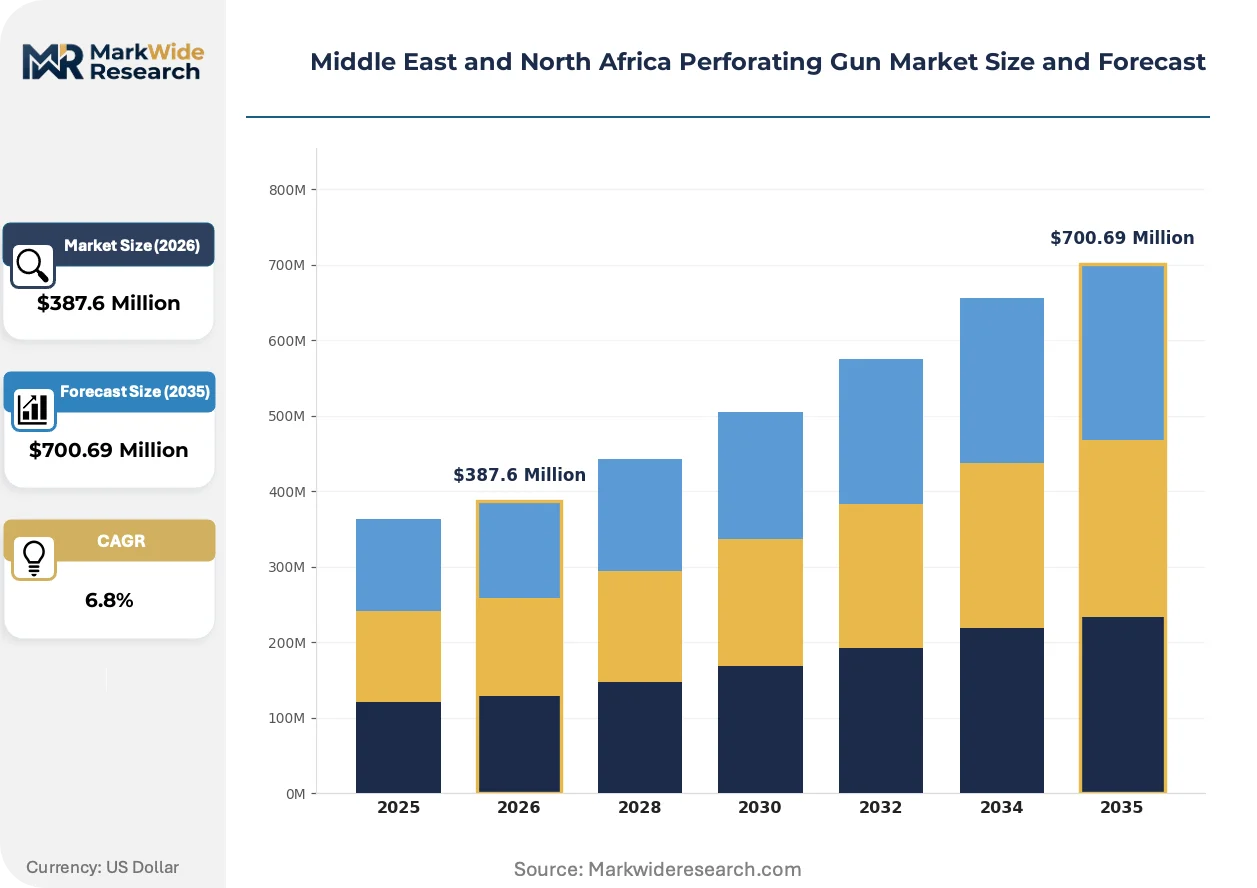
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wireline, Tubing conveyed, Coiled tubing, Others Application: Oil Extraction, Gas Extraction, Well Completion, Enhancing Production Technology: Hydraulic, Mechanical, Electrical, Hybrid End User: Onshore Operators, Offshore Operators, Service Companies, Independents |
| Companies Covered | Weatherford International plc, NOV Inc, Schlumberger Ltd, Sinopec Oilfield Service, ADNOC Drilling, Halliburton Company, Hunting plc, Yellow Jacket Oil Tools, Baker Hughes Co, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and North Africa Perforating Gun Market Shifts & Advancements
Downhole telemetry integration and shaped charge material science are compressing deployment risk while extending perforation effectiveness in carbonate formations. These shifts favor suppliers with captive manufacturing control over liner metallurgy.
Powdered composite liners incorporating tungsten-copper blends are rendering obsolete traditional copper cone geometries in deep carbonate targets. ADNOC's offshore sour gas operators specify these configurations for enhanced penetration in tight dolomite reservoirs. The technology compresses perforation tunnel length variance from 15% to under 5%.
Saudi Aramco's IKTVA localization framework now mandates 70% domestic value-add for perforating gun assemblies. The policy forces explosive charge loading operations into kingdom-based joint ventures. European and North American suppliers transfer liner pressing technology to Riyadh facilities or surrender preferred vendor status.
Integrated service contracting is displacing equipment rental models in high-pressure offshore completions. Operators bundle perforating guns with reservoir characterization and post-frac evaluation into single-vendor agreements. Abu Dhabi's Upper Zakum expansion exemplifies this consolidation, where ADNOC awards 10-year integrated services contracts to qualified consortiums.
Middle East and North Africa Perforating Gun Market Segmentation
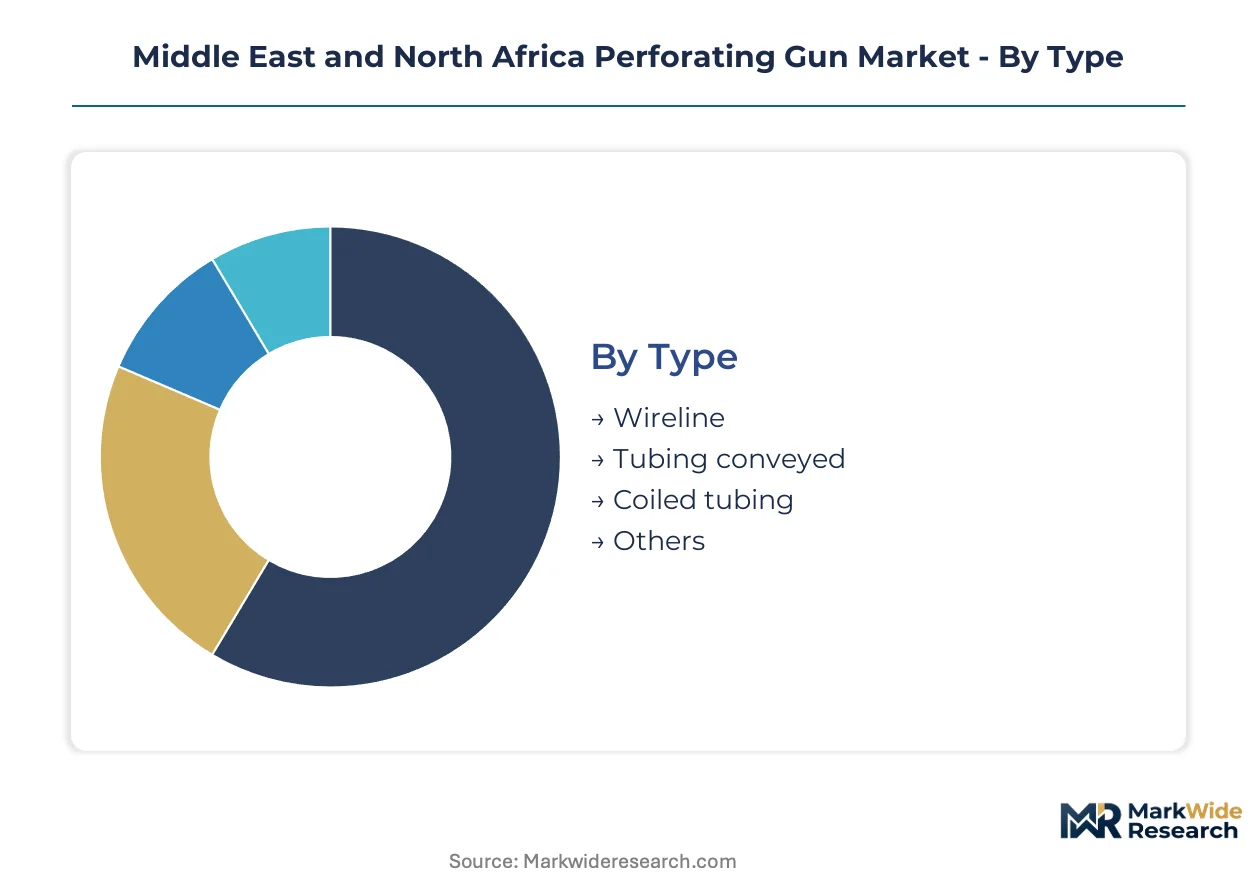
Deployment method, reservoir application, firing mechanism, and operator type each impose distinct engineering requirements on perforating gun specifications. Procurement patterns diverge sharply across these dimensions, with high-pressure offshore environments demanding redundant mechanical systems while mature onshore fields prioritize wireline speed.
Type:
Deployment configuration dictates pressure rating, depth correlation precision, and firing redundancy architecture.
- Wireline:Surface-deployed electric cable systems enable rapid deployment in cased-hole completions with real-time depth correlation. Egyptian Western Desert operators retain these systems for recompletion campaigns where mechanical simplicity outweighs pressure tolerance.
- Tubing conveyed:Gun assemblies run on production tubing withstand differential pressures exceeding 15,000 psi with redundant firing mechanisms. ADNOC's Upper Zakum offshore expansion specifies these configurations for high-temperature sour gas wells where wireline fatigue risks unacceptable.
- Coiled tubing:Continuous reel deployment enables live-well perforation in underbalanced conditions. Saudi Arabia's unconventional Jafurah basin pilots these systems for extended-reach laterals where conventional tubing constraints limit reach.
- Others:Through-tubing and pump-down systems address niche deployment geometries in slim-hole completions.
Wireline commands the established base. The steepest expansion runs through tubing conveyed systems.
Application:
Reservoir objective shapes charge density, phasing geometry, and penetration depth specifications.
- Oil Extraction:Perforating configurations optimize tunnel length in sandstone reservoirs with 6 to 12 shots per foot. Saudi Arabia's mature onshore fields drive steady replacement demand for these standard specifications.
- Gas Extraction:Deep carbonate targets require powdered composite liners with tungsten-copper blends achieving penetration depths exceeding 36 inches. The UAE's Shah sour gas development anchors this specification tier.
- Well Completion:Initial perforation events demand precise correlation with formation tops and stress profiles. Integrated telemetry systems command premium positioning in Abu Dhabi offshore contracts.
- Enhancing Production:Reperforation and stimulation access campaigns retrofit existing wellbores with oriented charge phasing. Libya's Sirte Basin rehabilitation creates intermittent demand spikes.
Oil extraction retains volume leadership. Gas extraction climbs the fastest as sour gas developments accelerate.
Technology:
Firing mechanism selection balances detonation precision against wellbore complexity and regulatory constraints.
- Hydraulic:Pressure-actuated firing heads dominate conventional sandstone completions with proven reliability across temperature ranges. Egyptian regulators mandate these systems for API RP 67 compliance simplicity.
- Mechanical:Drop-bar and pressure-delay mechanisms serve as backup redundancy in tubing-conveyed assemblies. Offshore operators in Saudi Arabia's Manifa field specify dual-mechanical failsafes.
- Electrical:Surface-controlled firing enables selective shot activation and real-time diagnostics. Kuwait's Lower Fars thermal projects pilot these systems for steam injection synchronization.
- Hybrid:Electro-hydraulic architectures combine surface command with downhole pressure amplification. Deep gas wells in the UAE's Hail field adopt these for precision depth correlation beyond 20,000 feet.
Hydraulic systems anchor the installed base. Hybrid configurations gain share fastest in high-specification offshore contracts.
End User:
Procurement authority and technical capability determine specification complexity and service bundling preferences.
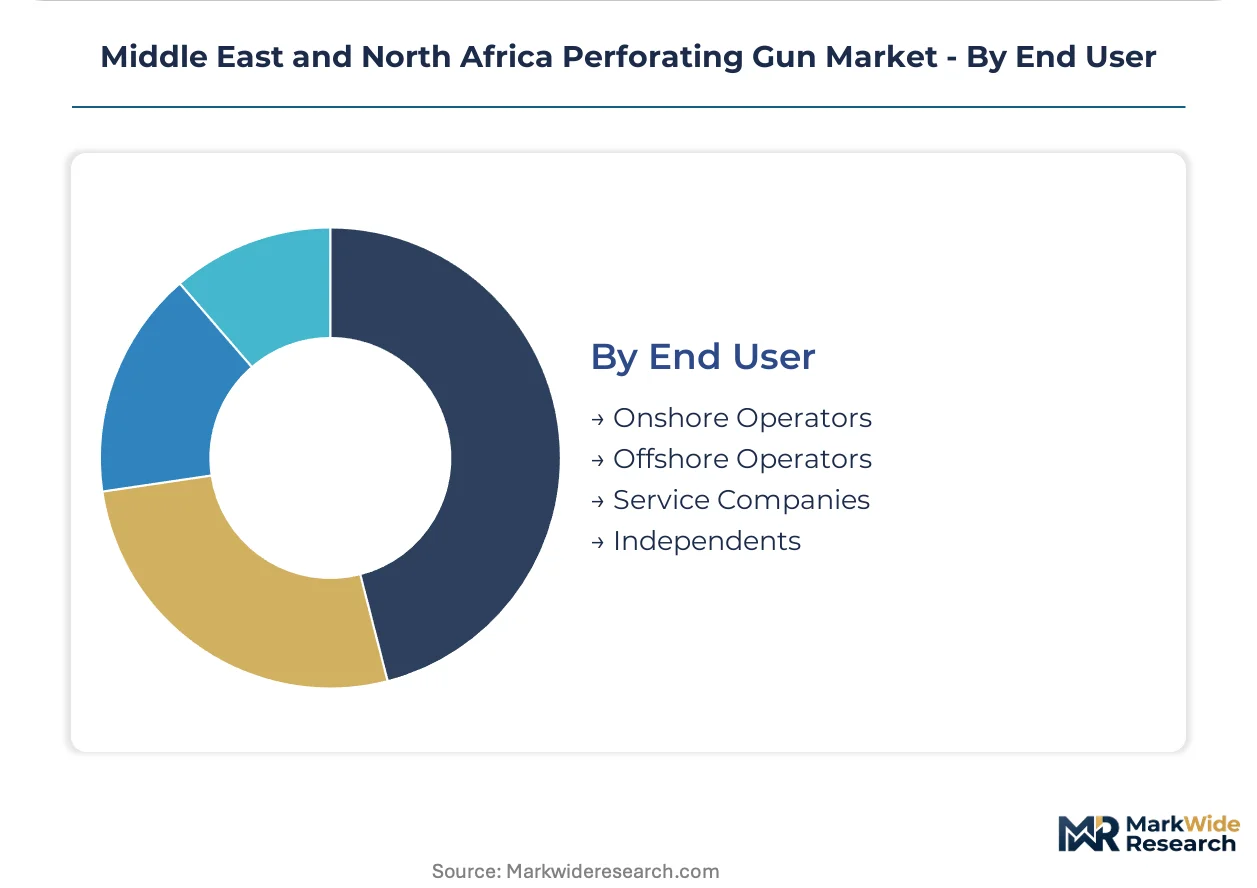
- Onshore Operators:National oil companies with mature field portfolios prioritize unit economics and localization compliance. Saudi Aramco's IKTVA mandates reshape supplier relationships for this cohort.
- Offshore Operators:High-pressure completion environments demand integrated service contracts bundling perforating with reservoir evaluation. ADNOC's 10-year Upper Zakum awards exemplify this procurement model.
- Service Companies:Rental-focused providers maintain wireline gun inventories for spot market workover demand. Egyptian independents rely on these intermediaries for Western Desert campaigns.
- Independents:Capital-constrained explorers favor standardized perforating specifications with minimal customization. Libya's post-conflict entrants represent this price-sensitive segment.
Onshore operators dominate procurement volume. Offshore operators expand most quickly as deep gas developments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based perforating gun manufacturers export tubing-conveyed systems to Saudi Arabia's Eastern Province and Kuwait's heavy oil fields. This trade corridor concentrates high-specification offshore technology flows toward national oil company procurement programs.
Saudi Arabia
Saudi Aramco's Jafurah unconventional gas development drives demand for extended-reach perforating configurations. The IKTVA localization mandate requires 70% domestic value-add for explosive charge assemblies. Riyadh-based manufacturing partnerships now host liner pressing technology transferred from European suppliers.
United Arab Emirates
ADNOC's Shah and Hail sour gas expansions specify perforating systems rated above 400°F with redundant firing mechanisms. The in-country value program reshapes procurement toward Abu Dhabi-based joint ventures. Upper Zakum offshore awards bundle perforating with reservoir evaluation in decade-long integrated contracts.
Egypt
Mature Western Desert fields sustain wireline gun demand for recompletion campaigns where speed outweighs mechanical redundancy. The petroleum regulator enforces API RP 67 testing protocols with third-party batch certification. Gulf of Suez operators face legacy wellbore diameter constraints that limit tubing-conveyed system adoption.
Kuwait
Lower Fars heavy oil thermal projects create demand for thermally stable charge carriers in steam-assisted gravity drainage installations. The national oil company pilots electrical firing systems for steam injection synchronization. Specialized gun metallurgy for cyclic thermal exposure represents an emerging specification niche.
Middle East and North Africa Perforating Gun Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service providers with captive manufacturing control over shaped charge liner metallurgy. Three strategic archetypes dominate: international oilfield service conglomerates with full technology stacks, regional joint ventures established under localization mandates, and specialized perforating system engineers. Competitive maneuvering centers on manufacturing joint venture formation and real-time telemetry capability acquisition.
Among the integrated service tier, Weatherford International plc, NOV Inc, and Schlumberger Ltd occupy anchor positions. Weatherford leverages controlled liner supply chains across North African operations. NOV anchors its presence through coiled tubing perforating system design. Schlumberger differentiates via downhole telemetry integration that correlates shot timing with reservoir stress profiles. These three exemplify the technology-transfer partnerships required under Saudi IKTVA and ADNOC in-country value frameworks.
| Leading Market Players |
|---|
| Weatherford International plc |
| NOV Inc |
| Schlumberger Ltd |
| Sinopec Oilfield Service |
| ADNOC Drilling |
| Halliburton Company |
| Hunting plc |
| Yellow Jacket Oil Tools |
| Baker Hughes Co |
| Others |
Supply & Pricing Matrix
Undercapacity in European RDX precursor production is compressing margins for shaped charge manufacturers while forcing Gulf operators to absorb freight premiums on explosive raw materials. This utilization squeeze simultaneously tightens supplier pricing power and accelerates localization investments across Saudi Arabia and the UAE.
Pricing Analysis
Next-generation powdered composite liner systems command substantial premiums over conventional copper cone geometries, while legacy wireline gun configurations face price erosion from oversupply in Egyptian spot markets. Three-tier pricing structure across premium telemetry-integrated, standard hydraulic-fired, and economy wireline tiers reflects certification grade differentiation and after-sales bundling intensity. Cost compression in the economy tier is intensifying because Egyptian independents prioritize speed over mechanical redundancy. National oil companies exhibit lowest price sensitivity due to integrated service contracting mandates, while Libyan post-conflict entrants represent the most price-sensitive buyer archetype.
Supply Chain Analysis
Upstream feedstock concentration for RDX and HMX precursors centers on chemical processing facilities in Germany, the United States, and China, creating extended lead times for Middle East manufacturers. Powdered metallurgy for tungsten-copper composite liners draws from specialty foundries in Germany and Japan, while steel charge carriers source from integrated mills in South Korea and Turkey. Single-source vulnerability in European explosive precursor supply creates disruption risk for just-in-time loading operations. Distribution runs through Abu Dhabi and Dammam port hubs serving ADNOC and Saudi Aramco procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Saudi Aramco's IKTVA consolidation and ADNOC's decade-long integrated service awards, fragmenting the supplier base into joint-venture-dependent service tiers.
For Market Incumbents: Harden manufacturing joint venture positions in Riyadh and Abu Dhabi through technology transfer commitments that satisfy localization thresholds. Secure captive liner pressing capacity to defend against emerging regional joint ventures that threaten preferred vendor status under Saudi Aramco procurement rules. For New Entrants and Emerging Players: Establish a beachhead in Libya's Sirte Basin rehabilitation segment where security-cleared partnerships remain undersupplied and NOC procurement prioritizes field restoration speed over established vendor relationships. Target Kuwait's Lower Fars thermal projects with specialized gun metallurgy for cyclic steam exposure as the most penetrable specification niche. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with decade-long ADNOC contracts bundling perforating with reservoir evaluation. Long-term viability hinges on telemetry integration capability and captive liner metallurgy control. Watch for inflection signals in Saudi Jafurah unconventional development acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Joint Venture Formation | IKTVA compliance secures preferred vendor status with Saudi Aramco procurement programs. |
| Powdered Composite Liner Technology Transfer | Tungsten-copper pressing capability unlocks premium positioning in UAE sour gas specifications. |
| Real-Time Telemetry Integration | MEMS sensor convergence enables dynamic shot timing optimization for ADNOC offshore contracts. |
| Security-Cleared Libya Partnership | Sirte Basin access captures stranded demand from post-conflict production restoration campaigns. |
| Thermal Stability Metallurgy Development | Cyclic steam injection specifications address Kuwait Lower Fars SAGD installation requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, national oil company procurement disclosures, and API RP 67 certification records. Interviews with perforating system engineers, explosives manufacturing directors, ADNOC and Saudi Aramco procurement leads, and Egyptian petroleum regulator officials provided operational validation. Secondary sources include SEC filings of listed oilfield service providers, OPEC production outlooks, and shaped charge patent filings. Bottom-up segment sizing triangulates against top-down national drilling activity forecasts.
Forecast inputs incorporate deployment method adoption curves, reservoir application mix shifts, and firing mechanism technology transitions across the analysis window. Segmentation dimensions modeled include gun type, reservoir objective, firing technology, and operator category with regional procurement policy overlays. CAGRs derive from elasticity-adjusted demand projections tied to Saudi Jafurah and UAE Shah-Hail development timelines. Explosive raw material cost trajectories and localization compliance thresholds inform price evolution assumptions.
Stress conditions across RDX supply disruption scenarios, IKTVA threshold modifications, and Libyan security environment volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about national oil company capital allocation priorities and joint venture technology transfer willingness. Cross-checking against Baker Hughes rig count data and national drilling permit issuances is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Artillery Ammunition Market