
 Middle East and Africa Ammunition Market | 2026-2036
Middle East and Africa Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ammunition Market Foresight
Defense procurement is decoupling from traditional Western supply chains as Gulf states prioritize indigenous manufacturing partnerships. Rheinmetall Denel Munition anchors regional large-caliber production through its South African facilities and joint ventures in the UAE. EDGE Group PJSC leverages Abu Dhabi-based vertical integration to compete across small and medium caliber segments for domestic and export contracts.
Ammunition encompasses complete rounds of firepower comprising projectile, propellant, primer, and casing engineered to precise chamber pressure and ballistic coefficient specifications for reliable weapon system function. Military application dominates regional value, with artillery and large caliber rounds commanding premium pricing due to limited qualified suppliers and extended certification cycles. Small caliber maintains volume leadership through sustained replenishment orders from defense forces and private security firms operating across conflict-affected zones.
Saudi Arabia's General Authority for Military Industries and South Africa's National Conventional Arms Control Committee impose divergent compliance frameworks that fragment market access protocols across the region. The UAE's Tawazun Council mandates offset requirements for foreign ammunition suppliers seeking defense contracts, redirecting procurement toward joint venture structures. Stakeholders must monitor localization threshold escalations and dual-use export control harmonization between Gulf and sub-Saharan regulatory regimes.
Market Dynamics
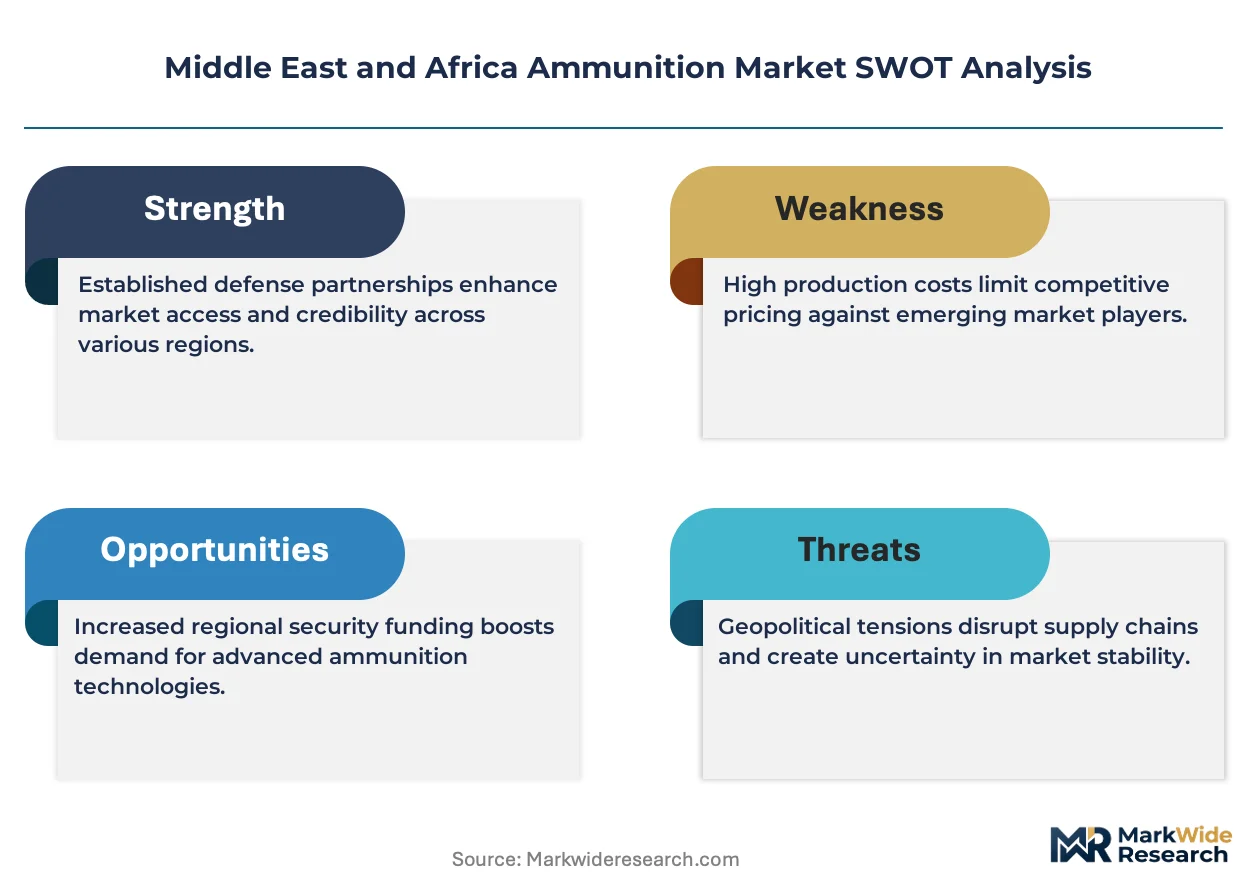
Localization mandates across Gulf Cooperation Council states are fragmenting established supply relationships, forcing foreign suppliers into joint venture structures with domestic entities to retain defense procurement access.
Growth Catalysts
- Armored Vehicle Modernization:Gulf defense forces are expanding procurement of medium and large caliber rounds to support fleet upgrades. This demand concentrates in Saudi Arabia and the United Arab Emirates under sovereign defense industrial strategies.
- REACH Compliance Divergence:South Africa's National Conventional Arms Control Committee tightens export permit requirements for munitions containing depleted uranium components. This regulatory friction redirects regional sourcing toward alternative material suppliers.
- Conflict-Zone Security Demand:Private security firms operating across sub-Saharan instability corridors sustain replenishment orders for small caliber ammunition. Volume leadership in this segment anchors manufacturing scale for regional producers.
Market Restraints
- Nitrocellulose Supply Concentration:Propellant precursor production clusters in Asian chemical processing hubs. Price volatility in this input compresses margin buffers for regional ammunition manufacturers.
- Extended Certification Cycles:Artillery and large caliber rounds require qualification timelines stretching across multiple defense procurement cycles. This technical limitation deters new market entrants.
- Dual-Use Export Control Fragmentation:Divergent compliance frameworks between Saudi Arabia's General Authority for Military Industries and South African regulators create administrative friction. Cross-border ammunition trade faces permit processing delays.
Strategic Opportunities
- Ethiopia Defense Reconstruction:Post-conflict security sector reform creates demand for standardized small and medium caliber procurement. Regional suppliers can establish early supplier relationships during institutional rebuilding.
- Tawazun Council Offset Mandates:The UAE's sovereign wealth vehicle mandates technology transfer and local production thresholds for foreign ammunition contractors. Joint venture structures unlock preferential contract access.
- Smart Munitions Convergence:Integration of guidance electronics with conventional explosive payloads creates premium product categories. Gulf defense budgets prioritize precision strike capabilities over dumb munitions.
Industry Challenges
- Ballistic Engineer Scarcity:Specialized expertise in propellant chemistry and terminal ballistics concentrates in legacy Western defense industrial bases. Regional training pipelines fail to replenish technical talent.
- Legacy System Integration:Indigenous ammunition production must achieve interoperability with NATO-standard and Eastern Bloc weapon platforms simultaneously. Dual certification requirements extend development timelines.
- Chamber Pressure Standardization:Inconsistent tolerance specifications across Gulf and sub-Saharan defense forces complicate mass production planning. Lot acceptance testing protocols vary by end-user.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ammunition Market |
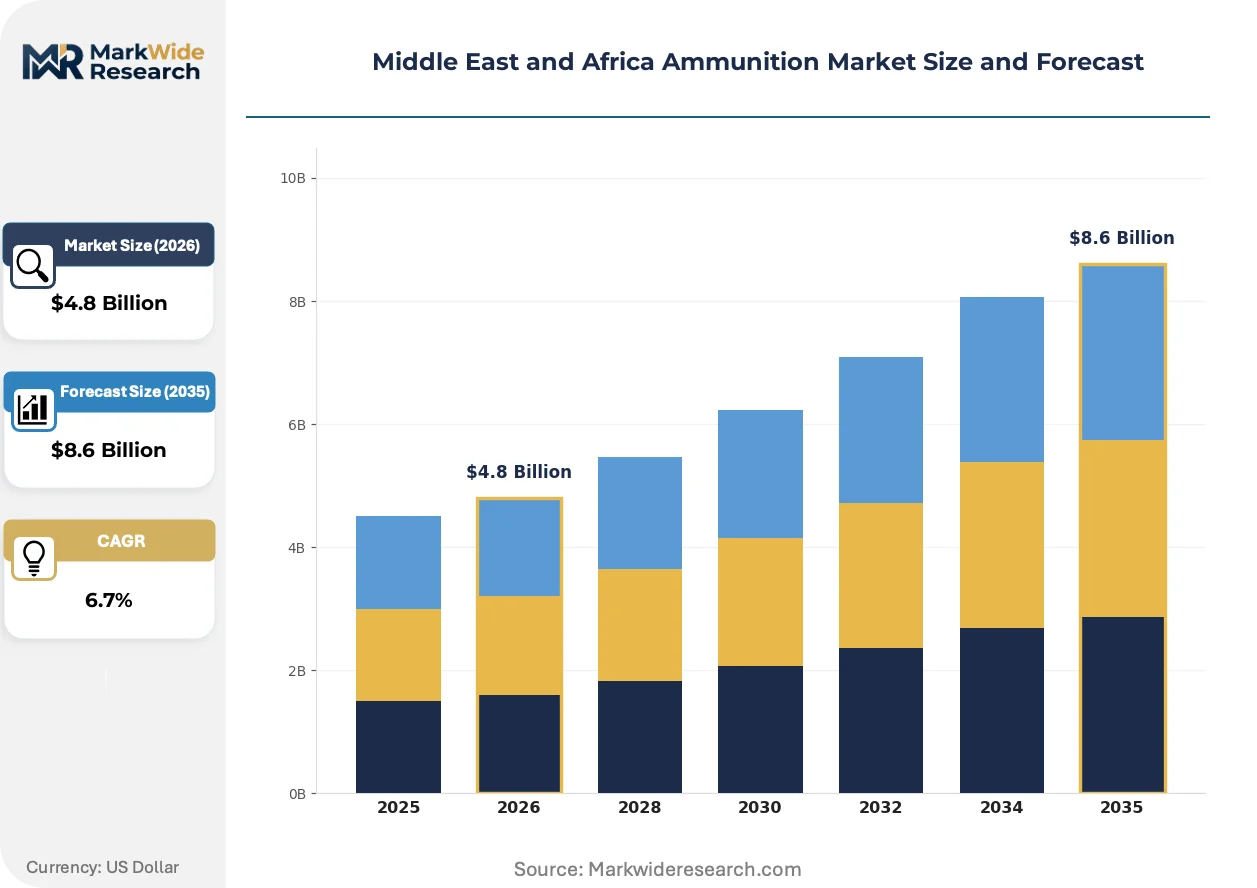
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Caliber, Medium Caliber, Large Caliber, Artillery Application: Military, Law Enforcement, Civil Defense, Sports Shooting End User: Defense Forces, Private Security Firms, Hunting Enthusiasts, Shooting Ranges Distribution Channel: Direct Sales, Wholesalers, Online Retail, Military Auctions |
| Companies Covered | Elbit Systems Ltd, Rheinmetall Denel Munition, EDGE Group PJSC, General Dynamics Corporation, Saudi Arabian Military Industries, BAE Systems plc, Denel PMP, Rheinmetall AG, Nexter Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ammunition Market Shifts & Advancements
Material substitution and digital manufacturing are compressing traditional production timelines while regulatory divergence forces suppliers to maintain parallel compliance systems across Gulf and sub-Saharan markets.
Polymer-cased ammunition is expanding into medium caliber applications previously dominated by brass and steel constructions. UAE-based defense contractors now specify composite casings for training rounds to reduce weight and corrosion. This technology is expanding into operational ammunition categories as Gulf forces prioritize logistics efficiency for expeditionary deployments.
The UAE's Tawazun Council now mandates domestic value-add thresholds for all defense procurement categories above specified contract values. Foreign ammunition suppliers must establish local manufacturing partnerships or forfeit eligibility. Large caliber artillery rounds face the steepest localization requirements, redirecting joint venture formation toward South African and European industrial partners.
Defense procurement across Saudi Arabia and the United Arab Emirates now bundles long-term ammunition supply with platform acquisition rather than treating consumables as separate line items. Original equipment manufacturers capture recurring revenue through captive ammunition provisioning. This consolidation is most visible in armored vehicle and artillery system contracts where lifecycle costing dominates evaluation criteria.
Middle East and Africa Ammunition Market Segmentation
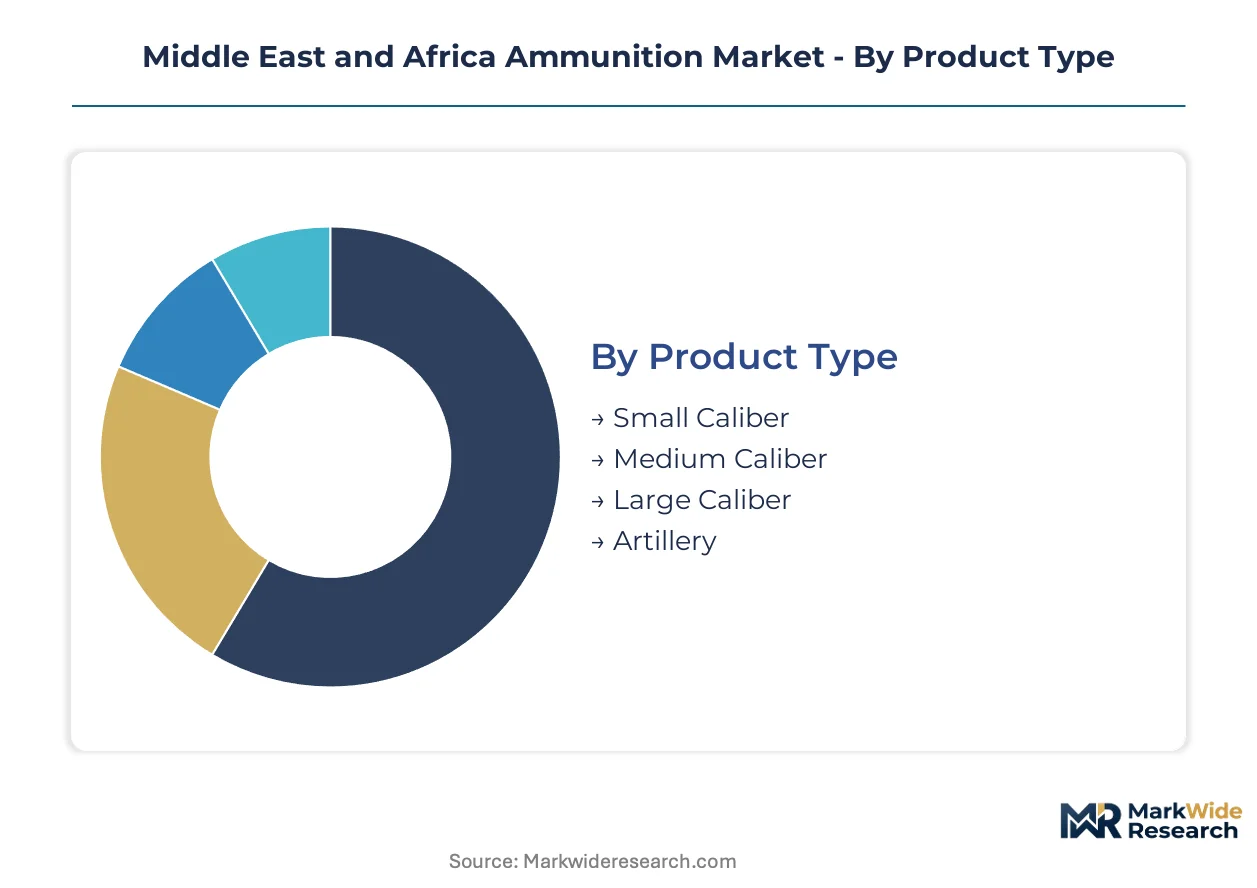
Ammunition procurement patterns across the Middle East and Africa diverge sharply by product scale and end-use authorization. Caliber classification determines manufacturing complexity, certification burden, and margin structure for regional suppliers.
Product Type:
Standalone munitions dominate procurement volumes, while embedded artillery systems require platform-integrated supply contracts.
- Small Caliber:Rounds up to 12.7mm encompassing rifle and pistol cartridges. Private security firms across sub-Saharan instability corridors sustain replenishment orders that anchor manufacturing scale for regional producers.
- Medium Caliber:Ranging 20-40mm for vehicle-mounted automatic cannons. Saudi Arabia and the United Arab Emirates drive demand through armored vehicle modernization programs under sovereign defense industrial strategies.
- Large Caliber:Tank and naval gun ammunition requiring specialized forging and propellant chemistry. South African facilities anchor regional production through joint ventures with European industrial partners.
- Artillery:Howitzer and mortar rounds with extended range and precision variants. Gulf defense budgets prioritize these capabilities, though limited qualified suppliers stretch certification timelines across multiple procurement cycles.
Small caliber leads volumes today; artillery is gaining share fastest.
Application:
Cost tier stratification separates sovereign defense procurement from commercial and recreational segments.
- Military:Combat and training ammunition for national defense forces. Saudi Arabia's General Authority for Military Industries and the UAE's Tawazun Council impose localization mandates that redirect sourcing toward joint venture structures.
- Law Enforcement:Standard issue and less-lethal rounds for police and border control agencies. Procurement concentrates through national interior ministries with preference for domestic suppliers where capacity exists.
- Civil Defense:Emergency response and perimeter security ammunition. Demand clusters in Gulf urban centers with integrated command and control infrastructure.
- Sports Shooting:Target and competition rounds for recreational markets. South African shooting ranges and UAE sporting clubs represent the primary addressable demand within the region.
Military commands value share; sports shooting expands most quickly as recreational infrastructure develops.
End User:
Customer type determines authorization requirements, contract structure, and payment security.
- Defense Forces:National military establishments with multi-year framework agreements. Gulf Cooperation Council nations bundle long-term supply with platform acquisition, consolidating procurement under original equipment manufacturers.
- Private Security Firms:Corporate and diplomatic protection services operating across conflict-affected zones. These entities drive small caliber volume through sustained replenishment orders outside formal defense budgets.
- Hunting Enthusiasts:Licensed recreational hunters in South Africa and select Gulf jurisdictions. Regulatory fragmentation limits market development compared to established Western hunting economies.
- Shooting Ranges:Commercial training facilities and club operations. UAE-based ranges specify polymer-cased training rounds to reduce weight and corrosion, creating technology pull for composite casing suppliers.
Defense forces dominate contract value; private security firms represent the most consistent volume outlet.
Distribution Channel:
Supply concentration varies by channel, with direct military sales requiring sovereign authorization and retail channels facing stricter end-user verification.
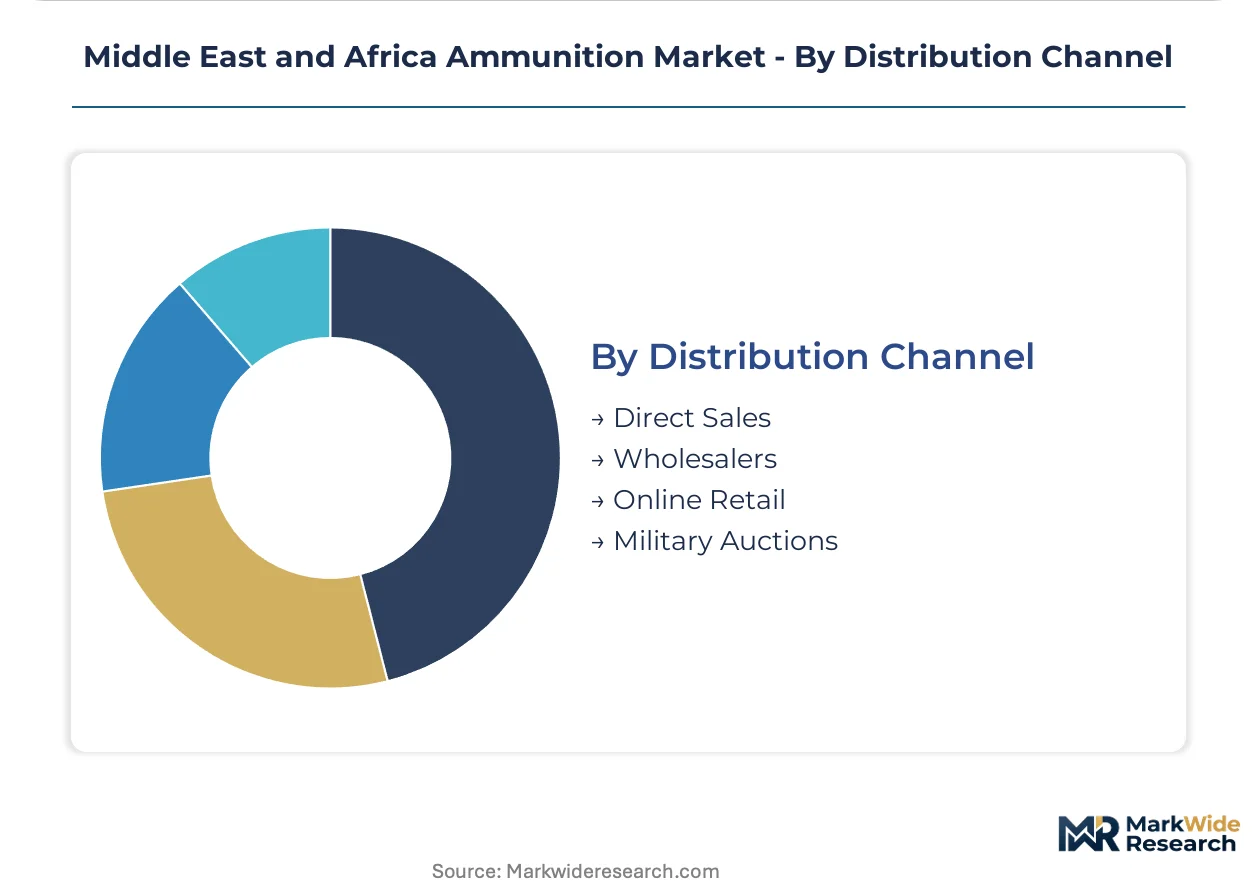
- Direct Sales:Manufacturer-to-military contracts with government-to-government offset arrangements. Tawazun Council mandates technology transfer thresholds that foreign suppliers must satisfy.
- Wholesalers:Regional distributors handling law enforcement and civil defense procurement. South Africa's National Conventional Arms Control Committee tightens permit requirements for munitions containing depleted uranium components.
- Online Retail:E-commerce platforms for sports shooting and hunting segments. Regulatory divergence between Gulf and sub-Saharan regimes fragments compliance protocols for cross-border transactions.
- Military Auctions:Surplus disposal and secondary market channels. Limited transparency and inconsistent lot acceptance testing protocols complicate quality assurance for end-users.
Direct sales capture the largest contract values; online retail faces the steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Al Tariq Industrial Area anchors ammunition manufacturing capacity across the Middle East and Africa region, with production clusters concentrated in the UAE, Saudi Arabia, and South Africa driving supply for armored vehicle modernization and sovereign defense industrial strategies.
United Arab Emirates
Abu Dhabi's defense industrial base accelerates medium and large caliber production through Tawazun Council offset mandates requiring technology transfer thresholds. The Tawazun Council redirects procurement toward joint venture structures that satisfy domestic value-add requirements. Al Tariq Industrial Area hosts integrated manufacturing facilities where polymer-cased ammunition production expands into operational categories.
Saudi Arabia
Armored vehicle fleet upgrades drive procurement of medium caliber rounds under General Authority for Military Industries localization frameworks. The General Authority for Military Industries imposes sovereign defense industrial strategies that fragment traditional Western supply relationships. Riyadh-based production clusters form through partnerships with South African and European industrial partners seeking preferential contract access.
South Africa
National Conventional Arms Control Committee restrictions on depleted uranium exports redirect regional sourcing toward alternative material suppliers. The National Conventional Arms Control Committee tightens permit requirements that create administrative friction for cross-border trade. Pretoria and Cape Town industrial zones anchor large-caliber forging and propellant chemistry capacity serving Gulf joint ventures.
Israel
Precision strike capability investments create demand for smart munitions integration with conventional explosive payloads. Israeli defense procurement prioritizes guidance electronics convergence over dumb munitions categories. Tel Aviv-area defense contractors develop dual-certification protocols achieving interoperability with NATO-standard and Eastern Bloc weapon platforms.
Egypt
Security sector modernization sustains replenishment orders for small and medium caliber ammunition across defense forces and law enforcement agencies. Egyptian military procurement operates through national framework agreements with preference for domestic suppliers where manufacturing capacity exists. Cairo and Alexandria industrial corridors concentrate assembly operations for training and standard issue rounds.
Middle East and Africa Ammunition Market Competitive Landscape
Joint venture formation dominates the current landscape as foreign suppliers establish local manufacturing partnerships to satisfy Tawazun Council and General Authority for Military Industries localization mandates. The market structure concentrates around sovereign wealth-backed entities, European industrial partners, and specialized South African producers. Three archetypes define competitive positioning: state-controlled defense conglomerates with vertical integration mandates, European industrial partners contributing propellant chemistry expertise, and regional specialists leveraging legacy ballistic engineering capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as stakeholders seek to satisfy offset requirements and secure multi-year framework agreements.
Among state-controlled entities, EDGE Group PJSC and Saudi Arabian Military Industries exemplify the sovereign wealth-backed archetype pursuing captive ammunition provisioning. Rheinmetall Denel Munition occupies a position bridging European industrial partnership and regional specialist categories, leveraging South African facilities to anchor large-caliber production. Elbit Systems Ltd sits within the precision systems tier, representing Israeli defense industrial capabilities in smart munitions convergence.
| Leading Market Players |
|---|
| Elbit Systems Ltd |
| Rheinmetall Denel Munition |
| EDGE Group PJSC |
| General Dynamics Corporation |
| Saudi Arabian Military Industries |
| BAE Systems plc |
| Denel PMP |
| Rheinmetall AG |
| Nexter Group |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers across the Gulf Cooperation Council anchor regional supply capacity, enabling disciplined pricing through captive procurement frameworks and technology transfer mandates that compress third-party supplier margins.
Pricing Analysis
Distributor margins on small caliber ammunition compress under direct-to-defense procurement consolidation, while large caliber rounds command premium positioning through extended certification cycles and limited qualified supplier pools. Pricing stratifies across NATO-standard, Eastern Bloc-compatible, and indigenous design tiers, with interoperability certification acting as the primary value discriminator. Cost compression in training ammunition intensifies as polymer-casing technology displaces brass constructions. Private security firms operating across sub-Saharan corridors exhibit the highest price sensitivity, whereas national defense forces prioritize lot consistency and traceability over unit economics.
Supply Chain Analysis
Freight costs for nitrocellulose propellant precursors escalate volatility across regional manufacturing margins, with Asian chemical processing hubs feeding South African forging facilities and Gulf assembly plants. Supply concentration clusters in South Africa for large-caliber forging, the United Arab Emirates for medium-caliber integration, and Saudi Arabia for emerging sovereign capacity. Raw material dependencies center on nitrocellulose from Asian processors, tungsten and depleted uranium alternatives for penetrator cores, and polymer resins for casing innovation. Single-source vulnerability in propellant chemistry creates systemic exposure. Distribution runs through government-to-government direct sales for defense procurement, with wholesale channels handling law enforcement and civil defense segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa ammunition market compounds steadily through sovereign localization mandates that perpetually recreate supplier relationships and sustain replacement demand across multi-year framework agreements.
For Market Incumbents: Extend backward integration into propellant chemistry to secure input cost control against Asian supply volatility. Consolidate certification capabilities for dual NATO-Eastern Bloc interoperability to capture platform-agnostic procurement bundles. The threat of sovereign-backed competitors with Tawazun Council and General Authority for Military Industries mandates demands pre-emptive joint venture positioning rather than reactive market access defense. For New Entrants and Emerging Players: Smart munitions guidance electronics offer the most penetrable wedge for technology-first entrants, as Gulf defense budgets prioritize precision strike capability over legacy dumb munitions. Target Ethiopian defense reconstruction and post-conflict security sector reform in sub-Saharan corridors where institutional rebuilding creates supplier relationship vacuums. A go-to-market angle bundling training system integration with ammunition provisioning bypasses entrenched incumbent supply relationships. For Investors and Strategic Acquirers: Sovereign wealth vehicles and state-controlled defense conglomerates are the most active acquirers in this space, seeking ballistic engineering capabilities and established certification pipelines. The 5-10 year viability window favors platforms with demonstrated joint venture execution in Gulf markets and polymer-casing manufacturing scale. The signal to watch is localization threshold escalation in Saudi Arabia and the UAE, which would accelerate captive supply consolidation and strand non-integrated foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Tawazun Council mandates technology transfer thresholds that foreign suppliers must satisfy for contract eligibility. |
| Polymer Casing Scale-Up | UAE-based ranges specify composite training rounds, pulling operational adoption across expeditionary deployment priorities. |
| Dual Certification Investment | Interoperability with NATO and Eastern Bloc platforms captures platform-agnostic procurement bundles in Gulf modernization. |
| Propellant Chemistry Backward Integration | Nitrocellulose supply concentration in Asian hubs creates margin volatility that captive chemistry control mitigates. |
| Smart Munitions Convergence | Guidance electronics integration with conventional payloads accesses premium Gulf defense budget allocations for precision strike. |
Research Methodology
Multiple input streams — defense procurement officer interviews, propellant chemistry technical assessments, and regulatory compliance documentation — were reconciled against customs trade data, National Conventional Arms Control Committee permit filings, and Tawazun Council offset disclosure records. Primary engagement with ballistic engineers, joint venture structuring advisors, and sovereign wealth investment officers combined with secondary validation from defense budget appropriation documents and industrial zone development filings. Bottom-up capacity modeling and top-down procurement flow analysis triangulated volume and value estimates.
Data-stream reconciliation applied across the analysis window linked caliber-specific production cost structures with end-user authorization tiers and localization mandate compliance thresholds. Segmentation dimensions modeled include product caliber classification, application authorization level, end-user customer type, and distribution channel concentration. CAGRs derived from procurement cycle timing, fleet modernization schedules, and sovereign industrial capacity buildout trajectories. Industry-specific forecast inputs incorporated nitrocellulose price volatility indices and dual-use export control harmonization progress between Gulf and sub-Saharan regulatory regimes.
The model holds under sustained sovereign localization policy commitment; deviation in propellant supply disruption or regulatory divergence acceleration would shift procurement timing and supplier competitive positioning. Forecasts reflect documented assumptions regarding framework agreement renewal rates and joint venture formation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
NATO Ammunition Market