
 Smartphone Camera Lenses Market | 2026-2036
Smartphone Camera Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Camera Lenses Market Intelligence
The gap between premium and commodity smartphone camera lens tiers is broadening as flagship devices adopt periscope and ultra-wide assemblies while budget segments standardize on simpler plastic-glass hybrids. Largan Precision leverages its vertical integration into glass molding to sustain margin leadership in high-aspheric designs. Sunny Optical Technology anchors volume production through dominant relationships with Chinese handset OEMs. Samsung Electro-Mechanics competes by controlling captive supply chains for its parent company's Galaxy lineup.
Smartphone camera lenses are optomechanical assemblies typically comprising five to seven elements with focal lengths ranging from 13mm to 125mm equivalent, engineered to resolve onto sub-micron pixel pitches while maintaining sub-5mm z-heights for slim device profiles. Periscope lens type segments command premium positioning due to complex prism-folded light paths and extended focal ranges that differentiate flagship specifications. Plastic material segments retain volume dominance in mid-range and budget tiers where cost-engineered molded aspheres replace ground glass, though glass-plastic hybrid stacks are displacing pure-plastic designs in camera-centric phones seeking superior low-light modulation transfer function.
FCC equipment authorization in the United States, CE marking under the EU's Radio Equipment Directive, and China's GB/T imaging standards collectively shape electromagnetic compatibility, safety, and optical performance thresholds for lens-integrated camera modules. REACH substance restrictions and RoHS hazardous material limits in Europe constrain lead-free solder choices and rare-earth dopants in coating layers, forcing reformulation of anti-reflective stacks. Stakeholders must monitor regulatory divergence between jurisdictions as divergent chemical compliance timelines fragment supply chain qualification cycles and complicate platform standardization strategies.
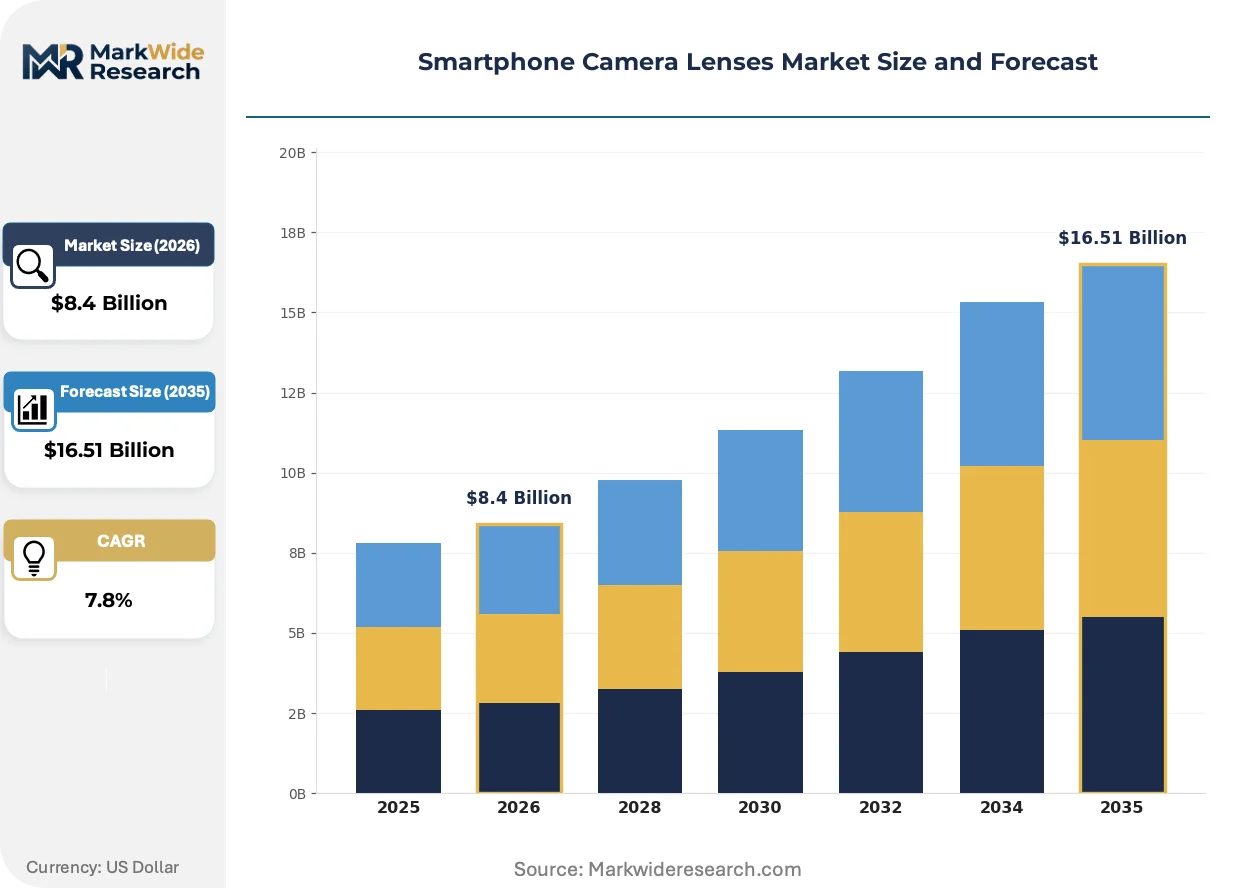
Market Dynamics
Computational photography demands are compressing development cycles as flagship manufacturers race to differentiate through periscope zoom and ultra-wide assemblies, forcing lens suppliers to synchronize roadmaps with semiconductor image signal processors.
Growth Catalysts
- Periscope lens architectures:Complex prism-folded light paths enable extended focal ranges that command premium positioning in flagship specifications, driving replacement cycles in high-aspheric designs.
- China's GB/T imaging standards:Mandatory optical performance thresholds for camera modules accelerate quality upgrades across domestic handset OEM supply chains, filtering into export requirements.
- Computational photography algorithms:Machine learning-based image stacking and night mode processing demand lens assemblies with superior modulation transfer function, pushing glass-plastic hybrid adoption beyond pure-plastic stacks.
Market Restraints
- Rare-earth dopant constraints:REACH substance restrictions and RoHS hazardous material limits in Europe constrain anti-reflective coating formulations, forcing reformulation of established deposition chemistries.
- Glass molding equipment scarcity:High-aspheric glass element production depends on specialized Japanese precision presses, creating single-source vulnerability for premium lens tiers.
- Pixel pitch resolution ceilings:Sub-micron pixel architectures approach diffraction limits, compressing the optical improvement window available through lens design alone.
Strategic Opportunities
- India handset manufacturing:Production-linked incentive schemes attract assembly operations that localize camera module sourcing, creating demand for lens suppliers establishing captive molding capacity.
- Automotive surround-view integration:Smartphone-derived lens designs transfer into vehicle camera clusters, opening specification overlap with ADAS Tier-1 suppliers seeking cost-engineered aspheres.
- EU Green Deal circularity mandates:Design-for-disassembly requirements favor modular lens-stack architectures that simplify element replacement and rare-earth recovery.
Industry Challenges
- Optical design talent scarcity:Aspheric surface optimization and tolerance analysis require specialized expertise concentrated in Taiwanese and Japanese engineering pools, constraining R&D scaling.
- Qualification timeline compression:Divergent chemical compliance timelines between REACH, RoHS, and China's GB standards fragment supply chain validation cycles, delaying platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Camera Lenses Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lens Type: Wide Angle, Telephoto, Macro, Fisheye, Ultra Wide, Periscope Material: Glass, Plastic, Sapphire, Optical Coated, Aspherical, Polymer Composite Application: Portrait Photography, Landscape Imaging, Low-Light Capture, Sports Photography, Video Recording, AR Imaging End User: Flagship Devices, Mid-Range Smartphones, Budget Smartphones, Gaming Phones, Foldable Phones, Camera-Centric Phones |
| Companies Covered | Largan Precision, Sunny Optical Technology, Samsung Electro-Mechanics, Sony Corporation, Canon Inc., OmniVision Technologies, LG Innotek, AAC Technologies Holdings, Genius Electronic Optical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Camera Lenses Market Strategic Shifts & Innovations
Wavefront engineering and materials science advances are redefining what slim-profile smartphone cameras can resolve, compressing the performance gap between mobile and dedicated imaging systems.
Liquid crystal polymer barrel housings are integrating into periscope assemblies to maintain dimensional stability across thermal cycling while shaving z-height margins. Flagship device manufacturers in South Korea and China are adopting these housings at accelerated cadences to enable folded-optic architectures. This material transition is integrating thermal management directly into structural elements, eliminating separate heat-spreader components.
REACH substance restrictions are forcing coating suppliers to eliminate perfluorinated compounds from hydrophobic surface treatments, triggering reformulation of anti-smudge layers across European-bound lens shipments. Deposition houses are responding with silane-based alternatives that meet ECHA hazard classifications while maintaining contact-angle performance. Premium lens tiers bear the brunt of qualification costs as mid-range suppliers delay compliance investments.
Handset OEMs are consolidating camera module procurement around vertically integrated suppliers capable of co-designing lens stacks with image sensor die placement. This pattern concentrates specification influence with module houses in China and South Korea that control both optical and electronic subsystems. The shift is most pronounced in flagship programs where time-to-market compression rewards single-source accountability.
Smartphone Camera Lenses Market Segmentation
Smartphone camera lens segmentation reveals how optical specifications, material choices, and device positioning interlock to create distinct value tiers. Manufacturers configure lens stacks differently based on whether the assembly serves standalone imaging or embedded computational photography subsystems.
Lens Type:
Integration depth varies sharply across lens architectures, with some designs functioning as standalone optical paths while others embed tightly with prism-folded or computational modules.
- Periscope:Prism-folded light paths enable extended focal ranges through folded-optic architectures that integrate mechanical stabilization and sensor-shift compensation. Samsung and Chinese flagship OEMs concentrate demand in South Korea and Shenzhen, driven by computational zoom algorithms requiring optical magnification beyond digital cropping limits.
- Ultra Wide:Sub-15mm equivalent focal lengths capture expanded fields of view through complex distortion correction that merges optical and software processing. Chinese handset manufacturers anchor volume demand in Dongguan and Beijing, compelled by social media platform specifications for immersive content formats.
- Wide Angle:Standard 24-28mm equivalent designs serve as primary camera modules across all device tiers.
- Telephoto:Narrow field-of-view optics enable portrait compression and distant subject isolation.
- Macro:Close-focusing capabilities support product photography and detail capture applications.
- Fisheye:Extreme barrel distortion creates immersive spherical perspectives for specialized content creation.
Wide Angle leads volumes today; Periscope is gaining share fastest.
Material:
Cost stratification across material categories determines which lens stacks qualify for premium versus volume manufacturing programs.
- Glass:Ground and molded optical glass delivers superior modulation transfer function and thermal stability through high refractive index formulations. Japanese precision press manufacturers constrain supply for high-aspheric elements, forcing Chinese module houses to qualify secondary sources for flagship programs.
- Plastic:Cost-engineered molded aspheres dominate mid-range and budget tier production through injection-molding cycles measured in seconds rather than minutes. Taiwanese compounders supply pellet formulations to Shenzhen molding clusters, though glass-plastic hybrids displace pure-plastic stacks in camera-centric phones seeking low-light performance.
- Sapphire:Synthetic single-crystal substrates provide extreme scratch resistance for protective cover lenses.
- Optical Coated:Multi-layer deposition stacks reduce flare and ghosting through tailored refractive index gradients.
- Aspherical:Non-spherical surface profiles correct aberrations with fewer elements than spherical designs.
- Polymer Composite:Reinforced thermoplastic blends balance dimensional stability with weight reduction.
Plastic leads volumes today; Glass is expanding most quickly.
Application:
Customer type differentiation separates professional-grade imaging demands from casual capture scenarios across device positioning tiers.
- Low-Light Capture:Large aperture designs and sensor-shift stabilization combine with computational stacking algorithms to extend usable illumination ranges. Flagship OEMs in Seoul and Beijing prioritize this segment, compelled by consumer benchmarking against dedicated camera systems.
- Portrait Photography:Telephoto-equivalent focal lengths with wide apertures create subject-background separation through optical bokeh or depth-map segmentation. Chinese social media platform requirements drive specification convergence across domestic handset supply chains.
- Landscape Imaging:Wide and ultra-wide optics maximize scene coverage for environmental documentation.
- Sports Photography:Predictive autofocus and burst-mode synchronization demand low-latency lens-sensor interfaces.
- Video Recording:Continuous autofocus and thermal management prioritize smooth aperture and focal transitions.
- AR Imaging:Depth-synchronized lens arrays support simultaneous localization and mapping for mixed reality overlays.
Portrait Photography leads volumes today; AR Imaging shows the steepest expansion trajectory.
End User:
Volume concentration versus margin extraction splits manufacturing priorities across device positioning tiers.
- Flagship Devices:Triple and quadruple camera arrays incorporate periscope, ultra-wide, and large-sensor primary modules with glass-dominant element stacks. Samsung and Apple procurement programs in South Korea and California set performance benchmarks that cascade into Chinese OEM roadmaps.
- Camera-Centric Phones:Specialized devices from Sony and Chinese imaging brands dedicate chassis volume and thermal budget to optical performance. Dongguan module houses co-design lens stacks with sensor placement for these programs, bypassing standard platform constraints.
- Mid-Range Smartphones:Dual and triple camera configurations balance cost and capability through plastic-glass hybrid elements.
- Budget Smartphones:Single or dual camera systems prioritize cost-engineered plastic aspheres.
- Gaming Phones:Thermal management constraints limit optical complexity despite high-performance processors.
- Foldable Phones:Z-height restrictions and flexible substrate compatibility impose unique mechanical packaging requirements.
Mid-Range Smartphones lead volumes today; Camera-Centric Phones are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent pools in Taiwan and Japan anchor precision glass molding capabilities, while Shenzhen and Seoul module houses concentrate downstream assembly operations.
China
MIIT's GB/T imaging standards mandate optical performance thresholds that accelerate quality upgrades across domestic handset OEM supply chains. Dongguan module houses co-design lens stacks with sensor placement for flagship programs, bypassing standard platform constraints. The Pearl River Delta clustering concentrates both molding capacity and final assembly for export-bound camera modules.
South Korea
Samsung and domestic flagship OEMs concentrate demand for periscope assemblies driven by computational zoom algorithms requiring optical magnification beyond digital limits. MFDS equipment authorization frameworks shape electromagnetic compatibility thresholds for lens-integrated modules. Seoul-based module houses control both optical and electronic subsystems, concentrating specification influence in flagship procurement programs.
Japan
METI industrial policy supports precision press manufacturers that constrain supply for high-aspheric glass elements, creating single-source vulnerability for premium lens tiers. Nagoya-area optical equipment fabricators maintain specialized glass molding capabilities that Chinese module houses struggle to replicate. JIS standards govern dimensional tolerances that cascade into export qualification requirements.
United States
FCC equipment authorization shapes electromagnetic compatibility thresholds for lens-integrated camera modules bound for North American handset programs. California-based computational photography developers drive specification convergence through image signal processor roadmaps that lens suppliers must synchronize. The San Francisco Bay Area clustering anchors algorithm development that redefines optical performance requirements.
Taiwan
Specialized aspheric surface optimization expertise concentrates in Taiwanese engineering pools, constraining R&D scaling for competitors lacking access. Largan Precision leverages backward integration into glass molding to sustain margin leadership in high-aspheric designs. Taichung-area optical fabricators supply pellet formulations to Shenzhen molding clusters while retaining core precision press operations domestically.
Smartphone Camera Lenses Market Key Industry Players
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates into consolidated module houses controlling captive supply chains, independent lens specialists maintaining precision molding assets, and diversified electronics conglomerates leveraging internal demand. Three strategic archetypes dominate: vertically integrated Korean and Chinese module houses, Taiwanese precision specialists, and Japanese optical equipment suppliers. Competitive moves concentrate on backward integration into glass molding capacity and co-design partnerships with flagship OEM image sensor programs.
Among Taiwan-based precision specialists, Largan Precision occupies a position exemplifying high-aspheric glass molding leadership. Sunny Optical Technology and AAC Technologies Holdings represent the Chinese module house archetype, anchoring volume production through relationships with domestic handset OEMs. Samsung Electro-Mechanics sits within the captive supply chain tier, controlling internal demand from its parent company's Galaxy lineup.
| Leading Market Players |
|---|
| Largan Precision |
| Sunny Optical Technology |
| Samsung Electro-Mechanics |
| Sony Corporation |
| Canon Inc. |
| OmniVision Technologies |
| LG Innotek |
| AAC Technologies Holdings |
| Genius Electronic Optical |
| Others |
Cost & Logistics Intelligence
Chinese flagship OEM procurement programs concentrate purchasing power across Shenzhen and Dongguan module houses, compressing lens stack pricing through consolidated volume commitments and co-design partnerships that eliminate redundant margin layers. Three-tier pricing structure across premium, standard, and economy levels separates periscope glass-molded assemblies from plastic-glass hybrid mid-range configurations and pure-plastic budget tiers.
Pricing Analysis
Bundled lens-sensor module procurement dominates flagship programs, while unbundled element sourcing persists for mid-tier suppliers seeking mix-and-match flexibility. Price differentiation hinges on glass element ratio and MIIT GB/T certification tier, with REACH-compliant coating formulations commanding modest premiums for European-bound shipments. Cost compression in plastic-molded tiers intensifies as Taiwanese compounders expand pellet supply to Shenzhen clusters. Budget smartphone OEMs exhibit highest price sensitivity, while camera-centric phone specialists prioritize modulation transfer function metrics over unit cost.
Supply Chain Analysis
Reverse-logistics flows for rare-earth recovery from coating layers are gaining traction under EU Green Deal circularity mandates, with modular lens-stack architectures simplifying element replacement. Raw material supply concentrates in Japan for precision glass molding presses, Taiwan for optical pellet formulations, and China for final module assembly. High-aspheric glass production draws from specialized Nagoya-area equipment fabricators, creating single-source vulnerability for premium tiers. Distribution runs through Dongguan module houses to handset OEM assembly plants across Shenzhen, Zhengzhou, and Noida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone camera lens market represents a late-cycle quality story as computational photography demands shift flagship specifications toward glass-dominant periscope assemblies with superior modulation transfer function performance.
For Market Incumbents: Deepen backward integration into glass molding capacity to defend margin position against Chinese module house consolidation. Prioritize co-design partnerships with Seoul and California-based image signal processor developers. Invest in REACH-compliant coating qualification to maintain European market access as ECHA substance restrictions tighten. For New Entrants and Emerging Players: Launch via specialized periscope element supply to Indian handset assembly operations under PLI schemes, bypassing established Shenzhen procurement clusters. Target camera-centric phone segments in Dongguan where specification customization rewards niche optical engineering. Pursue automotive surround-view qualification as specification overlap with ADAS Tier-1 suppliers opens secondary demand channels. For Investors and Strategic Acquirers: Chinese module houses are the most active acquirer in this space, consolidating lens stack co-design capabilities with sensor placement expertise. Long-term viability favors targets with captive glass molding assets and established MIIT certification pathways. Monitor periscope adoption rates in sub-flagship price tiers as the inflection indicator for technology democratization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Molding | Captures margin from Japanese precision press scarcity while securing high-aspheric element supply for flagship programs. |
| REACH-Compliant Coating Qualification | Maintains European market access as ECHA restrictions eliminate perfluorinated compounds from hydrophobic treatments. |
| Co-Design Partnership with Image Signal Processors | Synchronizes lens stack roadmaps with computational photography algorithm requirements from Seoul and California developers. |
| Modular Lens-Stack Architecture Development | Aligns with EU Green Deal design-for-disassembly mandates while simplifying rare-earth recovery from coating layers. |
| Automotive Surround-View Qualification | Transfers smartphone-derived aspheric designs into ADAS Tier-1 supplier specifications for vehicle camera clusters. |
Research Approach
Direct dialogue with optical design engineers, module house procurement directors, coating deposition specialists, and flagship OEM camera program managers grounded the qualitative assessment. Secondary validation drew from MIIT GB/T standard filings, Japan Optical Glass Industry Association production data, Shenzhen customs export records, and ECHA substance restriction updates. Bottom-up lens element shipment estimates triangulated against top-down handset production forecasts from Dongguan and Seoul assembly clusters.
Segment-level projections across lens type, material composition, application, and end-user tier fed into consolidated market sizing across the analysis window. The analytical framework modeled periscope penetration rates, glass-plastic hybrid adoption curves, and computational photography algorithm requirements as primary demand drivers. CAGRs derived from year-over-year shipment momentum in high-aspheric designs and coating chemistry reformulation cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Japan precision press supply disruptions or accelerated REACH substance restriction timelines. Practitioners should monitor periscope adoption in mid-range smartphone tiers and Indian PLI scheme localization progress for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Asia Pacific Fiber Optics Market
Optics
Fiber Optic Cable Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Optical Receivers Market
Optics
Optical Fiber Raw Material Market
Optics
Optical Lens for Mobile Phone Market
Optics
Fiber Optic Receiver Market
Optics
Plastic Lens Market
Optics
Photostimulation Lasers Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Germanium Lens Market
Optics
Global Fiber Optic Sensors Market
Optics
Optical Microscope Market
Optics
Europe Laser Interferometer Market
Optics
Sports Optics Market
Optics
Global Fiber Optic Components Market