
 Optical Microscope Market | 2026-2036
Optical Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Microscope Market Analysis
Clinical diagnostics is decoupling from academic research as the dominant revenue source for optical microscope vendors. Nikon Instruments leverages its fluorescence imaging lineage to anchor hospital pathology workflows across East Asia. Carl Zeiss sustains premium positioning through in-house production of apochromatic objectives. Motic competes aggressively on cost in the education and basic research tier.
An optical microscope magnifies visible-light images of specimens through refractive glass objective lenses and eyepieces, achieving resolutions near the diffraction limit of roughly 200 nanometers depending on numerical aperture and illumination wavelength. The instrument serves quality control, failure analysis, cellular biology, and clinical screening where electron microscopy remains impractical or destructive. Digital microscope systems are capturing margin pools as CMOS sensor integration displaces traditional eyepiece observation in industrial and educational settings. Compound microscopes dominate biological research and clinical diagnostics due to their superior magnification range, while stereo microscopes retain strongholds in electronics assembly and materials dissection where three-dimensional manipulation matters.
FDA 510(k) clearance pathways shape product development timelines for clinical diagnostic configurations, while EU MDR technical documentation requirements extend conformity assessment periods for fluorescence and phase contrast systems sold into European healthcare facilities. ISO 10993 biocompatibility testing and IEC 61010 electrical safety standards further constrain design choices for manufacturers targeting regulated end uses. Stakeholders must monitor convergence between optical platforms and computational imaging algorithms as software-defined resolution becomes a competitive differentiator separate from hardware specifications.
Market Dynamics
Computational imaging algorithms are decoupling resolution performance from pure hardware specifications, forcing vendors to invest in software-defined microscopy platforms that compress development cycles and alter R&D allocation across the supply base.
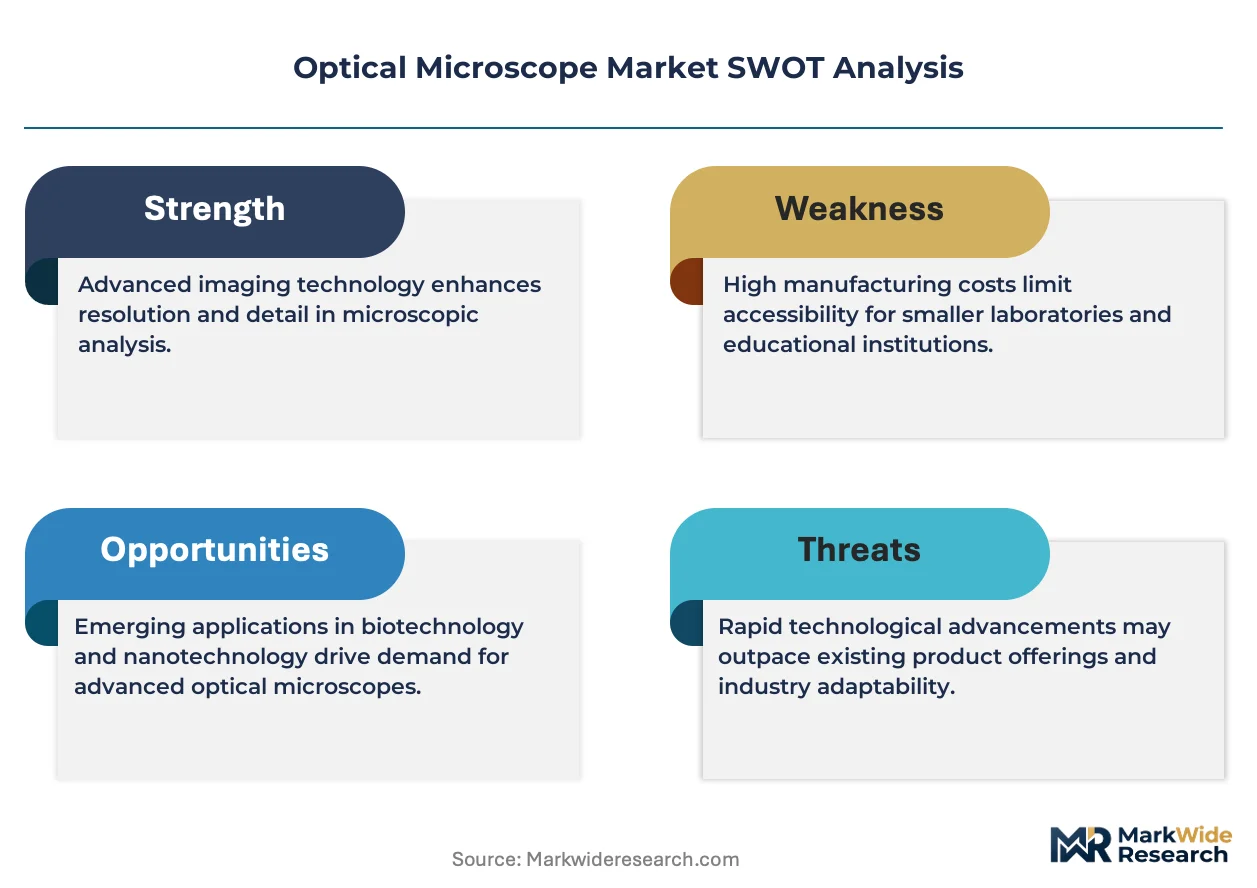
Growth Catalysts
- EU MDR conformity pathways:Tightened technical documentation requirements for fluorescence systems sold into European healthcare facilities are accelerating replacement cycles among legacy installed bases.
- Pathology laboratory automation:Clinical diagnostics workflows in East Asia are integrating digital slide scanning capabilities that require upgraded optical foundations.
- Precision optics clusters:Concentrated manufacturing competence in Germany's Jena and Wetzlar regions sustains component availability for high-numerical-aperture objectives.
Market Restraints
- Apochromatic glass supply concentration:Premium objective lens production depends on specialized rare-earth-doped glass formulations sourced from a limited supplier base in Central Europe.
- Electron microscopy substitution:Materials science and semiconductor failure analysis segments are migrating toward scanning electron microscopy where sample preparation permits.
- FDA 510(k) timeline friction:Clinical diagnostic configurations face extended premarket notification review periods that compress competitive windows for new entrants.
Strategic Opportunities
- CMOS sensor convergence:Integration of high-speed imaging sensors with optical platforms is expanding into industrial quality control applications previously served by eyepiece-based systems.
- Educational procurement modernization:Basic research and teaching institutions represent underpenetrated demand for digital microscope systems with networked image sharing capabilities.
- Biocompatibility testing mandates:ISO 10993 requirements for devices contacting biological specimens create certification-driven upgrade cycles in clinical settings.
Industry Challenges
- Computational imaging talent scarcity:Vendors face acute shortages of software engineers capable of integrating machine learning algorithms with optical hardware stacks.
- Legacy system integration complexity:Hospital pathology departments require seamless interoperability between new fluorescence platforms and existing laboratory information management systems.
- IEC 61010 electrical safety certification:Extended testing timelines for phase contrast and fluorescence configurations delay revenue recognition for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Microscope Market |
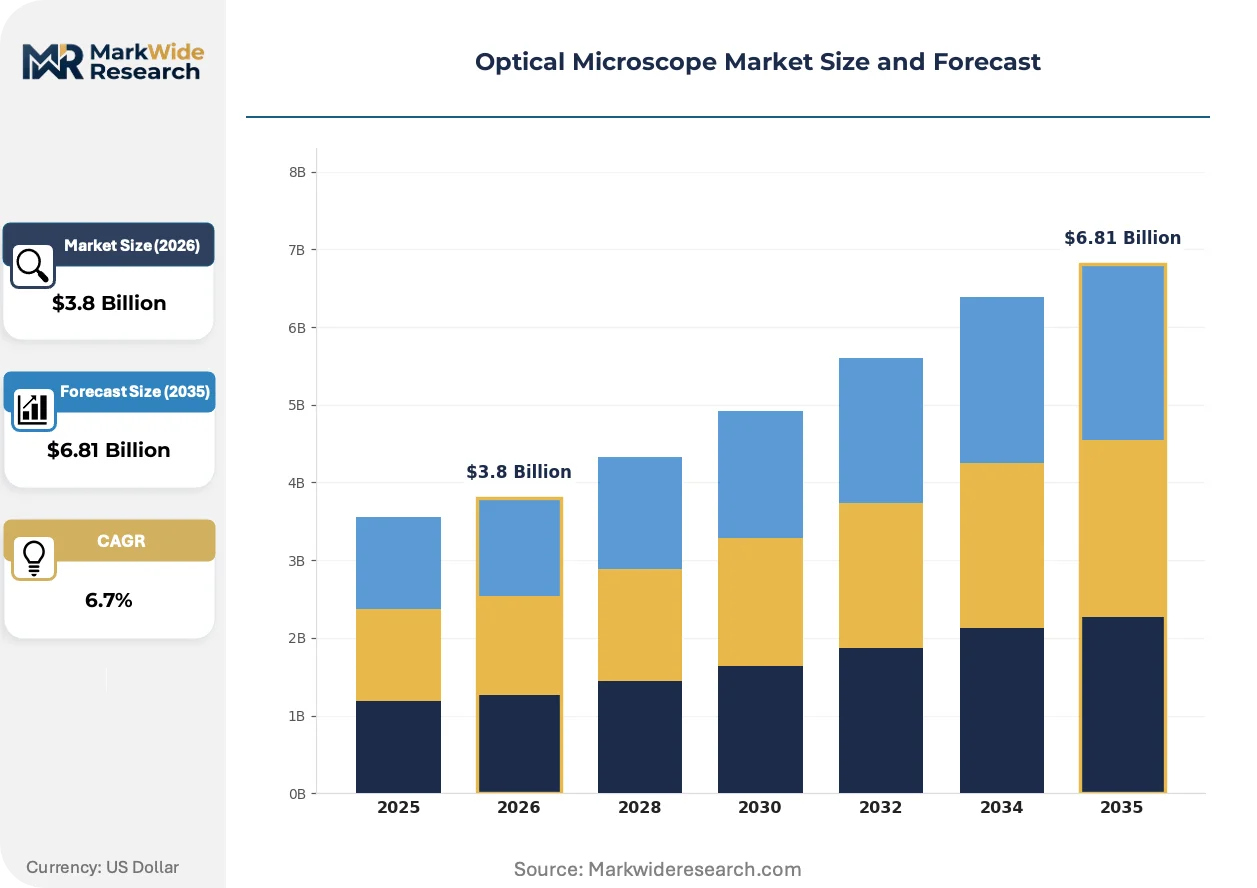
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverted Microscope, Stereo Microscope, Digital Microscope, Compound Microscope Technology: Fluorescence, Phase Contrast, Bright Field, Dark Field Application: Material Science, Biological Research, Education, Clinical Diagnostics End User: Academic Institutions, Healthcare Facilities, Research Laboratories, Industrial Sector |
| Companies Covered | Leica Microsystems, Meiji Techno, Motic, Carl Zeiss, Evident, AmScope, Nikon Instruments, ZEISS Microscopy, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Microscope Market Emerging Trajectories
Software-defined resolution is expanding into diagnostic workflows, regulatory harmonization is compressing conformity assessment timelines, and procurement centralization is concentrating purchasing authority among fewer institutional buyers.
Super-resolution computational microscopy is expanding into clinical pathology applications. Hospital laboratories in East Asia are adopting these platforms to achieve sub-diffraction imaging without electron microscopy infrastructure. The technology is expanding into routine diagnostic workflows by enabling pathologists to resolve cellular structures previously invisible under conventional optical limits.
EU MDR technical documentation requirements are extending conformity assessment periods for fluorescence and phase contrast systems. Manufacturers must submit comprehensive clinical evidence packages that strain regulatory affairs capacity. European healthcare facilities are responding by consolidating vendor relationships to reduce qualification overhead.
Consolidated procurement by multi-site hospital networks is displacing decentralized purchasing by individual pathology departments. Group purchasing organizations are negotiating enterprise-wide microscope contracts that bundle service and consumables. This pattern is most visible in Germany's university hospital systems where standardization reduces training and maintenance complexity.
Optical Microscope Market Segmentation
Optical microscope purchasing decisions fragment across certification intensity, application environment, and operator technical sophistication. Each segmentation dimension carries distinct margin profiles and vendor qualification requirements that reshape competitive positioning.
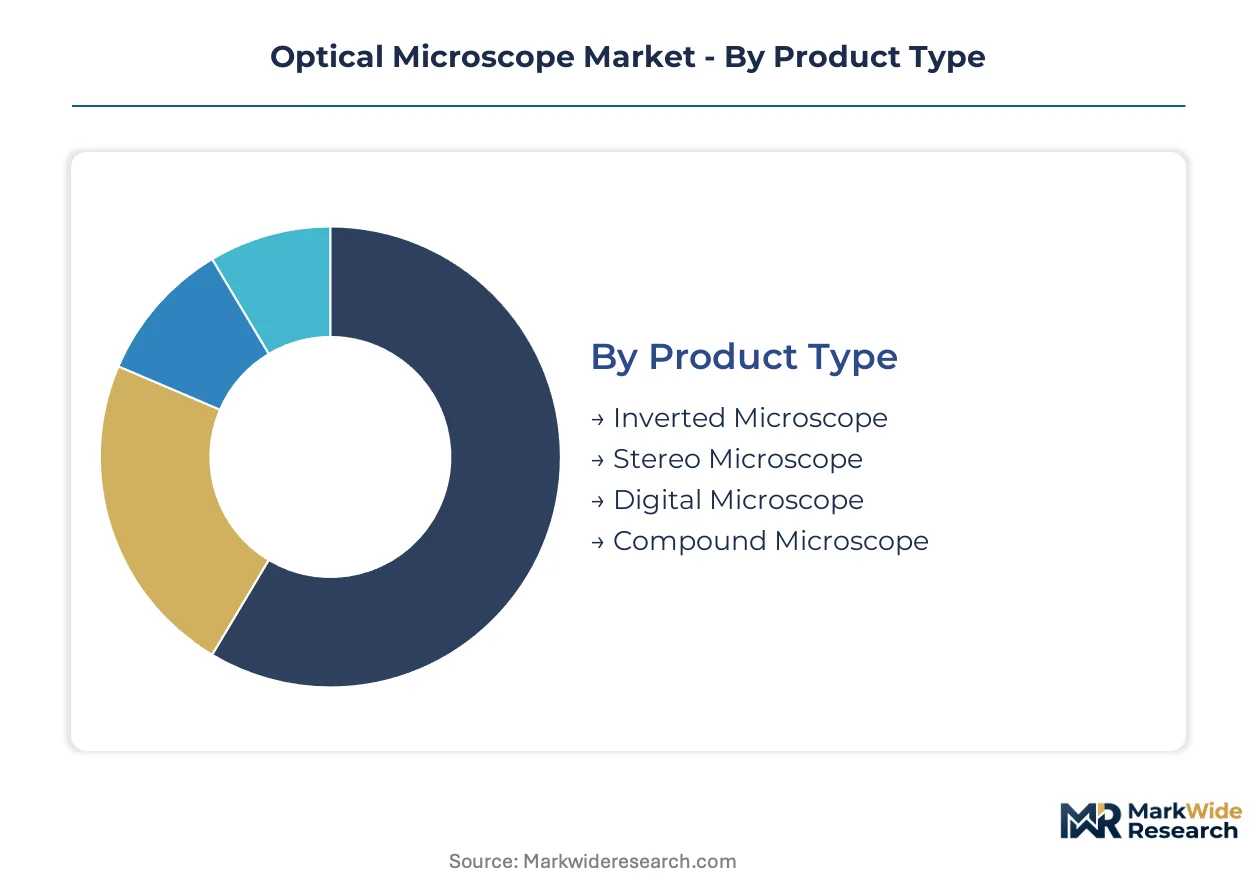
Product Type:
FDA 510(k) pathways apply selectively to clinical configurations, while educational and industrial variants face lighter conformity burdens.
- Compound Microscope:Multi-lens systems with objective turrets achieving up to 1000x magnification through oil-immersion optics. Hospital pathology departments in Germany's university hospital networks are consolidating procurement around fluorescence-equipped compound platforms to reduce training overhead.
- Digital Microscope:CMOS-integrated systems eliminating eyepieces in favor of direct display output. Industrial quality control operations in Japan's electronics assembly sector are displacing traditional stereo units with networked digital systems enabling remote inspection workflows.
- Stereo Microscope:Lower-magnification binocular systems optimized for three-dimensional specimen manipulation.
- Inverted Microscope:Objective positioning beneath the stage for live cell observation and tissue culture applications.
Compound Microscope sits at the top of the volume ranking, with Digital Microscope climbing the fastest.
Technology:
Cost tiers separate premium fluorescence configurations from basic bright field systems, with phase contrast occupying a mid-tier position requiring specialized optics without full fluorescence infrastructure.
- Fluorescence:High-intensity arc lamp or LED excitation combined with dichroic filter cubes for specific wavelength emission detection. EU MDR technical documentation requirements are extending conformity assessment periods for fluorescence systems sold into European healthcare facilities, accelerating replacement cycles among legacy installed bases.
- Bright Field:Transmitted white-light illumination through standard glass objectives. Basic research institutions in India's expanding university system represent underpenetrated demand for cost-optimized bright field configurations.
- Phase Contrast:Annular diaphragm and phase plate optics converting refractive index variations into intensity contrast.
- Dark Field:Oblique illumination blocking direct light to enhance scattering specimen visibility.
Fluorescence commands the steepest expansion trajectory as clinical diagnostics decouple from academic research as the dominant revenue source.
Application:
Customer type determines service bundling intensity, with clinical diagnostics requiring comprehensive maintenance contracts and education segments prioritizing capital cost minimization.
- Clinical Diagnostics:FDA-cleared configurations for histopathology, cytology, and hematology screening workflows. Pathology laboratory automation in South Korea's hospital networks is integrating digital slide scanning capabilities requiring upgraded optical foundations.
- Biological Research:Configurable platforms supporting fluorescence, phase contrast, and differential interference contrast modalities. Academic institutions in Switzerland's ETH network sustain demand for research-grade systems with modular upgrade paths.
- Material Science:Polarized light and metallurgical inspection applications.
- Education:Ruggedized student-proof designs with simplified optical paths.
Clinical Diagnostics dominates current procurement volumes, with Biological Research gaining share fastest through super-resolution computational adoption.
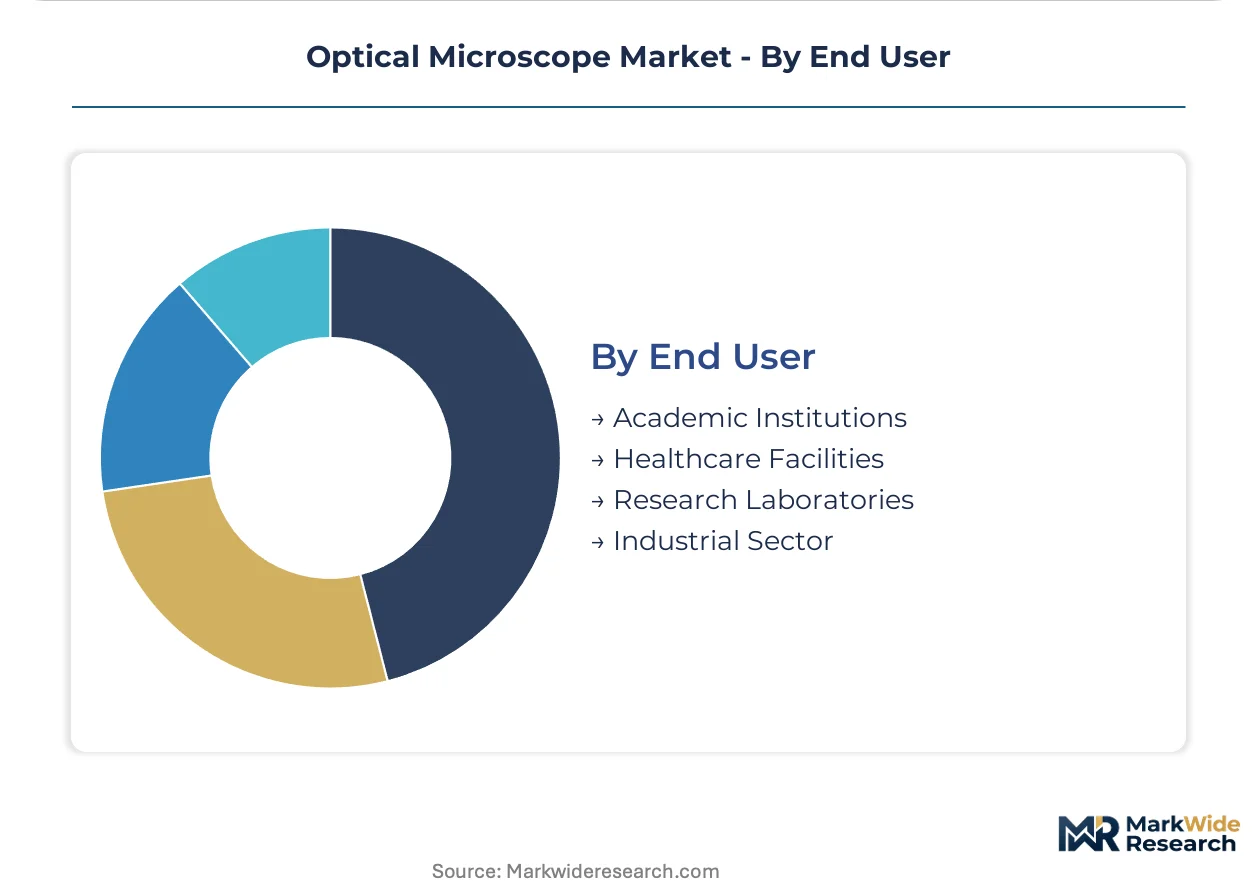
End User:
Supply concentration in Germany's precision optics cluster shapes availability and lead time differentiation across end user categories.
- Healthcare Facilities:Hospital pathology departments and clinical reference laboratories requiring IEC 61010 electrical safety certification and ISO 10993 biocompatibility compliance. FDA 510(k) timeline friction compresses competitive windows for new entrants targeting US healthcare procurement.
- Industrial Sector:Electronics assembly, semiconductor failure analysis, and pharmaceutical quality control operations. CMOS sensor convergence is expanding into industrial quality control applications previously served by eyepiece-based systems.
- Academic Institutions:University teaching laboratories and basic research groups.
- Research Laboratories:Government and private R&D facilities.
Healthcare Facilities anchor current demand volume, with Industrial Sector expanding most quickly through digital microscope adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as vendors relocate assembly to jurisdictions with streamlined medical device approval pathways. Production migration concentrates where EU MDR compliance costs and FDA 510(k) timelines create competitive gaps.
United States
Hospital pathology networks in Massachusetts and California are consolidating procurement around fluorescence-equipped platforms. FDA 510(k) premarket notification pathways compress competitive windows for new entrants targeting clinical diagnostics. Boston's life sciences corridor sustains demand for research-grade systems with modular upgrade paths.
Germany
University hospital systems in Baden-Württemberg and Bavaria are standardizing microscope fleets to reduce training complexity. EU MDR technical documentation requirements extend conformity assessment periods for fluorescence configurations. The precision optics cluster around Jena and Wetzlar anchors component supply for high-numerical-aperture objectives.
Japan
Electronics assembly operations in Osaka and Nagoya are displacing traditional stereo units with networked digital systems. METI industrial standards shape electrical safety certification timelines for phase contrast platforms. Tokyo's hospital networks integrate digital slide scanning capabilities requiring upgraded optical foundations.
China
Basic research institutions in Beijing and Shanghai sustain demand for cost-optimized bright field configurations. NMPA medical device registration pathways are tightening quality benchmarks for clinical microscopy platforms. The Yangtze River Delta manufacturing belt is capturing assembly migration from higher-compliance jurisdictions.
South Korea
Pathology laboratory automation in Seoul hospital networks is integrating super-resolution computational microscopy. MFDS medical device approval timelines influence product development cycles for fluorescence systems. The capital region's diagnostic imaging ecosystem anchors demand for clinical-grade configurations.
Optical Microscope Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium clinical configurations concentrating around heritage optics houses and educational tiers fragmenting among cost-optimized assemblers. The vendor base organizes into three archetypes: vertically integrated precision optics specialists, modular platform integrators, and volume-driven contract manufacturers. M&A activity targets computational imaging capabilities, while strategic partnerships secure rare-earth-doped glass supply from Central European sources.
Among heritage German optics houses, Carl Zeiss and Leica Microsystems exemplify the vertically integrated archetype through in-house apochromatic objective production. Nikon Instruments anchors the East Asian specialist tier, leveraging fluorescence imaging lineage for hospital pathology workflows. Motic occupies the cost-optimized education and basic research segment, competing aggressively on capital expenditure minimization for institutional procurement.
| Leading Market Players |
|---|
| Leica Microsystems |
| Meiji Techno |
| Motic |
| Carl Zeiss |
| Evident |
| AmScope |
| Nikon Instruments |
| ZEISS Microscopy |
| Bruker Corporation |
| Others |
Supply Flow & Price Mechanics
CMOS sensor integration into optical platforms is compressing eyepiece-assembly costs while concentrating procurement leverage among multi-site hospital networks in Germany and Japan. This dual shift simultaneously erodes margin pools in traditional stereo configurations and amplifies pricing power for vendors bundling computational imaging software with fluorescence hardware.
Pricing Analysis
Distributor margins in clinical diagnostics channels absorb the heaviest compression as group purchasing organizations consolidate procurement authority across German university hospital systems. Three-tier pricing structure across premium fluorescence, standard phase contrast, and economy bright field levels separates FDA-cleared configurations from educational variants. Cost compression in the education tier is intensifying because Motic and AmScope compete aggressively on capital expenditure minimization for institutional procurement. Academic buyers in India's expanding university system exhibit the highest price sensitivity, while pathology laboratories in Seoul and Tokyo prioritize optical resolution specifications over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from electronics assembly operations in Osaka and Nagoya, while distributor networks serve fragmented academic procurement across Europe and Asia. Rare-earth-doped glass formulations for apochromatic objectives draw from specialized suppliers concentrated in Germany's Jena-Wetzlar precision optics cluster and select Central European sources. Single-source vulnerability in specialized optical glass creates exposure to export restriction shocks from EU regulatory authorities. Distribution runs through authorized microscopy specialists for clinical configurations and direct e-commerce platforms for education-tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in optical microscopy rests on software-defined resolution capabilities that command premium pricing in clinical diagnostics while CMOS sensor commoditization erodes hardware-only profitability.
For Market Incumbents: Hedge against electron microscopy substitution in materials science by deepening software integration with laboratory information management systems. Capture rare-earth-doped glass supply through long-term offtake agreements with Central European suppliers before regulatory export restrictions tighten. Prioritize fluorescence platform standardization across German university hospital networks to entrench replacement cycle capture. For New Entrants and Emerging Players: E-commerce direct channels bypass established distributor relationships in the education tier, enabling rapid scale without clinical regulatory burden. India's expanding university system represents the most penetrable geography for cost-optimized bright field configurations. Target industrial quality control applications in China's Yangtze River Delta manufacturing belt with networked digital systems enabling remote inspection workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among modular platform integrators lacking captive optical glass supply but possessing computational imaging software stacks. Long-term viability favors vendors bridging hardware specifications with algorithm-driven resolution enhancement. Watch FDA 510(k) clearance velocity for fluorescence configurations as the inflection signal for competitive window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Imaging Acquisition | Machine learning algorithm integration with optical hardware stacks addresses acute software engineering talent scarcity. |
| Rare-Earth Glass Supply Agreement | Long-term offtake contracts with Central European suppliers mitigate single-source vulnerability in apochromatic objective production. |
| EU MDR Conformity Investment | Accelerated technical documentation capacity captures replacement cycles among legacy fluorescence installed bases in German healthcare facilities. |
| Digital Pathology Platform Launch | CMOS-integrated systems with networked image sharing penetrate industrial quality control applications in Japan's electronics assembly sector. |
| Educational Procurement Partnership | Standardized microscope fleet contracts with India's university system reduce training complexity while locking out cost-competitive alternatives. |
Methodological Framework
Bottom-up clinical diagnostics and biological research modeling reconciled against top-down precision optics component tracking forms the analytical core of this study. Primary interviews with hospital pathology directors, biomedical engineers in Seoul and Tokyo, GPO contracts managers, and fluorescence platform product managers combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and customs trade data for optical glass imports. Triangulation across these sources ensures segmentation integrity across product type, technology tier, and end-use application.
Input-output matrices map fluorescence-equipped compound microscope adoption against pathology laboratory automation investment cycles, while separate modules track CMOS sensor convergence in industrial quality control segments. Segmentation dimensions include product type, illumination technology, application environment, and end-user category across the projection horizon. CAGRs derive from installed base replacement velocity analysis and penetration curve modeling for super-resolution computational platforms. Forecast inputs incorporate EU MDR conformity assessment timeline extensions and MFDS approval pathway friction specific to South Korean clinical procurement.
The model assumes a particular technology adoption path for software-defined resolution; alternative pathways emphasizing pure hardware specification competition would alter the outlook for premium objective lens demand. Forecasts reflect assumptions about regulatory harmonization progress and rare-earth glass supply stability that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber Optic Switch Market
Optics
Photostimulation Lasers Market
Optics
Collimating Lens Market
Optics
Interchangeable Lens Market
Optics
North America Optical Imaging Market
Optics
MEMS Mirrors Market
Optics
Glass Scintillator Market
Optics
Latin America Optical Imaging Market
Optics
Fiber Optic Cable Market
Optics
Asia Pacific Fiber Optics Market
Optics
Optical Liquid Level Sensor Market
Optics
Photonics Sensor Market
Optics
Lasers Market
Optics
Fiber Optic Preform Market
Optics
Beam Expanders Market
Optics
Anti Glare Film Market