
 Global Fiber Optic Sensors Market | 2026-2036
Global Fiber Optic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Optic Sensors Market Analysis
Distributed fiber optic sensing is reshaping industrial monitoring architectures by replacing discrete point sensors with continuous, kilometer-scale measurement along a single optical strand. Corning Inc. leverages its vertically integrated glass science capabilities to dominate specialty fiber production for harsh-environment deployments. Yokogawa Electric Corporation competes through deep integration of optical interrogators with its distributed control systems for process industries. Honeywell International Inc. anchors its position in aerospace turbine monitoring through proprietary packaging that survives extreme thermal cycling.
Fiber optic sensors convert physical parameters—strain, temperature, pressure, or vibration—into modulated light signals within silica or polymer optical fibers, achieving immunity to electromagnetic interference across sensing distances exceeding fifty kilometers. Intrusive sensors and distributed sensors command the largest installed base in oil and gas pipeline monitoring, where margin pools concentrate in subsea umbilical contracts. Fibre Bragg Grating technology leads civil engineering applications for structural health monitoring of bridges and dams, while Raman Scattering-based distributed temperature sensing captures the fastest growth in geothermal well profiling and power cable hotspot detection.
FAA airworthiness standards and EU ATEX equipment directives impose stringent certification requirements on fiber optic sensor assemblies deployed in hazardous aerospace and petrochemical environments, effectively filtering out suppliers lacking accredited testing infrastructure. OSHA process safety management rules mandate continuous monitoring of high-pressure vessels, directly stimulating replacement of electrical gauge networks with intrinsically safe optical alternatives. Stakeholders must weigh the capital cost of interrogator hardware against lifecycle savings from eliminated calibration cycles and reduced cabling complexity.
Market Dynamics
Distributed fiber optic sensing architectures are displacing discrete sensor networks across hazardous industrial environments, driven by intrinsic safety advantages and regulatory mandates for continuous monitoring in explosion-risk zones.
Growth Catalysts
- EU ATEX Directives:Equipment explosion protection mandates compel petrochemical operators to replace electrical instrumentation with intrinsically safe optical alternatives in Zone 0 and Zone 1 hazardous areas.
- Subsea Pipeline Integrity:Deepwater oil and gas developments in the United States Gulf Coast and Brazil's pre-salt basins require kilometer-scale distributed temperature and strain monitoring along umbilical cables.
- Fibre Bragg Grating Maturation:Multiplexing capabilities now enable hundreds of sensing points on single fibers, reducing cabling complexity for civil infrastructure health monitoring.
Market Restraints
- Specialty Fiber Supply Concentration:High-purity germanium-doped silica preform production concentrates among three suppliers, creating input bottlenecks for harsh-environment sensor manufacturing.
- Interrogator Hardware Costs:Distributed temperature sensing systems require spectrometer-grade optical interrogators priced at multiples of conventional electronic dataloggers, extending payback periods.
- Technical Skill Thresholds:Deployment of Raman and Brillouin scattering systems demands rare expertise in photonics engineering and optical signal processing, constraining field service capacity.
Strategic Opportunities
- Geothermal Energy Expansion:Enhanced geothermal systems in Indonesia, Kenya, and Turkey require downhole distributed temperature profiling for reservoir management and flow characterization.
- Smart Grid Cable Monitoring:High-voltage underground power transmission networks in Germany and South Korea present untapped demand for hotspot detection and dynamic line rating.
- OSHA Process Safety Mandates:Continuous pressure vessel monitoring requirements create replacement cycles for aging electrical gauge networks in United States refineries and chemical plants.
Industry Challenges
- Calibration Drift Management:Long-term stability of optical reference points requires periodic recertification against NIST-traceable standards, complicating maintenance protocols.
- Legacy System Integration:Fiber optic sensor networks must interface with existing SCADA architectures through protocol converters, adding engineering complexity and latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Optic Sensors Market |
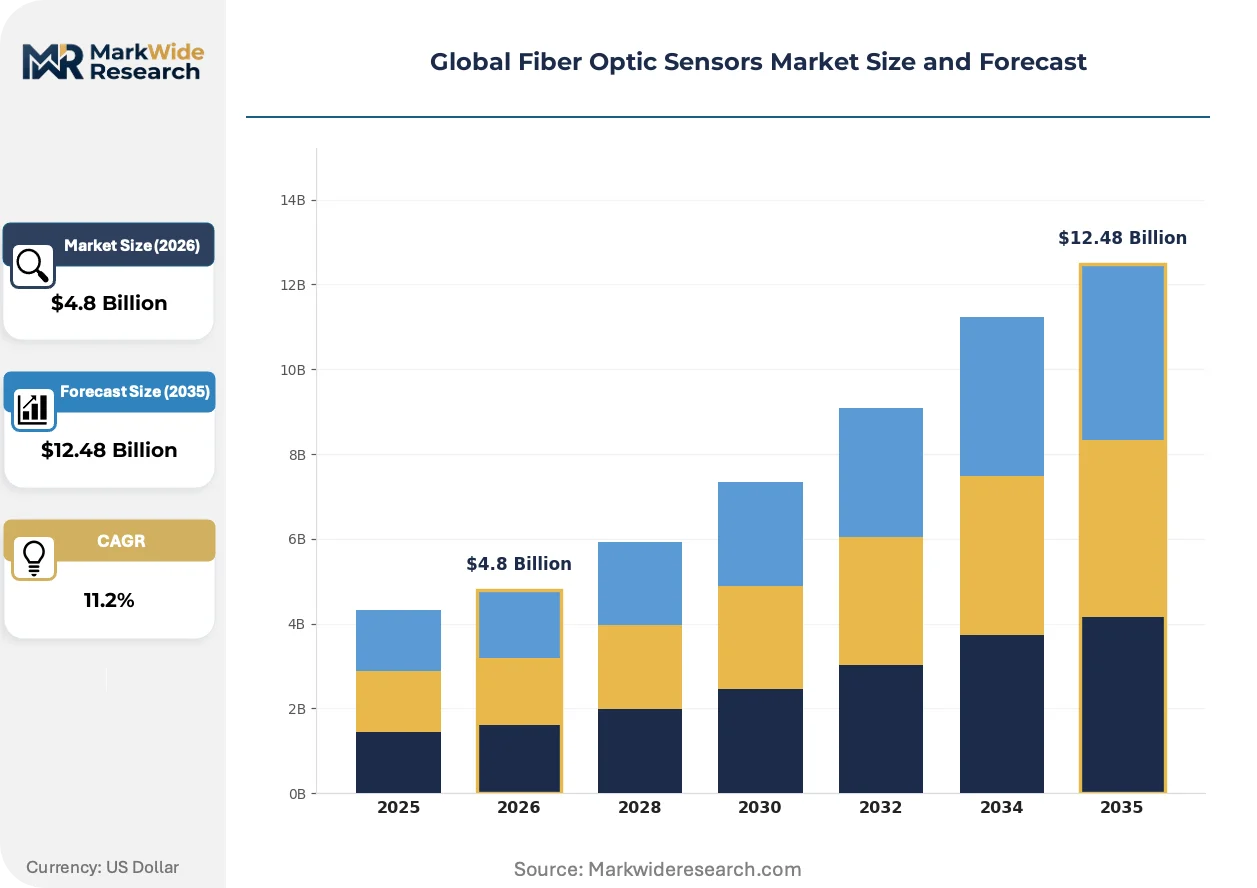
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusive Sensors, Non-Intrusive Sensors, Distributed Sensors, Point Sensors Technology: Fibre Bragg Grating, Optical Time-Domain Reflectometry, Interferometric Sensors, Raman Scattering End User: Oil & Gas, Civil Engineering, Aerospace, Medical Application: Temperature Monitoring, Structural Health Monitoring, Pressure Measurement, Pipeline Leak Detection |
| Companies Covered | Sumitomo Electric Industries Ltd., Yokogawa Electric Corporation, Halliburton, Schlumberger Limited, ABB, Honeywell International Inc., Corning Inc., TE Connectivity, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Optic Sensors Market Emerging Trajectories
Photonic integration and artificial intelligence are converging to transform fiber optic sensing from passive measurement tools into predictive diagnostic platforms. Three developments are restructuring competitive advantage.
Multiparameter fiber optic sensing is hybridizing distributed temperature, strain, and acoustic measurements onto single optical strands. Offshore platform operators in Norway's North Sea fields are deploying these unified systems to reduce umbilical cable counts. The technology is compressing supplier margins on discrete single-parameter sensors while expanding total addressable spend on integrated interrogator platforms.
Japan's METI has issued updated industrial safety guidelines requiring continuous structural monitoring of aging infrastructure, including bridges, tunnels, and dams exceeding fifty years of service life. Civil engineering contractors must now specify fiber optic sensor networks in public procurement bids. Domestic construction consortia are accelerating qualification of Fibre Bragg Grating systems to meet these compliance deadlines.
Asset owners are unbundling sensor hardware procurement from installation and data analytics services. North American pipeline operators now separately contract fiber deployment, interrogator supply, and cloud-based diagnostic platforms. This disaggregation is fragmenting vendor relationships and shifting margin capture toward specialized analytics providers with machine learning capabilities for anomaly detection.
Global Fiber Optic Sensors Market Segmentation
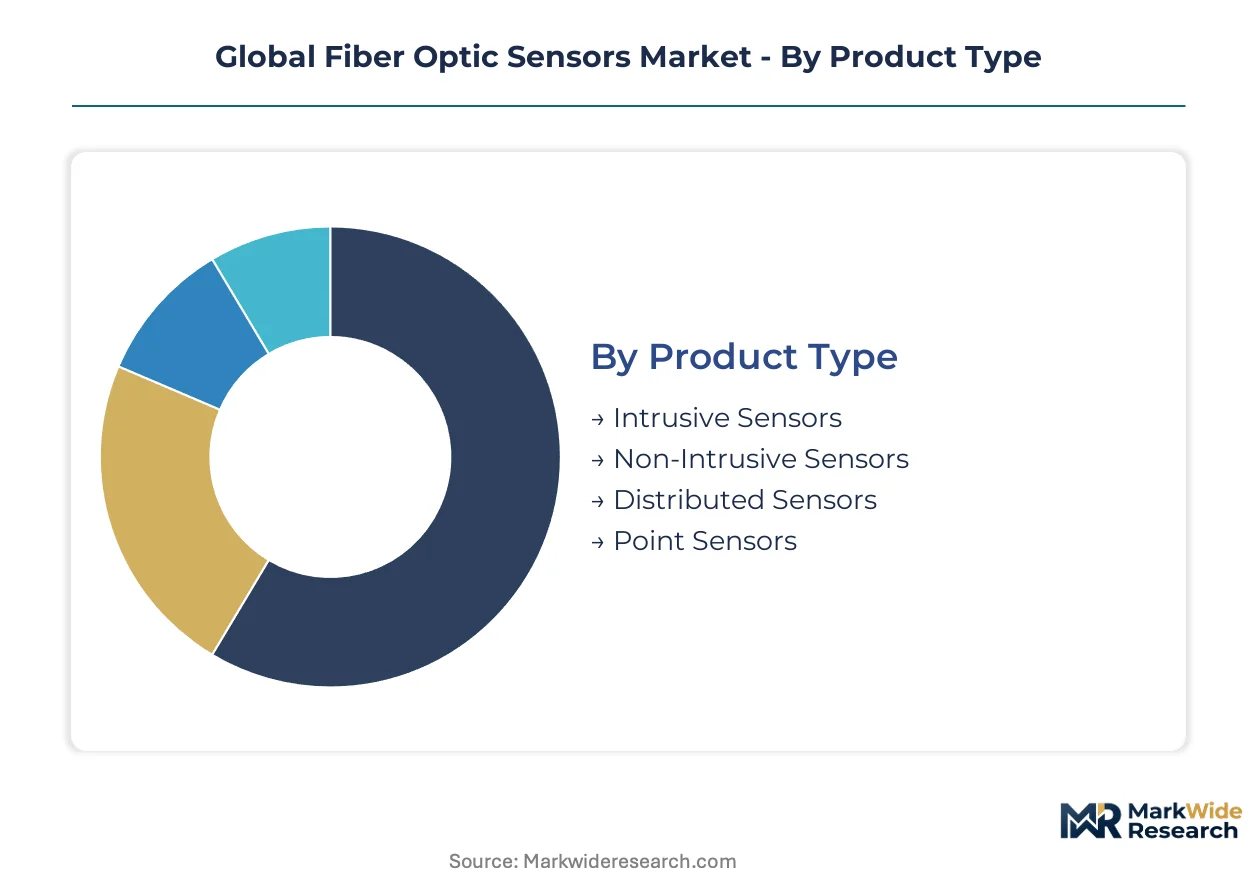
Fiber optic sensor procurement patterns vary sharply across deployment contexts, with subsea umbilical contracts demanding multi-year service agreements while civil infrastructure projects favor turnkey installation. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications dominate vendor selection criteria.
Product Type:
After-sales service intensity diverges dramatically across these hardware categories, with distributed architectures requiring continuous calibration support and point sensors operating on replaceable-unit models.
- Distributed Sensors:Continuous measurement along single optical fibers enables kilometer-scale temperature and strain profiling without discrete sensing points. Demand concentrates in United States Gulf Coast subsea developments where deepwater operators monitor umbilical integrity across extended tieback distances, driven by regulatory mandates for pipeline leak detection coverage. These systems command the highest service attach rates due to interrogator recalibration requirements.
- Intrusive Sensors:Direct insertion into process streams or structural members delivers point-specific measurements with minimal optical path complexity. Oil and gas operators in Norway's North Sea fields deploy these for high-pressure vessel monitoring where intrinsic safety requirements exclude electrical alternatives, compelled by EU ATEX directives for Zone 0 hazardous areas.
- Non-Intrusive Sensors:Surface-mounted configurations measure parameters through cladding or barrier materials without breaching containment boundaries.
- Point Sensors:Discrete optical transducers provide localized measurements at specific coordinates along fiber networks.
Distributed sensors hold the largest share; momentum sits with intrusive sensors as brownfield retrofit projects accelerate.
Technology:
Cost tier stratification separates spectrometer-grade interrogator platforms from simplified single-purpose units, with price multiples of five to ten times distinguishing commercial tiers.
- Raman Scattering:Temperature-dependent frequency shifts in backscattered light enable distributed thermal profiling without requiring fiber modifications. Geothermal developers in Indonesia and Turkey deploy these systems for reservoir characterization during enhanced geothermal system commissioning, where downhole conditions exceed electronic sensor survival limits.
- Fibre Bragg Grating:Periodic refractive index variations create wavelength-selective reflectors that multiplex hundreds of sensing points on single fibers. Japanese civil engineering contractors specify these for aging bridge and tunnel monitoring following METI safety guideline updates, with public procurement mandates driving qualification timelines.
- Optical Time-Domain Reflectometry:Pulse-echo techniques locate faults and measure distributed attenuation along fiber lengths.
- Interferometric Sensors:Phase modulation of coherent light sources achieves picometer-scale displacement resolution for precision metrology.
Fibre Bragg Grating dominates civil infrastructure; Raman Scattering is climbing the fastest in energy sector deployments.
End User:
Application maturity varies by sector, with aerospace certification cycles spanning years while medical device pathways accelerate through predicate approvals.
- Oil & Gas:Exploration, production, and pipeline operators constitute the foundational demand base for harsh-environment fiber optic sensing. United States refineries along the Gulf Coast petrochemical corridor are replacing electrical gauge networks under OSHA process safety management mandates, creating replacement cycles for pressure vessel and storage tank monitoring.
- Civil Engineering:Bridge, dam, and tunnel operators deploy structural health monitoring networks for compliance and risk management. South Korean infrastructure authorities are expanding fiber optic coverage across high-speed rail corridors following seismic vulnerability assessments.
- Aerospace:Turbine and airframe manufacturers require sensors surviving extreme thermal cycling and electromagnetic environments.
- Medical:Minimally invasive surgical and diagnostic applications leverage biocompatibility and electromagnetic immunity of optical fibers.
Oil and Gas retains the largest installed base; Civil Engineering is expanding most quickly as infrastructure age triggers monitoring mandates.
Application:
Customer procurement patterns bifurcate between continuous monitoring subscriptions and episodic inspection services, with structural health monitoring favoring long-term data contracts.
- Temperature Monitoring:Distributed and point thermal sensing addresses process control, fire detection, and electrical hotspot identification. German high-voltage grid operators are deploying underground cable monitoring systems for dynamic line rating and overload protection, responding to renewable integration challenges on transmission networks.
- Structural Health Monitoring:Strain, vibration, and deformation tracking enables predictive maintenance of critical infrastructure. Kenya's geothermal expansion projects require continuous downhole structural assessment for well casing integrity across corrosive high-temperature environments.
- Pressure Measurement:Optical transduction eliminates spark risks in high-pressure hydrocarbon processing.
- Pipeline Leak Detection:Distributed acoustic and thermal sensing enables rapid localization of integrity breaches.
Temperature Monitoring holds the largest share; Structural Health Monitoring is gaining share fastest as asset owners shift from scheduled to condition-based maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor nations with captive specialty fiber production, while import-dependent markets absorb distributed sensing hardware for subsea and infrastructure applications. Germany and Japan maintain net export positions in optical preforms and interrogator components. The United States, China, and South Korea represent concentrated demand centers where domestic assembly integrates imported photonic subsystems.
United States
Gulf Coast petrochemical corridors drive demand for distributed temperature sensing along subsea tiebacks and refinery pressure vessel networks. OSHA process safety management rules mandate continuous monitoring of high-pressure equipment, accelerating replacement of electrical gauge systems with intrinsically safe optical alternatives. Houston and Corpus Christi host the densest clusters of brownfield modernization projects requiring fiber optic structural health monitoring.
Germany
High-voltage grid operators deploy distributed temperature sensing for underground cable hotspot detection and dynamic line rating amid renewable integration challenges. EU ATEX directives compel chemical manufacturers in the Rhine-Ruhr industrial basin to adopt intrinsically safe optical instrumentation in Zone 0 hazardous areas. Munich and Stuttgart anchor precision photonics engineering clusters supplying spectrometer-grade interrogator platforms.
Japan
METI safety guidelines require continuous structural monitoring of aging bridges, tunnels, and dams exceeding fifty years of service life. Civil engineering contractors must specify fiber optic sensor networks in public procurement bids, driving qualification timelines for Fibre Bragg Grating systems. The Kanto region around Tokyo concentrates domestic construction consortia and optical component fabricators serving infrastructure compliance mandates.
China
Geothermal developers in western provinces deploy Raman scattering-based distributed temperature sensing for enhanced geothermal system reservoir characterization where downhole conditions exceed electronic sensor limits. MIIT industrial safety standards for high-pressure equipment create compliance-driven replacement cycles in Sichuan and Xinjiang petrochemical facilities. The Yangtze River Delta hosts domestic specialty fiber preform production scaling toward import substitution.
Brazil
Pre-salt basin deepwater developments require kilometer-scale distributed temperature and strain monitoring along subsea umbilical cables for pipeline integrity management. ANP regulatory mandates for leak detection coverage compel optical sensing adoption across Santos Basin production fields. Rio de Janeiro anchors engineering procurement clusters contracting integrated fiber optic monitoring packages for floating production facilities.
Global Fiber Optic Sensors Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated glass science specialists and process control system integrators with captive optical interrogator capabilities. Three strategic archetypes dominate: specialty fiber manufacturers controlling germanium-doped preform supply, industrial automation conglomerates bundling sensors with distributed control systems, and oilfield service providers packaging monitoring hardware with reservoir characterization contracts. Competitive dynamics center on backward integration into preform production and strategic partnerships to secure interrogator component supply.
Among Asia-Pacific-based conglomerates, Sumitomo Electric Industries Ltd. and Yokogawa Electric Corporation exemplify the integrated industrial systems archetype, occupying positions that bridge optical component fabrication with end-use application engineering. Halliburton and Schlumberger Limited represent the oilfield services integration model, anchoring demand capture through subsea monitoring contracts that specify fiber optic sensing packages. These groupings illustrate how supplier positioning follows end-use verticalization rather than pure component specialization.
| Leading Market Players |
|---|
| Sumitomo Electric Industries Ltd. |
| Yokogawa Electric Corporation |
| Halliburton |
| Schlumberger Limited |
| ABB |
| Honeywell International Inc. |
| Corning Inc. |
| TE Connectivity |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta specialty fiber cluster in China anchors global preform supply, with captive germanium-doped silica production concentrating pricing leverage among three dominant suppliers. This geographic chokepoint transmits upstream scarcity into downstream interrogator hardware premiums, while modular assembly in South Korea and Japan competes on cost engineering.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ATEX certification grade and interrogator optical resolution, with spectrometer-grade units commanding five-to-ten multiples over simplified dataloggers. Cost compression in standard-tier distributed temperature sensing intensifies as Chinese domestic preform capacity scales toward import substitution. Midstream oilfield service providers exhibit highest price sensitivity due to capital cycle timing, while aerospace turbine manufacturers absorb premiums for FAA-certified packaging surviving thermal cycling.
Supply Chain Analysis
Corning Inc., Sumitomo Electric Industries Ltd., and Yangtze Optical Fibre and Cable Joint Stock Limited Company hold concentrated contract-manufacturing capacity for high-purity germanium-doped preforms. Manufacturing draws from specialty silica feedstock sourced in the United States, Germany, and Japan, with final interrogator assembly clustering in South Korea and Japan. Single-source vulnerability concentrates in germanium tetrachloride purification, where three facilities supply global sensor-grade demand. Distribution runs through oilfield service integrators and industrial automation distributors, with direct OEM relationships dominating aerospace and civil engineering procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as regulatory mandates for continuous hazardous-area monitoring displace legacy electrical instrumentation faster than supply capacity can absorb. OSHA process safety rules and EU ATEX directives create compliance-driven replacement cycles that outpace organic growth in greenfield deployment.
For Market Incumbents: Insulate core margin pools by securing captive preform supply through long-term offtake agreements with Yangtze River Delta producers. Accelerate qualification of multiparameter sensing platforms to compress discrete single-parameter sensor margins before specialized analytics providers capture diagnostic value-add. The threat of unbundled hardware-procurement models demands defensive integration into cloud-based anomaly detection services.
For New Entrants and Emerging Players: Establish a beachhead in geothermal reservoir characterization, where Raman scattering deployment expertise remains scarce and Indonesian, Kenyan, and Turkish developers face electronic sensor survival limits. Target civil engineering structural health monitoring in Japan, where METI compliance deadlines force rapid Fibre Bragg Grating qualification and domestic construction consortia seek qualified suppliers. A go-to-market angle through specialized photonics engineering consultancies bypasses entrenched oilfield service relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because hazardous-area monitoring mandates create durable replacement demand independent of commodity cycles. Acquisition target archetype: mid-tier interrogator manufacturers with spectrometer-grade optical platforms but underdeveloped analytics capabilities. Watch for inflection in German high-voltage grid distributed temperature sensing procurement as renewable integration accelerates dynamic line rating adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Production | Captive germanium-doped silica supply secures margin control against three-supplier concentration. |
| Multiparameter Platform Development | Unified temperature-strain-acoustic sensing reduces umbilical counts for Norway North Sea operators. |
| Cloud-Based Diagnostic Service Launch | Machine learning anomaly detection captures margin shifting from hardware toward analytics providers. |
| Geothermal Sector Qualification | Downhole Raman expertise addresses Indonesian and Turkish reservoir characterization demand. |
| Japanese Civil Engineering Certification | METI compliance deadlines for aging infrastructure create urgent Fibre Bragg Grating procurement. |
Methodological Framework
The analysis maps distributed sensing architectures, point sensor modalities, and interrogator hardware tiers, each validated through primary interviews with oilfield service procurement directors, civil engineering contractors, aerospace sensor qualification engineers, and geothermal project developers. Secondary sources include SEC filings from listed industrial automation conglomerates, FAA airworthiness certification databases, EU ATEX notified body registers, and Japanese public procurement bid specifications. Bottom-up unit economics triangulate against top-down sector spend estimates.
Assumptions held fixed include regulatory enforcement intensity for OSHA process safety and EU ATEX directives, while oil and gas capital expenditure cycles and renewable integration pace in Germany were stress-tested across scenarios. Segmentation modeling spans product type, sensing technology, end-user industry, and application function. CAGRs derive from installed base growth plus replacement cycle timing, with inputs from specialty fiber preform capacity expansion schedules and interrogator component lead time trends.
Stress conditions across germanium feedstock pricing, Chinese preform capacity ramp rates, and oilfield service consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and could revise upon shifts in hazardous-area regulatory scope or breakthroughs in electronic sensor survival limits. Quarterly review of Japanese infrastructure procurement awards, German grid operator sensing tenders, and geothermal project financing closures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photonics Sensor Market
Optics
Photonic Crystals Market
Optics
Anti Glare Film Market
Optics
Global Optical Lens Market
Optics
Optical Profilometer Market
Optics
Interchangeable Lens Market
Optics
Stroboscope Market
Optics
Photostimulation Lasers Market
Optics
Digital Holographic Microscopy Market
Optics
Laser Transmitter Market
Optics
Fiber Optic Amplifier Market
Optics
Optical Imaging Market
Optics
Sports Optics Market
Optics
Fiber Optics Market
Optics
Global Super Hi Vision Market
Optics
Fiber Optic Switch Market