
 Germanium Lens Market | 2026-2036
Germanium Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Germanium Lens Market Insights
Capital-intensity divergence between integrated refiners and specialized polishers is reorganizing competitive tiers in the Germanium Lens Market. Umicore leverages its vertical control from metal refining through precision optics to sustain margin capture across the value chain. China Germanium Co., Ltd. anchors supply security through captive access to domestic concentrate, while 5N Plus competes on high-purity metal output for infrared substrate applications.
Germanium lenses transmit infrared wavelengths from 2 to 14 micrometers with high refractive index and low dispersion, requiring single-point diamond turning or precision molding to achieve surface accuracies below 100 nanometers. These properties make them indispensable for thermal imaging and IR sensing systems operating in defense, industrial, and medical environments. Aspherical lenses dominate product value due to their ability to correct aberrations in compact optical assemblies, while thermal imaging leads application demand driven by night-vision and surveillance modernization. Military Applications command premium pricing tiers through stringent durability and environmental testing protocols.
EMA medical device regulations, REACH substance restrictions, and ITAR export controls collectively shape product certification pathways and cross-border sales eligibility for germanium optical components. RoHS exemptions for infrared optics remain under periodic European Commission review, creating compliance planning uncertainty for manufacturers serving EU defense and healthcare buyers. Stakeholders must monitor regulatory recalibrations in China and Europe alongside raw material stockpile policies to anticipate supply availability and qualification timelines.
Market Dynamics
Defense procurement cycles for thermal imaging systems are compressing qualification timelines while REACH substance restrictions in Europe force dual-sourcing strategies for germanium feedstock. These intersecting pressures are restructuring how lens fabricators secure raw material and certify production batches.
Growth Catalysts
- Thermal Imaging Modernization:Night-vision system upgrades across NATO member states are accelerating orders for aspherical germanium optics. Defense contractors require surface accuracies below 100 nanometers for compact sight assemblies.
- REACH Compliance Services:RoHS exemption reviews for infrared optics create consulting demand for regulatory navigation. European lens suppliers differentiate through pre-certified material traceability documentation.
- China's Refining Dominance:Concentration of germanium tetrafluoride purification capacity in Yunnan and Inner Mongolia ensures feedstock availability for optical-grade metal production. Domestic polishers benefit from captive concentrate access.
Market Restraints
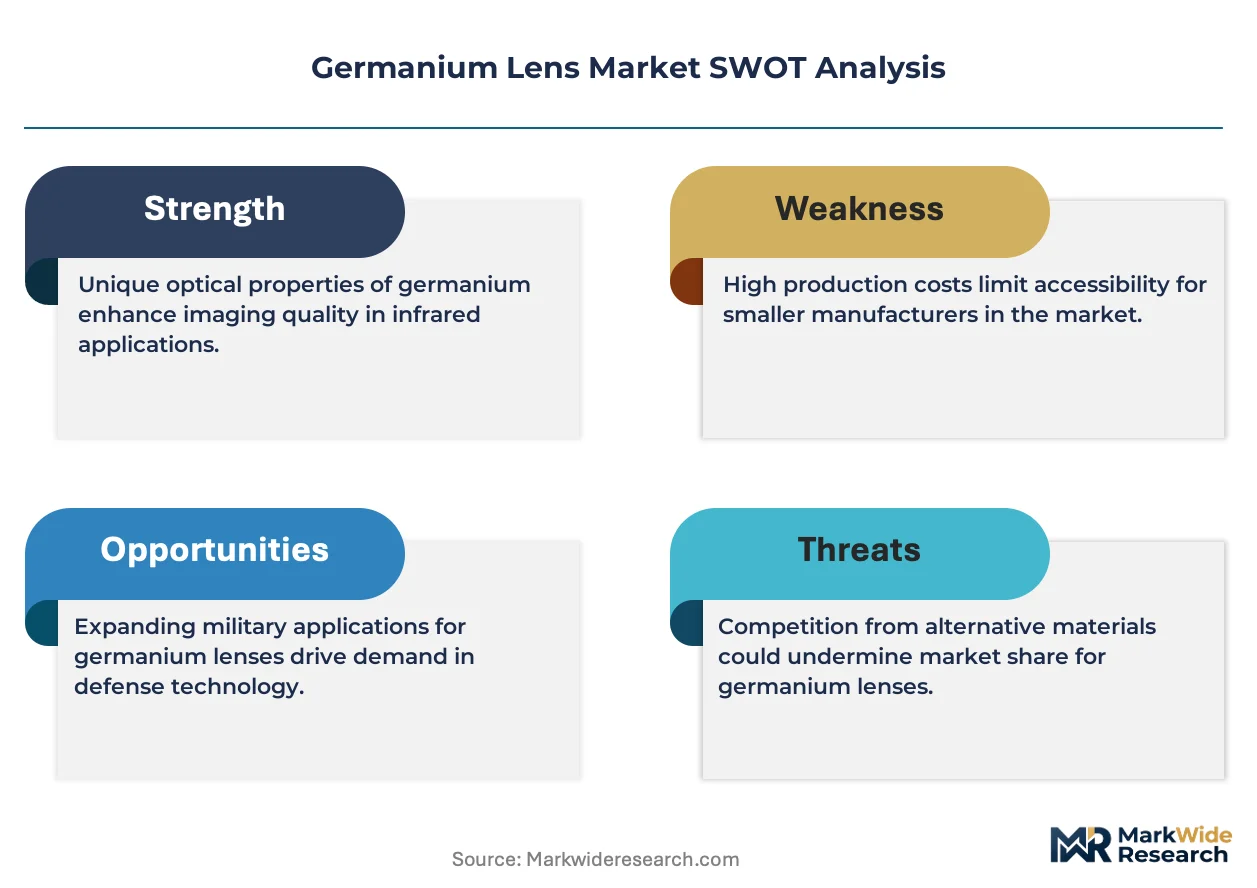
- Germanium Price Volatility:Zinc smelter byproduct supply fluctuations and photovoltaic sector competition for semiconductor-grade metal create input cost instability. Lens fabricators face margin compression during concentrate shortage periods.
- Single-Point Supply Risk:Over 60% of global germanium refining concentrates in Chinese state-affiliated entities. Non-Chinese optical houses confront qualification delays when diversifying feedstock sources.
- Chalcogenide Glass Substitution:Arsenic trisulfide and germanium-arsenic-selenide glasses transmit comparable infrared wavelengths at lower specific density. Weight-critical unmanned aerial vehicle payloads increasingly specify these alternatives.
Strategic Opportunities
- Medical Thermal Diagnostics:Non-contact fever screening and wound vascularization mapping expand addressable demand beyond traditional defense and industrial sensing. EMA Medical Device Regulation certification creates barrier-protected revenue pools.
- Precision Molding Convergence:Diamond-turned mold inserts enable high-volume replication of complex aspheric surfaces. Consumer automotive night-vision modules adopt molded germanium lenses at unit cost structures incompatible with single-point turning.
- India Defense Indigenization:Ministry of Defence production-linked incentive schemes for critical materials encourage joint ventures with established polishers. Domestic thermal sight manufacturing creates localized lens demand without ITAR transfer complications.
Industry Challenges
- Single-Point Diamond Turning Talent Scarcity:Master machinists capable of maintaining 50-nanometer form accuracy across infrared crystal materials command premium compensation. Training pipelines for precision optics craftsmanship remain underdeveloped outside Germany and Japan.
- ITAR Certification Timeline Compression:US State Department jurisdiction determinations for thermal imaging subcomponents now exceed 180 days for novel designs. Dual-use technology classification uncertainty delays international program participation.
- Coating Durability Qualification:Diamond-like carbon and anti-reflective stack adhesion under thermal cycling requires extended environmental testing. Military specification MIL-PRF-13830B compliance adds 12-18 months to new product introduction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germanium Lens Market |
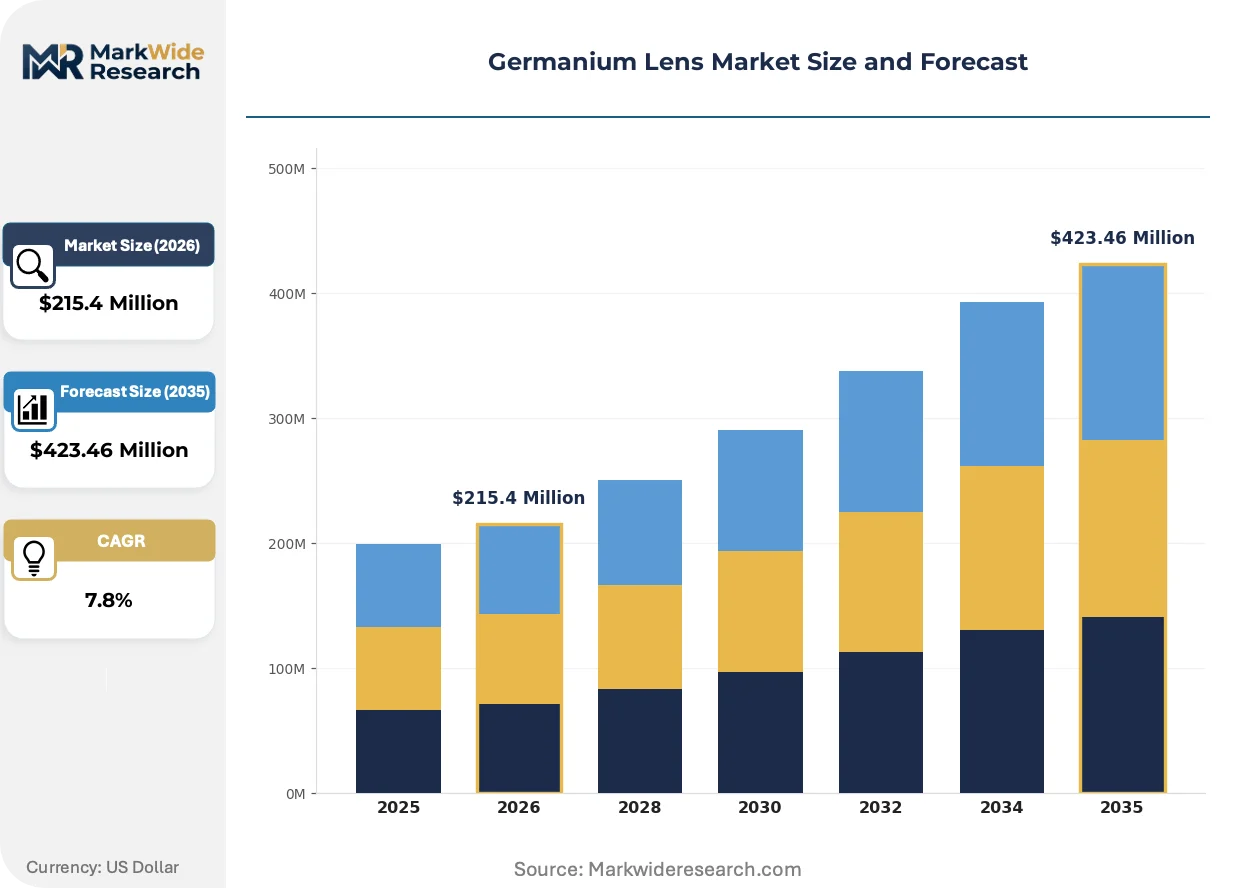
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $423.46 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspherical Lenses, Convex Lenses, Concave Lenses, Cylindrical Lenses Application: Thermal Imaging, Infrared Sensors, Optical Instruments, Military Applications End User: Aerospace, Defense, Healthcare, Industrial Manufacturing Stage: Raw Material Processing, Polishing, Assembly, Quality Control |
| Companies Covered | Umicore, Teck Resources Limited, China Germanium Co., Ltd., Indium Corporation, PPM Pure Metals GmbH, AXT, Inc., 5N Plus, JSC Germanium, Yunnan Chihong Zinc & Germanium Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germanium Lens Market Trends and Innovations
Diamond-turning automation and molded chalcogenide convergence are compressing traditional craftsmanship premiums while regulatory fragmentation across defense export controls forces modular product architectures. These shifts favor capital-intensive producers with in-house metrology capabilities.
Precision molding of germanium-silicon hybrid preforms is supplanting full-aperture single-point diamond turning for automotive night-vision camera objectives. Tier-1 automotive suppliers in Germany and Japan specify molded aspheres at annual volumes exceeding 50,000 units per platform. This process substitution collapses unit economics for mid-performance thermal optics while reserving diamond turning for defense-grade durability requirements.
EU F-Gas Regulation review timelines are extending refrigerant gas phase-out precedents to infrared optical material exemptions. European Commission deliberations on RoHS Annex III renewal for lead and cadmium in IR applications create planning uncertainty for lens houses serving medical device OEMs. German and French defense primes are accelerating qualification of cadmium-free chalcogenide alternatives to preempt 2026 restriction scenarios.
Integrated module procurement is consolidating discrete lens, detector, and electronics purchasing into single-source thermal camera contracts. Defense integrators in the United States and United Kingdom now specify performance outcomes rather than optical component specifications. This shift transfers design authority to subsystem vendors and compresses standalone lens supplier margins while expanding value capture for vertically integrated thermal engine providers.
Germanium Lens Market Segmentation
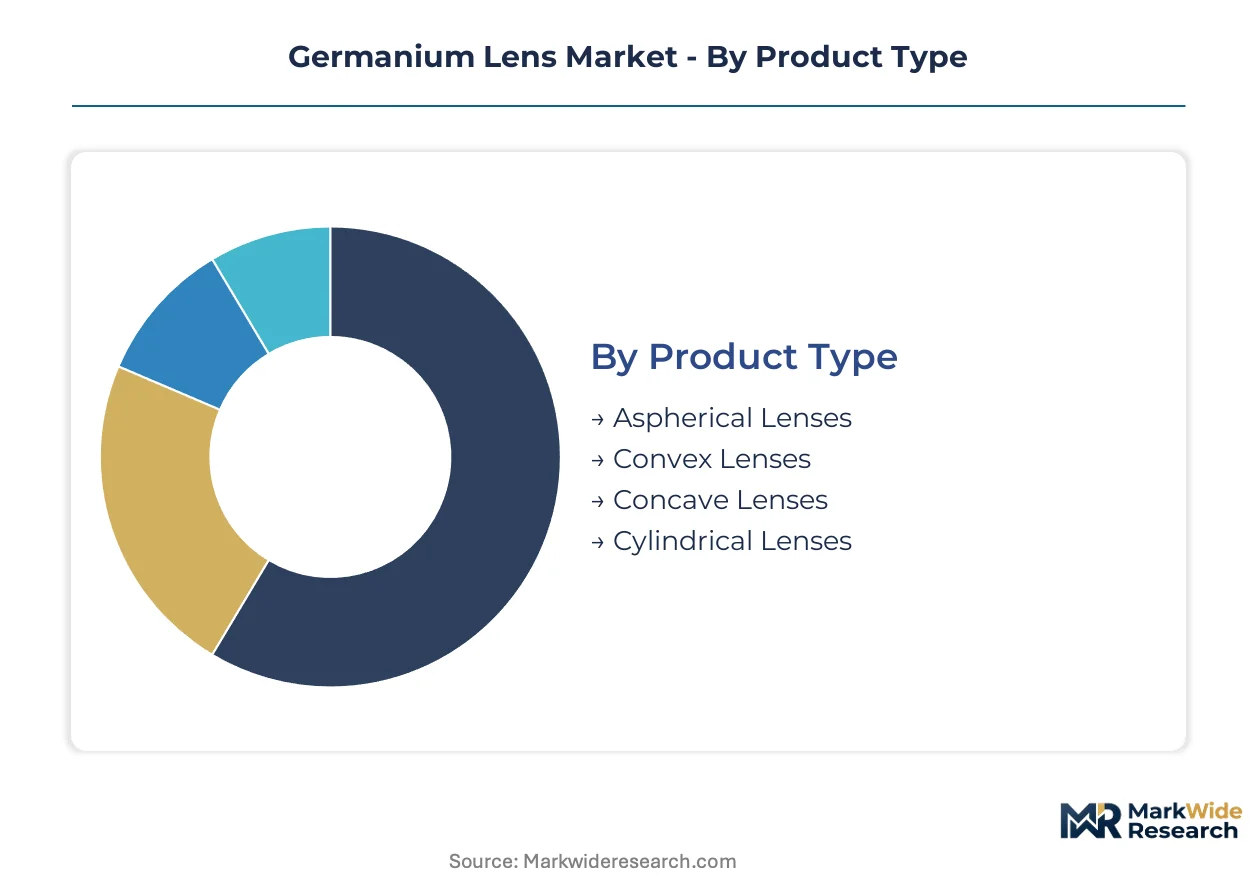
Germanium lens segmentation reveals how substitution pressures and manufacturing complexity concentrate value capture across distinct technical tiers. Each category exposes different vulnerability profiles to chalcogenide glass alternatives and automation-driven cost compression.
Product Type:
Chalcogenide glass substitution threatens spherical lens formats most severely while aspherical geometries retain defensible positioning through optical performance irreplaceability.
- Aspherical Lenses:Complex surface profiles correct aberrations without multiple elements, enabling compact thermal sight assemblies. Defense contractors in Germany and Japan specify these for NATO night-vision modernization programs where weight and packaging constraints override cost sensitivity.
- Convex Lenses:Simple positive meniscus designs concentrate infrared energy onto detector arrays. Industrial pyrometer manufacturers in the United States source these for non-contact temperature measurement systems where moderate optical performance suffices.
- Concave Lenses:Negative focal length elements expand beam divergence in laser rangefinder assemblies. Chinese domestic defense suppliers integrate these into localized thermal sight production lines.
- Cylindrical Lenses:Single-axis curvature corrects astigmatism in line-scan thermal imagers. Machine vision integrators deploy these for conveyor belt inspection systems in automotive manufacturing plants.
Convex lenses anchor the volume base while aspherical lenses gain share at the steepest rate.
Application:
Defense procurement cycles and medical device certification timelines create divergent margin structures across application segments.
- Thermal Imaging:Night-vision and surveillance systems transmit infrared wavelengths through germanium optics with minimal absorption. Military modernization programs in the United Kingdom and France drive specification tightening for surface accuracy below 100 nanometers.
- Infrared Sensors:Gas detection and spectroscopy applications exploit germanium's 2-14 micrometer transmission window. Industrial safety equipment manufacturers in Japan integrate these into refinery leak monitoring networks.
- Optical Instruments:Fourier-transform infrared spectrometers and thermal cameras for research laboratories demand high-purity substrates. Academic procurement channels in Germany sustain niche volume for precision optical houses.
- Military Applications:Durability testing under MIL-PRF-13830B environmental protocols commands extended qualification timelines. ITAR-controlled programs in the United States restrict supplier pools to domestically cleared fabricators.
Thermal imaging commands the revenue concentration while infrared sensors in industrial safety demonstrate the most rapid adoption acceleration.
End User:
Regulatory fragmentation across defense export controls and medical device pathways segments accessible supplier relationships.
- Aerospace:Satellite thermal control and earth observation payloads specify radiation-hardened germanium optics. European Space Agency programs source through qualified supply chains subject to REACH material traceability requirements.
- Defense:Land vehicle and soldier-mounted sight systems dominate procurement volume. India's Ministry of Defence production-linked incentive schemes attract joint venture formation with established polishers.
- Healthcare:Non-contact fever screening and wound vascularization mapping expand diagnostic applications. EMA Medical Device Regulation certification creates barrier-protected revenue pools for compliant suppliers.
- Industrial:Process monitoring and predictive maintenance systems deploy thermal imaging for equipment health assessment. German automotive manufacturers specify molded germanium lenses for night-vision camera modules at volumes exceeding 50,000 units annually.
Defense procurement anchors current volume while healthcare thermal diagnostics climbs the fastest toward commercial scale.
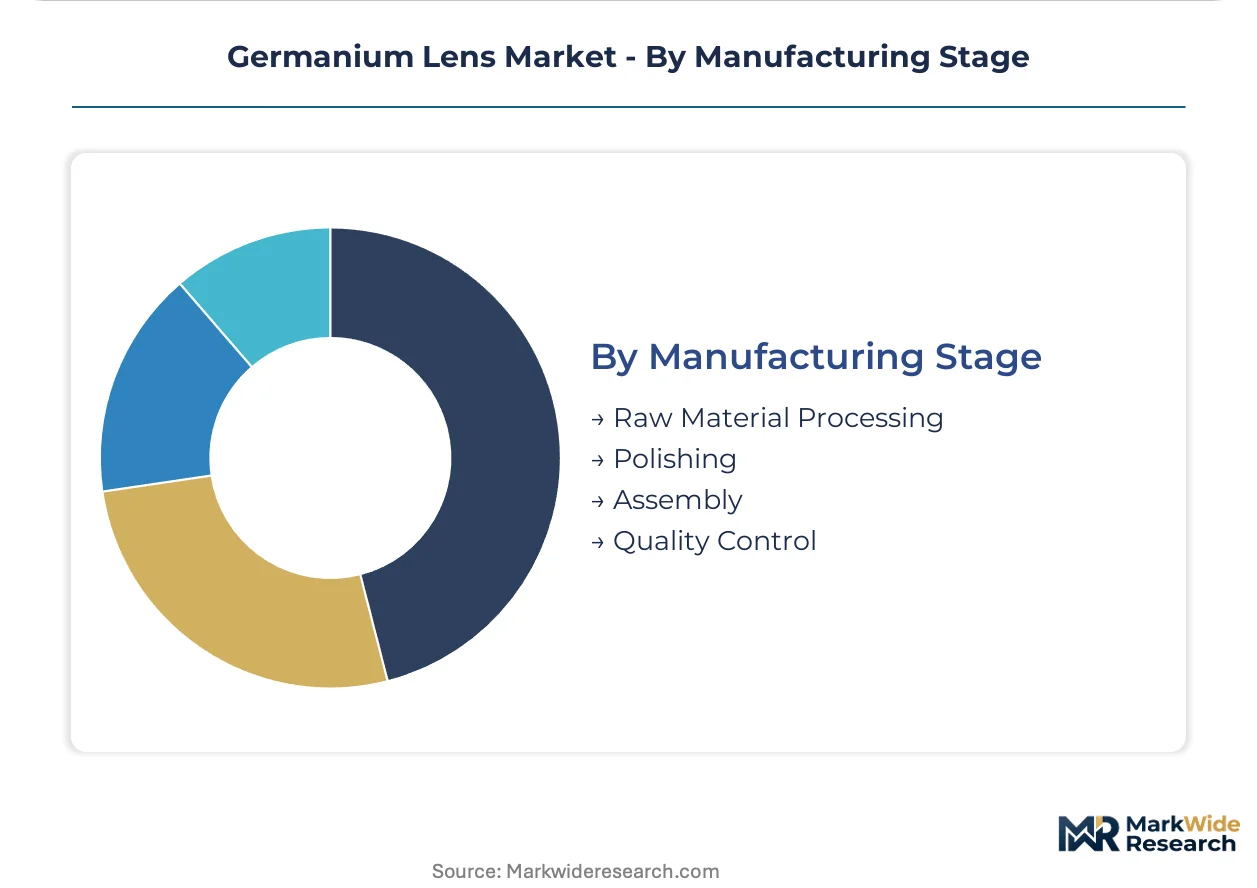
Manufacturing Stage:
Capital intensity divergence between upstream refining and downstream polishing reorganizes competitive tiers.
- Raw Material Processing:Germanium tetrafluoride purification from zinc smelter byproducts concentrates in Yunnan and Inner Mongolia facilities. Chinese state-affiliated entities control over 60% of global refining capacity.
- Polishing:Single-point diamond turning achieves surface accuracies below 50 nanometers for defense-grade specifications. Master machinists capable of maintaining this precision command premium compensation in Germany and Japan.
- Assembly:Detector integration and thermal camera module construction transfers design authority to subsystem vendors. Tier-1 automotive suppliers in Germany consolidate lens, detector, and electronics purchasing into single-source contracts.
- Quality Control:Environmental testing for coating durability under thermal cycling extends product introduction schedules. MIL-PRF-13830B compliance adds 12-18 months to military qualification pathways.
Polishing operations capture the margin premium while assembly stages face the steepest compression from integrated module procurement trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in Germany tolerates extreme price premiums for sub-100-nanometer surface accuracy, while industrial buyers in China prioritize volume scalability over optical tolerances. Healthcare segments in Japan and the United States occupy intermediate elasticity positions where EMA and FDA certification costs filter price-sensitive entrants.
Germany
NATO night-vision modernization programs drive specification tightening for aspherical germanium optics in compact sight assemblies. KBA automotive safety standards accelerate molded lens qualification for premium vehicle night-vision modules. Precision optics clusters in Jena and Oberkochen host diamond-turning workshops serving Bundeswehr contractors.
China
Domestic defense indigenization and thermal sight localization expand captive demand for optical-grade germanium. SAMR oversight of critical material stockpiles influences concentrate allocation between photovoltaic and optical applications. Yunnan and Inner Mongolia refining complexes supply tetrafluoride purification capacity to polishers in Jiangsu and Zhejiang.
United States
ITAR-controlled thermal imaging subcomponents restrict supplier pools to domestically cleared fabricators, sustaining premium pricing tiers. State Department jurisdiction determinations now exceed 180 days for novel dual-use designs. Arizona and Florida defense corridors concentrate subsystem integrators specifying performance outcomes rather than discrete optical components.
Japan
Industrial pyrometer manufacturers and refinery leak monitoring networks sustain demand for convex lens formats. METI technology roadmaps prioritize chalcogenide glass substitution research for weight-critical unmanned payloads. Nagoya and Osaka precision manufacturing belts host master machinists commanding premium compensation for 50-nanometer form accuracy maintenance.
India
Ministry of Defence production-linked incentive schemes for critical materials encourage joint venture formation with established polishers. DGFT import substitution policies accelerate domestic thermal sight manufacturing capacity. Tamil Nadu and Telangana defense corridors attract lens fabricators seeking ITAR-free market access.
Germanium Lens Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Germanium Lens Market. Umicore leverages upstream metal refining through precision optics to sustain margin capture across multiple value chain stages. China Germanium Co., Ltd. and Yunnan Chihong Zinc & Germanium Co., Ltd. anchor supply security through captive concentrate access. Competitive repositioning concentrates on backward integration into tetrafluoride purification and precision molding capacity expansion for automotive volumes.
Among integrated refiners, Umicore exemplifies vertical control from zinc smelter byproduct recovery through optical-grade metal output. China Germanium Co., Ltd. occupies a position representing state-affiliated supply security. 5N Plus sits within the high-purity specialist tier competing on semiconductor-grade metal specifications for infrared substrate applications.
| Leading Market Players |
|---|
| Umicore |
| Teck Resources Limited |
| China Germanium Co., Ltd. |
| Indium Corporation |
| PPM Pure Metals GmbH |
| AXT, Inc. |
| 5N Plus |
| JSC Germanium |
| Yunnan Chihong Zinc & Germanium Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Yunnan refiners and German optical houses lock in both tetrafluoride concentrate access and price visibility across volatile zinc smelter byproduct cycles. These arrangements insulate defense contractors from spot market spikes while binding polishers to minimum volume commitments that shape capacity planning.
Pricing Analysis
After-sales service contracts for coating refurbishment and recalibration drive lifetime value capture beyond initial lens shipments. Three-tier pricing structure across ITAR-cleared defense, EMA-certified medical, and industrial pyrometer tiers separates qualification-burdened premiums from volume-scaled automotive molded lenses. Cost compression in consumer automotive night-vision modules is intensifying because precision molding displaces diamond-turned craftsmanship at 50,000-unit annual volumes. Defense integrators exhibit least price sensitivity due to MIL-PRF-13830B durability mandates, while industrial equipment OEMs face procurement pressure from chalcogenide glass substitution.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on the Asia-Europe trade lane periodically delay optical-grade metal shipments to Jena and Oberkochen polishing clusters. Supply concentrates in China, Belgium, and Canada, with Chinese state-affiliated entities controlling tetrafluoride purification and Umicore anchoring European metal output. Raw material dependencies rest on zinc smelter byproduct streams, high-purity chlorine gas for reduction, and single-crystal growth crucibles. Tariff exposure on Chinese-sourced concentrate creates qualification delays for non-Chinese optical houses diversifying feedstock. Distribution runs through defense prime contractor integration, medical device OEM direct procurement, and Tier-1 automotive supplier consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision molding convergence and REACH substance restrictions are reshaping competitive positioning in a market where craftsmanship premiums face automation-driven compression. This dual inflection creates asymmetric opportunity for capital-intensive producers with in-house metrology capabilities.
For Market Incumbents: Compound backward integration into tetrafluoride purification to secure concentrate allocation against photovoltaic sector competition. Expand precision molding capacity in Germany or Japan to capture automotive night-vision volumes exceeding 50,000 units annually. Chalcogenide glass substitution in weight-critical UAV payloads threatens spherical lens margins; defend aspherical positioning through sub-50-nanometer form accuracy investments.
For New Entrants and Emerging Players: Anchor in India's Ministry of Defence production-linked incentive corridors to bypass ITAR transfer complications and supply localized thermal sight manufacturers. Target EMA Medical Device Regulation certification for non-contact fever screening applications where barrier-protected revenue pools filter price-sensitive competitors. Pursue joint venture structures with established Yunnan refiners to secure captive concentrate access without greenfield purification investment.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive refining and diamond-turning craftsmanship depth. Long-term viability hinges on positioning upstream of chalcogenide substitution pressure and downstream of defense procurement consolidation into integrated thermal engine contracts. Monitor EU F-Gas Regulation and RoHS Annex III renewal timelines as inflection indicators for cadmium-free chalcogenide qualification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tetrafluoride Purification | Captive concentrate access insulates margin capture against zinc smelter byproduct volatility and photovoltaic sector competition. |
| Precision Molding Capacity Expansion | Automotive night-vision modules at 50,000-unit volumes demand molded aspheres incompatible with single-point diamond turning economics. |
| EMA Medical Device Regulation Certification | Pre-certified material traceability documentation creates barrier-protected revenue pools in non-contact fever screening applications. |
| India Defense Corridor Joint Venture Formation | Ministry of Defence PLI schemes enable ITAR-free market access for localized thermal sight manufacturing supply. |
| Cadmium-Free Chalcogenide Alternative Qualification | Preemptive 2026 restriction scenario planning addresses EU RoHS Annex III renewal uncertainty for medical device OEMs. |
Research Methodology
The analysis maps raw material processing, precision polishing, and integrated module assembly stages, each validated through primary interviews with zinc smelter procurement leads, diamond-turning workshop managers, defense prime contractor optical engineers, and EMA regulatory affairs specialists. Secondary validation draws from REACH substance restriction filings, SAMR critical material stockpile disclosures, SEC 10-K filings from listed refiners, and Bundeswehr procurement contract announcements. Bottom-up volume estimates from polishing capacity utilization and top-down demand segmentation from defense budget allocations were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type complexity, application durability requirements, end-user regulatory pathways, and manufacturing stage capital intensity as segmentation dimensions. CAGRs were derived from defense procurement cycle analysis, automotive platform adoption curves, and medical device certification timeline compression. Industry-specific forecast inputs include ITAR jurisdiction determination backlogs and EU F-Gas Regulation review timelines.
Decision-makers should treat outputs as directional under assumptions of sustained NATO night-vision modernization budgets and stable zinc smelter byproduct supply; material deviation would warrant model refresh. Specific risks include REACH substance restriction acceleration, Chinese concentrate export quota adjustments, and chalcogenide glass technical performance breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
US Photonics Market
Optics
MEMS Mirrors Market
Optics
Collimating Lens Market
Optics
Fiber-Optic Couplers Market
Optics
Optical Wavelength Service Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Fiber Optic Development Tools Market
Optics
Picosecond Lasers Market
Optics
Global Nanophotonics Market
Optics
Digital Holographic Microscopy Market
Optics
Optical Fiber Raw Material Market
Optics
Europe Laser Interferometer Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Interchangeable Lens Market
Optics
Stroboscope Market
Optics
Fiber Optics Market