
 Photostimulation Lasers Market | 2026-2036
Photostimulation Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Photostimulation Lasers Market Intelligence
Recurring revenue from software licenses and clinical support contracts is reconfiguring the traditional hardware-centric business model. Zimmer MedizinSysteme specializes in integrated systems for rehabilitation therapy, combining laser units with diagnostic software. BTL International leverages its extensive distribution network to supply clinical facilities across Europe and North America. EMS Physio differentiates through a focus on portable devices for pain management applications.
Photostimulation lasers are coherent light sources designed to precisely activate or inhibit light-sensitive biological cells. These systems often utilize specific wavelengths, such as 473 nm blue light, to control genetically modified neurons in optogenetics research. Diode lasers command a significant share of the product landscape due to their compact size, reliability, and cost-efficiency. Neuroscience research represents the fastest-growing application, with clinical facilities driving volume in pain management and rehabilitation therapy.
Market access hinges on compliance with medical device regulations, including FDA 510(k) clearance in the United States and CE marking under the EU's Medical Device Regulation (MDR). These frameworks mandate extensive clinical data for therapeutic claims, governing market entry for pain management and rehabilitation systems. The key strategic decision for manufacturers is balancing investment between pioneering neuroscience applications and navigating the validation pathways for broader clinical use.
Market Dynamics
The market's primary dynamic is the strategic divergence between high-value, niche neuroscience applications and the volume-driven, highly regulated clinical therapy segment. This forces manufacturers to choose between pioneering research tools or pursuing broader, validated medical device pathways for pain management and rehabilitation.
Growth Catalysts
- Neuroscience Funding Initiatives:Government-backed research programs in the United States and Europe provide significant, non-dilutive capital for academic labs to procure advanced photostimulation systems for neural circuit mapping.
- Pulsed Laser Advancements:Improvements in the precision and stability of pulsed laser technology enable more complex optogenetics experiments, expanding the addressable scope of neuroscience research applications.
- Expanding Clinical Evidence:A growing body of clinical data supporting the efficacy of photostimulation in pain management and rehabilitation therapy encourages adoption by mainstream clinical facilities.
Market Restraints
- High System Cost:The significant initial capital investment required for integrated laser systems, particularly those combined with diagnostic software, acts as a barrier for smaller research labs and private clinics.
- Stringent Regulatory Pathways:The extensive clinical data and documentation required for FDA 510(k) clearance and CE marking under the MDR create long and costly development cycles for therapeutic devices.
- Technical Expertise Requirement:Operating advanced photostimulation systems for optogenetics demands specialized training in both laser physics and neurobiology, limiting use to highly skilled personnel in dedicated research centers.
Strategic Opportunities
- Portable Device Development:Engineering compact, user-friendly lasers for pain management opens opportunities in decentralized clinical trials and the home-care market, moving beyond traditional clinic-based therapy.
- Recurring Revenue Models:Expanding software-as-a-service (SaaS) offerings for data analysis and clinical support provides a stable, recurring revenue stream that complements hardware-centric sales.
- Untapped Clinical Indications:Exploring and validating new therapeutic applications beyond pain and rehabilitation, such as in dermatology or veterinary medicine, could unlock new market segments.
Industry Challenges
- Interdisciplinary Talent Gaps:A scarcity of technicians and scientists possessing the combined expertise in optical engineering, software development, and clinical neuroscience hinders system deployment and innovation.
- Lack of Protocol Standardization:The absence of universally accepted treatment protocols for clinical applications complicates the comparison of study outcomes, slowing regulatory approval and broader clinical acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photostimulation Lasers Market |
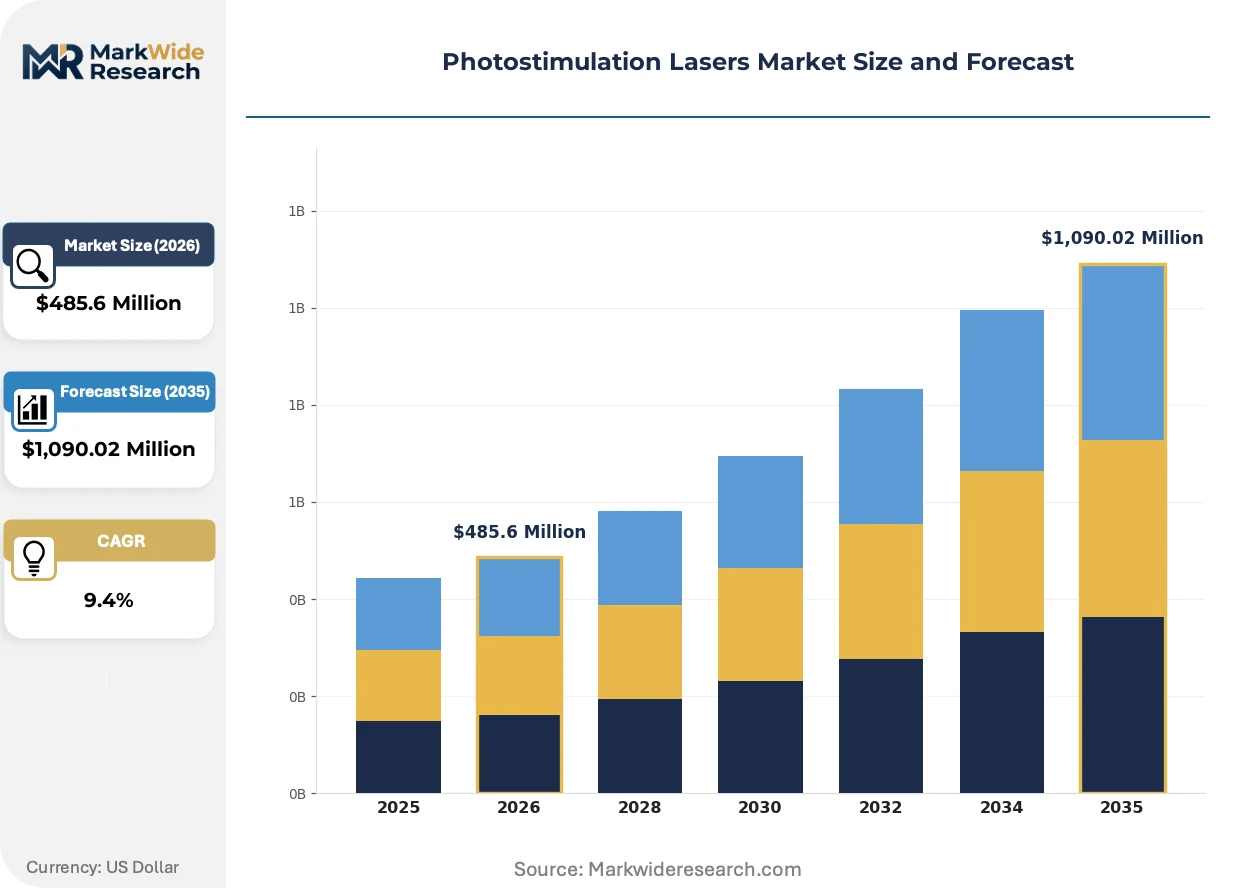
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,090.02 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Fiber Lasers, Solid-State Lasers, Gas Lasers Application: Neuroscience Research, Pain Management, Rehabilitation Therapy, Animal Studies End User: Research Institutions, Clinical Facilities, Veterinary Clinics, Pharmaceutical Companies Technology: Pulsed Laser, Continuous-Wave Laser, Q-Switched Laser, Tunable Laser |
| Companies Covered | Chattanooga International, BTL International, Elettronica Pagani, EMS Physio, GymnaUniphy, Astar, RIKTAMED, Mettler Electronics, Zimmer MedizinSysteme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photostimulation Lasers Market Strategic Shifts & Innovations
Convergence of hardware, software, and clinical services is recasting the market's value proposition. The business model is shifting from one-time equipment sales towards integrated systems supported by recurring revenue from software and support contracts, which is reshaping competitive positioning.
Closed-loop systems integrate laser sources with real-time biofeedback sensors for automated parameter adjustment. Advanced clinical facilities and neuroscience research consortia are the primary adopters. The standalone laser hardware is hybridizing with diagnostic software platforms, compressing the value of hardware alone and creating intelligent, responsive therapeutic devices.
The European Union's Medical Device Regulation (MDR) elevates requirements for clinical data and post-market surveillance. This regulation substantially increases the cost and timeline for bringing new therapeutic laser systems to market. Manufacturers targeting pain management and rehabilitation applications are most affected, now needing more extensive clinical trials to support their claims.
A preference for service-based agreements over direct capital expenditure is altering procurement patterns. This model challenges the traditional one-time hardware sale, favoring vendors who offer comprehensive clinical support and software updates. The shift is most pronounced in large hospital networks across North America and Europe seeking predictable operational costs and guaranteed uptime.
Photostimulation Lasers Market Segmentation
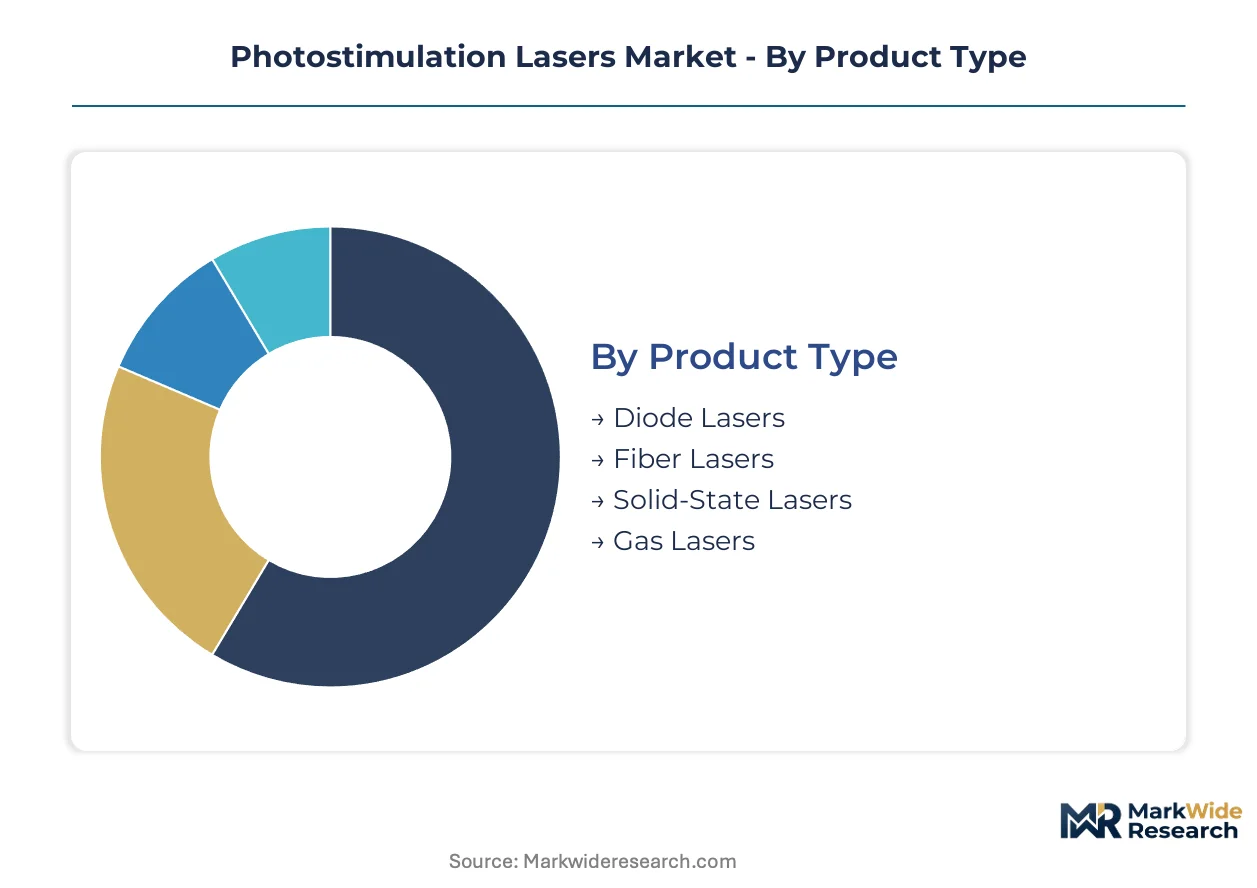
Understanding the Photostimulation Lasers Market through its distinct segments is essential for identifying specific demand drivers and technological shifts. This segmentation analysis provides a granular view of product types, applications, end users, and underlying technologies, guiding strategic investment and product development efforts within this specialized domain.
Product Type:
The product type segmentation reveals varying lifecycles and adoption rates for different laser technologies, reflecting their maturity and integration into research and clinical workflows.
- Diode Lasers:These compact, energy-efficient semiconductor lasers are widely adopted for their reliability and cost-effectiveness, commanding a significant share of the product landscape. Demand concentrates in both research settings and clinical facilities due to their versatility and low operational costs.
- Fiber Lasers:Fiber lasers offer excellent beam quality and high power output, making them suitable for demanding applications requiring precise control and stability. Their use is expanding in advanced neuroscience research for complex neural circuit mapping experiments.
- Solid-State Lasers:These lasers, often optically pumped, provide high power and a range of wavelengths, traditionally used in research and some industrial applications.
- Gas Lasers:Gas lasers, such as argon-ion or helium-neon, offer specific wavelengths and high coherence, though they are generally larger and have higher power consumption.
Diode Lasers dominate the installed base due to their widespread utility. Fiber Lasers are where expansion concentrates for high-precision, advanced applications.
Application:
Application segments highlight the diverse end-uses for photostimulation lasers, ranging from fundamental scientific inquiry to therapeutic interventions, each with distinct market dynamics and regulatory pathways.
- Neuroscience Research:This segment involves the precise activation or inhibition of genetically modified neurons using light, primarily for mapping neural circuits and understanding brain function. Demand is particularly strong in academic research clusters within the United States and Germany, driven by significant government funding initiatives.
- Pain Management:Photostimulation lasers are employed in rehabilitation therapy to alleviate chronic and acute pain through non-invasive light exposure, leveraging anti-inflammatory and analgesic effects. Clinical facilities are driving volume adoption as expanding clinical evidence supports treatment efficacy.
- Rehabilitation Therapy:This application focuses on accelerating tissue repair, reducing inflammation, and improving mobility in patients recovering from injury or surgery. Adoption in mainstream clinical settings is growing due to a rising body of supportive clinical data.
- Animal Studies:Photostimulation lasers are used in preclinical research involving animal models to investigate neurological disorders, behavioral science, and drug discovery.
Neuroscience Research holds the largest share of innovation. Pain Management applications are gaining traction most rapidly in clinical adoption.
End User:
The end-user segmentation delineates the primary organizations procuring photostimulation laser systems, each with unique procurement processes, budget cycles, and technical requirements.
- Research Institutions:Universities, academic hospitals, and government-funded laboratories utilize these systems for basic and translational neuroscience research, often supported by grants. Procurement patterns favor advanced, high-precision systems for complex experimental setups.
- Clinical Facilities:Hospitals, physiotherapy clinics, and rehabilitation centers deploy photostimulation lasers for patient therapy in pain management and rehabilitation. Procurement often involves balancing initial capital cost with long-term operational efficiency and patient throughput.
- Veterinary Clinics:These facilities use photostimulation lasers for pain relief, wound healing, and rehabilitation in animal patients.
- Pharmaceutical Companies:Biopharmaceutical firms leverage photostimulation systems in drug discovery and development, particularly for neurological and pain-related research.
Research Institutions represent the primary adopters of cutting-edge systems. Clinical Facilities are strategically important for market volume and broader patient access.
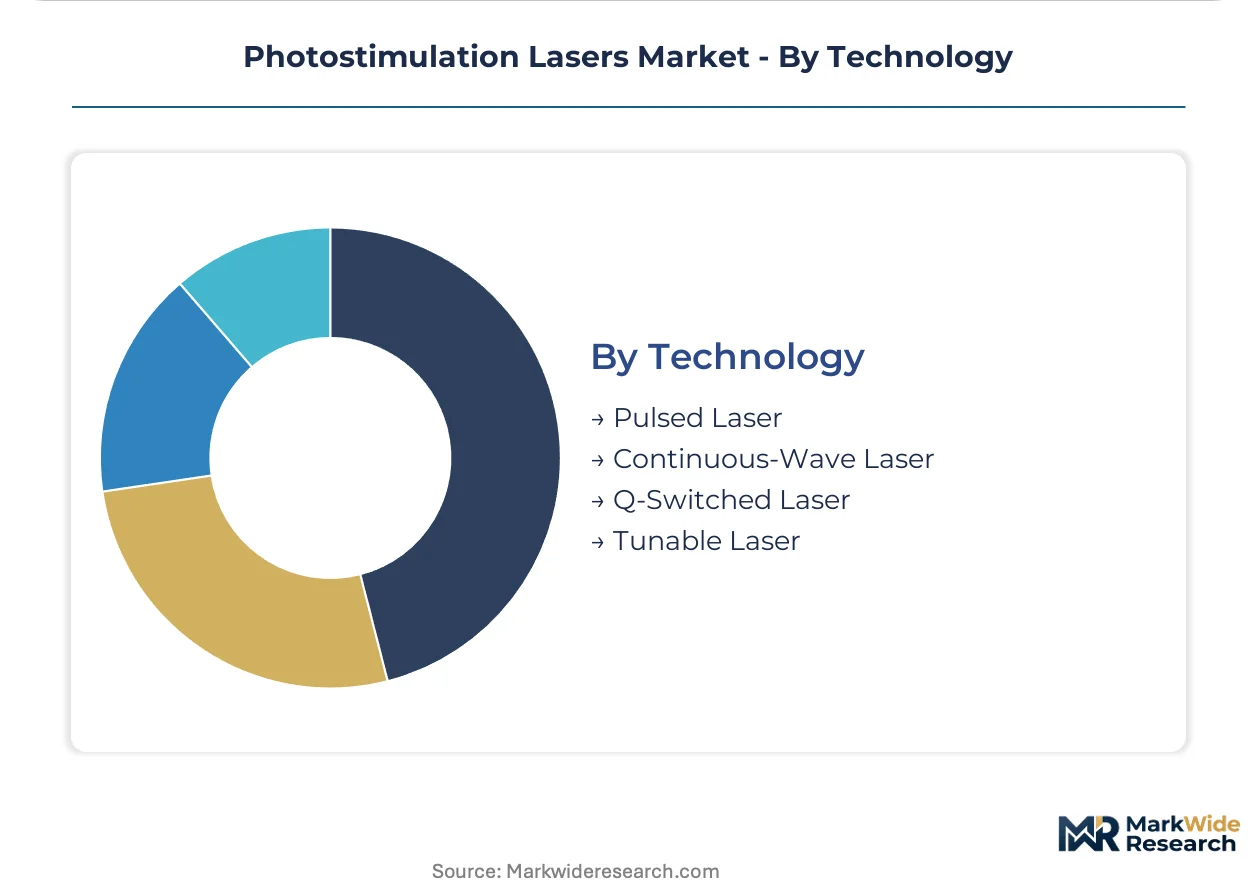
Technology:
Technology segmentation categorizes photostimulation lasers based on their operational characteristics, influencing their suitability for specific research protocols and clinical applications.
- Pulsed Laser:These lasers deliver light in short, high-intensity bursts, enabling precise temporal control over neural activity and reducing thermal effects in biological tissues. Advancements in pulsed laser technology are expanding the scope of complex optogenetics experiments.
- Tunable Laser:Tunable lasers allow for the adjustment of output wavelength across a specific range, providing flexibility for experiments requiring activation of different light-sensitive proteins or chromophores. Their application is critical in advanced multi-color optogenetics and spectroscopy.
- Continuous-Wave Laser:Continuous-wave lasers emit a constant beam of light, suitable for applications requiring prolonged illumination or where temporal precision is less critical.
- Q-Switched Laser:Q-switched lasers produce extremely short, high-peak-power pulses, often used in applications requiring precise ablation or non-linear optical effects.
Pulsed Laser technology currently drives the most significant research advancements. Tunable Laser systems are becoming increasingly vital for experimental versatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for photostimulation lasers is evident in established research hubs and advanced medical technology markets. These regions also exhibit strong demand for both cutting-edge neuroscience tools and validated clinical therapy systems. Regulatory frameworks and government funding initiatives significantly influence market development across these key geographies.
United States
Neuroscience research funding and expanding clinical trials for pain management drive demand for photostimulation lasers. The FDA 510(k) clearance process governs market entry for therapeutic devices, requiring extensive data. Major research institutions in the Boston area and San Francisco Bay Area lead advancements in optogenetics applications.
Germany
Academic collaborations and the strong adoption of rehabilitation therapy applications underpin market growth in Germany. CE marking under the EU's Medical Device Regulation (MDR) sets high standards for clinical evidence and post-market surveillance. Research clusters in Munich and Berlin actively contribute to novel photostimulation techniques.
Japan
Advanced photonics research and an aging population requiring rehabilitation services contribute to photostimulation laser demand. PMDA medical device approvals emphasize safety and efficacy for clinical systems. Tokyo's research universities and Kyoto's precision instrumentation manufacturers are central to technological development.
United Kingdom
Government-backed research programs and a growing body of clinical evidence for pain management applications propel the market in the United Kingdom. The MHRA medical device registration process ensures compliance for therapeutic devices. The Cambridge Biomedical Campus and London's clinical research centers foster innovation and adoption.
China
Increasing healthcare investment and rapid expansion of research infrastructure are accelerating the adoption of photostimulation lasers. NMPA medical device regulations are becoming more stringent, influencing market access for foreign manufacturers. Research parks in Shanghai and academic institutions in Beijing are key centers for technology integration.
Photostimulation Lasers Market Key Industry Players
Vertically integrated hardware manufacturers and specialized software developers split the market for photostimulation lasers. A tiered structure emerges, with established players focusing on comprehensive integrated systems and agile innovators targeting niche applications. Strategic partnerships for technology integration and geographic expansion are dominant competitive moves.
Integrated system providers such as Zimmer MedizinSysteme occupy a position focused on comprehensive rehabilitation therapy, often combining laser units with diagnostic software. BTL International leverages its extensive distribution network to supply clinical facilities across Europe and North America, emphasizing market reach. EMS Physio differentiates through a focus on portable devices for pain management applications, catering to decentralized clinical settings.
| Leading Market Players |
|---|
| Chattanooga International |
| BTL International |
| Elettronica Pagani |
| EMS Physio |
| GymnaUniphy |
| Astar |
| RIKTAMED |
| Mettler Electronics |
| Zimmer MedizinSysteme |
| Others |
Cost & Logistics Intelligence
Kyoto's precision instrumentation manufacturers, central to advanced photostimulation laser development, influence downstream pricing power for high-end systems. Their specialized capacity and technological leadership shape market entry costs for complex devices.
Pricing Analysis
CE marking under the EU's Medical Device Regulation (MDR) dictates the pricing tier structure for therapeutic photostimulation lasers. The market primarily features a hybrid model, combining initial hardware sales with recurring software-as-a-service and support contracts. Price differentiation stems from system integration levels, particularly diagnostic software bundling, and device portability for decentralized applications. Pricing pressure stems from extensive regulatory compliance costs and the need for significant clinical validation. Smaller private clinics exhibit the highest price sensitivity, while major research institutions prioritize advanced features over initial capital outlay.
Supply Chain Analysis
Export control regimes on advanced photonics components limit the free flow of critical technologies, impacting photostimulation laser supply chains. Manufacturing concentrates in the United States, Germany, and Japan for high-precision optical components and specialized diode laser modules. The industry depends on semiconductor substrates and specialized optical fibers for high-power fiber lasers. Single-source vulnerability for these highly specialized components presents a notable supply chain risk. Distribution largely runs through established networks of specialized medical device distributors and direct sales teams targeting research institutions and clinical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photostimulation lasers market presents a fragmentation opportunity, driven by the demand-side shift towards portable devices for decentralized pain management. This creates distinct niches for specialized solutions beyond integrated research systems.
For Market Incumbents: Insulate core integrated system offerings by deepening software-as-a-service (SaaS) integration and expanding clinical support contracts. This strategy mitigates threats from agile innovators targeting niche, hardware-only applications. Invest heavily in FDA 510(k) and CE marking certification pathways to validate therapeutic claims for broader clinical adoption. Control distribution channels in key regional markets to maintain market share against new entrants.
For New Entrants and Emerging Players: Underpenetration in the home-care market represents a significant opportunity for new entrants. Target the rapidly expanding clinical therapy segment in China with cost-effective, portable devices for pain management. Focus on developing user-friendly interfaces and offering bundled service agreements to reduce the technical expertise barrier for smaller clinics. Validate novel clinical indications beyond rehabilitation to unlock new market segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized firms with advanced pulsed and tunable laser intellectual property. The market's long-term viability hinges on continued expansion in neuroscience research and broader clinical adoption. Acquire companies possessing unique laser-biofeedback integration capabilities or strong regulatory approval portfolios. The signal to watch for inflection is the increasing number of FDA and CE-marked therapeutic devices for novel applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Service Expansion | This provides stable, recurring revenue streams and enhances customer loyalty for hardware providers. |
| Portable Device Launch | Unlocking decentralized clinical trials and the growing home-care market expands patient access. |
| Clinical Trial Investment | Generating extensive data supports regulatory approvals and broadens therapeutic claims for new indications. |
| Closed-Loop System Integration | Enhancing precision and automation in therapy delivery improves patient outcomes and operational efficiency. |
| Geographic Market Entry in China | Tapping into accelerating healthcare investment and expanding research infrastructure drives volume growth. |
Research Approach
Operator-level perspectives from neuroscience researchers, clinical facility managers, medical device engineers, and regulatory affairs specialists anchored the qualitative base. This study combined primary interviews with extensive secondary validation from academic journals, FDA 510(k) filings, and EU MDR guidelines. A bottom-up data aggregation and top-down market sizing approach ensured comprehensive market understanding.
Scenario-bracketing provided a robust framework for projecting photostimulation laser market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, technology, and regional regulatory environment. Compound annual growth rates were derived from historical adoption trends and projected technology advancements. Neuroscience funding levels and clinical trial success rates served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized component manufacturers or integrated system providers would shift outcomes. This analysis assumes current regulatory frameworks and technological trajectories persist. Material shifts in medical device regulations for novel therapeutic applications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Lasers Market
Optics
Photonic Crystals Market
Optics
Optical Imaging Market
Optics
Fiber Optic Cable Market
Optics
Fiber-Optic Filters Market
Optics
Beam Combining Optics Market
Optics
Optical Measuring Systems Market
Optics
Fiber Optics Market
Optics
Liquid Crystal on Silicon Market
Optics
APAC Smart Glass Market
Optics
Germanium Lens Market
Optics
Fiber Optic Development Tools Market
Optics
Global Fiber Optic Components Market
Optics
Photonics Market
Optics
Fiber-Optic Couplers Market
Optics
Solid State Lasers Market