
 Camera Lens Market | 2026-2036
Camera Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Lens Market Analysis
Asset-light leasing models for cinema-grade glass are rewriting competitive access in professional videography. Canon leverages its captive foundry network to sustain margin control across prime and zoom lines. Sony anchors high-end cinematography through exclusive E-mount partnerships with rental houses. Sigma differentiates by occupying the third-party autofocus niche that major OEMs leave exposed.
A camera lens is an optomechanical assembly of ground glass or synthetic elements, coated with anti-reflective compounds such as magnesium fluoride, that focuses electromagnetic radiation onto an image plane for capture or projection. Its primary commercial purpose spans consumer imaging, industrial inspection, security surveillance, and scientific instrumentation. Zoom lenses currently dominate unit volume in consumer channels, while prime lenses command the margin pool among professional photographers seeking maximum aperture performance. Surveillance applications are expanding fastest in municipal and enterprise security deployments, with telephoto variants gaining share in perimeter monitoring systems.
Japan's METI enforces JIS standards on optical precision that constrain import eligibility for uncertified manufacturers. The EU RoHS and REACH frameworks restrict hazardous substances in lens coatings and barrel alloys, reshaping material selection across Asian supply chains. China's SAMR administers GB standards for surveillance equipment that gate domestic procurement. Stakeholders must monitor how dual-use export controls on precision optics alter cross-border sourcing strategies.
Market Dynamics
Computational optics from smartphone manufacturers is virtualizing image capture for casual photographers, collapsing the addressable base for standalone consumer lenses while elevating performance expectations for professional-grade glass.
Growth Catalysts
- Surveillance infrastructure mandates:China's GB standards for municipal security procurement are accelerating telephoto lens deployment in perimeter monitoring systems across smart city projects.
- Computational imaging convergence:Machine learning algorithms paired with multi-element arrays are expanding depth-of-field control in smartphone cameras, pulling R&D investment toward hybrid optical-digital systems.
- Japan's precision manufacturing standards:METI-enforced JIS tolerances are creating certified supplier tiers that lock in premium pricing for qualified optical houses.
Market Restraints
- Rare earth element concentration:Lanthanum and tantalum supply chains cluster in Chinese processing facilities, exposing lens manufacturers to input volatility and export licensing friction.
- Optical glass melting capacity:High-index flint and crown glass production requires specialized continuous-melting furnaces concentrated among three Japanese and German suppliers.
- Smartphone substitution curve:Computational photography from Apple and Samsung devices satisfies 80% of casual imaging needs without dedicated lens purchases.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for camera module assembly are attracting lens mount and barrel manufacturers to Chennai and Noida industrial corridors.
- Asset-light rental channels:Cinema-grade glass leasing through specialized rental houses unlocks professional access without capital purchase, expanding addressable users in independent filmmaking.
- EU Green Deal material mandates:REACH restrictions on hexavalent chromium coatings are creating first-mover advantage for manufacturers with certified eco-coating lines.
Industry Challenges
- Optical design software licensing:Zemax and Code V seat costs and export control restrictions complicate talent development in emerging manufacturing clusters.
- Anti-reflective coating qualification:Magnesium fluoride and nano-layer deposition processes require 18-24 month validation cycles with end-user camera OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Lens Market |
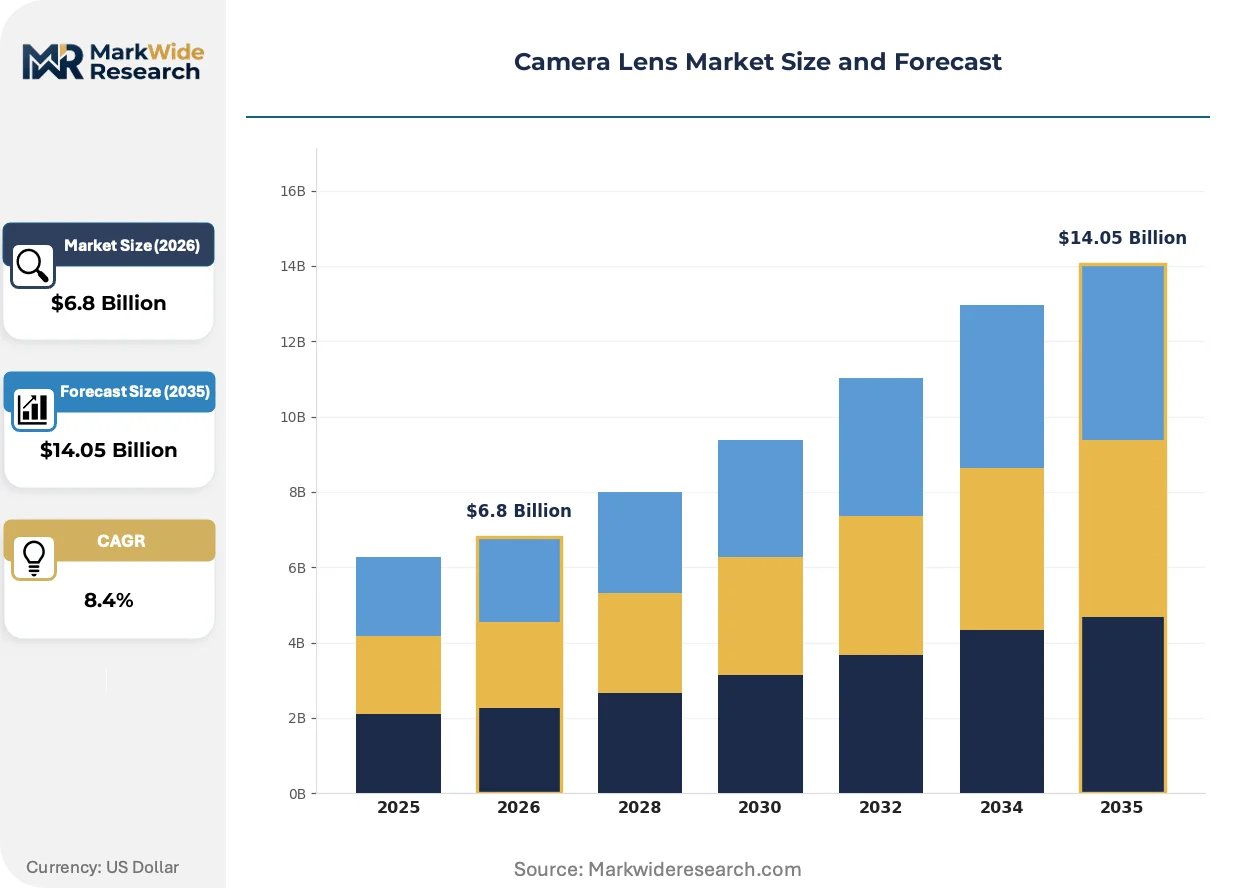
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prime Lens, Zoom Lens, Wide-Angle Lens, Telephoto Lens Application: Photography, Videography, Surveillance, Scientific Research End User: Professional Photographers, Hobbyists, Cinematographers, Researchers Technology: Optical, Digital, Hybrid, Smart |
| Companies Covered | Canon, Edmund Optics, Tamron, Commonlands, Towin, Sigma, Nikon, Lensation, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Lens Market Emerging Trajectories
Three forces are restructuring competitive advantage: lens virtualization through computational pipelines, regulatory tightening on coating chemistries, and procurement fragmentation across rental and direct channels.
Multi-element computational arrays are virtualizing traditional optical paths by replacing mechanical aperture and focus mechanisms with software-defined depth mapping. Professional cinematographers are adopting these hybrid systems for pre-visualization and virtual production stages. This virtualization is compressing the premium attached to mechanical precision in mid-market segments.
REACH substance restrictions are eliminating perfluorooctanoic acid from anti-reflective coating processes across European supply chains. Lens manufacturers are reformulating magnesium fluoride deposition protocols to maintain transmission rates under tightened ECHA thresholds. German and French optical houses face the steepest compliance timelines given their exposure to EU medical and industrial end-use certification.
Equipment procurement is fragmenting between direct purchase, short-term rental, and subscription access models. Independent content creators and regional broadcasters are migrating toward rental-house networks for project-specific glass needs. This channel rotation is most pronounced in North American and Western European markets where production financing favors operating expense treatment over capital deployment.
Camera Lens Market Segmentation
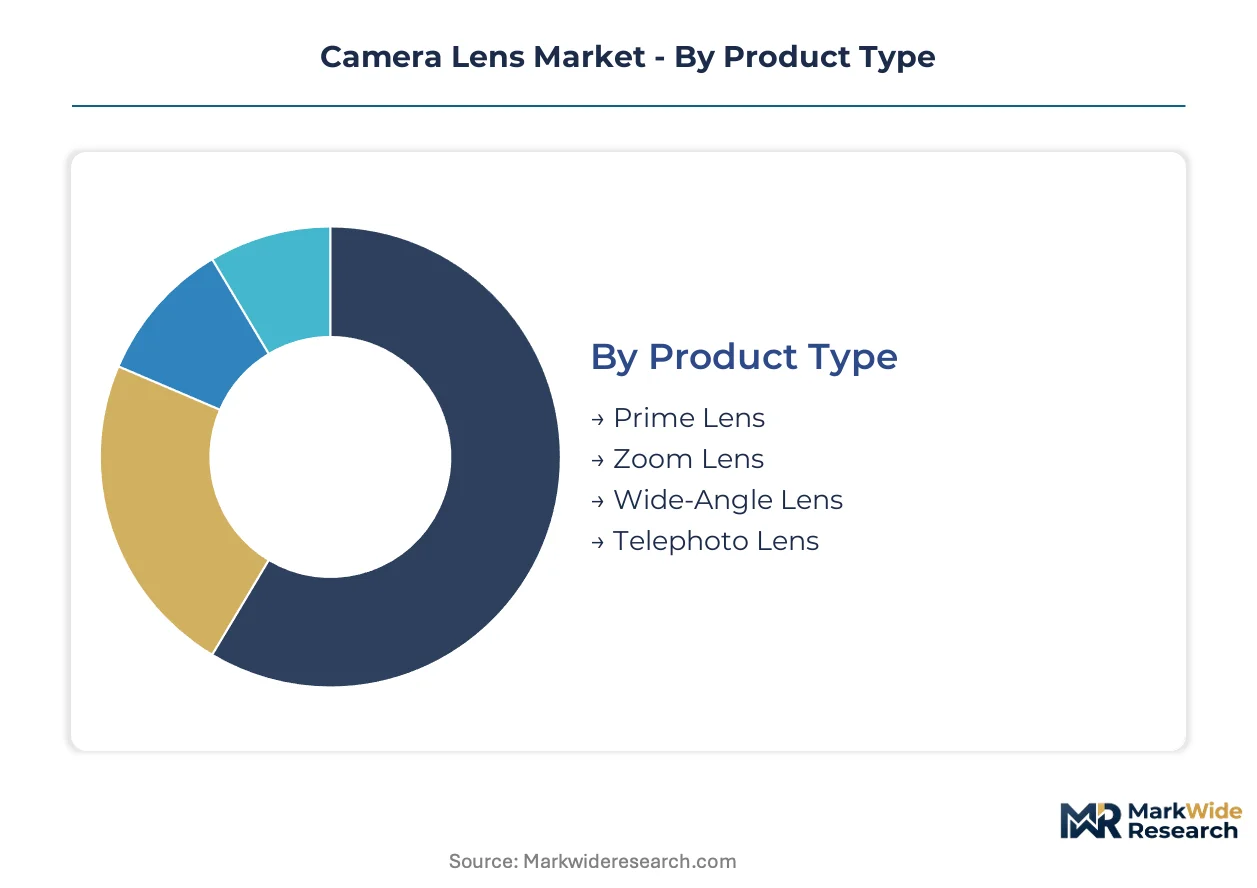
Camera lens segmentation reveals divergent margin structures across optical architectures and user sophistication tiers. Product type and application splits expose where mechanical precision commands premium pricing versus where computational substitutes erode standalone demand.
Product Type:
Mature zoom configurations dominate unit economics while emerging telephoto variants capture surveillance-driven expansion.
- Prime Lens:Fixed focal length assemblies maximize aperture diameter and minimize optical aberrations through simpler element stacks. Professional photographers in Japan and Germany sustain demand for f/1.4 and faster specifications despite higher per-unit cost. METI-certified manufacturers capture margin premiums through JIS-compliant precision grinding.
- Zoom Lens:Variable focal length mechanisms integrate multiple optical groups with complex cam-driven alignment systems. Consumer channels in the United States and Western Europe absorb the highest unit volumes for travel and event photography applications. Canon and Nikon maintain captive assembly lines for standard zoom ranges to defend margin pools.
- Wide-Angle Lens:Short focal length designs below 24mm equivalent address architectural and landscape specialists.
- Telephoto Lens:Long focal length assemblies exceed 85mm equivalent for distance-constrained capture scenarios.
Zoom configurations retain volume leadership; telephoto specifications hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive cinematography from mass-market consumer imaging.
- Photography:Still image capture spans consumer, prosumer, and professional tiers with divergent optical quality thresholds. Hobbyist segments in India and Southeast Asia increasingly satisfy casual needs through smartphone computational pipelines. Standalone lens demand concentrates among enthusiasts seeking shallow depth-of-field control unavailable in mobile form factors.
- Videography:Motion picture capture requires parfocal zoom maintenance and silent autofocus actuation for professional production environments. Cinema-grade glass leasing through Los Angeles and London rental houses expands access for independent filmmakers without capital purchase requirements.
- Surveillance:Continuous monitoring applications demand weather-sealed barrels and motorized remote focus across perimeter installations.
- Scientific Research:Laboratory and field instrumentation requires specialized transmission curves and thermal stability specifications.
Photography applications retain volume leadership; surveillance deployments hold the steepest expansion curve.
End User:
Customer type segmentation maps directly to procurement channel preferences and price elasticity differentials.
- Professional Photographers:Commercial image-makers purchase through authorized dealer networks with warranty and service bundling. Wedding and portrait specialists in France and Italy prioritize prime lens collections for consistent low-light performance. This segment exhibits lowest price sensitivity and highest replacement frequency for wear-damaged equipment.
- Cinematographers:Motion picture professionals access equipment through rental-house subscriptions and production-specific procurement. E-mount and PL-mount ecosystems lock in lens-body compatibility decisions across multi-year project pipelines.
- Hobbyists:Enthusiast consumers balance performance aspirations against budget constraints through third-party autofocus alternatives.
- Researchers:Institutional buyers navigate extended validation cycles and grant-funded procurement timelines.
Hobbyists retain volume leadership; cinematographers hold the steepest expansion curve.
Technology:
Supply concentration in precision glass melting constrains hybrid and smart lens development timelines.
- Optical:Purely mechanical light-bending through ground and polished glass elements remains the reference standard for professional applications. Japanese and German optical houses control high-index flint and crown glass production through specialized continuous-melting furnaces. REACH compliance requirements are forcing coating chemistry reformulations across European supply chains.
- Hybrid:Combined optical-digital systems integrate computational depth mapping with traditional lens architectures. Smartphone manufacturers in China and South Korea drive R&D investment toward software-defined focus and aperture control.
- Digital:Sensor-integrated capture without discrete optical elements addresses ultra-compact device constraints.
- Smart:Network-connected lenses with embedded processing enable automated scene analysis and cloud synchronization.
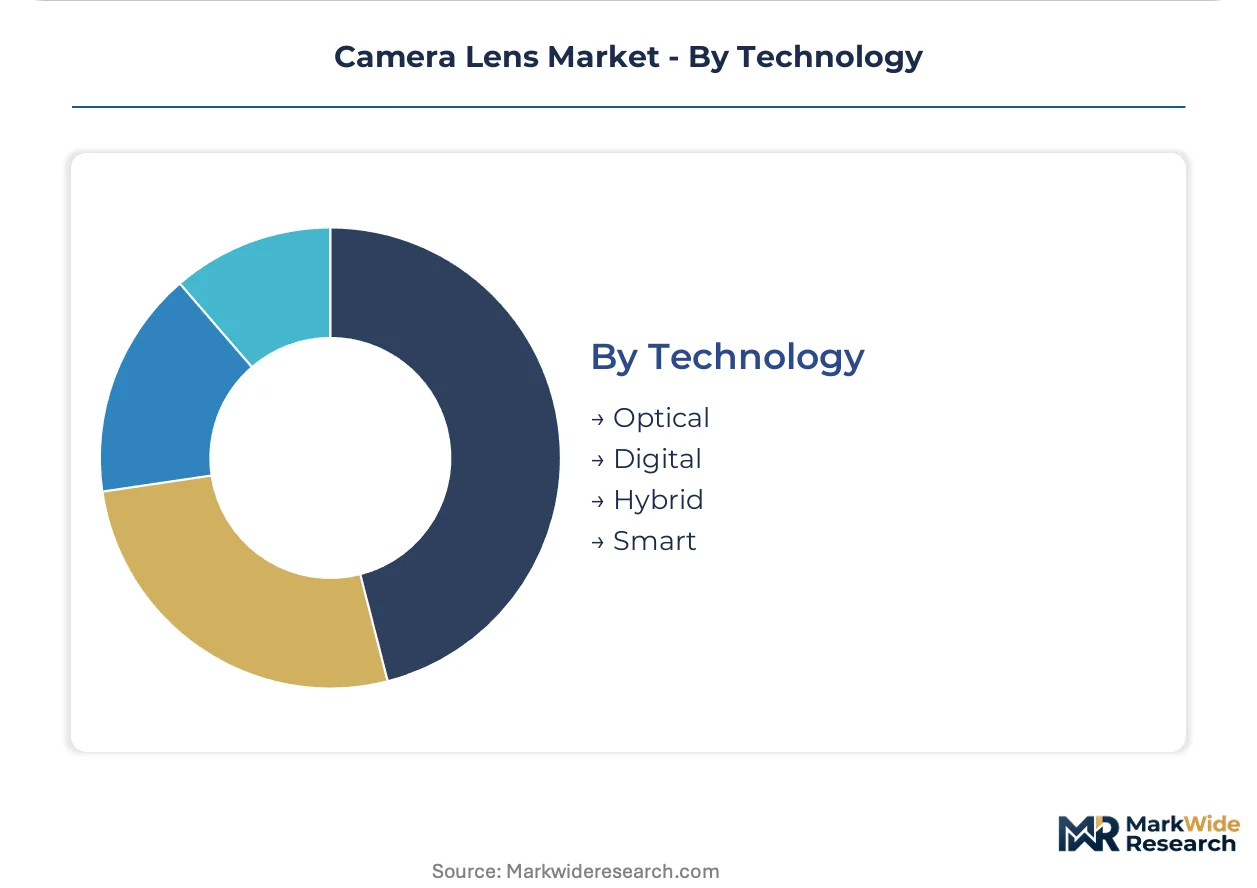
Optical technology retains volume leadership; hybrid systems hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI precision standards and China's surveillance procurement mandates are reshaping regional supply configurations. Lens manufacturers navigate divergent regulatory incentives across major production clusters.
China
Surveillance infrastructure deployment under SAMR-administered GB standards accelerates telephoto lens assembly in Shenzhen and Dongguan industrial corridors. Municipal smart city contracts mandate domestic-certified optics for perimeter monitoring systems. The Yangtze River Delta concentrates precision glass grinding operations serving both security and consumer export markets.
Japan
JIS-certified optical houses in the Kanto region sustain premium pricing through METI-enforced tolerance regimes for professional cinematography and scientific instrumentation. Continuous-melting furnace capacity for high-index flint glass remains concentrated among Nagano and Yamanashi prefecture suppliers. Canon and Sony anchor captive foundry networks across prime and zoom product lines.
Germany
ECHA REACH compliance deadlines are forcing coating chemistry reformulations among Baden-Württemberg optical houses serving medical and industrial end-use certification. Stuttgart and Munich clusters specialize in aspherical grinding for automotive inspection systems. German manufacturers face the steepest transition timelines for eliminating perfluorooctanoic acid from anti-reflective deposition protocols.
United States
Independent filmmaking expansion in Los Angeles and New York Metro drives rental-house network growth for cinema-grade glass access without capital purchase. FAA regulations on commercial drone imaging create specialized telephoto demand for aerial cinematography operators. The Southeast industrial corridor attracts barrel and mount assembly through proximity to camera module distribution channels.
India
PLI scheme incentives for electronics manufacturing are drawing lens mount fabricators to Chennai and Noida production zones. DGFT import tariff structures on finished optics encourage domestic assembly of consumer zoom configurations. Karnataka's imaging technology cluster hosts emerging third-party autofocus specialists targeting hobbyist price points.
Camera Lens Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. The vendor base stratifies between integrated optical houses with captive glass melting capacity and modular assemblers sourcing precision elements from certified tier-two suppliers. Three archetypes dominate: foundry-integrated majors, third-party autofocus specialists, and rental-house network operators. Competitive moves center on backward integration into high-index glass production and exclusive mount ecosystem lock-in through body-lens compatibility protocols.
Among Japanese foundry-integrated majors, Canon and Sony exemplify the captive supply archetype through in-house precision grinding and coating operations. Sigma occupies the third-party autofocus tier that major OEMs leave exposed in consumer and prosumer segments. These three companies anchor divergent competitive vectors—foundry control versus ecosystem openness—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Canon |
| Edmund Optics |
| Tamron |
| Commonlands |
| Towin |
| Sigma |
| Nikon |
| Lensation |
| Sony |
| Others |
Supply Flow & Price Mechanics
Rare earth element concentration in Chinese processing facilities determines both JIS-certified premium spreads and the geographic clustering of optical glass melting capacity. METI tolerance enforcement and REACH coating compliance create tiered supplier eligibility that locks qualified manufacturers into premium pricing while marginalizing uncertified competitors.
Pricing Analysis
Certification level under JIS and REACH frameworks creates the primary spread between qualified optical houses and commodity assemblers. Three-tier pricing structure across premium, standard, and economy levels reflects METI tolerance tiers, after-sales service bundling, and captive foundry control. Cost compression in consumer zoom configurations is intensifying because smartphone computational pipelines satisfy casual imaging demand without standalone lens purchases. Hobbyist segments exhibit highest price sensitivity; cinematographers accessing rental-house networks show lowest elasticity due to project-based procurement.
Supply Chain Analysis
Extended payment terms from Japanese optical houses to certified tier-two suppliers stabilize cash flow across precision grinding operations. High-index flint and crown glass production draws from continuous-melting furnace capacity concentrated in Japan and Germany, with lanthanum and tantalum sourcing anchored in Chinese processing facilities. Single-source vulnerability around specialized furnace operators exposes manufacturers to input volatility. Distribution runs through authorized dealer networks for professional tiers and rental-house subscriptions for cinematography access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational optics from smartphone manufacturers threatens standalone consumer lens demand, forcing incumbents to defend professional-grade margin pools through certification-locked precision manufacturing.
For Market Incumbents: Entrench JIS-certified precision grinding capacity in Nagano and Yamanashi prefectures to maintain premium pricing power against commodity assemblers. Deepen backward integration into high-index glass melting to reduce dependency on the three specialized furnace operators controlling critical input supply. For New Entrants and Emerging Players: Pursue third-party autofocus niches that Canon and Nikon leave exposed in prosumer zoom segments, particularly in India's PLI-subsidized Chennai and Noida corridors. White-space concentrates in rental-house network partnerships for independent filmmaking access without capital purchase requirements. For Investors and Strategic Acquirers: The market sits at a substitution-defense phase that favors foundry-integrated majors with captive coating and grinding operations over modular assemblers. Long-term viability hinges on exclusive mount ecosystem control through body-lens compatibility protocols. Watch for inflection in smartphone computational depth-mapping performance as threat acceleration signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Index Glass Melting | Canon and Sony reduce furnace dependency through captive Nagano foundry capacity. |
| JIS Certification Investment | METI-enforced tolerance tiers lock premium pricing for qualified optical houses. |
| Rental-House Network Partnership | Sigma expands cinematography access through Los Angeles and London subscription channels. |
| REACH-Compliant Coating Line Conversion | German optical houses eliminate perfluorooctanoic acid to maintain EU medical certification. |
| Hybrid Optical-Digital R&D Partnership | Samsung and Apple computational pipelines pull investment toward software-defined focus systems. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed optical equipment manufacturers, JIS certification registries, and ECHA substance restriction updates. Optical design engineers, procurement leads at camera OEMs, rental-house operations managers, and precision grinding facility supervisors provided structured input. Bottom-up assembly cost modeling triangulates against top-down market sizing from trade flow analysis.
Forecast inputs include product type segmentation across prime, zoom, and telephoto architectures; application splits between photography, videography, and surveillance; and technology tiers separating optical, hybrid, and digital systems. CAGRs derive from regression analysis against smartphone imaging performance curves and municipal security procurement trajectories. Surveillance infrastructure mandates under SAMR-administered GB standards and PLI scheme electronics incentives anchor regional growth assumptions.
Sensitivities concentrate around rare earth export licensing friction, REACH coating chemistry transition timelines, and smartphone computational depth-mapping advancement. Forecasts reflect documented assumptions on substitution elasticities and certification tier pricing power. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global 3D Camera Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Thermal Imaging Systems Market
Imaging
Pocket Video Camera Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Europe CT Market
Imaging
Printed Image Sensors Market
Imaging
Frame Grabber Market
Imaging
High Dynamic Range Market
Imaging
Raman-Imaging System Market
Imaging
Widefield Imaging Systems Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Global Trail Camera Market
Imaging
X Ray Tubes Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Plenoptic Camera Market