
 Asia Pacific Fiber Optics Market | 2026-2036
Asia Pacific Fiber Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fiber Optics Market Insights
Single-mode fiber specifications is unwinding legacy multimode dominance across Asia Pacific backbone networks. Corning Incorporated leverages its proprietary low-loss waveguide designs to anchor premium supply contracts with Chinese state-owned carriers. Sumitomo Electric Industries, Ltd. sustains leadership in submarine cable systems through integrated marine installation capabilities.
Fiber optics comprises silica-based waveguides with core diameters of 8-10 micrometers for single-mode and 50-62.5 micrometers for multimode variants, manufactured via modified chemical vapor deposition to transmit data via total internal reflection at terabit-per-second capacities. Cables dominates product-type revenue as subsea and terrestrial trunk lines absorb bulk volume, while connectors captures margin concentration through precision ferrule assemblies for data center interconnects. Telecommunications end-use leads absolute spend, though data centers represents the fastest structural expansion as hyperscalers expand cloud regions across Singapore, Sydney, and Tokyo.
China's MIIT enforces GB standards for optical fiber mechanical reliability, while India's TRAI mandates domestic sourcing preference under BharatNet Phase III procurement rules. Japan's METI coordinates national R&D consortia for next-generation hollow-core fiber through its SIP program. Stakeholders must track divergence between China's GB certification requirements and India's BIS fiber specifications as fragmentation in test protocols complicates pan-Asian product platform strategies.
Market Dynamics
Single-mode fiber specifications are displacing legacy multimode infrastructure across Asia Pacific backbone networks, while China's MIIT broadband targets and India's TRAI BharatNet procurement rules simultaneously reshape carrier procurement patterns and vendor qualification requirements.
Growth Catalysts
- 5G network densification:China's MIIT mandates gigabit city coverage by 2025, forcing fiber-to-the-antenna deployments across 300-plus metropolitan clusters. Carrier procurement volumes concentrate in the Yangtze River Delta manufacturing corridor.
- TRAI BharatNet Phase III:India's domestic sourcing preference rules redirect fiber optic cable procurement toward indigenous manufacturers, creating captive demand for rural broadband infrastructure spanning 600,000 villages.
- Submarine cable expansion:Trans-Pacific and intra-ASEAN cable systems absorb high-count fiber bundles for data center interconnects, with Singapore and Sydney emerging as hyperscaler landing hubs.
Market Restraints
- Purified silica supply concentration:High-purity silicon tetrachloride feedstock production clusters in China's Jiangsu and Shandong provinces, exposing cable manufacturers to regional supply disruptions and input cost volatility.
- GB-BIS certification divergence:China's GB standards for optical fiber mechanical reliability differ materially from India's BIS fiber specifications, forcing vendors to maintain dual testing protocols and inventory SKUs.
- Copper cable residual infrastructure:Legacy last-mile copper networks in Southeast Asian secondary cities delay fiber substitution timelines where capital constraints limit trenching and pole-access investments.
Strategic Opportunities
- Philippines archipelago connectivity:The country's 7,600-island geography creates structural demand for submarine fiber links and aerial cable systems where terrestrial deployment remains economically prohibitive.
- Hollow-core fiber R&D:Japan's METI SIP program coordinates national consortia for next-generation waveguide architectures promising lower latency for financial trading and high-frequency data transmission.
- Direct-to-hyperscaler contracting:Cloud infrastructure providers in Singapore and Tokyo are bypassing traditional carrier intermediaries for dark fiber procurement, compressing channel margins and accelerating deployment cycles.
Industry Challenges
- Precision splicing technician scarcity:Fusion splicing for single-mode fiber requires sub-micron alignment accuracy, and certified technician pools lag deployment timelines across India's BharatNet implementation zones.
- Marine installation coordination complexity: Submarine cable projects require simultaneous permitting from coastal regulatory bodies, fisheries authorities, and naval zones across multiple ASEAN jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fiber Optics Market |
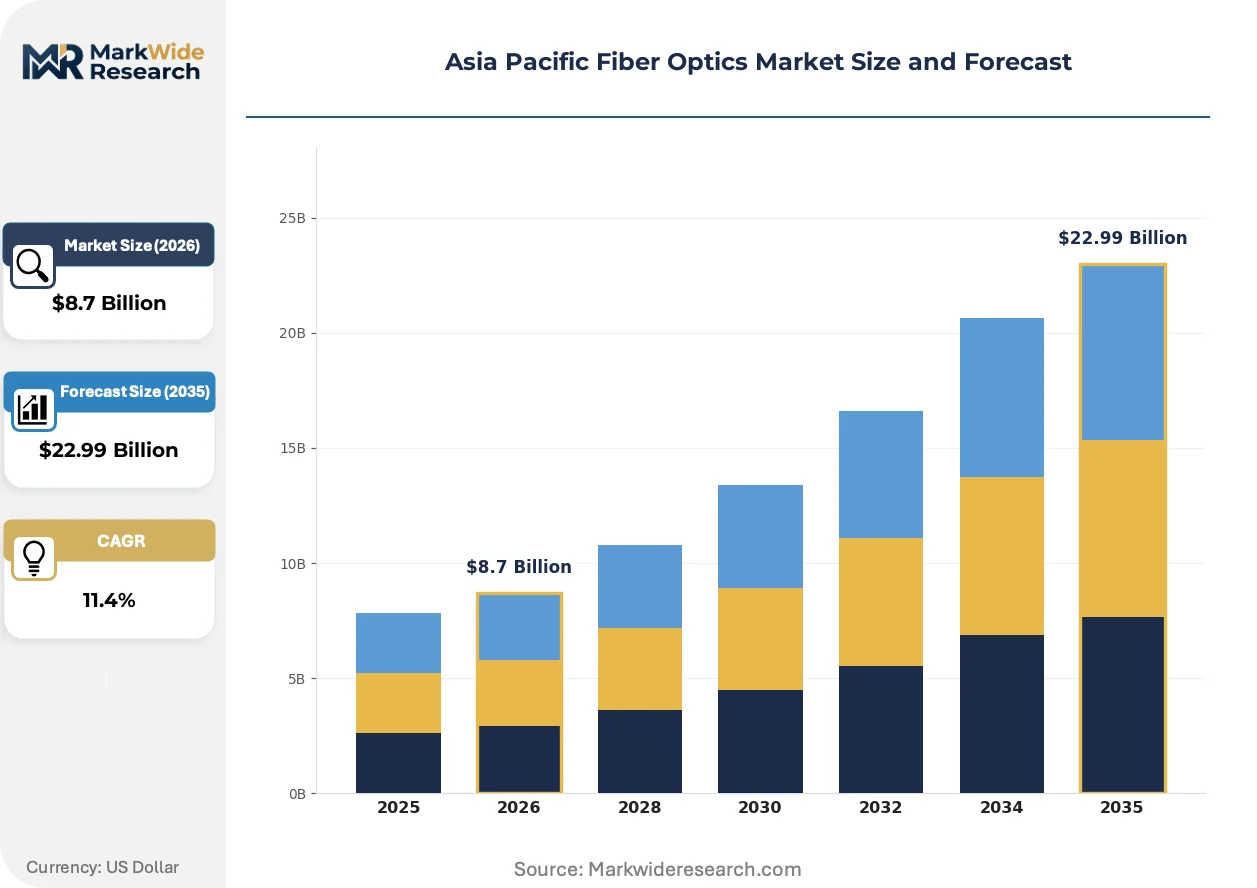
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Connectors, Splices, Splitters Installation Type: Indoor, Outdoor, Aerial, Underground End User: Telecommunications, Data Centers, Government, Enterprises Application: Telecom, Industrial Automation, Networking, Medical |
| Companies Covered | Corning Incorporated, Prysmian Group, Sumitomo Electric Industries, Ltd., Yangtze Optical Fibre and Cable (YOFC), Fujikura Ltd., Hengtong Group Co., Ltd., Furukawa Electric Co., Ltd., Sterlite Technologies Ltd., LS Cable & System Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fiber Optics Market Trends and Innovations
Photonic integration and hollow-core architectures are compressing latency benchmarks while regulatory mandates in China and India force simultaneous compliance with divergent national certification regimes.
Silicon photonics is miniaturizing optical transceiver form factors by embedding lasers, modulators, and detectors onto single silicon substrates. Hyperscalers in Singapore and Tokyo are adopting 800G coherent pluggable modules at compressed refresh cycles. This convergence is miniaturizing data center interconnect hardware while forcing traditional discrete component suppliers toward foundry partnerships or exit.
China's MIIT enforces revised GB standards for optical fiber mechanical reliability and environmental stress testing, extending qualification timelines for imported cable products. Domestic manufacturers gain preferential access to state-owned carrier tenders under the framework. Foreign vendors are responding by establishing localized preform drawing and cable sheathing facilities within Jiangsu and Zhejiang free trade zones.
Consolidated procurement by hyperscale cloud operators is disintermediating traditional telecom equipment distributors across the Asia Pacific region. Direct contracting for dark fiber and wavelength services now dominates transactions above 100 Gbps capacity thresholds. This concentration is most visible in Singapore's data center corridor, where Microsoft, Amazon, and Google collectively account for dominant fiber demand.
Asia Pacific Fiber Optics Market Segmentation
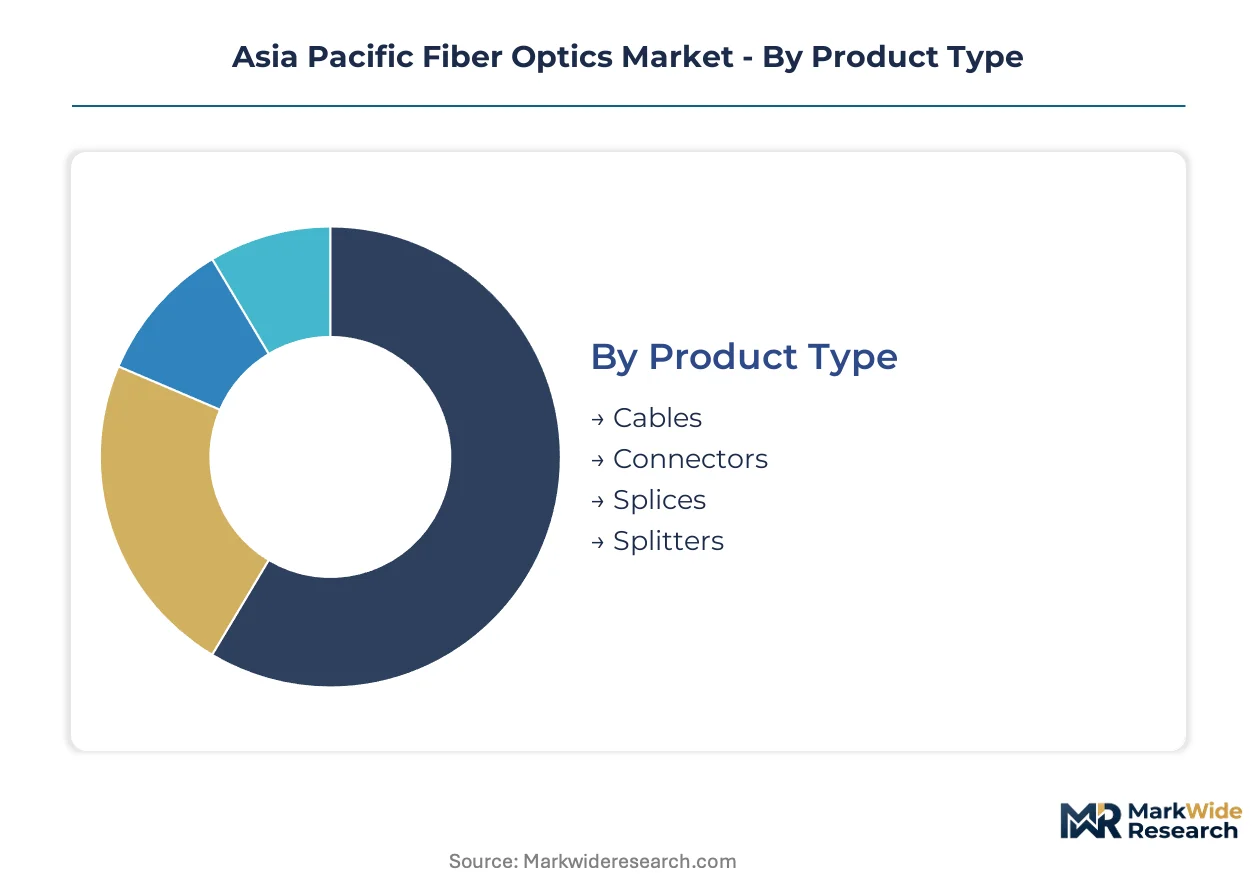
Segmentation in the Asia Pacific fiber optics market reveals how procurement priorities diverge between state-backed broadband programs and hyperscaler-driven data center buildouts. Understanding these fault lines exposes where substitution threats from wireless and satellite technologies concentrate.
Product Type:
Substitution pressure from wireless backhaul and low-earth orbit satellite constellations weighs most heavily on cable segments serving rural trunk lines, while precision interconnect components face minimal displacement risk in data center environments.
- Cables:Silica-based waveguide bundles with polyethylene or steel-armored sheathing deliver terabit-per-second capacity across terrestrial and submarine spans. China's Yangtze River Delta manufacturing corridor absorbs bulk procurement volumes from MIIT-mandated gigabit city programs.
- Connectors:Ceramic ferrule assemblies with sub-micron alignment tolerances enable rapid data center interconnect deployment. Singapore and Tokyo hyperscalers drive specification tightening toward 800G pluggable form factors.
- Splices:Fusion-spliced fiber joints restore continuity across cable breaks and branching points.
- Splitters:Planar lightwave circuit devices divide optical signals for passive optical network distribution.
Cables retains volume leadership; Connectors holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates premium submarine and underground deployments from budget-constrained aerial alternatives across Southeast Asian secondary markets.
- Outdoor:Armored cable designs withstand moisture, UV exposure, and rodent damage across uncontrolled environments. India's BharatNet Phase III rural buildout concentrates procurement in pole-mounted and trench-buried configurations spanning 600,000 villages.
- Underground:Direct-buried and conduit-drawn installations protect fiber from weather and physical interference in dense urban corridors. China's MIIT gigabit city mandates accelerate metro duct infrastructure investment.
- Indoor:Riser-rated and plenum-certified cables serve building distribution and data center structured cabling.
- Aerial:Self-supporting and lashed fiber deployments leverage existing utility pole infrastructure where trenching costs prove prohibitive.
Outdoor dominates absolute deployment scale; Underground climbs fastest as urban densification accelerates.
End User:
Application maturity varies sharply between established telecommunications infrastructure and emerging enterprise private network demand.
- Telecommunications:State-owned and private carriers deploy fiber for core backbone, metro aggregation, and last-mile access networks. TRAI's domestic sourcing preference rules under BharatNet Phase III redirect procurement toward indigenous cable manufacturers.
- Data Centers:Hyperscale cloud operators and colocation providers consume high-fiber-count cables and precision connectors for intra-facility and inter-campus interconnects. Singapore's data center corridor sees direct contracting for dark fiber bypassing traditional carrier channels.
- Government:National broadband initiatives and defense communications networks drive sovereign infrastructure investment.
- Enterprises:Private fiber networks for manufacturing campuses and financial trading floors generate specialized low-latency requirements.
Telecommunications commands installed base dominance; Data Centers gains share most rapidly.
Application:
Customer type concentration splits between volume-driven telecom infrastructure and margin-rich industrial automation deployments.
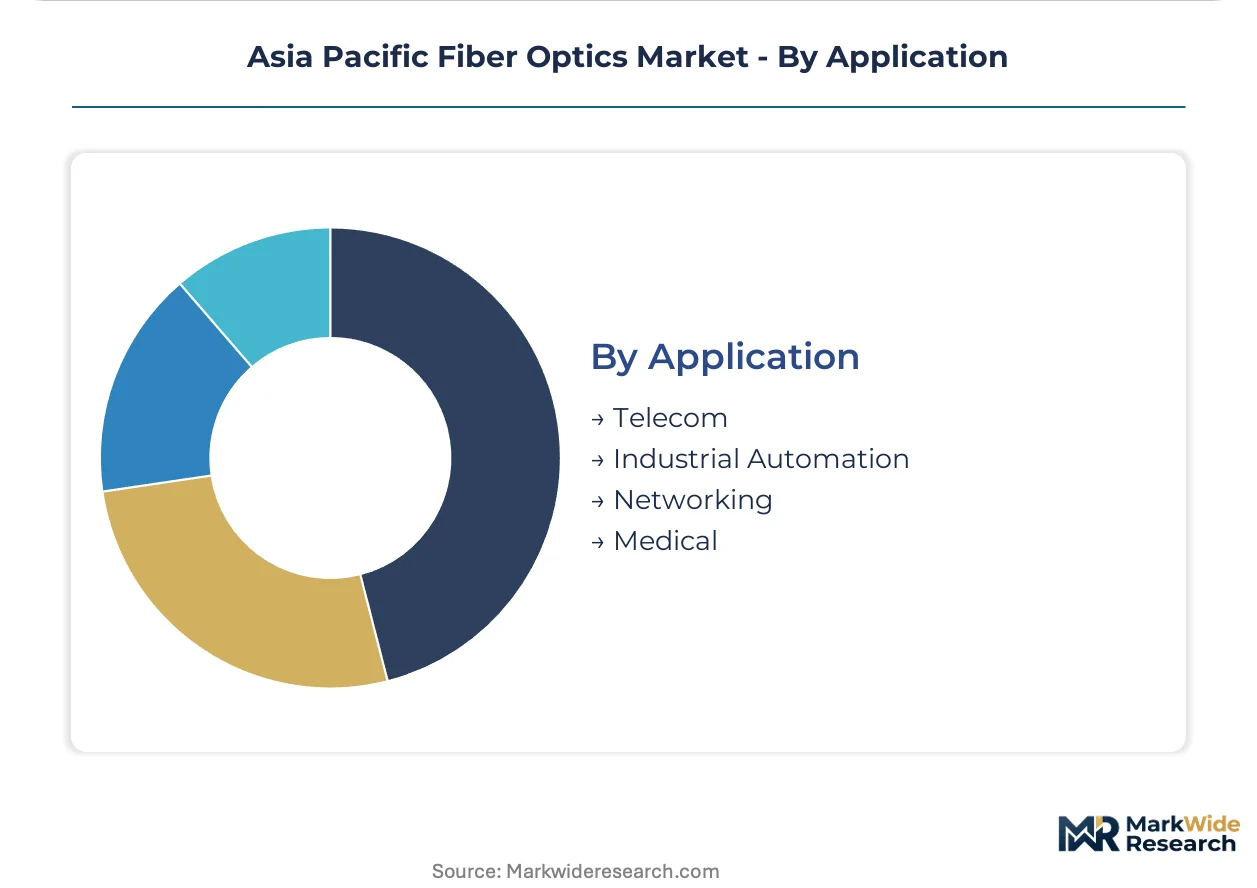
- Telecom:Voice, video, and data transmission across fixed and mobile network infrastructure. 5G fiber-to-the-antenna densification across China, India, and Southeast Asia propels single-mode fiber specification upgrades.
- Networking:Enterprise LAN, WAN, and data center switching infrastructure. Japan's METI SIP program coordinates hollow-core fiber R&D for next-generation low-latency switching applications.
- Industrial Automation:Factory-floor fiber networks resist electromagnetic interference in heavy manufacturing environments.
- Medical:Fiber-optic illumination and imaging systems for surgical and diagnostic equipment.
Telecom anchors revenue scale; Networking expands most quickly as cloud architecture proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fiber optic cable exports flow predominantly to Southeast Asian telecom operators and Indian infrastructure contractors under MIIT-coordinated production quotas. Japan and South Korea supply precision components and submarine cable systems across the Pacific corridor.
China
MIIT gigabit city mandates drive fiber-to-the-antenna deployments across 300-plus metropolitan clusters. GB standards enforcement for optical fiber mechanical reliability extends qualification timelines for imported products. The Yangtze River Delta manufacturing corridor concentrates preform drawing and cable sheathing capacity where state-owned carriers anchor procurement volumes.
India
TRAI's BharatNet Phase III targets 600,000 villages with rural broadband infrastructure. Domestic sourcing preference rules redirect cable procurement toward indigenous manufacturers under CEA coordination. Deployment concentrates in Maharashtra and Gujarat where certified technician pools lag installation timelines.
Japan
METI's SIP program coordinates national R&D consortia for hollow-core fiber architectures targeting low-latency financial trading applications. JIS standards govern precision connector specifications for data center interconnects. The Kanto region around Tokyo anchors hyperscaler landing hubs for trans-Pacific cable systems.
South Korea
MFDS-aligned quality protocols support submarine cable component exports to ASEAN markets. The Busan-Ulsan coastal zone houses marine installation capabilities for intra-Asia fiber links. Domestic 5G densification sustains demand for high-count fiber bundles in the Seoul Capital Area.
Singapore
Direct hyperscaler contracting for dark fiber bypasses traditional carrier channels as Microsoft, Amazon, and Google anchor regional cloud infrastructure. The data center corridor demands 800G pluggable form factors with compressed refresh cycles. Marine cable landing stations position the city-state as a trans-Pacific bandwidth exchange.
Asia Pacific Fiber Optics Market Competitive Landscape
Listed leaders compete with private specialists across state procurement access and technology licensing dimensions. The vendor base stratifies into three tiers: integrated preform-to-cable manufacturers, marine installation specialists, and precision component suppliers. Archetypes include state-backed champions with captive domestic demand, submarine system integrators with marine assets, and hyperscale-focused interconnect vendors. Competitive moves concentrate on capacity expansion in Jiangsu free trade zones and strategic partnerships for silicon photonics foundry access.
Among Japan-based integrated manufacturers, Sumitomo Electric Industries, Ltd. and Fujikura Ltd. occupy positions within the submarine cable specialist archetype, while Corning Incorporated represents the premium-tier waveguide design segment. These three exemplify divergent strategic postures: marine installation capabilities versus proprietary low-loss designs versus ceramic ferrule precision manufacturing.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Sumitomo Electric Industries, Ltd. |
| Yangtze Optical Fibre and Cable (YOFC) |
| Fujikura Ltd. |
| Hengtong Group Co., Ltd. |
| Furukawa Electric Co., Ltd. |
| Sterlite Technologies Ltd. |
| LS Cable & System Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day preform inventory cycles at Yangtze River Delta cable plants concentrate pricing leverage among Chinese state-owned carriers, compressing margin buffers for foreign vendors facing GB certification delays. This inventory-to-pricing dynamic tightens procurement terms for imported silica feedstock while amplifying cost advantages for domestic manufacturers operating under MIIT-coordinated production quotas.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across submarine cable and data center interconnect procurement. Price differentiation separates GB-certified mechanical reliability tiers from BIS-compliant alternatives, with volume scale and certification level as primary drivers. Cost compression in standard-grade terrestrial cables intensifies as China's Yangtze River Delta capacity expansion floods regional spot markets. Hyperscale cloud operators exhibit lowest price sensitivity due to latency-critical specifications, while Southeast Asian municipal carriers face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit routes for silicon tetrachloride feedstock expose cable manufacturers to maritime logistics chokepoints and customs clearance variability. Geographic supply concentration centers on China's Jiangsu and Shandong provinces for purified silica preforms, Japan for precision ferrule ceramics, and South Korea for submarine cable armoring compounds. Raw material dependencies draw from high-purity silicon tetrachloride, germanium-doped core glass, and marine-grade polyethylene sheathing. Single-source vulnerability in Jiangsu-based preform drawing creates systemic concentration risk. Distribution runs through state-owned carrier tender platforms in China and direct hyperscaler contracting channels in Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
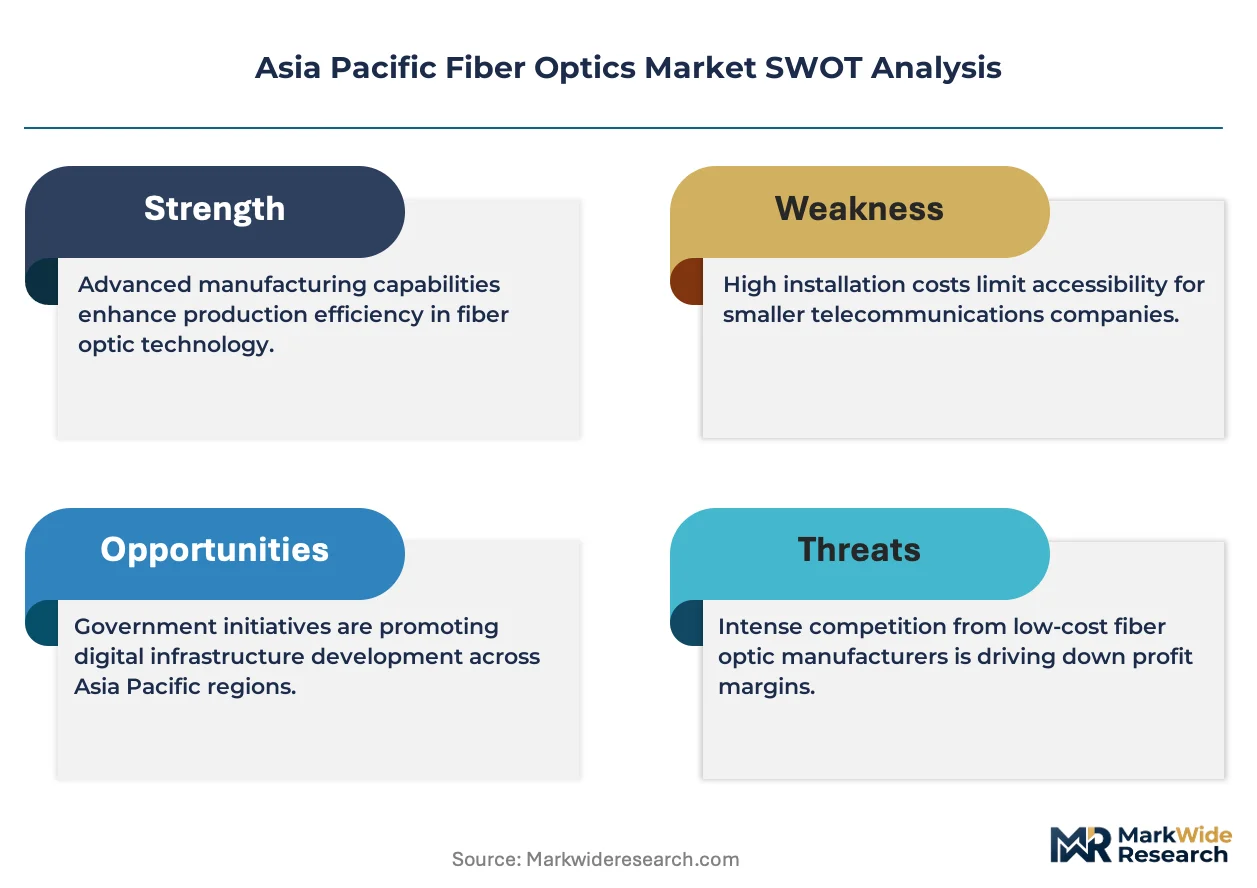
Buyer power is concentrating through hyperscaler direct procurement consolidation, fragmenting traditional carrier-intermediary channels across the Asia Pacific region.
For Market Incumbents: Compound defensive positioning through backward integration into Jiangsu free trade zone preform drawing facilities and accelerated GB certification investment. Threat from hollow-core fiber substitution under Japan's METI SIP program demands R&D allocation toward low-latency waveguide architectures. Vertical integration into marine installation assets protects submarine cable margins. For New Entrants and Emerging Players: Lead with precision connector specialization targeting Singapore data center corridor 800G pluggable refresh cycles. The Philippines archipelago submarine connectivity gap offers most penetrable geography given terrain-prohibitive terrestrial alternatives. Go-to-market angle should emphasize rapid-deployment aerial cable systems for island-hopping topologies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive fiber optic divisions lacking scale for hyperscaler qualification. Long-term viability favors specialists with marine installation capabilities or silicon photonics foundry partnerships. Signal to watch is TRAI BharatNet Phase III domestic sourcing enforcement intensity as inflection indicator for indigenous manufacturer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Drawing | Jiangsu free trade zone localization neutralizes GB certification timeline disadvantages for foreign cable vendors. |
| Silicon Photonics Foundry Partnership | Access to 800G coherent pluggable module capacity secures hyperscaler interconnect share in Singapore corridor. |
| Marine Installation Capability Acquisition | Integrated submarine cable system offerings capture trans-Pacific and intra-ASEAN project margins. |
| Dual GB-BIS Certification Investment | Pan-Asian product platform qualification opens simultaneous access to China's MIIT tenders and India's BharatNet procurement. |
| Hollow-Core Fiber R&D Consortium Participation | Japan METI SIP program alignment positions for next-generation low-latency financial trading applications. |
Research Methodology
Desk research of customs trade databases, carrier procurement disclosure filings, and national broadband program documentation preceded structured interviews with submarine cable system engineers, state-owned carrier procurement directors, data center interconnect specialists, and optical component manufacturing executives. Primary fieldwork across China's Yangtze River Delta, Singapore's data center corridor, and India's Maharashtra-Gujarat deployment zones combined with secondary validation from MIIT production quota announcements and TRAI BharatNet progress reports. Bottom-up volume modeling triangulated against top-down infrastructure investment forecasts.
Variance decomposition across product type, installation configuration, end-user category, and national regulatory cluster shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include cable versus connector versus splice product tiers, outdoor versus underground versus aerial installation methods, telecommunications versus data center versus government end-use splits, and country-specific certification regime clusters. CAGRs derived from infrastructure deployment timelines, hyperscaler capex disclosure patterns, and national broadband program milestone tracking. Forecast inputs incorporated 5G fiber-to-the-antenna densification curves and submarine cable landing station commissioning schedules.
Forecasts assume regulatory continuity in China's MIIT gigabit city mandates and India's TRAI domestic sourcing preference rules; material policy shifts would require re-modeling procurement volume trajectories. Practitioners should keep alternative scenarios live as hollow-core fiber commercialization timelines and ASEAN submarine cable permitting reform evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Smart Vision Systems Market
Optics
Single-Mode Optical Fiber Market
Optics
Optical Receivers Market
Optics
Interchangeable Lens Market
Optics
Global Nanophotonics Market
Optics
Collimating Lens Market
Optics
Excimer Laser Market
Optics
Fiber Optic Receiver Market
Optics
Tunable Laser Market
Optics
Fiber Optic Amplifier Market
Optics
Optical Measuring Systems Market
Optics
Germanium Lens Market
Optics
Global Fiber Optic Components Market
Optics
Optical Gratings Market
Optics
Optical Fiber Raw Material Market
Optics
Digital Holographic Microscopy Market