
 Global Fiber Optic Components Market | 2026-2036
Global Fiber Optic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Optic Components Market Intelligence
The European Union's Restriction of Hazardous Substances (RoHS) directive is shifting material specifications for fiber optic components, mandating the removal of lead and other hazardous materials from solders and coatings. Lumentum Holdings Inc. leverages its expertise in photonic integrated circuits to meet these stringent environmental standards. Broadcom Inc. competes on the basis of its highly integrated transceiver portfolio for data center applications. Sumitomo Electric Industries sustains its market position through extensive R&D in new fiber and component materials.
Fiber optic components are devices that manipulate light signals within an optical fiber network, including generation, transmission, amplification, and reception. These components, such as transceivers operating at specific wavelengths like 1310nm or 1550nm, are essential for converting electrical signals to optical signals and back. Optical transceivers represent the largest segment by component type, driven by constant upgrade cycles in telecommunications and data center infrastructure. Within applications, demand from military communications for secure, high-bandwidth connections is a high-margin niche.
Product compliance is governed by multiple bodies, including the US Federal Communications Commission (FCC) for telecommunications equipment, the EU's CE marking for safety, and China's MIIT for network access. These regulations directly influence component design, testing protocols, and market entry requirements for manufacturers. Navigating the evolving standards for co-packaged optics and next-generation passive optical networks will be critical for component suppliers to maintain a competitive edge.
Market Dynamics
The primary force shaping the market is the exponential growth in data traffic. This pressure from cloud services, 5G deployments, and AI workloads necessitates continuous innovation in component density, speed, and power efficiency to prevent network bottlenecks.
Growth Catalysts
- 5G Network Expansion:Extensive government-backed 5G rollouts, particularly in China and South Korea, require a massive volume of optical transceivers and passive components for fronthaul and backhaul infrastructure.
- Data Center Interconnects:The proliferation of hyperscale data centers drives demand for high-speed, high-density components like 400G and 800G transceivers to link servers, switches, and entire facilities.
- DWDM Technology:Continued deployment of Dense Wavelength Division Multiplexing systems allows network operators to increase fiber capacity without laying new cables, fueling upgrades of transponders, amplifiers, and multiplexers.
Market Restraints
- High Capital Intensity:The fabrication of advanced photonic components requires substantial and continuous investment in specialized cleanroom facilities and semiconductor manufacturing equipment, creating high barriers to entry.
- Material Supply Concentration:Key raw materials, such as high-purity germanium and indium phosphide substrates, are sourced from a limited number of geographic regions, posing supply chain risks.
- Signal Integrity Challenges:At data rates approaching and exceeding 1.6T, managing signal degradation and dispersion within components becomes a fundamental physical limitation requiring complex compensation techniques.
Strategic Opportunities
- Co-Packaged Optics:The integration of optical I/O directly onto processor and switch packages presents a significant opportunity to reduce power consumption and improve bandwidth density in next-generation data centers.
- Quantum Communications:The development of quantum networks for secure communication creates a new, high-value market for specialized components like single-photon detectors and quantum-state manipulators.
- Emerging Market Infrastructure:Digitalization initiatives and greenfield network builds in regions like Southeast Asia, Latin America, and Africa offer long-term growth potential for component suppliers.
Industry Challenges
- Complex Standardization:Achieving industry consensus for next-generation standards, such as those for pluggable coherent optics or passive optical networks, is a slow process that can delay mass-market adoption.
- Photonic Engineering Talent:A persistent shortage of engineers with expertise in photonic design, integration, and testing constrains the research and development capacity of many component manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Optic Components Market |
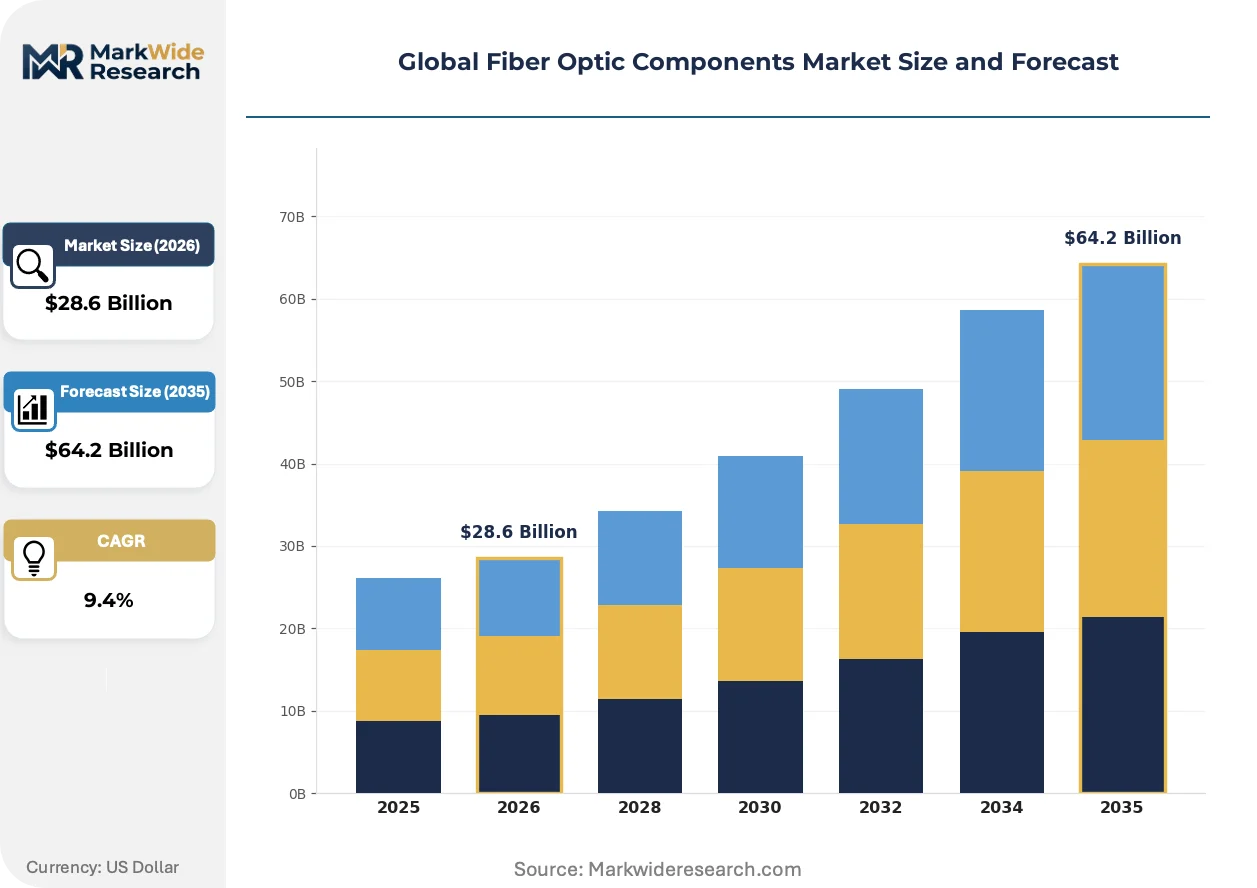
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Optical Transceivers, Optical Connectors, Optical Amplifiers, Optical Switches, Multiplexers, Attenuators Technology: DWDM, CWDM, GPON, EPON, Active Optical Cable, Passive Optical Network Application: Telecommunications, Data Centers, Military Communications, Broadcasting Networks, Sensor Networks, Education Networks End User: Internet Service Providers, Cloud Service Providers, Defense Sector, Broadcast Companies, Research Institutions, Education Providers |
| Companies Covered | Coherent Corporation, Lumentum Holdings Inc., Broadcom Inc., Sumitomo Electric Industries, Accelink Technologies, Amphenol Corporation, Furukawa Electric, Fujitsu Optical Components, EMCORE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Optic Components Market Strategic Shifts & Innovations
Miniaturization and environmental compliance are the twin forces driving product evolution. Component manufacturers face simultaneous pressure to increase data density and reduce power consumption while also redesigning products to meet stringent material regulations like the EU's RoHS directive.
Photonic Integrated Circuits (PICs) consolidate multiple optical functions like laser generation and modulation onto a single semiconductor chip. Network equipment manufacturers and data center operators are adopting PICs to manage rising data volumes. This technology is modularizing the design of optical transceivers, enabling faster development cycles and more compact, power-efficient systems.
The European Union's Restriction of Hazardous Substances (RoHS) directive mandates the removal of lead, mercury, and other materials from electronic products. This regulation directly impacts component design, forcing suppliers to invest in alternative, compliant materials for solders and coatings. The transceiver segment, with its complex material composition, is most affected and must undergo costly requalification processes.
A clear shift in purchasing behavior favors integrated optical subsystems over discrete components. This pattern disrupts the traditional channel for individual lasers and modulators, benefiting vendors who can deliver pre-validated, higher-level assemblies. The trend is most visible in North American hyperscale data centers, where simplifying the supply chain is a primary procurement goal.
Global Fiber Optic Components Market Segmentation
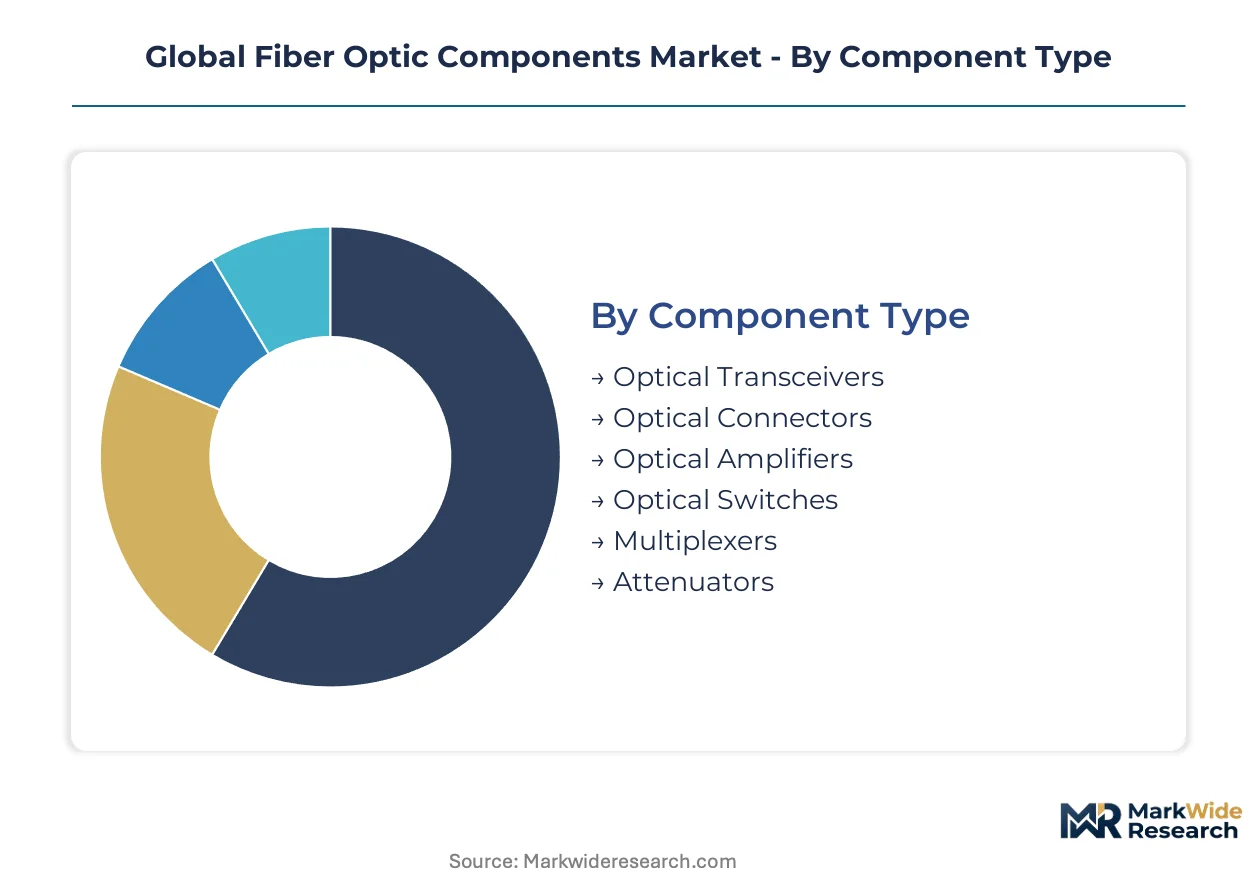
The Global Fiber Optic Components Market segmentation provides a granular view of product types, technologies, and applications driving industry expansion. These distinct segments reveal where innovation concentrates and how end-user demands shape manufacturing priorities.
Component Type:
This component type segmentation highlights varying integration levels, from standalone passive elements to complex active modules embedding multiple functions.
- Optical Transceivers:These devices convert electrical to optical signals and back, operating at specific wavelengths for data transmission. Hyperscale data centers and telecommunications networks drive demand, necessitating higher data rate upgrades.
- Optical Amplifiers:Components like Erbium-Doped Fiber Amplifiers (EDFAs) boost optical signal strength without electrical conversion, extending transmission distances. DWDM systems deploy amplifiers to maintain signal integrity.
- Optical Connectors:Mechanical devices join optical fibers, enabling temporary or permanent connections in network configurations.
- Optical Switches:Switches direct optical signals from one fiber to another without electrical conversion, improving network flexibility.
- Multiplexers:Multiplexers combine multiple optical signals onto a single fiber, maximizing bandwidth utilization in DWDM systems.
- Attenuators:Attenuators intentionally reduce optical signal power to prevent receiver saturation, ensuring optimal performance.
Volume placements concentrate in Optical Connectors; the faster expansion belongs to Optical Transceivers.
Technology:
The technology segmentation reveals diverse methods to transmit and manage optical signals, each optimized for specific network architectures and performance.
- DWDM:Dense Wavelength Division Multiplexing increases fiber capacity by transmitting multiple data streams using different laser wavelengths. Telecommunications operators deploy DWDM for long-haul and metro networks.
- Passive Optical Network:PON technologies utilize unpowered optical splitters, enabling a single optical fiber to serve multiple endpoints and reducing infrastructure costs. These networks are critical for fiber-to-the-home (FTTH).
- GPON:Gigabit Passive Optical Network represents a widely adopted PON standard, offering high bandwidth for residential and business fiber connections.
- EPON:Ethernet Passive Optical Network is another PON standard, often favored in Asian markets for compatibility with existing Ethernet infrastructure.
- Active Optical Cable:AOCs integrate transceivers and fiber optic cables into a single assembly, simplifying high-speed data links within data centers.
- CWDM:Coarse Wavelength Division Multiplexing uses fewer wavelengths with wider spacing than DWDM, making it a cost-effective solution for shorter distances.
Expansion across DWDM and Passive Optical Network
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen, China, leads global fiber optic component manufacturing and deployment, driven by its robust electronics ecosystem. This city's extensive infrastructure supports massive 5G network expansion across the nation. Government initiatives, particularly through the MIIT, drive significant investment in digital infrastructure projects here, fueling demand for advanced components.
China
Extensive 5G network rollouts and government-led digital infrastructure projects drive significant demand for optical transceivers and passive components. The MIIT's strategic plans for digital transformation accelerate this market expansion. Major manufacturing hubs like Shenzhen and Wuhan concentrate component production and innovation.
United States
Hyperscale data centers and cloud service provider networks represent primary demand drivers for high-speed fiber optic components. The US Federal Communications Commission (FCC) regulates telecommunications equipment, influencing component design and testing protocols. Silicon Valley and other tech clusters foster continuous innovation in photonic integrated circuits.
Germany
Industrial automation, advanced manufacturing, and research in quantum communications create specific demand for high-performance optical components. The EU's CE marking and RoHS directive mandate stringent environmental and safety compliance. Munich's technology cluster and research institutions actively develop next-generation fiber optic solutions.
Japan
Advanced telecommunications infrastructure upgrades and extensive R&D in new fiber materials sustain demand for sophisticated components. Japan's METI initiatives promote innovation in optical technologies and digital transformation. Tokyo and Osaka serve as major hubs for telecommunications network deployment and component integration.
India
Digitalization initiatives, fiber-to-the-home (FTTH) deployments, and emerging 5G networks are accelerating component consumption. The government's PLI scheme encourages local manufacturing of telecom equipment, including fiber optic components. Bengaluru's IT and electronics hub attracts investment in optical communication technologies.
Global Fiber Optic Components Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and integration levels. The market exhibits a tiered structure, with a few large integrated providers alongside numerous specialized component manufacturers. Key strategic archetypes include vertically integrated solution providers and niche innovators focusing on specific component types. Portfolio diversification and strategic partnerships are dominant competitive moves among market participants.
On the premium-tier vector, Lumentum Holdings Inc. exemplifies advanced photonic integration, leveraging its expertise in photonic integrated circuits. Broadcom Inc. occupies a position among providers of highly integrated transceiver portfolios for data center applications. Sumitomo Electric Industries anchors the segment focused on extensive research and development in new fiber and component materials.
| Leading Market Players |
|---|
| Coherent Corporation |
| Lumentum Holdings Inc. |
| Broadcom Inc. |
| Sumitomo Electric Industries |
| Accelink Technologies |
| Amphenol Corporation |
| Furukawa Electric |
| Fujitsu Optical Components |
| EMCORE Corporation |
| Others |
Cost & Logistics Intelligence
Photonic engineering talent concentration in specific regions like Silicon Valley and Shenzhen creates labor-cost differentials, influencing pricing-tier spreads across the fiber optic components market.
Pricing Analysis
Throughput optimization anchors value-based pricing for high-speed optical transceivers, reflecting their direct impact on network performance. Price differentiation stems from performance tiers and customization levels, particularly for co-packaged optics designed for specific data center architectures. Pricing softness runs through commodity connectors due to high-volume manufacturing and intense competition. Hyperscale data centers exhibit high price sensitivity for standard components, while military communications prioritize security and reliability over cost.
Supply Chain Analysis
Single-source vulnerability sits with specific geographic regions for high-purity germanium and indium phosphide substrates, critical raw materials for advanced photonic components. Manufacturing concentration largely centers in China, with Japan contributing specialized fiber materials and the United States leading advanced R&D. Material supply concentration presents a structural risk to the global supply chain. Distribution runs primarily through direct sales to large telecommunications operators and hyperscale data centers, complemented by specialized distributors for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber optic components market enters a technology-transition phase, with co-packaged optics gradually displacing traditional pluggable transceivers in next-generation data centers.
For Market Incumbents: To counter the rapid technological shifts towards co-packaged optics, incumbents must deepen their R&D investments in photonic integrated circuits. Strategic partnerships with semiconductor foundries can ensure access to advanced manufacturing capabilities. Diversifying the raw material supply base reduces dependency on single geographic regions. Maintaining strong compliance with regulations like the EU's RoHS directive is also crucial.
For New Entrants and Emerging Players: Specialized system integrators offer new entrants a direct pathway into emerging market infrastructure projects and niche applications like quantum communications. Focus on high-margin, customized solutions for secure military communications or specialized industrial automation can provide market entry. Leveraging regional government incentives, such as India's PLI scheme for local manufacturing, also creates a competitive advantage.
For Investors and Strategic Acquirers: Re-rating potential sits with agile, specialized component manufacturers given the accelerating demand for secure, high-bandwidth connections and next-generation network architectures. Long-term viability hinges on companies demonstrating clear roadmaps for co-packaged optics and quantum communications. The commercialization of silicon photonics platforms for broader applications serves as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen R&D in Photonic Integrated Circuits | This initiative drives miniaturization and power efficiency, essential for next-generation data center interconnects and network architectures. |
| Expand Manufacturing in Emerging Markets | This move capitalizes on digitalization initiatives and 5G network rollouts in regions like Southeast Asia and Latin America. |
| Invest in Advanced Material Compliance | This ensures adherence to stringent environmental regulations like the EU's RoHS directive, maintaining market access. |
| Form Strategic Partnerships for 800G/1.6T Transceivers | This accelerates the development and adoption of ultra-high-speed components, critical for hyperscale data center upgrades. |
| Target Niche Quantum Communication Applications | This secures early market share in a high-value, emerging segment requiring specialized single-photon detectors. |
Research Approach
Multi-period observation of component adoption rates, technology roadmaps, and regulatory compliance benchmarks anchored the trend analysis, supplemented by interviews. Primary research involved discussions with CTOs at hyperscale data centers, network architects at telecommunications operators, R&D directors at component manufacturers, and procurement managers. Secondary validation drew from FCC filings, MIIT reports, EU RoHS compliance documents, and industry association publications, ensuring bottom-up and top-down triangulation.
Segment-weighting across component types, technologies, and applications structured the quantitative model, projecting market evolution across the analysis window. The analytical framework incorporated historical data extrapolation and future demand projections to derive compound annual growth rates. Key industry-specific forecast inputs included global data traffic growth forecasts and regional 5G deployment schedules, informing market size and expansion estimates.
Caveats apply where unforeseen regulatory changes or material supply disruptions could materially shift the outlook for fiber optic components. Forecasts reflect documented assumptions regarding technological advancements and infrastructure investment patterns. Deviation in 5G rollout speeds or data center expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Beam Expanders Market
Optics
Anomaloscope Market
Optics
Smartphone Camera Lenses Market
Optics
Single-Mode Optical Fiber Market
Optics
Fiber Optic Amplifier Market
Optics
Laser Transmitter Market
Optics
Glass Scintillator Market
Optics
Fiber Optic Connectivity Market
Optics
Global High Purity Quartz Glass Market
Optics
Digital Holographic Microscopy Market
Optics
Fiber-Optic Filters Market
Optics
Middle East and Africa Tunable Laser Market
Optics
AR and VR Lens Market
Optics
Optical Imaging Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Optical Fiber Market