
 Optical Receivers Market | 2026-2036
Optical Receivers Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Receivers Market Intelligence
Modular packaging of optical front ends alongside DSP subsystems is recalibrating how telecom OEMs evaluate supplier proposals. Broadcom Inc. leverages captive CMOS design capabilities to bundle silicon photonics with custom signal processing. Coherent Corp. anchors its competitive position through vertical integration from III-V wafer fabrication to module assembly. Sumitomo Electric Industries Ltd. differentiates via precision coupling expertise in high-speed receivers for coherent transmission.
An optical receiver converts modulated light into electrical signals through photodetection and transimpedance amplification, typically operating at wavelengths of 1310 nm or 1550 nm with bandwidths exceeding 50 GHz in leading-edge designs. Silicon photonics receivers now dominate volume production for data center interconnects due to CMOS-compatible foundry economics, while InP technology sustains premium positioning in long-haul coherent applications where avalanche photodiode sensitivity proves indispensable. Metro networks represent the fastest-expanding application segment as edge computing deployments compress latency requirements across regional fiber rings.
FCC broadband infrastructure mandates in the United States, EU Green Deal energy-efficiency benchmarks under the CSRD framework, and China's GB standards for optical communications equipment collectively tighten efficiency and interoperability requirements. These regulations force module vendors to pre-certify receivers across multiple jurisdictional regimes before commercial release. Stakeholders must monitor divergence between U.S. export controls on advanced photonics and China's import substitution directives to anticipate supply chain reconfiguration.
Market Dynamics
Silicon photonics integration is compressing component counts and foundry economics, forcing legacy discrete architectures into retreat across data center interconnect and coherent transmission applications simultaneously.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in the United States and China are standardizing on pluggable coherent optics, pulling demand for 400G and 800G silicon photonics receivers.
- EU Green Deal energy-efficiency mandates:CSRD disclosure requirements and F-Gas Regulation phase-downs are accelerating replacement of power-hungry legacy transceivers with integrated photonic subsystems.
- 5G backhaul fiberization:China's MIIT infrastructure directives and state-led semiconductor localization programs are channeling procurement toward domestic III-V and silicon photonics suppliers for metro and access networks.
Market Restraints
- InP substrate supply concentration:Indium phosphide wafer production clusters in Japan and select European suppliers, exposing coherent receiver manufacturers to input cost volatility and allocation risk.
- US export control friction:Commerce Department restrictions on advanced photonics manufacturing equipment are complicating technology transfer for China-bound foundry expansions and joint development programs.
- Silicon photonics wavelength limitations:CMOS-compatible platforms struggle to integrate high-sensitivity avalanche photodiodes for ultra-long-haul submarine links, preserving InP dominance in premium segments.
Strategic Opportunities
- Edge computing metro rings:Latency-sensitive AI inference deployments across Germany, France, and the United Kingdom are creating incremental demand for coherent pluggables in regional aggregation nodes.
- Co-packaged optics convergence:Integration of silicon photonics with switch ASICs through advanced packaging is opening architecture redesign cycles at hyperscale network equipment buyers.
- India's PLI scheme for telecom:Production-linked incentives for optical component manufacturing are attracting module assembly investments to serve domestic 5G and future BharatNet fiber expansion.
Industry Challenges
- Packaging engineering talent scarcity:Precision optical coupling and thermal management expertise for high-speed receivers concentrates among experienced specialists in Japan and select European research institutes.
- Multi-jurisdictional pre-certification timelines:FCC Part 15, EU CE marking, and China GB standard compliance must complete sequentially before commercial release, extending product development cycles.
- Legacy SONET/SDH integration complexity:Incumbent telecom operators in North America and Europe require backward-compatible receiver interfaces, constraining silicon photonics design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Receivers Market |
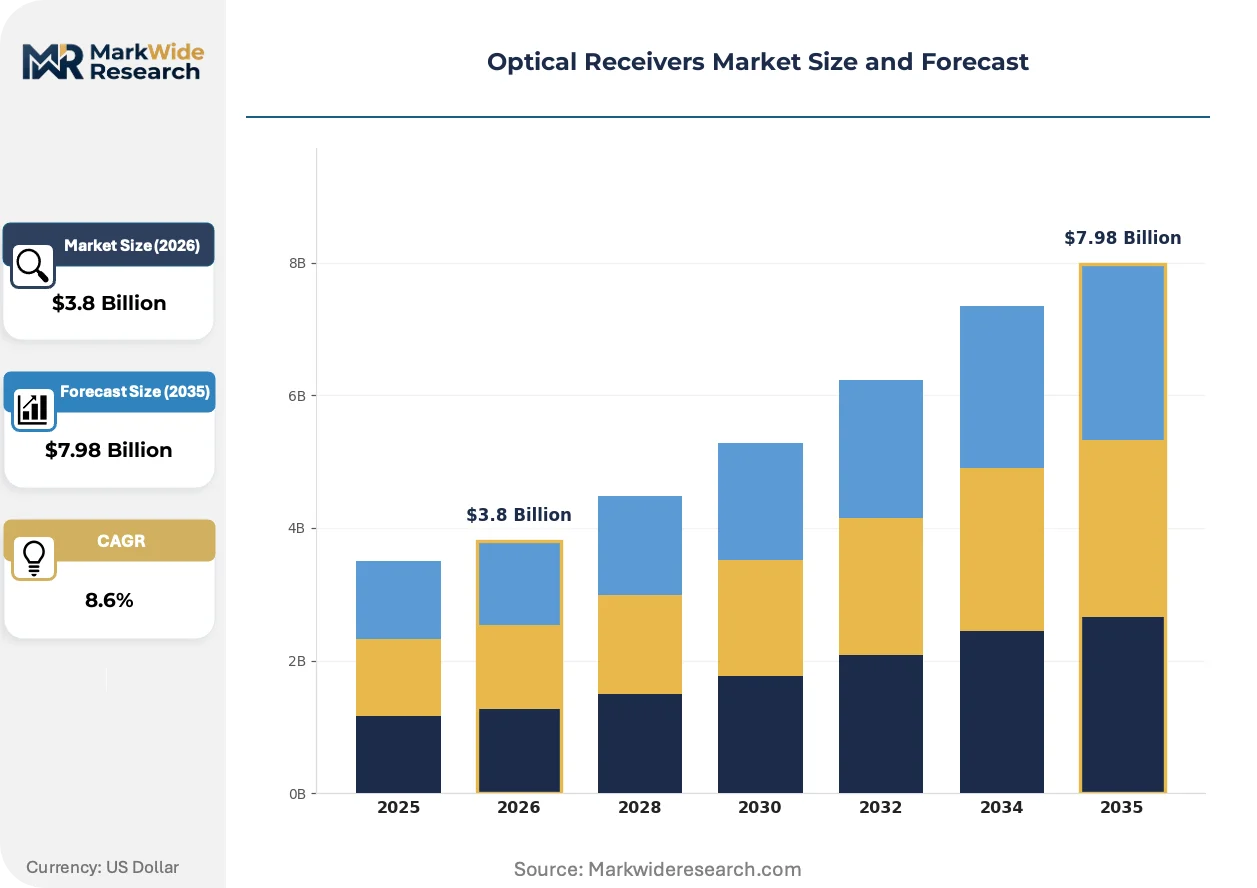
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Receivers, Integrated Receivers, Optical Front End, High-Speed Receivers End User: Telecommunication, Data Centers, Broadcasting, Military Technology: Silicon Photonics, InP Technology, GaAs Technology, APD Technology Application: Long Haul Transmission, Short Haul Communication, Metro Networks, Space Communication |
| Companies Covered | Coherent Corp., Broadcom Inc., Lumentum Operations LLC, Sumitomo Electric Industries Ltd., Finisar Corporation, NeoPhotonics Corporation, Source Photonics, Fujitsu Optical Components Limited, Accelink Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Receivers Market Strategic Shifts & Innovations
Receiver architecture is converging around co-designed photonic and electronic subsystems, collapsing traditional boundaries between component suppliers and module integrators.
Silicon photonics with monolithically integrated germanium photodetectors performs photodetection and initial signal conditioning on a single CMOS die. Hyperscale cloud operators in the United States and China are adopting these platforms for intra-data center links at 400G and above. This integration is overtaking discrete InP-based receiver assemblies in volume applications, compressing supplier margins on standalone photodiodes and transimpedance amplifiers.
The EU CSRD framework and F-Gas Regulation are mandating granular energy consumption disclosure and refrigerant phase-down across network infrastructure. Equipment vendors must now document receiver power efficiency across operational temperature ranges. Data center operators in Germany, France, and the Netherlands are prioritizing silicon photonics modules with published carbon footprint data to satisfy procurement scorecards.
Hyperscale buyers are consolidating supplier relationships around vertically integrated module vendors capable of co-designing DSP and optical front-end subsystems. Traditional component distributors are losing share to direct foundry partnerships and captive supply arrangements. This consolidation is most visible in China, where state-directed procurement favors domestic suppliers with in-house silicon photonics and packaging capabilities.
Optical Receivers Market Segmentation
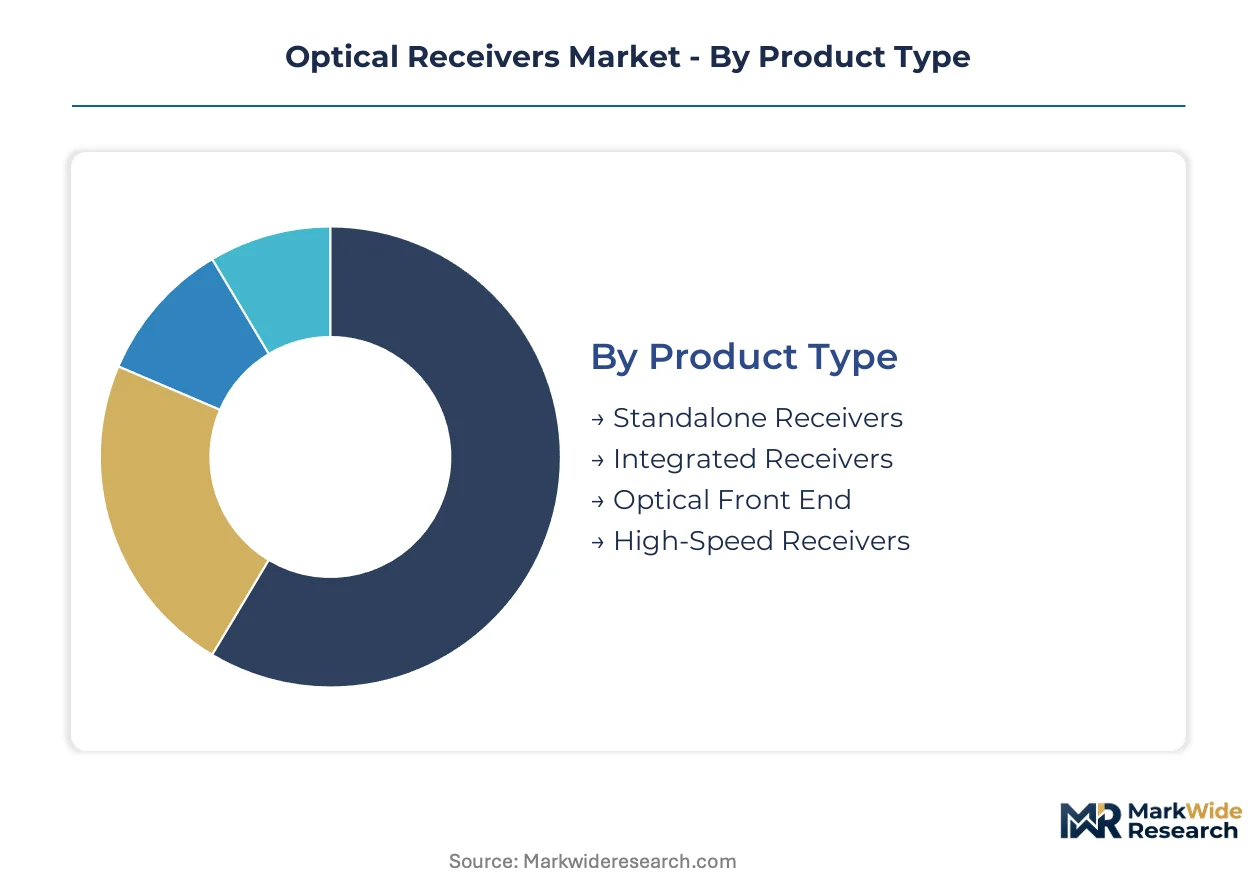
Technology migration cycles and packaging evolution create distinct upgrade pathways across receiver architectures. Procurement patterns diverge sharply between hyperscale cloud operators replacing transceivers every 18-24 months and telecom incumbents maintaining decade-long infrastructure depreciation schedules.
Product Type:
Replacement cadence varies dramatically by integration level, with modular designs enabling field upgrades while monolithic platforms force full subsystem swaps.
- Integrated Receivers:Silicon photonics-based subsystems combining photodetection, amplification, and signal conditioning on single CMOS dies. Hyperscale data centers in the United States and China are standardizing these for 400G/800G pluggable optics to minimize power and footprint. Co-packaged optics roadmaps favor this architecture for switch-ASIC convergence.
- Standalone Receivers:Discrete photodiode and transimpedance amplifier assemblies allowing mixed-technology procurement. Legacy telecom operators in Europe retain these for backward-compatible sparing pools and multi-vendor interoperability requirements. Procurement is concentrating among tier-1 equipment vendors with captive optical component divisions.
- Optical Front End:Receiver subassemblies without DSP integration, enabling OEM customization of signal processing chains. Demand clusters in defense and specialized industrial applications requiring non-standard modulation formats.
- High-Speed Receivers:Bandwidth-optimized designs exceeding 50 GHz for coherent transmission. Metro network buildouts in Germany and France are pulling these for 400ZR pluggable deployments.
Integrated Receivers sits at the top of the volume ranking, with High-Speed Receivers climbing the fastest.
End User:
Customer procurement sophistication spans from commodity spot-buying to multi-year co-development partnerships, with margin structures tracking accordingly.
- Data Centers:Hyperscale operators with direct foundry relationships and published carbon footprint procurement scorecards. Cloud infrastructure expansion in Northern Virginia, Frankfurt, and Singapore is channeling volume toward silicon photonics platforms with energy efficiency certifications.
- Telecommunication:Incumbent carriers with legacy SONET/SDH integration requirements and extended qualification timelines. 5G backhaul fiberization in China under MIIT directives is accelerating InP and silicon photonics procurement for metro aggregation.
- Military:Programs requiring radiation-hardened and temperature-extreme specifications with multi-year development cycles.
- Broadcasting:Video transport infrastructure with synchronous timing requirements and specialized latency constraints.
Data Centers command the highest shipment volumes, with Telecommunication expanding most quickly on 5G infrastructure commitments.
Technology:
Foundry economics and performance tradeoffs segment suppliers into CMOS-compatible volume production versus compound semiconductor premium positioning.
- Silicon Photonics:Germanium photodetector integration on 300mm CMOS wafers enabling foundry-scale economics. Data center interconnect applications in the United States and China have adopted this as default for 400G and above. EU CSRD disclosure requirements favor its superior power efficiency documentation.
- InP Technology:Indium phosphide substrates supporting avalanche photodiode sensitivity for ultra-long-haul coherent links. Submarine cable systems and premium metro deployments retain this despite higher substrate costs and supply concentration in Japanese wafer suppliers.
- GaAs Technology:Gallium arsenide platforms for specific wavelength and speed combinations outside silicon photonics sweet spots.
- APD Technology:Avalanche photodiode architectures implemented across multiple material systems for sensitivity-critical applications.
Silicon Photonics dominates absolute shipment volumes, with InP Technology gaining share fastest in coherent transmission upgrades.
Application:
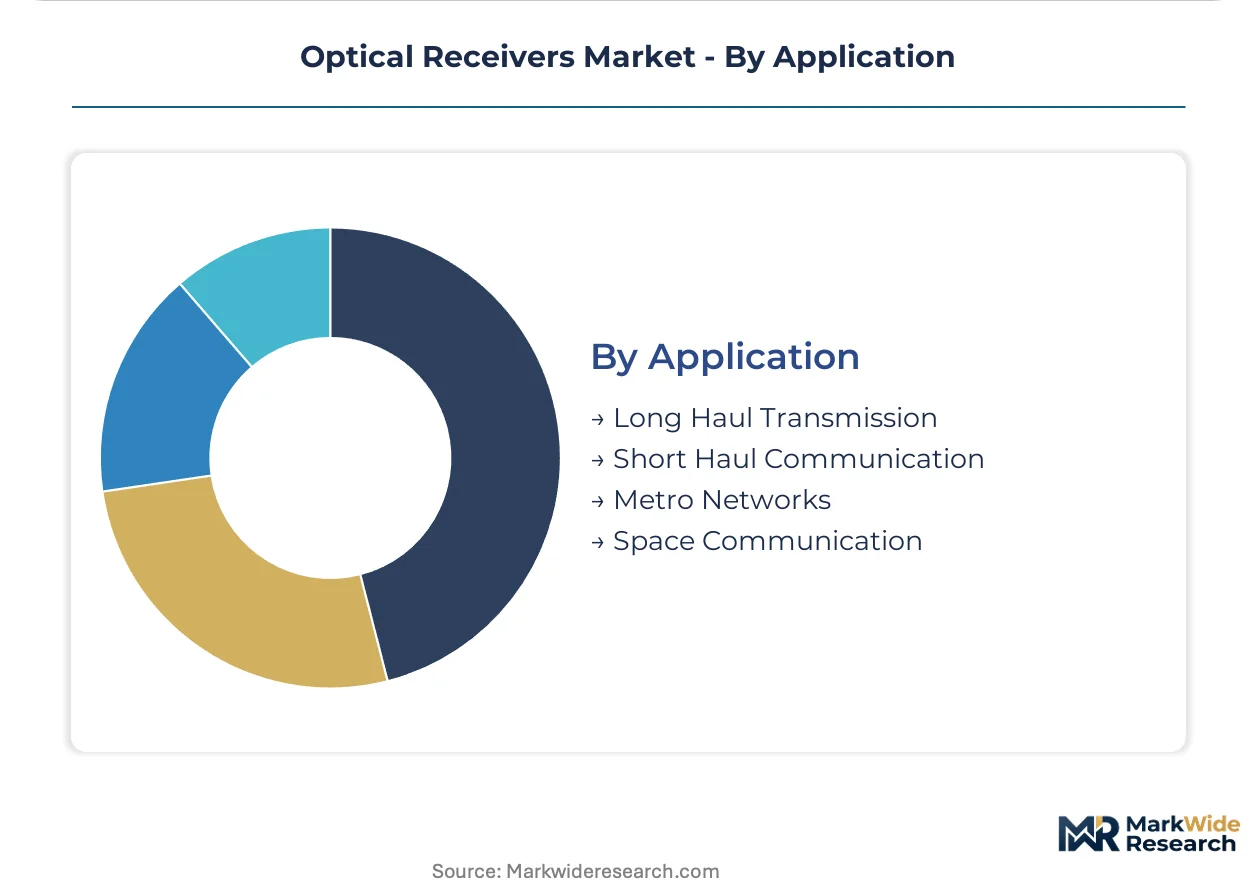
Distance-based performance requirements create tiered procurement specifications with diverging sensitivity, power, and form factor priorities.
- Metro Networks:Regional fiber rings connecting edge data centers and 5G aggregation points with 80-120km reach requirements. Latency-sensitive AI inference deployments across the United Kingdom, Germany, and France are accelerating 400ZR pluggable adoption. Edge computing compression of latency budgets favors coherent receiver integration.
- Long Haul Transmission:Submarine and terrestrial ultra-long-haul links demanding premium sensitivity and forward error correction performance. Trans-Pacific cable systems and continental backbones retain InP-based coherent receivers with DSP co-design.
- Short Haul Communication:Data center internal links and campus interconnects with relaxed sensitivity requirements.
- Space Communication:Satellite and deep-space applications requiring radiation tolerance and extreme temperature operation.
Metro Networks leads volume deployment, with Long Haul Transmission showing the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The optical receivers industry traces its commercial origins to Bell Labs innovations in photodetection during the 1970s, with subsequent scaling concentrated in Japanese precision manufacturing and American semiconductor foundries before silicon photonics integration shifted volume production toward CMOS-compatible ecosystems.
United States
Hyperscale data center operators in Northern Virginia and the Pacific Northwest are standardizing on 400G and 800G pluggable coherent optics. FCC Part 15 certification requirements and Commerce Department export controls on advanced photonics equipment shape vendor qualification timelines. San Jose and Austin host concentrated design activity for silicon photonics-DSP co-integration.
China
MIIT infrastructure directives are accelerating 5G backhaul fiberization across provincial metro networks. State-led semiconductor localization programs channel procurement toward domestic III-V and silicon photonics suppliers. The Yangtze River Delta and Pearl River Delta clusters host captive module assembly serving state-directed procurement.
Germany
Latency-sensitive AI inference deployments across Frankfurt and Munich metro rings are pulling demand for 400ZR coherent pluggables. EU CSRD disclosure requirements and F-Gas Regulation phase-downs mandate granular energy efficiency documentation. Berlin hosts regulatory compliance engineering for multi-jurisdictional pre-certification.
Japan
Indium phosphide wafer fabrication concentrates among established suppliers serving submarine cable and premium coherent applications. METI industrial policy supports precision packaging engineering for high-speed receivers. Tokyo and Osaka metropolitan areas retain specialized coupling expertise for avalanche photodiode integration.
India
Production-linked incentive schemes for telecom component manufacturing are attracting module assembly investments. TRAI spectrum allocation frameworks and BharatNet fiber expansion targets create procurement pull for optical front-end subsystems. Bengaluru and Hyderabad emerging as design centers for indigenous receiver development.
Optical Receivers Market Key Industry Players
Premium-margin players sit above commodity-margin players across integration depth and foundry access, with silicon photonics specialists commanding valuation multiples above discrete component assemblers. The vendor base stratifies into three tiers: vertically integrated module houses with captive CMOS design, compound semiconductor foundries with precision packaging capabilities, and fabless subsystem specialists. Consolidation pressure intensifies through strategic partnerships between DSP vendors and optical front-end suppliers, alongside capacity expansion in 300mm silicon photonics foundries.
Within the vertically integrated tier, Coherent Corp. and Broadcom Inc. occupy positions defined by upstream control over wafer fabrication and signal processing co-design. Sumitomo Electric Industries Ltd. exemplifies the precision-coupling specialist archetype, anchoring competitive positioning through packaging engineering rather than monolithic integration. These three entities collectively represent divergent strategic bets on architecture convergence.
| Leading Market Players |
|---|
| Coherent Corp. |
| Broadcom Inc. |
| Lumentum Operations LLC |
| Sumitomo Electric Industries Ltd. |
| Finisar Corporation |
| NeoPhotonics Corporation |
| Source Photonics |
| Fujitsu Optical Components Limited |
| Accelink Technology Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud operators with direct foundry relationships and 18-24 month replacement cadences anchor pricing power toward volume-scaled contract structures, compressing margins for discrete component vendors while rewarding integrated subsystem suppliers with multi-year offtake agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by integration depth and certification grade. Premium tiers command valuation multiples for silicon photonics-DSP co-design capabilities, while standard tiers compete on foundry-scale unit economics. Price differentiation hinges on energy efficiency documentation under EU CSRD frameworks and backward-compatible sparing pools for legacy telecom operators. Pricing pressure stems from hyperscale procurement consolidation around vertically integrated module houses, with commodity discrete receivers experiencing the steepest margin compression. Data center operators exhibit lowest price sensitivity due to total-cost-of-ownership procurement scorecards, whereas legacy telecom incumbents remain most price-sensitive given extended depreciation schedules.
Supply Chain Analysis
Freight cost volatility and specialized cold-chain requirements for InP wafer shipments are forcing inventory positioning closer to end-use assembly clusters. Supply concentrates in Japan for indium phosphide substrate fabrication, Taiwan for CMOS foundry services, and China for captive module assembly serving state-directed procurement. Raw material dependencies include germanium epitaxy for photodetector integration, III-V compound semiconductors for avalanche photodiodes, and precision ceramic substrates for thermal management. Single-source vulnerability concentrates in Japanese wafer suppliers for coherent receiver inputs. Distribution runs through direct foundry partnerships for hyperscale buyers and traditional component distributors for legacy telecom sparing pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward premium specifications requiring silicon photonics-DSP co-design capabilities and published carbon footprint documentation under EU CSRD mandates.
For Market Incumbents: Deploy precision packaging engineering capabilities as the primary defensive lever. Incumbents should deepen backward integration into III-V wafer fabrication to secure allocation priority from Japanese substrate suppliers amid InP supply concentration. Capacity addition in 300mm silicon photonics foundries counters emerging Chinese domestic suppliers threatening volume positions. Certification investment across FCC Part 15, EU CE marking, and China GB standards simultaneously extends product development cycles but raises competitive barriers against fabless entrants lacking compliance infrastructure.
For New Entrants and Emerging Players: Fabless subsystem specialists can access white-space through co-packaged optics roadmaps at hyperscale network equipment buyers seeking switch-ASIC convergence. India's PLI scheme for telecom component manufacturing offers the most penetrable geography for module assembly investments serving domestic 5G and BharatNet fiber expansion. Edge computing metro rings across Germany, France, and the United Kingdom present underdeveloped demand for 400ZR coherent pluggables. Go-to-market positioning should emphasize direct foundry partnerships bypassing traditional component distributors losing share to captive supply arrangements.
For Investors and Strategic Acquirers: DSP vendors are the most active acquirer in this space, consolidating optical front-end suppliers to capture architecture redesign cycles at hyperscale buyers. Long-term viability favors vertically integrated module houses with in-house silicon photonics and packaging capabilities over discrete component assemblers facing margin compression. Acquisition target archetypes include precision coupling specialists in Japan and emerging design centers in Bengaluru and Hyderabad. The signal to monitor is divergence between U.S. export controls on advanced photonics equipment and China's import substitution directives, which will reconfigure supply chain geography and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics-DSP Co-Integration | Captures architecture redesign cycles at hyperscale cloud operators standardizing on pluggable coherent optics. |
| 300mm Foundry Capacity Expansion | Secures CMOS-compatible volume production economics against InP substrate supply concentration in Japan. |
| Multi-Jurisdictional Pre-Certification | Raises competitive barriers through sequential FCC, EU CE, and China GB compliance before commercial release. |
| Precision Packaging Engineering Acquisition | Consolidates scarce coupling expertise concentrated among Japanese and European research institutes. |
| Edge Computing Metro Ring Deployment | Addresses latency-sensitive AI inference demand across Frankfurt, Munich, and London aggregation nodes. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged optical component procurement managers at hyperscale data center operators, DSP vendor platform engineers, III-V wafer fabrication executives, and telecom OEM supply chain directors. Secondary validation drew from SEC 10-K filings, MIIT infrastructure directives, EU CSRD disclosure frameworks, and hyperscaler capital expenditure disclosures. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Comparable historical periods anchored the projection horizon to technology migration cycles observed during 100G-to-400G transitions. Segmentation dimensions modeled include integration level, technology platform, application distance tier, and end-user procurement sophistication. CAGRs derived from segment-level growth trajectories weighted by foundry capacity expansion timelines and regulatory compliance deadlines. Forecast inputs incorporated silicon photonics yield curves and InP substrate allocation patterns from Japanese suppliers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to U.S. export control enforcement, Chinese localization program acceleration, and EU energy efficiency mandate expansion. Forecasts reflect assumptions about technology substitution rates and supply chain reconfiguration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
India Laser Market
Optics
Anti Glare Film Market
Optics
Global High Purity Quartz Glass Market
Optics
Electro Optics Market
Optics
Optical Fiber Market
Optics
Fiber Optic Development Tools Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Tunable Laser Market
Optics
Collimating Lens Market
Optics
Interchangeable Lens Market
Optics
Optical Imaging Market
Optics
US Photonics Market
Optics
Plastic Lens Market
Optics
Fiber Optic Receiver Market
Optics
Optical Telescope Market
Optics
Global Fiber Optic Components Market