
 Global Camera Module Market | 2026-2036
Global Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Global Camera Module Market Intelligence
Plastic lens elements is pivoting toward glass-hybrid assemblies as manufacturers chase superior optical clarity in slim form factors. Sony Corporation leverages vertical integration from sensor die to module assembly. Samsung Electro-Mechanics anchors high-volume supply through captive smartphone demand. LG Innotek differentiates via Apple-exclusive supply relationships and automotive-grade certification.
A camera module integrates an image sensor, optical lens assembly, and driver IC within a compact housing to capture and convert photonic data into digital signals for downstream processing. CMOS technology dominates fabrication due to lower power draw and on-chip integration capacity versus legacy CCD architectures. Multi-lens configurations command premium positioning in smartphone flagships, while time-of-flight modules represent the fastest-expanding category as depth sensing proliferates across augmented reality and automotive safety systems. Infrared segments serve mature surveillance applications with stable margin pools.
FCC certification governs electromagnetic emissions for modules entering US consumer electronics, while EU RoHS and REACH restrict hazardous substances in lens coatings and solder interconnects. China's GB standards and MIIT type-approval requirements shape domestic product specifications and import substitution trajectories. Stakeholders must monitor regulatory divergence between CE marking and emerging Indian BIS imaging standards as supply chain regionalization accelerates.
Market Dynamics
Resolution mandates from China's MIIT and India's PLI localization requirements are restructuring procurement geography, forcing module suppliers to replicate assembly capacity across multiple regulatory jurisdictions rather than concentrating in single-source manufacturing clusters.
Growth Catalysts
- MIIT Resolution Mandates:China's Ministry of Industry and Information Technology requires higher-resolution imaging standards for domestic smartphones, compelling OEMs to upgrade module specifications across their product portfolios.
- Automotive Depth Sensing:Time-of-flight modules are penetrating advanced driver-assistance systems as vehicle manufacturers integrate 3D vision for collision avoidance and cabin monitoring.
- India PLI Scheme:Production-linked incentives concentrate procurement authority with local assemblers, accelerating import substitution for camera modules in the world's second-largest smartphone market.
Market Restraints
- Glass-Hybrid Cost Structure:The pivot from plastic to glass-hybrid lens assemblies elevates material costs and tightens margin pools for mid-tier module suppliers.
- Sensor Die Concentration:Advanced CMOS fabrication capacity concentrates among a handful of foundry operators, creating supply vulnerability for module integrators without captive wafer supply.
- EU REACH Compliance:Restrictions on hazardous substances in lens coatings and solder interconnects extend certification timelines and limit qualified supplier pools for European-bound shipments.
Strategic Opportunities
- India Domestic Assembly:Local module assembly under PLI incentives offers tariff arbitrage and faster regulatory clearance for brands serving the South Asian market.
- AR/VR Headset Integration:Passthrough camera arrays for mixed reality devices represent an emerging volume category with specialized form-factor requirements distinct from smartphone modules.
- Automotive-Grade Certification:AEC-Q100 and ISO 26262 qualification opens module supply to tier-one automotive electronics suppliers at premium pricing tiers.
Industry Challenges
- Optical Design Talent Scarcity:The shift to multi-lens computational imaging architectures outpaces the supply of experienced lens system engineers capable of optimizing ray tracing across asymmetric element configurations.
- FCC Certification Bottlenecks:Electromagnetic emissions testing for modules entering US consumer electronics creates queue delays during peak product launch windows, compressing effective selling seasons.
- Cross-Platform Integration Complexity:Module suppliers must maintain divergent driver IC firmware branches for Android, iOS, and proprietary automotive operating systems, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Camera Module Market |
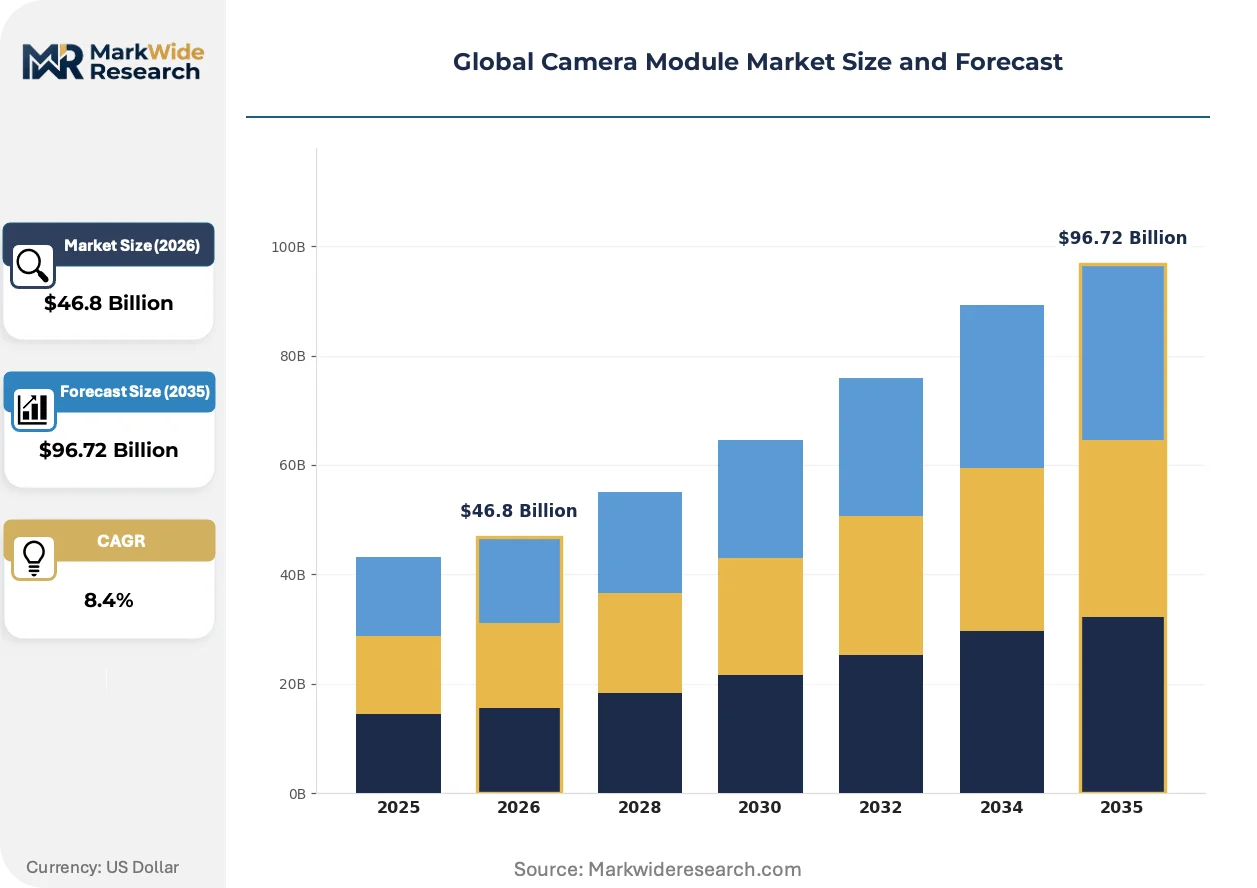
| Market Size in 2026 | $46.8 Billion |
| Market Size in 2035 | $96.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lens, Multi Lens, 3D Sensing, Time of Flight, Infrared Technology: CMOS, CCD, BSI, Spherical, Liquid Lens Application: Smartphones, Automotive Safety Systems, Surveillance Systems, Robotics, Augmented Reality End User: Consumer Electronics Manufacturers, Vehicle Integrators, Security Agencies, Industrial Automation Firms |
| Companies Covered | ams AG, Chicony Electronics Co., Ltd., Sony Corporation, STMicroelectronics, OmniVision Technologies, Samsung Electro-Mechanics, LG Innotek, Rayprus Holding Ltd. (Foxconn), Sunny Optical Technology (Group), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Camera Module Market Strategic Shifts & Innovations
Computational photography requirements and regulatory fragmentation are forcing module architecture decisions upstream into semiconductor design, collapsing traditional boundaries between sensor, lens, and processing domains.
Periscope folded-optics technology is converging with high-resolution CMOS die stacking to enable 10x optical zoom in sub-10mm smartphone thicknesses. Flagship OEMs in South Korea and China are adopting these assemblies as primary camera differentiators. This convergence is compressing the addressable market for conventional digital zoom solutions while elevating assembly precision requirements.
EU RoHS substance restrictions are tightening permissible thresholds for cadmium and lead in lens edge-blackening coatings and solder ball interconnects. Module suppliers serving European consumer electronics must reformulate materials or risk market exclusion. Automotive module categories face parallel pressure from REACH SVHC disclosure requirements for cabin-facing cameras.
Smartphone OEMs are consolidating module procurement under single-source framework agreements with exclusive design rights, displacing the multi-vendor competitive bidding that historically governed component purchasing. This concentration transfers design risk to module suppliers while locking in volume commitments. The shift is most visible in Apple's supply chain and is now replicating among Chinese flagship brands.
Global Camera Module Market Segmentation
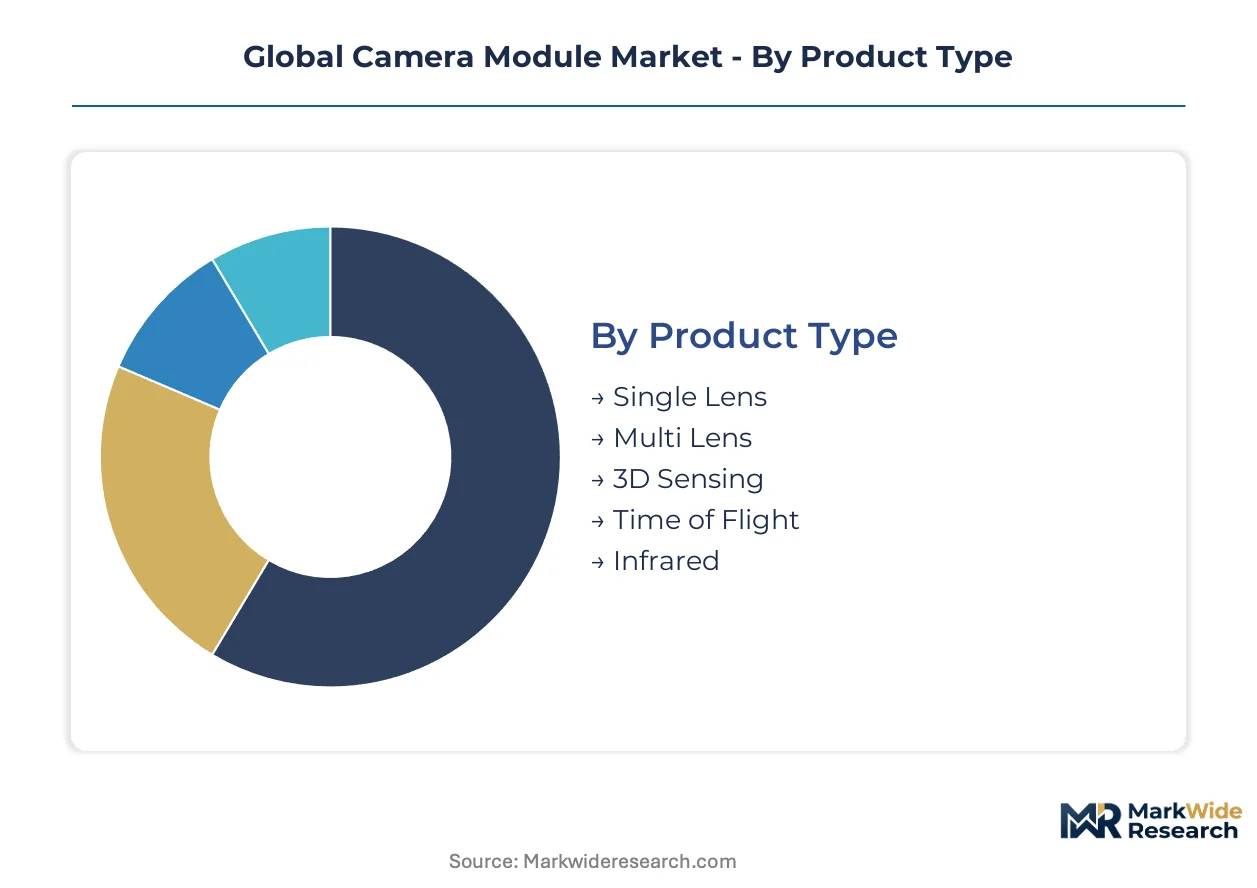
Camera module segmentation reveals how technical specifications cascade into divergent supply chain configurations. Product architecture determines lens material requirements, sensor die selection, and assembly precision thresholds that separate premium from commodity supply tiers.
Product Type:
Supply concentration clusters around configurations serving smartphone OEMs with the tightest form-factor constraints and highest volume predictability.
- Multi Lens:Arrays stack three to seven optical elements with independent voice-coil motors for computational depth mapping. Flagship smartphone programs in South Korea and China absorb the majority of high-precision assembly capacity as OEMs differentiate through optical zoom ranges.
- Time of Flight:Vertical-cavity surface-emitting laser arrays paired with single-photon avalanche diodes enable millimeter-accurate depth sensing. Automotive safety systems and augmented reality headsets are pulling capacity expansion as these modules penetrate cabin monitoring and passthrough vision applications.
- Single Lens:Fixed-focus assemblies dominate entry-tier smartphones and legacy surveillance deployments with minimal margin contribution.
- 3D Sensing:Structured light and stereoscopic configurations serve facial authentication and industrial metrology with specialized calibration requirements.
- Infrared:Thermal and near-infrared variants sustain mature security and night-vision applications with stable but limited growth trajectories.
Multi Lens absorbs the bulk of installed capacity; Time of Flight is expanding most quickly.
Technology:
Cost tier stratification separates captive wafer production from merchant foundry sourcing, with back-side illumination commanding premium positioning.
- CMOS:Complementary metal-oxide-semiconductor fabrication dominates with lower power draw and on-chip integration of analog-to-digital conversion. Sony and Samsung captive production supplies the majority of smartphone and automotive demand while merchant foundries serve secondary applications.
- BSI:Back-side illumination flips the sensor substrate to eliminate wiring obstruction, improving quantum efficiency in low-light conditions. Premium smartphone flagships and automotive night-vision systems concentrate demand as OEMs prioritize imaging performance over die cost.
- CCD:Charge-coupled device architectures persist in scientific and medical imaging with specialized readout requirements.
- Spherical:Curved sensor geometries reduce field curvature aberrations in compact optical systems.
- Liquid Lens:Electrowetting-based focal adjustment enables variable focus without mechanical actuation.
CMOS commands the dominant production footprint; BSI is gaining share fastest among premium tier deployments.
Application:
Volume concentration in smartphone procurement creates margin pressure that module suppliers offset through automotive and industrial diversification.
- Smartphones:Front and rear camera arrays drive the majority of unit demand with aggressive cost-down cycles and annual specification refresh requirements. Chinese OEMs and Apple anchor procurement volumes through multi-year framework agreements.
- Automotive Safety Systems:Surround-view, driver monitoring, and forward-collision cameras require AEC-Q100 qualification and extended temperature operation. European and Japanese vehicle programs are accelerating module qualification as regulatory mandates for advanced driver-assistance expand.
- Surveillance Systems:Fixed and pan-tilt-zoom cameras serve government and enterprise security infrastructure with multi-year deployment cycles.
- Robotics:Machine vision and navigation modules enable autonomous mobile platforms and manufacturing automation.
- Augmented Reality:Passthrough and spatial mapping cameras impose stringent size and power constraints distinct from smartphone form factors.
Smartphones absorb the bulk of installed capacity; Automotive Safety Systems is climbing the fastest.
End User:
Customer type determines certification burden, volume commitment structures, and technical support intensity across divergent procurement patterns.
- Consumer Electronics Manufacturers:Smartphone, tablet, and laptop OEMs drive high-volume demand with compressed product cycles and consolidated supplier bases. Foxconn, Pegatron, and Chinese EMS providers concentrate assembly authority under PLI and MIIT compliance frameworks.
- Vehicle Integrators:Tier-one automotive electronics suppliers require ISO 26262 functional safety certification and multi-year production guarantees. Bosch, Continental, and Denso anchor module procurement with stringent qualification protocols.
- Security Agencies:Government and municipal surveillance programs impose cybersecurity and data sovereignty requirements.
- Industrial Automation Firms:Manufacturing and logistics robotics vendors prioritize machine vision accuracy and environmental durability.
Consumer Electronics Manufacturers absorb the bulk of installed capacity; Vehicle Integrators is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of module procurement through smartphone OEM concentration, while supply chain regionalization accelerates assembly replication across regulatory jurisdictions. India's PLI scheme and China's MIIT mandates are redrawing procurement geography.
China
Domestic smartphone OEMs anchor module demand through multi-year framework agreements with exclusive design rights. MIIT mandates higher-resolution imaging standards for devices sold within the country, forcing specification upgrades across product portfolios. Shenzhen and Dongguan manufacturing clusters concentrate precision assembly capacity for glass-hybrid lens configurations.
South Korea
Flagship smartphone programs from Seoul-based OEMs absorb the majority of high-precision multi-lens assembly capacity. The country's national technology regulator shapes domestic certification requirements for electromagnetic emissions. Suwon and Gyeonggi-do industrial corridors host captive sensor fabrication and module integration facilities.
United States
Consumer electronics OEMs and automotive tier-one suppliers drive demand for time-of-flight and automotive-grade modules. FCC certification governs electromagnetic emissions for modules entering consumer electronics, creating queue delays during peak launch windows. California's Bay Area technology corridor concentrates AR/VR headset development requiring specialized passthrough camera arrays.
India
Production-linked incentive schemes concentrate procurement authority with local assemblers, accelerating import substitution in the world's second-largest smartphone market. BIS imaging standards are emerging as regulatory requirements for domestic device certification. Tamil Nadu and Uttar Pradesh manufacturing corridors scale module assembly capacity under tariff arbitrage advantages.
Japan
Automotive electronics suppliers anchor demand for AEC-Q100 qualified modules serving advanced driver-assistance systems. METI industrial policy supports domestic imaging technology development for vehicle safety applications. Kyushu and Nagoya industrial clusters concentrate automotive module qualification and extended-temperature testing facilities.
Global Camera Module Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply at the sensor die level and fragmented assembly tiers. Sony and Samsung captive production dominates CMOS wafer supply, while module integrators compete on optical design and assembly precision. Three archetypes prevail: vertically integrated sensor-to-module suppliers, pure-play optical specialists, and contract manufacturers serving EMS providers. Capacity replication across jurisdictions and automotive-grade certification acquisition represent the dominant competitive moves.
Among Asia-Pacific-based integrators, Chicony Electronics Co., Ltd., LG Innotek, and Samsung Electro-Mechanics exemplify divergent strategic positioning. Chicony occupies a position within the contract manufacturing tier serving multiple OEM programs. LG Innotek represents the exclusive-supply archetype through Apple-dedicated relationships and automotive certification. Samsung Electro-Mechanics anchors the captive-demand model, leveraging internal smartphone volume to sustain high-throughput assembly lines.
| Leading Market Players |
|---|
| ams AG |
| Chicony Electronics Co., Ltd. |
| Sony Corporation |
| STMicroelectronics |
| OmniVision Technologies |
| Samsung Electro-Mechanics |
| LG Innotek |
| Rayprus Holding Ltd. (Foxconn) |
| Sunny Optical Technology (Group) |
| Others |
Cost & Logistics Intelligence
Smartphone OEM consolidation under exclusive framework agreements is forcing module suppliers to absorb design risk and certification costs, compressing margin pools for non-captive integrators while elevating pricing power for vertically integrated sensor-to-module producers. Glass-hybrid lens migration and multi-jurisdiction assembly replication further stratify cost structures across premium and commodity tiers.
Pricing Analysis
Volume-margins split sharply between flagship multi-lens arrays commanding premium positioning and single-lens commodity assemblies facing relentless cost-down cycles. Three-tier pricing structure across premium, standard, and economy levels differentiates by optical element count, BSI sensor grade, and automotive certification status. Pricing pressure stems from OEM single-sourcing consolidation transferring design burden to suppliers. Entry-tier smartphone integrators exhibit highest price sensitivity; automotive tier-one suppliers accept premium pricing for AEC-Q100 qualification.
Supply Chain Analysis
Advanced CMOS sensor die supply rests on captive fabrication in Japan and South Korea, with merchant foundry capacity concentrated in Taiwan. Glass-hybrid lens elements, voice-coil motors, and specialized driver ICs constitute critical input dependencies. Single-source vulnerability concentrates at the wafer level, where Sony and Samsung captive production controls premium sensor supply. Distribution runs through EMS providers Foxconn and Pegatron, with direct automotive tier-one relationships bypassing contract assembly for safety-critical modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
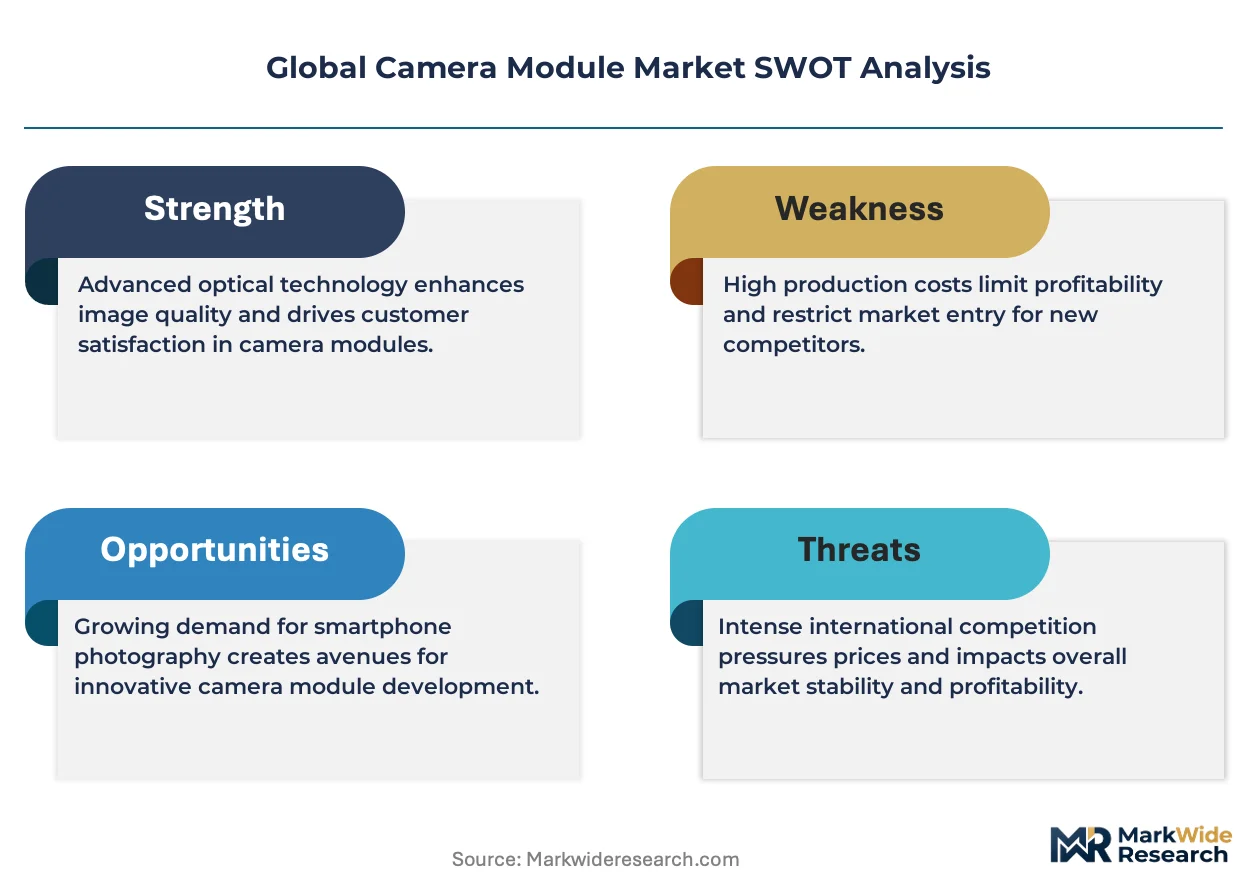
This market reads as a cost-of-compliance story where EU REACH substance restrictions and automotive-grade certification requirements create regulatory moats that favor incumbents with established qualification protocols and multi-jurisdiction assembly footprints.
For Market Incumbents: Deepen automotive-grade certification acquisition to capture premium pricing tiers as ADAS penetration accelerates, while replicating assembly capacity in India under PLI tariff arbitrage. Threat of Chinese flagship OEMs consolidating procurement under exclusive design rights demands defensive positioning through captive sensor supply or Apple-tier exclusive relationships. For New Entrants and Emerging Players: Direct-to-module procurement platforms for mid-tier smartphone brands offer lower barrier entry than flagship supply chains. White-space targets include India domestic assembly under PLI incentives and AR/VR passthrough camera arrays with specialized form-factor requirements distinct from smartphone modules. Machine vision for industrial robotics represents the most penetrable segment with less consolidated buyer power. For Investors and Strategic Acquirers: The window for entry favors automotive-qualified module integrators with AEC-Q100 and ISO 26262 credentials, as vehicle electrification and safety mandates extend the addressable market. Long-term viability hinges on backward integration into optical design capability or sensor die supply. Watch MIIT resolution mandate enforcement velocity as inflection indicator for premium module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Certification Investment | AEC-Q100 qualification opens supply to Bosch, Continental, and Denso at premium pricing tiers. |
| India PLI Assembly Expansion | Local module assembly under PLI schemes accelerates regulatory clearance for South Asian smartphone demand. |
| Glass-Hybrid Lens Migration | Optical clarity upgrades in slim form factors differentiate flagship Samsung and Chinese OEM programs. |
| Periscope Folded-Optics Integration | 10x optical zoom convergence with stacked CMOS die compresses conventional digital zoom addressable market. |
| Time-of-Flight Capacity Buildout | VCSEL and SPAD module expansion captures automotive cabin monitoring and AR passthrough vision growth. |
Research Approach
SEC filings, customs trade databases, and MIIT type-approval registries formed the secondary backbone, cross-referenced against primary interviews with smartphone OEM procurement directors, automotive tier-one supplier quality engineers, and EMS provider supply chain managers. Bottom-up module shipment data triangulated against top-down smartphone and automotive production estimates.
Historical trendline analysis of CMOS sensor die output, lens assembly precision migration, and regulatory certification timelines anchored the projection framework across the analysis window. Segmentation modeling incorporated product architecture, technology tier, application vertical, and end-user procurement pattern dimensions. CAGRs derived from supply-side capacity expansion schedules and demand-side specification upgrade cycles, with time-of-flight and automotive safety system penetration as primary growth inputs.
The model holds under stable regulatory enforcement and OEM consolidation trajectories; deviation in MIIT mandate timing, PLI scheme renewal, or REACH substance restriction tightening would shift volume and value distributions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Gel Imaging Documentation Market
Imaging
Camera Technology Market
Imaging
Microscope Digital Cameras Market
Imaging
Digitizer Market
Imaging
Chemiluminescence Imaging Market
Imaging
Document Imaging Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Global Broadcast Cameras Market
Imaging
Handheld Imaging Devices Market
Imaging
Global Mobile Image Sensor Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Webcam Market
Imaging
Global Microbolometer Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market