
 Optical Lens for Mobile Phone Market | 2026-2036
Optical Lens for Mobile Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Lens for Mobile Phone Market Insights
Component refurbishment and upgrade-cycle extension is reconfiguring margin pools away from first-fit OEM supply toward aftermarket lens replacement and module recycling. Sunny Optical Technology sustains manufacturing scale across plastic and hybrid lens arrays for mid-tier handset brands. Largan Precision dominates high-aspheric glass lens production for flagship periscope cameras. LG Innotek anchors supply relationships with Korean smartphone OEMs through integrated module-to-lens design.
An optical lens for mobile phone is a precision-engineered refractive element, typically molded from optical-grade plastic or ground from borosilicate glass with surface tolerances below 0.5 micrometers, designed to focus incident light onto a CMOS image sensor for digital capture. Wide angle and telephoto product types command the largest volume commitments from smartphone manufacturers, though macro lenses are gaining traction in specialized photography handsets. Glass material segments retain premium positioning in flagship devices where thermal stability and light transmission rates exceed plastic alternatives, while hybrid constructions balance cost and optical performance across mid-range portfolios.
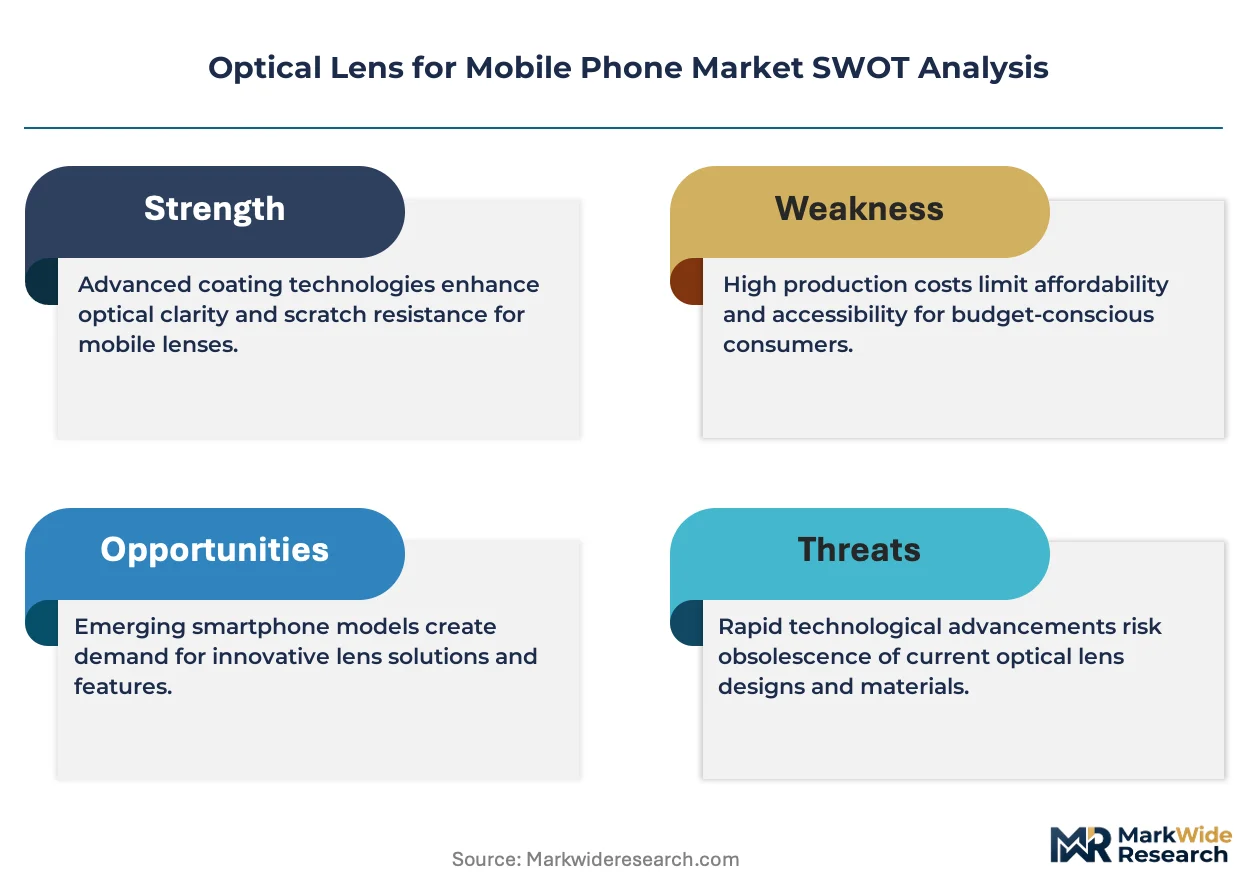
MIIT certification requirements in China and REACH substance restrictions in Europe constrain adhesive and coating chemistries used in lens barrel assemblies, raising compliance costs for cross-border suppliers. The EU Green Deal circular-economy directives are pressuring OEMs to design lenses for disassembly and material recovery. Stakeholders must monitor how divergent regional sustainability mandates reshape supplier qualification timelines and material selection protocols.
Market Dynamics
Periscope telephoto module proliferation is compressing design cycles and forcing lens suppliers to synchronize roadmaps with smartphone OEM camera system architectures. MIIT quality certification tightening in China accelerates this coordination burden.
Growth Catalysts
- Periscope Lens Adoption:Smartphone OEMs in China are expanding orders for periscope-style telephoto modules as handset photography capabilities become primary purchase determinants for consumers.
- MIIT Certification Standards:Tightened camera module quality requirements from China's Ministry of Industry and Information Technology are elevating technical barriers and consolidating supplier relationships around certified manufacturers.
- Guangdong Cluster Concentration:Lens assembly operations concentrate in Guangdong Province, where integrated manufacturing ecosystems feed both domestic handset production and export supply chains with shortened logistics loops.
Market Restraints
- Glass Input Cost Volatility:Borosilicate glass raw material prices fluctuate with energy costs and specialty chemical availability, compressing margins for high-aspheric lens producers serving flagship segments.
- Supply Concentration Risk:High-aspheric glass lens manufacturing concentrates among a limited supplier base in Taiwan and Korea, creating vulnerability to regional disruption or capacity allocation decisions.
- Plastic Thermal Limitation:Optical-grade plastic lenses face performance ceilings in thermal stability and light transmission rates that constrain their deployment in premium periscope modules requiring extended focal lengths.
Strategic Opportunities
- EU Circular Economy Mandates:EU Green Deal directives pressuring OEMs to design lenses for disassembly and material recovery create first-mover advantage for suppliers with modular barrel architectures and recyclable adhesive chemistries.
- Macro Photography Application:Specialized photography handsets are incorporating dedicated macro lenses, opening volume commitments beyond the wide-angle and telephoto categories that currently dominate procurement.
- Hybrid Construction Convergence:Mid-range smartphone portfolios are adopting glass-plastic hybrid lens arrays that balance optical performance against unit economics, expanding addressable market for suppliers with dual-material process capabilities.
Industry Challenges
- Sub-Micron Tolerance Manufacturing:Surface tolerance requirements below 0.5 micrometers demand capital-intensive grinding and molding equipment with extended qualification timelines, raising entry barriers for new suppliers.
- REACH Compliance Timeline:European chemical restrictions on adhesives and coating materials used in lens barrel assemblies are extending supplier qualification cycles and requiring reformulation investments.
- Cross-Border Certification Friction:Divergent regional sustainability mandates between MIIT standards in China and EU Green Deal requirements are forcing suppliers to maintain parallel material selection protocols and testing regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Lens for Mobile Phone Market |
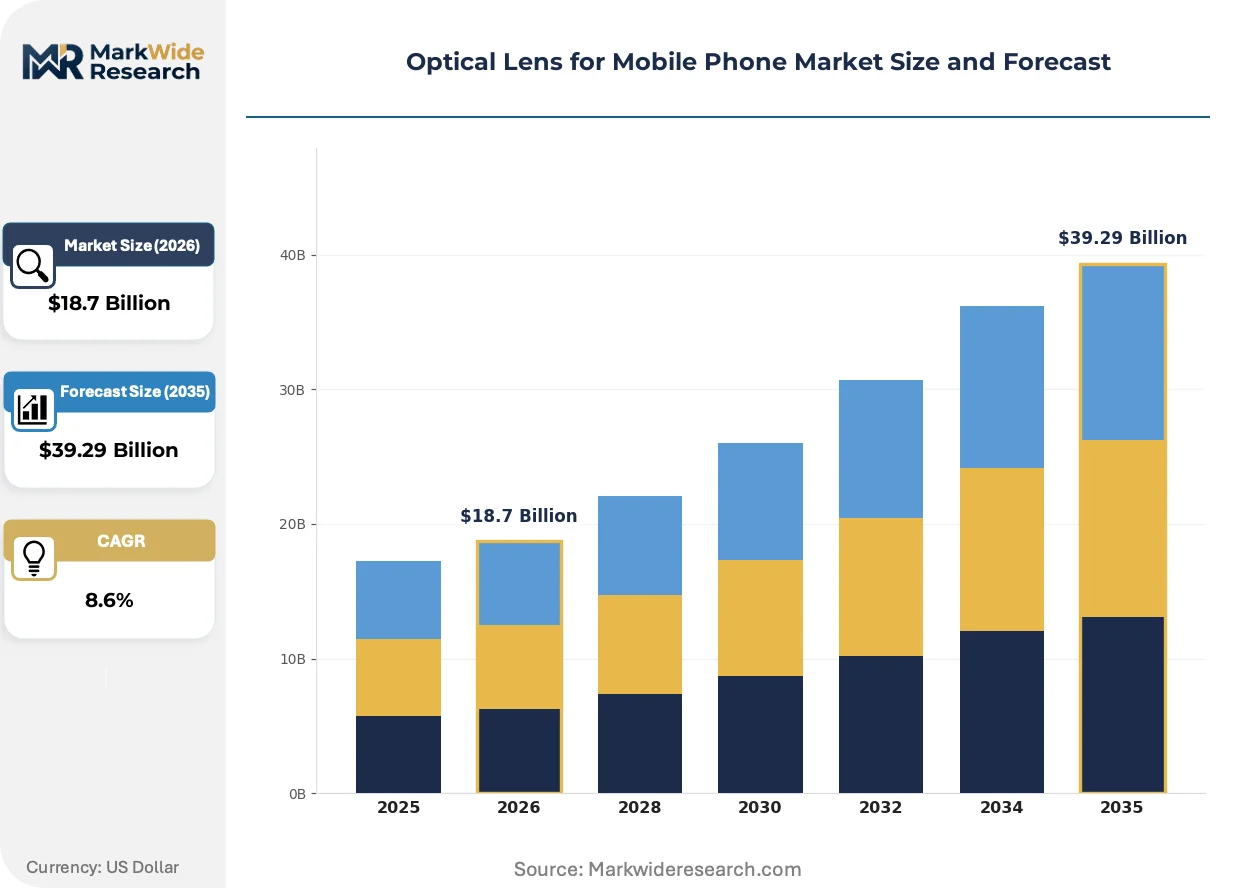
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Angle, Telephoto, Macro, Fisheye Material: Glass, Plastic, Polycarbonate, Hybrid Application: Photography, Videography, Augmented Reality, Virtual Reality End User: Smartphone Manufacturers, Aftermarket Retailers, OEMs, Distributors |
| Companies Covered | Largan Precision Co., Ltd., Sunny Optical Technology (Group) Co., Ltd., Samsung Electro-Mechanics Co., Ltd., Genius Electronic Optical Co., Ltd., Asia Optical Co., Inc., SEKONIX Co., Ltd., OFILM Group Co., Ltd., AAC Technologies Holdings Inc., LG Innotek Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Lens for Mobile Phone Market Trends and Innovations
Computational photography integration is reshaping hardware-software boundaries, requiring lens designers to optimize for algorithmic correction rather than pure optical perfection. This convergence is digitizing traditional specification frameworks.
Wavefront-coding technology is digitizing depth-of-field control through modified phase masks in lens elements that enable post-capture focus adjustment. Flagship smartphone OEMs are integrating these elements into periscope modules to reduce mechanical complexity. This approach is digitizing the trade-off between lens stack thickness and optical zoom range, compressing physical volume requirements.
REACH substance restrictions in Europe are constraining adhesive and coating chemistries used in lens barrel assemblies, raising compliance costs for cross-border suppliers. The regulation is forcing reformulation of traditional lens mounting compounds and anti-reflective coatings. Mid-tier suppliers serving multiple geographies are responding by establishing separate production lines with region-specific material sets.
Aftermarket lens replacement demand is fragmenting traditional OEM-first procurement patterns as consumers extend handset lifecycles through component refurbishment. Independent repair channels in North America and Europe are building inventory positions for replacement camera modules. This behavioral shift is most visible in markets with right-to-repair legislation gaining traction, where diagnostic tools and spare part availability are becoming purchase decision factors.
Optical Lens for Mobile Phone Market Segmentation
Optical lens segmentation in mobile phones maps directly to camera system architecture decisions made by smartphone OEMs. Each dimension—product type, material, application, and end user—carries distinct margin profiles and supplier qualification requirements that reshape competitive positioning.
Product Type:
Use-case spectrum spans casual photography through professional-grade imaging, with focal length requirements driving lens stack complexity and unit economics.
- Wide Angle:These lenses incorporate multiple aspheric elements to minimize distortion across 120-degree fields of view. Flagship handsets from Guangdong-based manufacturers anchor procurement volumes as ultra-wide photography becomes a standard consumer expectation.
- Telephoto:Periscope-style folded optics enable 5x-10x optical zoom in sub-10mm z-heights. MIIT certification tightening in China is compressing supplier qualification timelines for these precision modules.
- Macro:Dedicated close-focus optics serve specialized photography handsets with working distances below 10cm.
- Fisheye:Extreme 180-degree coverage addresses niche VR capture and creative imaging applications.
The dominant share belongs to Wide Angle, while Telephoto is closing the gap fastest.
Material:
Cost tier separation between premium glass and volume plastic creates distinct manufacturing footprints and capital intensity requirements.
- Glass:Ground borosilicate elements deliver thermal stability and transmission rates exceeding 99%. High-aspheric production concentrates in Taiwan and Korea, where sub-micron tolerance grinding equipment commands extended depreciation schedules.
- Hybrid:Glass-plastic combinations balance optical performance against unit economics in mid-range portfolios. Guangdong assembly clusters favor this construction for domestic handset brands targeting 200-400 USD price bands.
- Plastic:Injection-molded optical-grade polymers serve cost-sensitive volume segments with shorter mold cycle times.
- Polycarbonate:Lower refractive index alternatives occupy entry-tier handsets where thermal performance is secondary to bill-of-materials compression.
Glass commands premium positioning in flagship devices, though Hybrid constructions are expanding their addressable market most quickly.
Application:
Volume concentration follows smartphone camera system roadmaps, with computational photography integration blurring traditional hardware-software boundaries.
- Photography:Still-image capture drives the largest lens commitments across all smartphone tiers.
- Videography:Cinematic mode and 8K recording demand stabilized lens barrels with reduced focal breathing.
- Augmented Reality:Time-of-flight and structured light systems require specialized infrared-transmissive coatings.
- Virtual Reality:Stereoscopic lens pairs for mobile VR headsets represent a smaller but specification-intensive segment.
Photography maintains the installed base, while Videography is climbing the fastest as content creation monetization reshapes OEM priorities.
End User:
Customer type determines contract structure, with first-fit OEM supply diverging sharply from aftermarket replacement patterns.
- Smartphone Manufacturers:Direct OEM relationships specify qualification protocols, volume commitments, and co-development roadmaps.
- Aftermarket Retailers:Component refurbishment channels in North America and Europe are building inventory positions as right-to-repair legislation extends handset lifecycles.
- OEMs:Module-integrated suppliers purchase bare lens elements for barrel assembly and alignment.
- Distributors:Wholesale channels serve independent repair operators and regional handset assemblers with standard catalog offerings.
Smartphone Manufacturers control the volume base, though Aftermarket Retailers are gaining share fastest as circular-economy directives reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese buyers prioritize periscope telephoto capabilities regardless of price tier, while Indian and Southeast Asian markets show acute sensitivity to bill-of-materials costs in lens selection.
China
MIIT certification tightening accelerates supplier consolidation around qualified manufacturers. The Ministry of Industry and Information Technology's camera module quality standards now mandate extended thermal cycling tests. Guangdong Province hosts the densest lens assembly clusters, with Shenzhen and Dongguan feeding both domestic handset brands and export supply chains.
South Korea
Flagship smartphone OEMs drive specifications for high-aspheric glass elements in folded-optics telephoto modules. The Korean Agency for Technology and Standards enforces electromagnetic compatibility protocols that lens barrel assemblies must satisfy. Gyeonggi Province concentration around Suwon and Hwaseong anchors module-to-lens integrated design partnerships.
Japan
Specialized coating and grinding equipment suppliers serve the sub-micron tolerance tier of the market. METI's manufacturing technology roadmap prioritizes optical component precision as a strategic capability. Nagoya and surrounding Aichi Prefecture maintain legacy precision optics infrastructure now repurposed for mobile lens element production.
Taiwan
High-aspheric glass lens grinding capacity concentrates among a limited supplier base serving premium periscope module requirements. The Bureau of Standards, Metrology and Inspection administers optical component quality verification protocols. Taichung and Tainan industrial zones house capital-intensive grinding equipment with extended depreciation schedules.
United States
Aftermarket lens replacement channels expand as right-to-repair legislation gains traction in multiple states. The Federal Trade Commission's repair restrictions enforcement creates inventory demand for independent service providers. California and Texas distribution hubs stock replacement camera modules for extended handset lifecycle support.
Optical Lens for Mobile Phone Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. High-aspheric glass lens production demands sub-micron grinding equipment and extended qualification timelines that few suppliers can sustain. Plastic and hybrid lens arrays operate at different capital intensity thresholds, enabling volume-focused competitors to capture mid-tier procurement. Three archetypes dominate: precision grinding specialists, integrated module-to-lens designers, and scale-driven hybrid manufacturers. Competitive moves center on capacity allocation decisions and co-development roadmap synchronization with smartphone OEM camera system architectures.
Within the precision grinding tier, Largan Precision Co., Ltd. exemplifies capability concentration in high-aspheric glass elements. Sunny Optical Technology (Group) Co., Ltd. anchors the scale-driven hybrid manufacturing archetype across plastic and glass-plastic combinations. LG Innotek Co., Ltd. occupies a position representing integrated module-to-lens design relationships with Korean smartphone OEMs. These three entities illustrate the structural segmentation between optical performance specialization, manufacturing scale, and vertical integration strategies.
| Leading Market Players |
|---|
| Largan Precision Co., Ltd. |
| Sunny Optical Technology (Group) Co., Ltd. |
| Samsung Electro-Mechanics Co., Ltd. |
| Genius Electronic Optical Co., Ltd. |
| Asia Optical Co., Inc. |
| SEKONIX Co., Ltd. |
| OFILM Group Co., Ltd. |
| AAC Technologies Holdings Inc. |
| LG Innotek Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Taiwanese high-aspheric glass grinding capacity anchors the upstream tier, concentrating pricing power among sub-micron tolerance specialists while downstream margin pools fragment toward aftermarket replacement channels and module recycling operations.
Pricing Analysis
Aftermarket lens replacement and refurbishment services drive lifetime value expansion as consumers extend handset lifecycles. Three-tier pricing structure across premium glass, hybrid construction, and molded plastic separates flagship periscope modules from mid-range portfolios and entry-tier alternatives. Price differentiation rests on MIIT certification grade and volume scale commitments from Guangdong-based smartphone OEMs. Cost compression in plastic lens arrays intensifies because thermal performance limitations constrain their deployment in premium telephoto modules. Mid-tier domestic handset brands exhibit acute price sensitivity, while flagship OEMs prioritize optical performance over unit economics.
Supply Chain Analysis
Export-control restrictions on sub-micron grinding equipment limit technology transfer to emerging manufacturing hubs. Supply concentration in Taiwan, South Korea, and Japan draws from specialized borosilicate glass feedstock, precision coating chemistries, and capital-intensive aspheric grinding machinery. Single-source vulnerability runs through Taiwan's limited high-aspheric capacity serving periscope module requirements. Distribution runs through Guangdong assembly clusters feeding domestic handset production and export supply chains with integrated logistics loops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component refurbishment and aftermarket module replacement represent the fastest-expanding revenue layer, outpacing first-fit OEM supply as right-to-repair legislation extends handset lifecycles across North American and European markets.
For Market Incumbents: Harden supply relationships with Guangdong smartphone OEMs through co-development roadmaps synchronized with periscope camera system architectures. Deepen backward integration into optical-grade plastic resin production to offset borosilicate glass cost volatility. MIIT certification tightening threatens supplier consolidation around qualified manufacturers, making certification investment the critical defensive lever. For New Entrants and Emerging Players: Mid-range hybrid lens arrays for 200-400 USD smartphone price bands in Southeast Asia represent the most penetrable entry point, given lower capital intensity thresholds and expanding volume commitments from regional handset brands. Specialized macro lens modules for photography-focused handsets offer white-space access beyond saturated wide-angle and telephoto categories. Direct partnerships with Guangdong assembly clusters provide the most viable go-to-market path. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision grinding specialists in Taiwan possessing sub-micron tolerance equipment and extended depreciation schedules. The five-to-ten year viability window favors suppliers with dual-material process capabilities spanning glass and plastic constructions. Watch for MIIT certification expansion beyond camera modules into lens barrel assemblies as the inflection signal for accelerated supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Periscope Module Co-Development Partnership | Aligns lens roadmaps with Samsung and Xiaomi camera system architectures. |
| Backward Integration into Optical Resin Production | Captures margin from plastic lens arrays serving mid-tier handset volumes. |
| MIIT Certification Pre-Qualification Investment | Accelerates supplier approval timelines for Chinese domestic OEM procurement. |
| Modular Barrel Architecture for Disassembly | Positions suppliers for EU Green Deal circular-economy compliance requirements. |
| Aftermarket Distribution Channel Expansion | Builds inventory positions in North America as right-to-repair legislation advances. |
Research Methodology
The analysis maps wide-angle, telephoto, macro, and fisheye lens categories, each validated through primary interviews with smartphone OEM camera system architects, lens supplier R&D directors, Guangdong assembly cluster operations managers, and aftermarket refurbishment channel distributors. Secondary sources include MIIT certification databases, EU REACH substance restriction filings, SEC 10-K disclosures from listed optical component manufacturers, and customs trade data for borosilicate glass imports. Bottom-up lens shipment estimates triangulate against top-down smartphone production forecasts.
Assumptions held fixed include MIIT certification standards at current stringency levels and EU Green Deal implementation timelines, while periscope adoption rates and aftermarket replacement volumes varied across sensitivity scenarios. Segmentation modeling incorporated product type, material construction, application use case, and end-user channel dimensions alongside regional production cluster dynamics. CAGRs derive from fitted growth curves calibrated to historical lens shipment patterns and announced OEM camera system roadmaps. Forecast inputs include announced periscope module design wins and right-to-repair legislative progression.
Practitioners should monitor MIIT certification scope expansion and EU circular-economy directive enforcement intensity for early signals of supplier qualification disruption. Forecasts reflect documented assumptions regarding smartphone replacement cycle extension and computational photography integration rates. Material shifts in export-control restrictions on sub-micron grinding equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Latin America Optical Imaging Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
MEMS Mirrors Market
Optics
Tunable Laser Market
Optics
Global High Purity Quartz Glass Market
Optics
Electro Optics Market
Optics
Europe Laser Interferometer Market
Optics
Optical Imaging Market
Optics
Smartphone Camera Lenses Market
Optics
Digital Holographic Microscopy Market
Optics
Beam Combining Optics Market
Optics
Photonic Crystals Market
Optics
Beam Expanders Market
Optics
Anti Glare Film Market
Optics
Smart Glass Market
Optics
Acrylic Lenses Market