
 RF Front End Module Market | 2026-2036
RF Front End Module Market Size, Share, and Industry Trends Forecast 2026-2036
RF Front End Module Market Intelligence
Consumer electronics procurement is consolidating around 5G-enabled handsets and IoT gateways, pulling RF front end volumes upward. Murata Manufacturing Co., Ltd. leverages its filter dominance and LTCC substrate expertise to anchor Japanese supply chains. Qualcomm Technologies, Inc. competes through modem-to-antenna platform integration, while Qorvo, Inc. specializes in GaN-based defense and base station amplifiers.
An RF front end module integrates filters, power amplifiers, low-noise amplifiers, and switches into a single package, typically operating between 600 MHz and 6 GHz for cellular bands and extending to 28–39 GHz for mmWave. The assembly relies on advanced packaging such as wafer-level chip-scale or system-in-package to minimize insertion loss and footprint. Filter and power amplifier categories command the deepest margin pools due to material scarcity in BAW resonators and thermal management complexity in GaN die. CMOS technology segments face commoditization pressure, whereas GaAs and hybrid architectures sustain premium positioning in automotive radar and satellite communication terminals.
The FCC in the United States enforces stringent out-of-band emission limits that shape power amplifier linearity requirements, while the EU's Radio Equipment Directive mandates interoperability testing for CE-marked modules. China's MIIT imposes domestic encryption and frequency authorization protocols that condition market access. Stakeholders must monitor spectrum reallocation proceedings and packaging material export controls to anticipate cost structure shifts and qualification timelines.
Market Dynamics
Smartphone OEM procurement of integrated 5G modules is intensifying as sub-6 GHz and mmWave architectures proliferate, forcing filter and amplifier suppliers to co-locate design teams with system-level packaging clusters.
Growth Catalysts
- 5G mmWave spectrum allocation:South Korea's Ministry of Science and ICT released 28 GHz bands for commercial deployment, pulling module volumes into advanced packaging facilities in Suwon and Pyeongtaek.
- Filter material scarcity premiums:Bulk acoustic wave resonator-grade aluminum nitride substrates face allocation constraints, concentrating margin pools with Japanese and Korean substrate specialists.
- Automotive radar frequency expansion:77-81 GHz band designation for collision avoidance systems is creating parallel demand channels for GaAs low-noise amplifiers and beamforming switches.
Market Restraints
- GaN die thermal management costs:Defense and base station power amplifiers require diamond or silicon carbide heat spreaders, adding 15-20% bill-of-materials overhead compared to LDMOS alternatives.
- Packaging equipment lead times:Flip-chip bonders and plasma dicers from German and Japanese tool vendors currently extend beyond 14 months, constraining capacity expansion timelines.
- EU electromagnetic compatibility thresholds:The Radio Equipment Directive's tightened out-of-band emission limits force redundant filtering stages, increasing module footprint and insertion loss.
Strategic Opportunities
- India PLI scheme for telecom equipment:Domestic value-add mandates for 5G base stations create localized assembly demand for sub-6 GHz front end modules with reduced import duty exposure.
- Satellite terminal flat-panel arrays:Low-earth orbit broadband constellations require Ka-band beamforming modules, opening volume channels outside cellular handset cyclicality.
- Wafer-level chip-scale packaging convergence:Integration of acoustic filters with CMOS switches on silicon interposers enables single-source module procurement for mid-tier smartphone OEMs.
Industry Challenges
- Compound semiconductor process engineering talent:GaAs and GaN foundry operations face acute shortages of epitaxy technicians and RF device physicists, extending new product introduction cycles.
- Multi-band carrier aggregation certification:FCC and MIIT interoperability testing for non-contiguous spectrum combinations adds 4-6 months to module qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Front End Module Market |
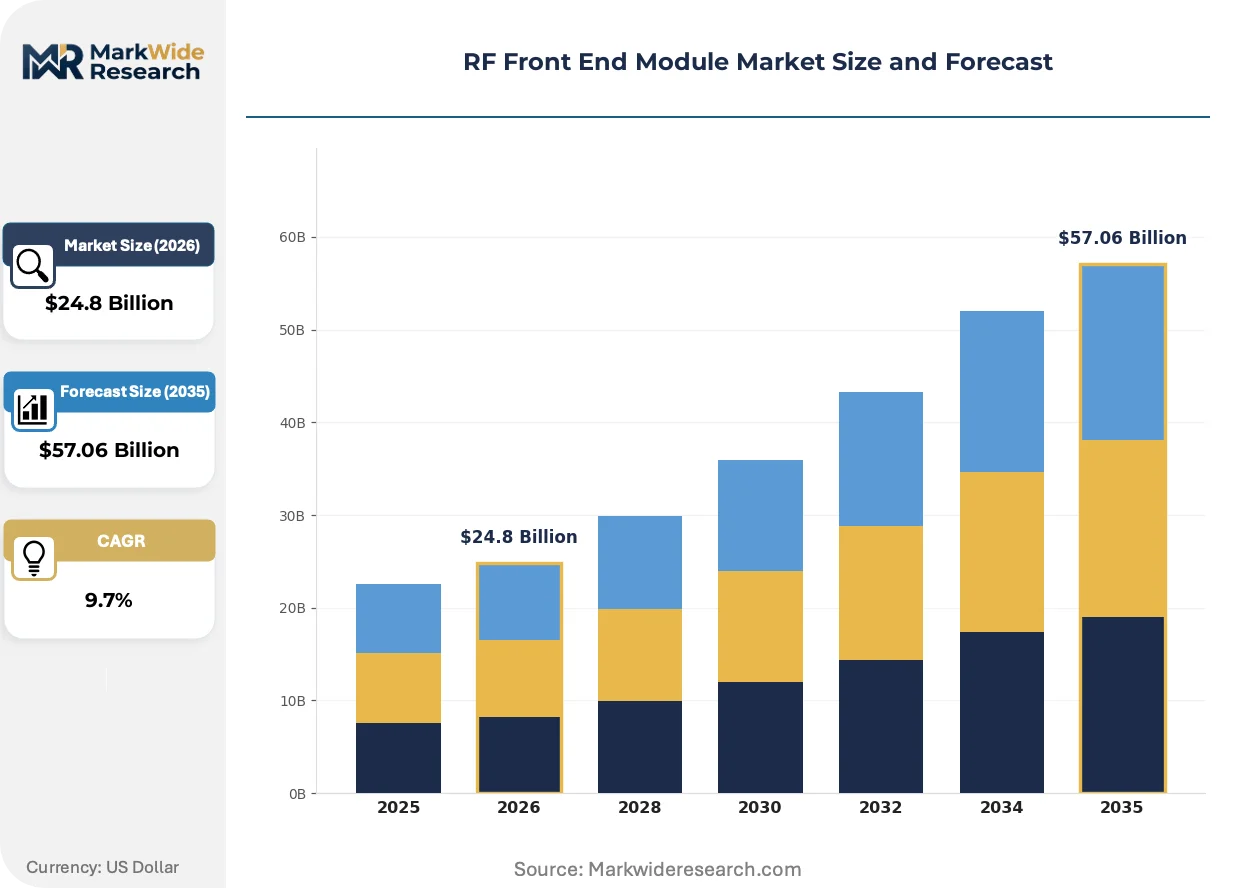
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $57.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter, Amplifier, Transceiver, Power Amplifier Technology: GaN, GaAs, CMOS, Hybrid Application: Telecommunication, Satellite Communication, Aerospace, Automotive End User: Telecom Operators, Defense, Commercial, Consumer Electronics |
| Companies Covered | Murata Manufacturing Co., Ltd., Infineon Technologies AG, Skyworks Solutions, Inc., TDK Corporation, NXP Semiconductors N.V., Broadcom Inc., Qualcomm Technologies, Inc., Analog Devices, Inc., Qorvo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Front End Module Market Strategic Shifts & Innovations
Module architectures are compressing discrete component counts through acoustic filter integration and antenna tuning convergence, while regulatory pressure on electromagnetic emissions forces linearity investments that reshape power amplifier design priorities.
BAW-SMR technology is overtaking traditional FBAR constructions in sub-6 GHz filtering applications due to superior power handling and temperature stability. Tier-one smartphone OEMs have shifted procurement specifications toward solidly mounted resonator designs for n77 and n79 bands. This transition is overtaking legacy air-gap architectures in high-band filter sockets, compressing the addressable market for incumbent FBAR specialists.
The FCC's revised out-of-band emission limits for 3.5 GHz CBRS and 6 GHz unlicensed operations now mandate adjacent channel leakage ratio thresholds that exceed 3GPP Release 16 baselines. Power amplifier designers must implement digital pre-distortion circuits or sacrifice efficiency margins to maintain linearity compliance. High-power user equipment for fixed wireless access bears the heaviest redesign burden, with OEMs adding 10-15% to amplifier die area.
Consolidated module sourcing is displacing discrete component procurement among mid-tier handset manufacturers seeking to reduce qualification overhead and supply base complexity. Platform vendors now bundle filter-amplifier-switch assemblies with modem software stacks, capturing design-in decisions earlier in product development cycles. This pattern is most pronounced in Chinese and Indian OEM supply chains, where time-to-market compression outweighs marginal cost premiums for integrated solutions.
RF Front End Module Market Segmentation
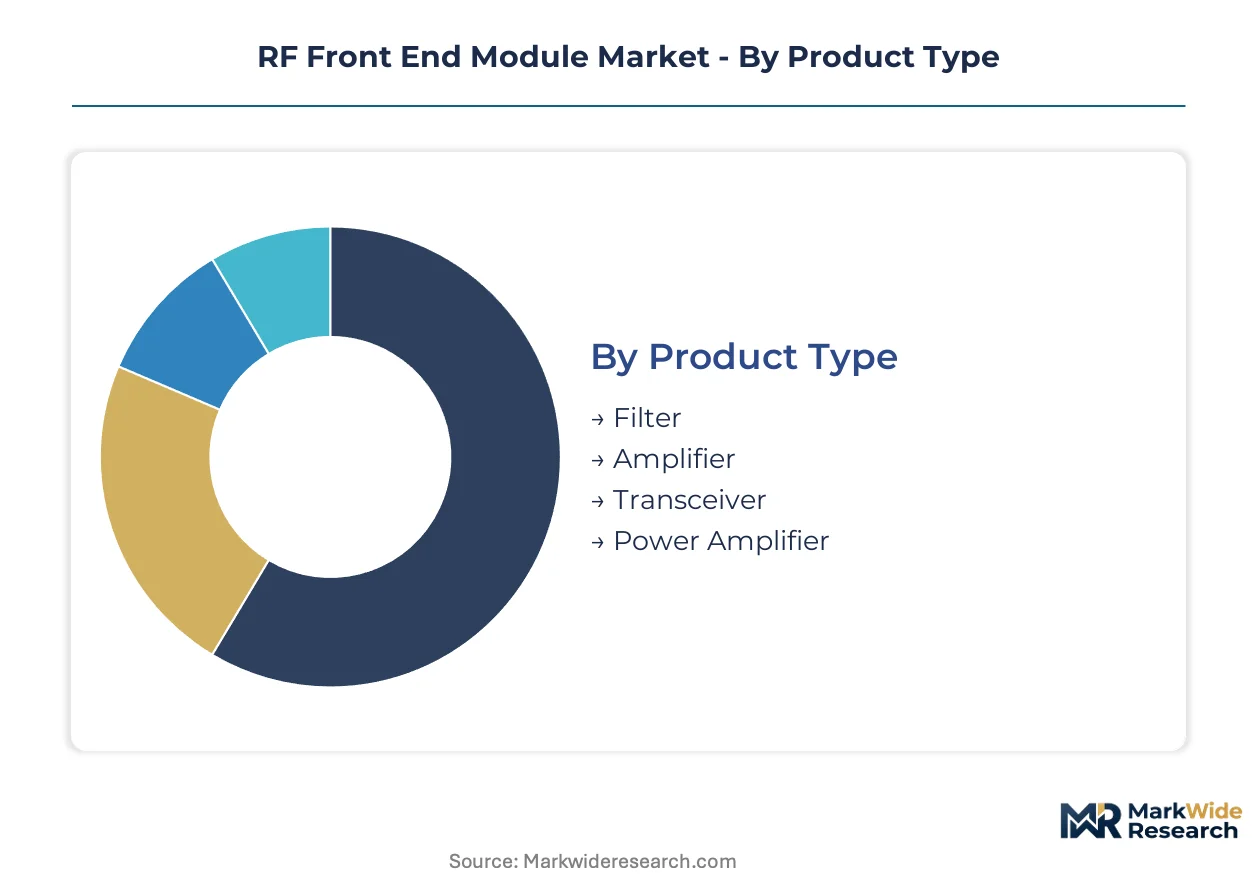
RF front end module procurement splits across four distinct category hierarchies. Product type and technology choices determine thermal budgets and frequency agility, while application and end-user segments dictate certification rigor and volume scale.
Product Type:
Buyers differentiate primarily by margin capture potential and material scarcity exposure in resonator substrates and amplifier die.
- Filter:Bulk acoustic wave and surface acoustic wave constructions dominate sub-6 GHz cellular bands. Demand concentrates in Suwon and Pyeongtaek packaging clusters where Samsung Electronics co-locates design teams with Murata substrate specialists, pulled by South Korea's 28 GHz commercial deployment.
- Power Amplifier:GaN and GaAs die architectures handle 28–39 GHz mmWave with linearity thresholds exceeding 3GPP Release 16 baselines. Defense and base station procurement in the United States absorbs premium thermal management solutions despite 15-20% bill-of-materials overhead from diamond heat spreaders.
- Amplifier:Low-noise amplifiers for 77-81 GHz automotive radar leverage GaAs epitaxy with beamforming switch integration. Tier-one automotive OEMs in Germany specify collision-avoidance modules under KBA frequency allocation rules.
- Transceiver:Modem-to-antenna platform integration bundles RF conversion with digital baseband. Qualcomm captures design-in decisions early through bundled procurement specifications.
Filter leads volumes today; power amplifier is gaining share fastest.
Technology:
Process node selection trades off integration density against frequency performance and thermal headroom.
- GaN:Wide bandgap properties enable 100W+ output power for defense radar and 5G massive MIMO base stations. The FCC's out-of-band emission limits for CBRS operations force digital pre-distortion circuits that expand die area 10-15%.
- GaAs:Established foundry infrastructure supports 77-81 GHz automotive radar with proven reliability metrics. Japanese epitaxy houses face acute technician shortages extending new product introduction cycles.
- CMOS:Silicon integration enables cost-sensitive IoT gateways and mid-tier handsets. Commoditization pressure intensifies as wafer-level chip-scale packaging converges acoustic filters with switches on interposers.
- Hybrid:Multi-process stacking combines GaN power stages with CMOS control logic. Satellite terminal flat-panel arrays for Ka-band beamforming exploit this architecture outside cellular cyclicality.
GaAs commands the largest installed base; GaN shows the steepest expansion trajectory.
Application:
Frequency band authorization and electromagnetic compatibility thresholds segment buyers by regulatory jurisdiction and certification timeline.
- Telecommunication:Sub-6 GHz and mmWave 5G infrastructure drives module volumes into advanced packaging facilities. China's MIIT domestic encryption protocols condition market access for foreign suppliers.
- Automotive:77-81 GHz radar modules for collision avoidance integrate with camera fusion systems. EU's Radio Equipment Directive tightened out-of-band emission limits force redundant filtering stages.
- Satellite Communication:Low-earth orbit broadband constellations require Ka-band beamforming with electronic steering. Flat-panel terminal demand opens volume channels independent of handset replacement cycles.
- Aerospace:Defense platforms specify GaN-based amplifiers with hermetic packaging for radiation tolerance. Extended qualification timelines reflect MIL-STD-883 screening requirements.
Telecommunication absorbs dominant volume; satellite communication is expanding most quickly.
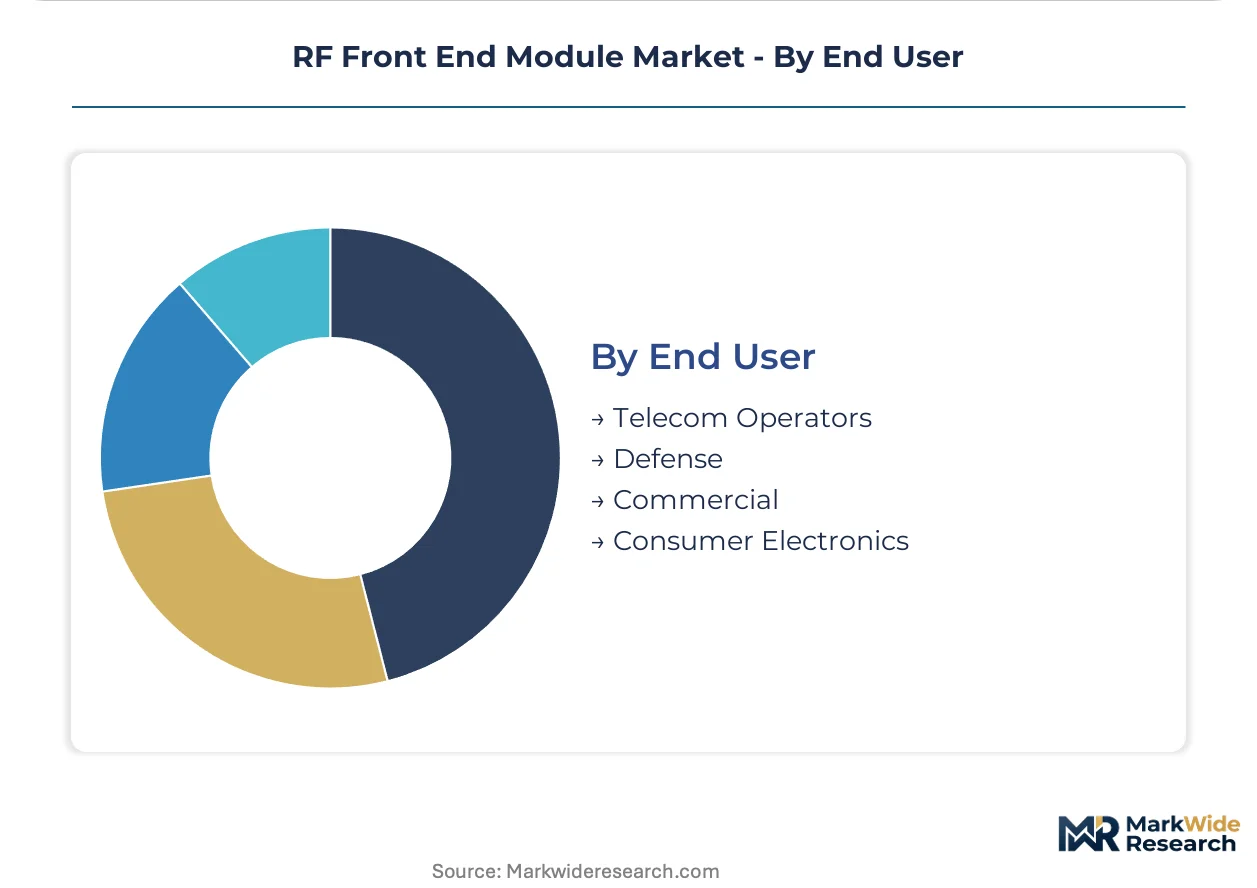
End User:
Procurement consolidation patterns and supply base complexity tolerance distinguish buyer segments.
- Consumer Electronics:Smartphone OEMs consolidate around integrated 5G modules to reduce qualification overhead. Chinese and Indian manufacturers prioritize time-to-market compression over marginal cost premiums.
- Telecom Operators:Base station deployment drives sub-6 GHz front end demand with domestic value-add mandates under India's PLI scheme reducing import duty exposure.
- Defense:GaN amplifier procurement for radar and electronic warfare specifies thermal management solutions with silicon carbide heat spreaders. Extended flip-chip bonder lead times from German and Japanese vendors constrain capacity expansion.
- Commercial:Enterprise fixed wireless access equipment faces the heaviest FCC linearity redesign burden for high-power user equipment in 3.5 GHz and 6 GHz bands.
Consumer electronics leads procurement volumes; telecom operators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between electromagnetic compatibility regimes are redirecting module assembly toward jurisdictions with streamlined certification pathways. South Korea and Japan leverage domestic substrate supply chains to compress qualification timelines, while India's localization mandates reshape import substitution patterns.
United States
Defense procurement of GaN-based radar amplifiers absorbs premium thermal management solutions despite material overhead. The FCC enforces out-of-band emission limits for CBRS and 6 GHz unlicensed bands that exceed 3GPP baselines, forcing digital pre-distortion circuit redesigns. Boston and Austin design clusters concentrate fabless RF firms near DARPA-funded research institutions.
China
Domestic smartphone OEM procurement of integrated 5G modules intensifies around sub-6 GHz architectures. MIIT imposes encryption protocols and frequency authorization rules that condition foreign supplier market access. Shenzhen and Dongguan packaging hubs co-locate filter specialists with system-level integrators serving Huawei and Xiaomi supply chains.
South Korea
Samsung Electronics anchors integrated module demand through co-located design teams in Suwon and Pyeongtaek. The Ministry of Science and ICT released 28 GHz mmWave bands for commercial deployment, pulling volumes into advanced packaging facilities. Domestic BAW substrate specialists concentrate margin pools through allocation-controlled aluminum nitride supply.
Japan
Murata Manufacturing leverages LTCC substrate expertise to anchor filter supply chains for global handset OEMs. METI industrial policy supports compound semiconductor foundry infrastructure amid acute epitaxy technician shortages. Kyoto and Nagoya industrial corridors host acoustic resonator specialists facing extended new product introduction cycles.
Germany
Automotive OEMs specify 77-81 GHz radar modules for collision-avoidance systems under KBA frequency allocation rules. The EU Radio Equipment Directive's tightened electromagnetic compatibility thresholds force redundant filtering stages in module designs. Munich and Stuttgart engineering clusters integrate RF front ends with camera fusion systems for tier-one suppliers.
RF Front End Module Market Key Industry Players
Capacity expansion dominates the current landscape as packaging equipment lead times extend beyond fourteen months. The vendor base stratifies between integrated platform providers and discrete component specialists, with consolidation pressure intensifying at the module level. Three archetypes define competitive positioning: filter-dominant Japanese conglomerates, GaN-specialized defense contractors, and modem-to-antenna platform integrators. M&A activity and strategic foundry partnerships represent the primary competitive moves as firms secure compound semiconductor capacity.
Among Japanese substrate and component fabricators, Murata Manufacturing Co., Ltd. exemplifies the filter-centric archetype through LTCC and acoustic resonator dominance. Qualcomm Technologies, Inc. occupies the platform integration tier, bundling modem software with RF module specifications to capture early design-in decisions. Qorvo, Inc. represents the compound semiconductor specialist position, with corporate naming conventions suggesting GaN and GaAs process heritage. These three anchors illustrate how geographic supply chain concentration and technology specialization stratify competitive positioning across the module value chain.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Infineon Technologies AG |
| Skyworks Solutions, Inc. |
| TDK Corporation |
| NXP Semiconductors N.V. |
| Broadcom Inc. |
| Qualcomm Technologies, Inc. |
| Analog Devices, Inc. |
| Qorvo, Inc. |
| Others |
Cost & Logistics Intelligence
Aluminum nitride substrate allocation constraints cascade through BAW filter pricing tiers, with Japanese and Korean substrate specialists commanding premium positioning for n77 and n79 band modules while CMOS-integrated mid-tier alternatives face commoditization pressure from wafer-level packaging convergence.
Pricing Analysis
Distributor margin compression in the RF front end module market intensifies as smartphone OEMs consolidate procurement around integrated 5G platforms with direct-to-manufacturer volume commitments. Price differentiation separates GaN-based defense and base station amplifiers with diamond heat spreader premiums from standard LDMOS alternatives, while certification-grade modules for FCC CBRS compliance bear 10-15% die area overhead. Pricing pressure stems from flip-chip bonder equipment scarcity extending capacity expansion timelines. Mid-tier Chinese and Indian handset manufacturers exhibit highest price sensitivity, prioritizing time-to-market compression over marginal cost premiums for fully integrated solutions.
Supply Chain Analysis
India's PLI scheme domestic value-add mandates for 5G base stations are reshaping sourcing patterns for sub-6 GHz front end modules, pulling assembly capacity toward localized facilities with reduced import duty exposure. Geographic supply concentration centers on South Korea's Suwon and Pyeongtaek packaging clusters, Japan's Kyoto and Nagoya acoustic resonator corridors, and China's Shenzhen and Dongguan system-level integration hubs. Raw material dependencies encompass aluminum nitride substrates for BAW resonators, GaN epitaxy wafers for power amplifiers, and LTCC ceramic tapes for filter packaging. Single-source vulnerability in German and Japanese flip-chip bonder equipment creates capacity bottlenecks. Distribution runs through tier-one smartphone OEM direct procurement channels and defense contractor long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in RF front end modules rests on thermal management premium capture in GaN defense amplifiers and BAW filter material scarcity premiums, offset by CMOS commoditization pressure in mid-tier handset integration.
For Market Incumbents: Hedge GaAs foundry exposure by securing captive aluminum nitride substrate supply through Japanese and Korean specialist partnerships, while accelerating GaN-on-diamond process qualification for defense radar amplifiers before LDMOS substitution threatens premium positioning. Capacity addition in India's PLI-compliant assembly facilities addresses tariff exposure from import-dependent supply chains. For New Entrants and Emerging Players: Enter via Ka-band beamforming module supply for low-earth orbit satellite terminal flat-panel arrays, exploiting demand channels outside cellular handset cyclicality with hybrid GaN-CMOS architectures. The most penetrable segment sits in automotive radar 77-81 GHz low-noise amplifiers for German tier-one collision-avoidance systems, accessed through KBA-certified design partnerships with camera fusion integrators. For Investors and Strategic Acquirers: Consolidation pressure builds where compound semiconductor process engineering talent scarcity extends new product introduction cycles beyond carrier aggregation certification timelines. Long-term viability favors targets with backward integration into aluminum nitride substrate supply or captive GaN epitaxy capacity. The signal to watch is South Korea's Ministry of Science and ICT mmWave spectrum auction velocity as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| BAW-SMR Technology Transition | Solidly mounted resonator designs displace legacy FBAR architectures in n77 and n79 band sockets. |
| GaN-on-Diamond Process Qualification | Thermal management premiums in defense radar amplifiers justify 15-20% bill-of-materials overhead. |
| India PLI Localization | Domestic value-add mandates reduce import duty exposure for sub-6 GHz base station modules. |
| Wafer-Level Chip-Scale Packaging Convergence | Acoustic filter-CMOS switch integration enables single-source procurement for mid-tier OEMs. |
| Satellite Terminal Ka-Band Beamforming | Flat-panel array demand opens volume channels independent of smartphone replacement cycles. |
Research Approach
Bottom-up smartphone OEM procurement modeling reconciled against top-down compound semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with RF device physicists, epitaxy technicians, packaging equipment specialists, and MIIT regulatory affairs consultants combined with secondary validation from FCC spectrum allocation proceedings, EU Radio Equipment Directive harmonized standards, and South Korean Ministry of Science and ICT deployment disclosures. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of filter and power amplifier shipment patterns informed the projection framework across the analysis window. Segmentation dimensions modeled encompass product type hierarchy, process technology node, frequency band authorization, and end-user procurement consolidation patterns. CAGRs derived from installed base replacement cycles, spectrum reallocation timelines, and packaging equipment lead time constraints. Industry-specific forecast inputs included 5G mmWave commercial deployment velocity and automotive radar frequency expansion under KBA rules.
Inputs from MIIT domestic encryption protocol filings and EU electromagnetic compatibility test house disclosures were available through the study window; gaps in real-time aluminum nitride substrate allocation data introduce uncertainty bands around BAW filter margin projections. Forecasts reflect assumptions regarding South Korean 28 GHz deployment pace and India's PLI scheme localization compliance rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Flat Panel Antenna Market
RF Components
China Small Signal Transistor Market
RF Components
Tunable Capacitors Market
RF Components
Radio Frequency Filters Market
RF Components
GPS Low Noise Amplifier Market
RF Components
RF Interconnect Market
RF Components
RF Filters Market
RF Components
Gaas RF Switch Market
RF Components
Frequency Synthesizer Market
RF Components
Silicon Tuners Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Analog Phase Shifter Market
RF Components
RF Power Detector Market
RF Components
RF Passive Component Market
RF Components
UHF RFID Inlays Market
RF Components
SMD Resonator Market