
 Plastic Lens Market | 2026-2036
Plastic Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Lens Market Analytics
The plastic lens supply base is restructuring around a sharp divergence between premium ophthalmic lenses and commodity molded optics. EssilorLuxottica S.A. dominates the premium ophthalmic tier through its vertically integrated prescription labs and retail networks. Largan Precision Co. Ltd. anchors the high-volume smartphone camera lens segment with precision injection molding at scale. Sunny Optical Technology (Group) Company Limited extends its position across automotive and mobile imaging modules, competing on unit cost and yield optimization.
Plastic lenses are optical components manufactured from thermoset or thermoplastic polymers such as polycarbonate, CR-39, Trivex, or acrylic, typically formed through injection molding, casting, or precision lapping to achieve specified diopter powers, Abbe numbers, and impact resistance ratings for vision correction, protection, or imaging applications. Single vision lenses retain the largest volume share within ophthalmic applications, while progressive lenses capture disproportionate margin pools due to complex freeform surfacing requirements and customization intensity. Photochromic formulations represent the fastest-growing product type as consumers seek dual-function eyewear that adapts to ambient light without auxiliary accessories.
FDA oversight of medical device lenses and CE marking under the EU MDR shape product standards, testing protocols, and market access pathways for ophthalmic devices across North America and Europe. China's NMPA and GB standards govern domestic manufacturing quality and import clearance for optical products distributed within its borders. Stakeholders must monitor evolving regulatory convergence between medical device classifications and consumer product safety regimes, as reclassification risks could redirect capital toward compliance infrastructure or geographic repositioning.
Market Dynamics
Freeform surfacing technology has collapsed the production cost differential between single-vision and progressive lenses, compressing margin pools and forcing manufacturers to differentiate through coating stacks and personalization software rather than base curve complexity.
Growth Catalysts
- EU MDR certification requirements:Stricter CE marking protocols for ophthalmic devices are filtering out marginal suppliers and consolidating volume among accredited labs in Germany and France.
- Photochromic formulation advances:Faster darkening-clearing kinetics in Trivex substrates are capturing commuter demand in sun-intensive latitudes.
- China's aging demographic:Presbyopia prevalence in the 50-plus cohort is sustaining replacement cycle velocity in Shanghai and Guangzhou optical chains.
Market Restraints
- Crude-derived monomer volatility:Polycarbonate resin prices track benzene and propylene feedstock swings, compressing gross margins during petrochemical upcycles.
- Injection molding tool concentration:Precision mold fabrication for freeform progressive geometries concentrates among Japanese and German toolmakers, creating 16-24 week lead time bottlenecks.
- Abbe number limitations:High-index polycarbonate's inherent chromatic aberration restricts adoption in premium dispensing channels where CR-39 and Trivex dominate.
Strategic Opportunities
- India's underpenetrated correction rate:Cataract surgery volume growth and rising disposable income in tier-two cities are opening greenfield dispensing opportunities outside Mumbai and Delhi.
- Blue-light filtering coatings:Screen-time anxiety among remote workers is creating attach-rate expansion for anti-fatigue treatments in prescription and plano categories.
- Direct-to-consumer refraction apps:Smartphone-based prescription validation is compressing the traditional optometrist-dispenser channel in North American and European markets.
Industry Challenges
- Freeform metrology technician scarcity:Operation of precision lapping and power mapping equipment requires 18-24 month training curves that outpace vocational pipeline output.
- ISO 8980-1 testing backlog:Optical power tolerance certification queues at accredited labs are extending new product introduction timelines by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Lens Market |
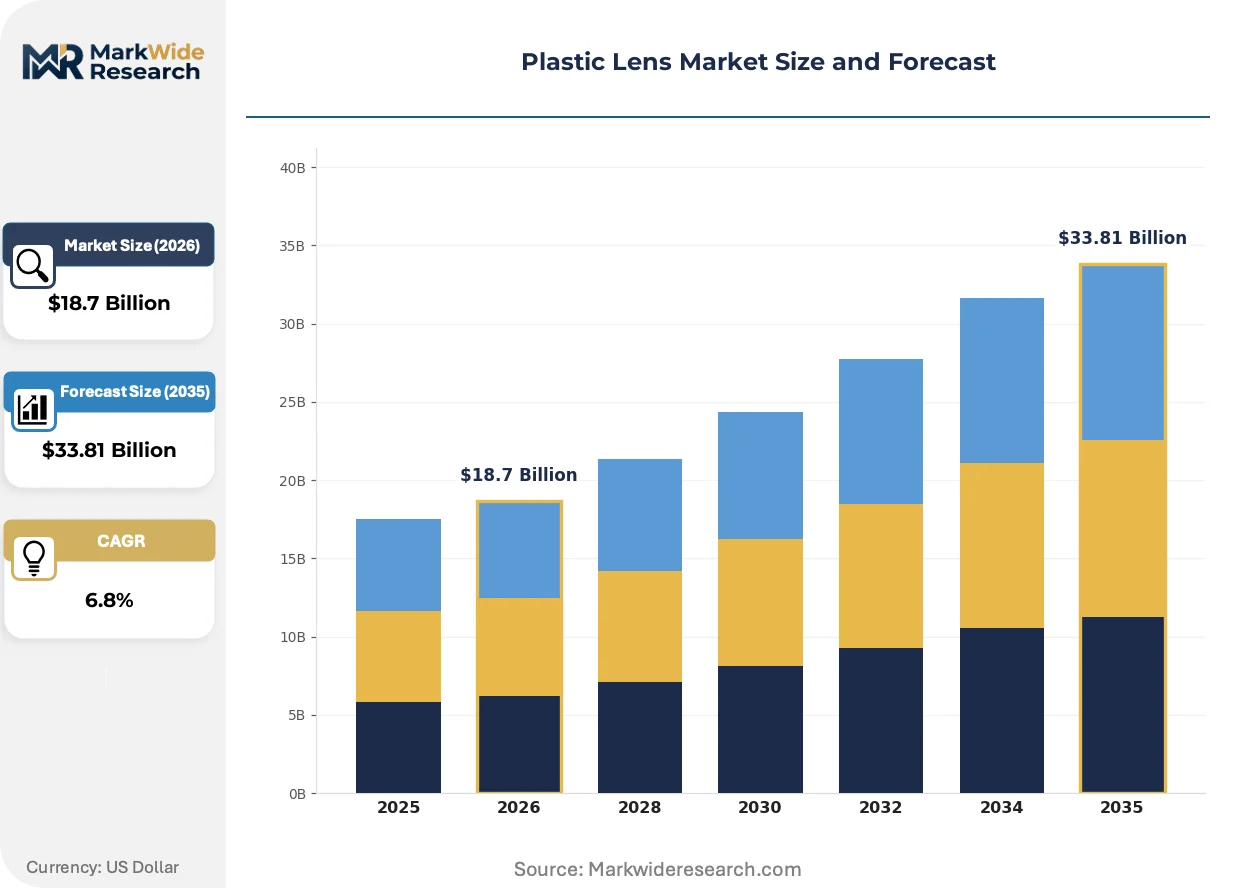
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Photochromic Application: Eyeglasses, Sunglasses, Safety Goggles, Industrial Masks End User: Retail Consumers, Optical Centers, Hospitals, Online Stores Material: Polycarbonate, CR-39, Trivex, Acrylic |
| Companies Covered | EssilorLuxottica S.A., Largan Precision Co. Ltd., Sunny Optical Technology (Group) Company Limited, Carl Zeiss AG, Johnson & Johnson Vision Care Inc., Bausch + Lomb Corporation, Canon Inc., Sekonix Co. Ltd., Kantatsu Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Lens Market Evolving Landscape
Digital surfacing and additive coating deposition are converging to enable mass-customized lens architectures that were economically unfeasible under conventional casting and grinding workflows.
Digital freeform surfacing is expanding into mid-tier prescription labs that previously lacked capital for five-axis diamond turning equipment. Independent optical retailers in South Korea and Italy are adopting these systems to offer progressive lenses with personalized corridor lengths. The technology is expanding into territory once reserved for premium captive labs, compressing the price premium between independent and vertically integrated supply.
REACH Annex XVII restrictions on bisphenol-A in articles intended for prolonged skin contact are pressuring manufacturers to validate alternative hardcoat chemistries for rimless mountings. German and French coating suppliers are accelerating aliphatic urethane formulations to maintain EU market access. The regulation is reshaping R&D allocation toward BPA-free adhesion promoters and UV-curable topcoats.
Subscription lens replacement programs are displacing traditional breakage-driven repurchase cycles in North American vision benefit plans. Employers and payers are bundling annual lens allowances with frame allowances, shifting volume toward planned consumption rather than distress purchases. The model is most developed in California and Texas group vision contracts, where managed care administrators negotiate direct-to-lab fulfillment.
Plastic Lens Market Segmentation
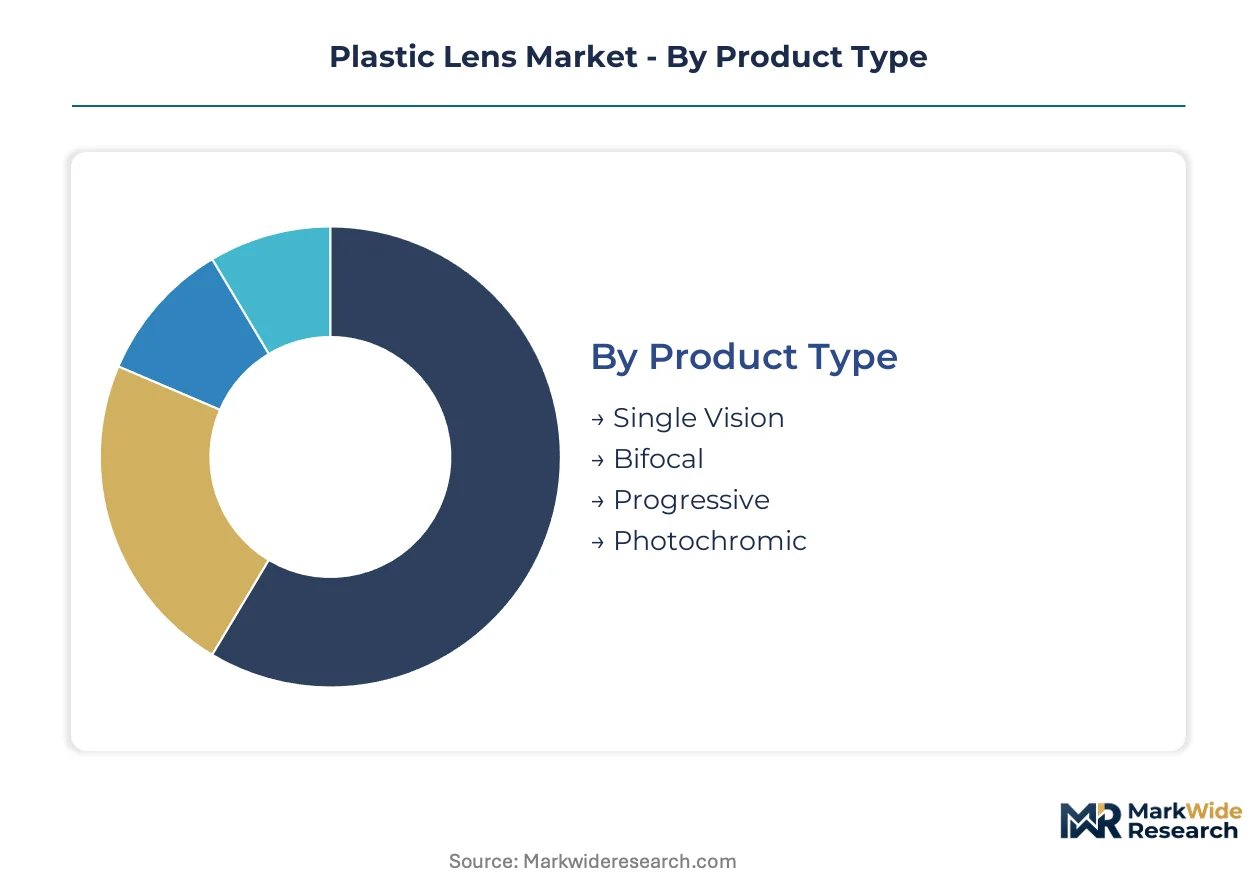
Plastic lens manufacturers calibrate production lines against four intersecting axes: optical function, use environment, procurement channel, and polymer substrate. Each axis carries distinct margin profiles and certification burdens that reshape capital allocation across prescription labs and molded optics foundries.
Product Type:
Optical complexity and surfacing technology define tier boundaries, with freeform diamond-turning capability separating premium progressive production from commodity single-vision molding.
- Single Vision:Uniform diopter power across the entire lens surface, manufactured through precision injection molding or continuous casting. Volume concentrates in China's Wenzhou and Danyang manufacturing clusters where automated edging equipment processes millions of units monthly for domestic optical chains and export markets.
- Progressive:Gradient power zones enabling near-to-distance vision without visible lines, requiring five-axis freeform surfacing and point-by-point power mapping. German and French captive labs retain pricing power through proprietary corridor designs, while South Korean independent labs are compressing premiums through imported digital surfacing systems.
- Bifocal:Two discrete optical zones fused or molded together, now declining in ophthalmic dispensing but persisting in occupational safety applications where cost minimization overrides cosmetic concerns.
- Photochromic:Light-reactive organic dyes embedded in Trivex or polycarbonate substrates, darkening under UV exposure. Faster clearing kinetics in latest-generation formulations are capturing commuter demand across sun-intensive latitudes.
Mature deployment sits with Single Vision. Newer deployment is concentrated in Photochromic.
Application:
End-use environments dictate impact resistance ratings, coating durability specifications, and frame mounting tolerances that cascade back to resin selection and hardcoat chemistry.
- Eyeglasses:Corrective lenses for myopia, hyperopia, and astigmatism, representing the volume anchor across all polymer substrates. Japan's aging demographic sustains replacement velocity in Tokyo and Osaka independent optical retailers, where progressive attach rates exceed regional averages.
- Sunglasses:Plano and prescription tinted lenses for UV protection and glare reduction. Italian frame manufacturers in Belluno province source CR-39 and polycarbonate blanks from captive molding operations, integrating polarization films in-house.
- Safety Goggles:Impact-rated eye protection for construction, manufacturing, and laboratory environments. Polycarbonate dominates due to ANSI Z87.1 and EN 166 certification requirements for high-velocity particle resistance.
- Industrial Masks:Full-face respirator and welding helmet lenses requiring chemical splash resistance and optical clarity under thermal stress. German industrial safety distributors specify aliphatic polyurethane hardcoats to meet REACH Annex XVII compliance.
Volume leadership belongs to Eyeglasses. Margin expansion is steepest in Safety Goggles.
End User:
Channel structure determines prescription validation workflows, customization depth, and inventory positioning between made-to-order surfacing and pre-finished stock lens distribution.
- Retail Consumers:Direct purchasers through brand-owned stores, independent opticians, and big-box optical departments. EssilorLuxottica's vertically integrated retail networks in France and Italy capture recurring replacement cycles through bundled frame-lens subscriptions.
- Optical Centers:Independent and chain-affiliated dispensing locations with in-house edging labs. These operators are consolidating procurement through regional buying groups in Germany's ZVA federation and Japan's JOA cooperatives.
- Hospitals:Ophthalmology departments and ambulatory surgery centers sourcing post-cataract corrective lenses. India's Aravind Eye Care and LV Prasad Eye Institute networks drive volume through high-throughput community outreach models.
- Online Stores:Direct-to-consumer platforms with remote prescription upload and home trial programs. North American venture-backed entrants are compressing traditional optometrist-dispenser channel margins through automated refraction apps and direct lab fulfillment.
Traditional concentration rests with Optical Centers. Channel shift is accelerating fastest through Online Stores.
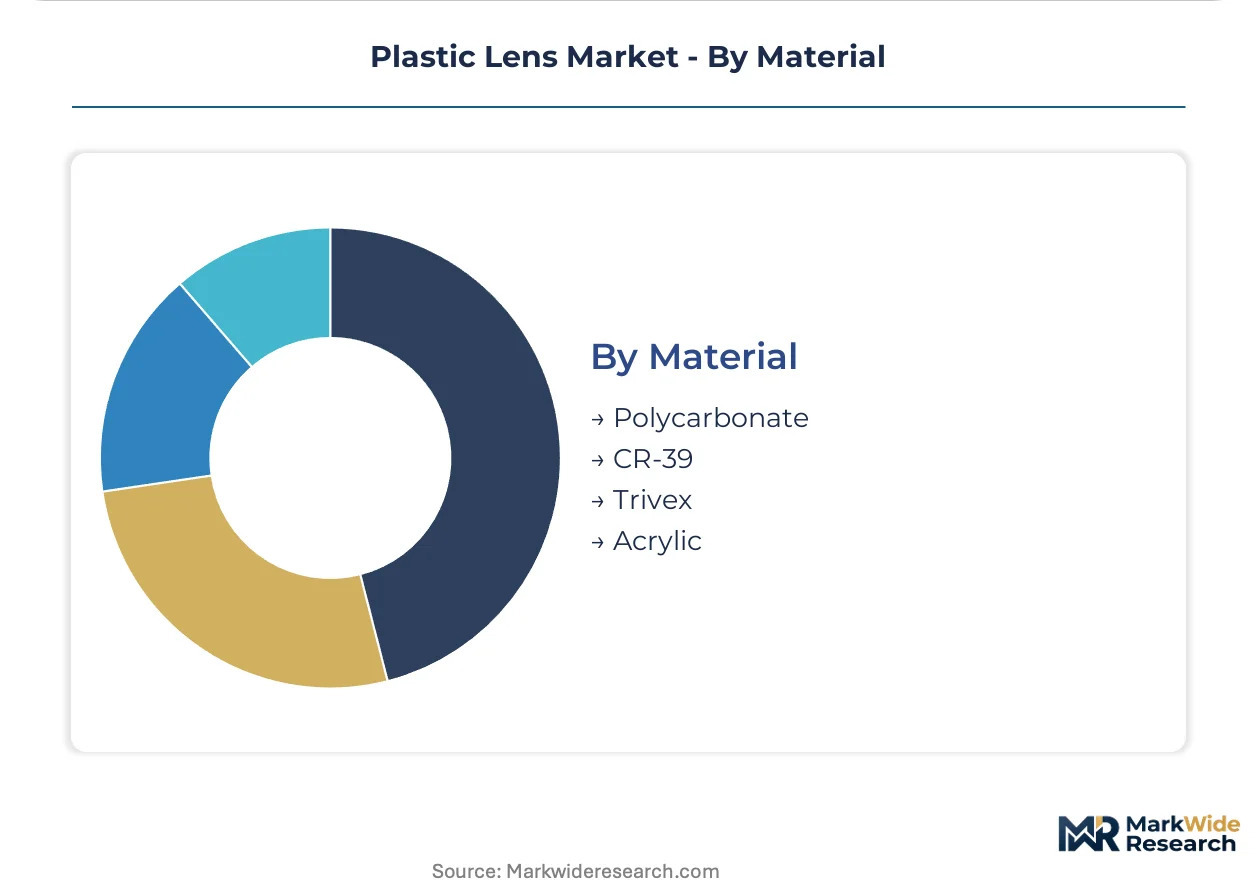
Material:
Polymer selection trades off refractive index, Abbe number, impact resistance, and specific gravity against coating adhesion properties and regulatory compliance burdens.
- Polycarbonate:Thermoplastic with highest impact resistance and lowest density, favored in safety applications and children's eyewear. Benzene and propylene feedstock volatility compresses gross margins during petrochemical upcycles, forcing inventory hedging at major molders.
- CR-39:Allyl diglycol carbonate thermoset with superior optical clarity and Abbe number, dominating premium dispensing channels where chromatic aberration tolerance is minimal. Japanese and Korean independent labs specify CR-39 for high-cylinder prescriptions.
- Trivex:Urethane-based material combining impact resistance near polycarbonate with optical quality approaching CR-39, plus inherent UV absorption. Photochromic formulation advances in Trivex substrates are displacing polycarbonate in mid-tier progressive segments.
- Acrylic:Lower-cost alternative for plano sunglass lenses and disposable magnification products where weight and impact ratings are secondary to price point. Chinese exporters dominate this commodity tier through Danyang molding clusters.
Established volume centers on CR-39. Fastest material transition is occurring in Trivex.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danyang in Jiangsu Province anchors global plastic lens manufacturing through automated molding clusters that process millions of units monthly for optical chains and export markets.
China
Presbyopia prevalence among the 50-plus cohort sustains replacement velocity in Shanghai and Guangzhou optical chains. NMPA and GB standards govern domestic manufacturing quality and import clearance for optical products. Wenzhou and Danyang manufacturing clusters deploy automated edging equipment to serve domestic optical chains and export markets.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria sustain lens consumption through aging demographics and premium dispensing channels. Stricter EU MDR certification protocols for ophthalmic devices filter out marginal suppliers and consolidate volume among accredited labs. ZVA federation members in Munich and Stuttgart coordinate regional procurement through buying groups that standardize coating specifications.
Japan
Tokyo and Osaka independent optical retailers maintain progressive attach rates that exceed regional averages. METI oversight aligns with JIS standards for optical power tolerance and coating durability. Nagoya precision mold fabricators supply 16-24 week lead time tooling for freeform progressive geometries to domestic and export labs.
United States
California and Texas group vision contracts drive subscription lens replacement programs that displace breakage-driven repurchase cycles. FDA oversight of medical device lenses shapes product standards and testing protocols for ophthalmic devices. Remote refraction apps in North American markets compress traditional optometrist-dispenser channel margins through automated prescription validation.
India
Cataract surgery volume growth and rising disposable income in tier-two cities open greenfield dispensing opportunities outside Mumbai and Delhi. The national pharmaceutical regulator maintains quality standards for post-surgical corrective lenses distributed through hospital networks. Aravind Eye Care and LV Prasad Eye Institute networks drive volume through high-throughput community outreach models in Tamil Nadu and Andhra Pradesh.
Plastic Lens Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating complexity and prescription customization depth. The supply base restructures around a sharp divergence between premium ophthalmic lenses and commodity molded optics. Three archetypes dominate: vertically integrated prescription labs with captive retail networks, precision injection molders serving high-volume electronics imaging, and independent optical retailers adopting digital surfacing systems. Competitive moves concentrate on M&A consolidation of regional lab networks and technology licensing for freeform surfacing equipment.
Within the vertically integrated tier, EssilorLuxottica S.A. exemplifies premium ophthalmic positioning through captive prescription labs and retail network control. Among Asia-Pacific precision molders, Largan Precision Co. Ltd. and Sunny Optical Technology (Group) Company Limited occupy positions at the high-volume smartphone camera lens and automotive imaging module segments respectively. These three companies represent the dominant competitive archetypes: prescription lab integration, electronics imaging scale, and diversified imaging module cost optimization.
| Leading Market Players |
|---|
| EssilorLuxottica S.A. |
| Largan Precision Co. Ltd. |
| Sunny Optical Technology (Group) Company Limited |
| Carl Zeiss AG |
| Johnson & Johnson Vision Care Inc. |
| Bausch + Lomb Corporation |
| Canon Inc. |
| Sekonix Co. Ltd. |
| Kantatsu Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Japan and Germany anchor premium progressive lens manufacturing, their multi-generational capital structures enabling patient investment in freeform surfacing equipment that commodity molders in China cannot replicate. This ownership pattern sustains pricing discipline through 16-24 week tooling lead times and proprietary corridor designs that independent labs license at premium rates.
Pricing Analysis
Outcome-based pricing tied to prescription accuracy and visual comfort anchors premium tier positioning. Three-tier pricing structure across premium, standard, and economy levels separates EssilorLuxottica's captive lab networks from South Korean independent operators and Chinese export molders. Cost compression in mid-tier progressives is intensifying because digital surfacing equipment imports erode German and French labs' historical technology premiums. Price-sensitive volume buyers in India's tier-two cities prioritize unit economics over customization depth, while Japanese independent optical retailers exhibit lowest sensitivity due to progressive attach rate premiums.
Supply Chain Analysis
Returns and refurbishment flows for prescription lens edging equipment create secondary market liquidity that extends asset life cycles in India's emerging optical chains. Raw material dependencies draw from benzene and propylene feedstocks for polycarbonate resin, allyl diglycol carbonate monomers for CR-39, and aliphatic urethane precursors for REACH-compliant hardcoats. Supply chain risk centers on Japanese and German precision mold fabrication concentration for freeform progressive geometries. Distribution runs through EssilorLuxottica's vertically integrated retail networks, Germany's ZVA buying group federation, and direct-to-lab fulfillment platforms in North American vision benefit plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeform surfacing technology is displacing conventional casting and grinding workflows, compressing the production cost differential between single-vision and progressive lenses and forcing legacy equipment-dependent labs into rapid capital refresh cycles.
For Market Incumbents: Deepen backward integration into captive mold fabrication to escape 16-24 week lead time bottlenecks at Japanese and German toolmakers. EssilorLuxottica's retail network control and proprietary corridor designs defend against South Korean independent labs' digital surfacing equipment imports. Certification investment in EU MDR-accredited facilities filters marginal competitors and consolidates volume among accredited labs in Baden-Württemberg and Bavaria. For New Entrants and Emerging Players: Tier-two Indian cities beyond Mumbai and Delhi present the most penetrable buyer archetype for greenfield dispensing opportunities. Cataract surgery volume growth and rising disposable income in these markets create white-space targets unclaimed by established optical chains. Remote refraction apps paired with direct-to-lab fulfillment offer a go-to-market angle that compresses traditional optometrist-dispenser channel margins. For Investors and Strategic Acquirers: Accelerating adoption of photochromic Trivex formulations in sun-intensive latitudes is the leading indicator that material substitution trends favor optical quality over pure impact resistance. The 5-10 year viability window favors acquisition targets with installed freeform surfacing capacity and BPA-free hardcoat chemistry validation. Monitor REACH Annex XVII enforcement actions against bisphenol-A in prolonged skin contact articles for early signals of regulatory-driven R&D reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Freeform Surfacing Equipment Acquisition | South Korean labs compress German premium pricing through imported five-axis diamond turning systems. |
| BPA-Free Hardcoat Chemistry Validation | Aliphatic urethane formulations from French and German suppliers secure EU market access under REACH Annex XVII. |
| Subscription Lens Replacement Program Launch | California and Texas group vision contracts displace breakage-driven repurchase cycles through planned consumption. |
| Precision Mold Fabrication Partnership | Nagoya toolmakers supply 16-24 week lead time tooling for progressive geometries to domestic and export labs. |
| Direct-to-Consumer Refraction App Development | Automated prescription validation in North American markets compresses traditional optometrist-dispenser channel margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with prescription lab operations directors, optical chain procurement managers, ophthalmic device regulatory affairs leads, and freeform surfacing equipment distributors combined with FDA 510(k) filings, EU MDR notified body records, NMPA registration databases, and ZVA federation purchasing reports. Bottom-up unit volume modeling and top-down value chain triangulation validated segment-level estimates.
Data-stream reconciliation across polymer substrate consumption, surfacing equipment shipments, and retail dispensing volumes shaped the analytical framework. Segmentation dimensions modeled include optical function tier, polymer material type, procurement channel structure, and regional regulatory cluster. CAGRs derived from fitted trend analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated presbyopia prevalence demographics, photochromic formulation adoption curves, and digital surfacing equipment penetration rates.
Revisions become necessary when EU MDR reclassification actions, feedstock price volatility spikes, or freeform metrology technician pipeline constraints materialize beyond baseline assumptions. Practitioners should monitor REACH Annex XVII enforcement patterns, benzene-propylene spread movements, and vocational training program output for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Global Nanophotonics Market
Optics
Optical Wavelength Service Market
Optics
Optical Receivers Market
Optics
Interchangeable Lens Market
Optics
Optical Liquid Level Sensor Market
Optics
Optical Lens for Mobile Phone Market
Optics
US Photonics Market
Optics
Electro Optics Market
Optics
Fiber Optic Switch Market
Optics
Camera Module Lens Market
Optics
India Laser Market
Optics
Europe Laser Interferometer Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Beam Combining Optics Market
Optics
Optical Sensing Market
Optics
Optical Measuring Systems Market