
 Excimer Lasers for DUV Lithography Market | 2026-2036
Excimer Lasers for DUV Lithography Market Size, Share, and Industry Trends Forecast 2026-2036
Excimer Lasers for DUV Lithography Market Insights
Advanced logic foundry demand is consolidating share from memory-centric procurement as leading-edge node transitions below 3nm require higher-resolution ArF immersion layers. Coherent Corp. leverages captive optical component supply to tighten beam delivery integration. Gigaphoton sustains intense R&D spending on high-repetition-rate discharge chambers. TRUMPF anchors European service infrastructure for laser gas recycling and refurbishment cycles.
Excimer lasers for DUV lithography generate deep ultraviolet light through noble-halide gas mixtures excited by electrical discharge, typically producing 193 nm (ArF) or 248 nm (KrF) wavelengths with pulse energies critical for sub-100 nm feature resolution. These systems enable photolithographic patterning of semiconductor wafers at nodes where optical proximity correction and multiple patterning extend 193 nm immersion technology. ArF laser sources command the dominant installed base among product types, while KrF equipment retains substantial volume in mature node and power semiconductor fabrication where cost-per-layer economics favor established wavelengths. Foundry end users represent the most concentrated demand pool, with integrated device manufacturers pursuing selective upgrades for automotive and analog process lines.
Japan's METI enforces stringent efficiency benchmarks on industrial laser systems, while the EU F-Gas Regulation constrains fluorinated gas supply chains that feed excimer laser gas mixtures. The US EPA and FDA jointly influence export-controlled manufacturing equipment standards through dual-use technology classifications. Stakeholders must monitor regulatory divergence on fluorinated gas phase-down timelines against foundry capacity build-out schedules.
Market Dynamics
Node migration below 3nm at TSMC and Samsung Foundry is compressing ArF immersion layer requirements while EU F-Gas Regulation tightens fluorinated gas supply chains, creating a structural squeeze between resolution demands and chemistry constraints.
Growth Catalysts
- Logic foundry expansion:Leading-edge node transitions at Taiwan Semiconductor Manufacturing Company and Samsung Electronics are multiplying ArF immersion exposure layers per wafer.
- Japan METI efficiency mandates:Energy consumption benchmarks for industrial laser systems are accelerating discharge chamber redesigns toward higher repetition rates.
- 193 nm wavelength dominance:Optical proximity correction and multiple patterning extensions sustain ArF laser relevance where shorter wavelengths remain economically prohibitive.
Market Restraints
- Fluorinated gas supply concentration:EU F-Gas Regulation phase-down timelines constrain noble-halide mixture availability for laser gas replenishment cycles.
- Discharge chamber degradation:Electrode erosion and gas contamination in high-repetition-rate systems compress mean time between overhauls.
- EUV lithography substitution:ASML's extreme ultraviolet systems displace ArF immersion for critical layers at 5nm and below, capping long-term DUV expansion.
Strategic Opportunities
- Power semiconductor fabrication:Silicon carbide and gallium nitride device manufacturing at mature nodes retains substantial KrF laser demand for cost-per-layer economics.
- Laser gas recycling infrastructure:Closed-loop fluorinated gas recovery systems align with EU circular economy frameworks while reducing operational expenditure.
- Automotive analog process lines:Integrated device manufacturers are selectively upgrading 200mm facilities for microcontroller and sensor production.
Industry Challenges
- Optical component integration complexity:Beam delivery system alignment tolerances tighten as numerical aperture increases in immersion lithography.
- Specialized field service engineer scarcity:Deep ultraviolet laser maintenance requires expertise spanning gas chemistry, high-voltage discharge physics, and precision optics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excimer Lasers for DUV Lithography Market |
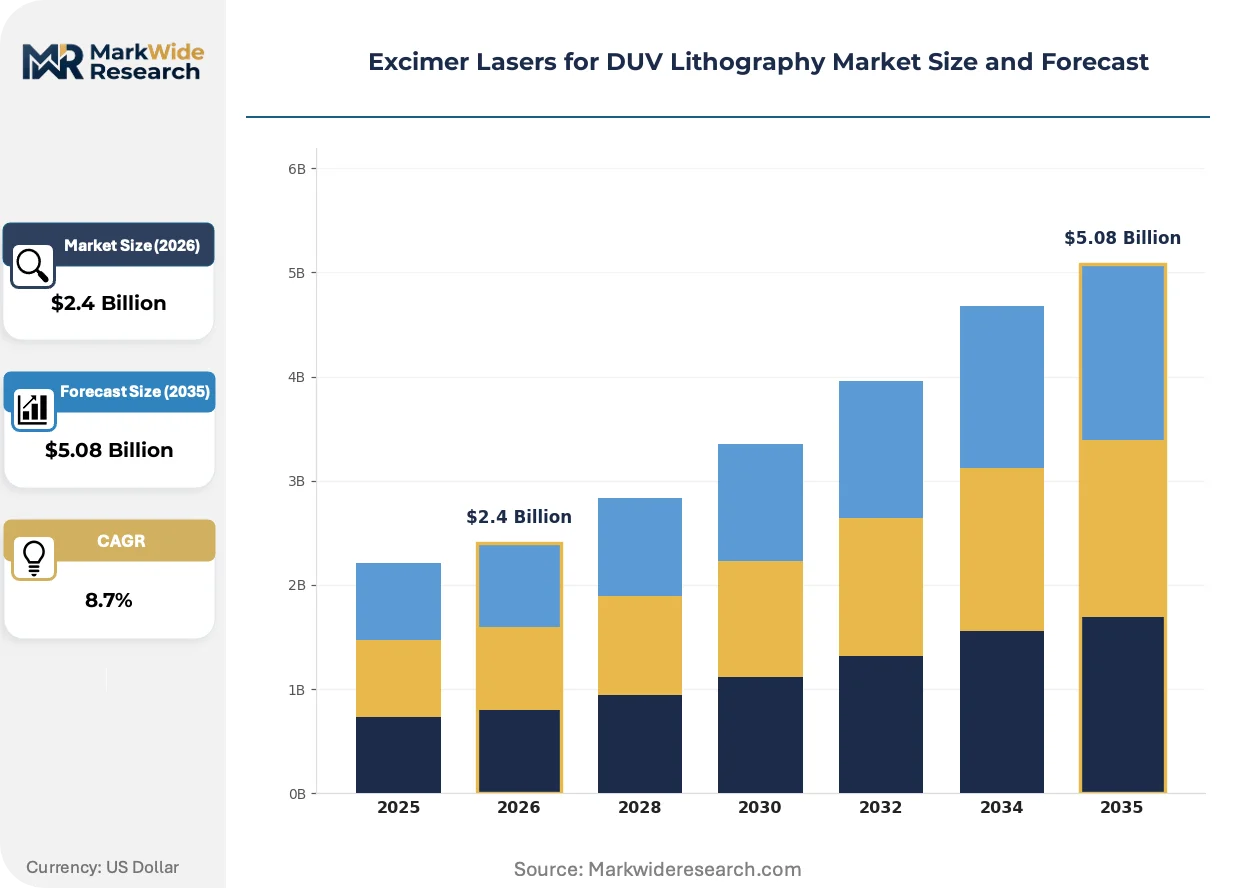
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: KrF, ArF, F2, Mixtures Application: Semiconductor Fabrication, Mask Etching, Wafer Inspection, Lithography Process End User: Foundries, Integrated Device Manufacturers, Research Institutions, Equipment Manufacturers Technology: Laser Source, Optical Components, Timing Control, Beam Delivery Systems |
| Companies Covered | IPG Photonics Corporation, Jenoptik AG, TRUMPF, MKS Instruments, Inc., Novanta, Inc., Gigaphoton, Lumentum Holdings Inc., Keyence Corporation, Coherent Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excimer Lasers for DUV Lithography Market Trends and Innovations
Discharge chamber architectures and regulatory chemistry frameworks are converging to reshape how ArF and KrF laser systems deliver pulse energy stability for sub-100 nm patterning.
Advanced ceramic electrode materials are automating chamber lifetime extension in high-duty-cycle ArF lasers. Foundry customers at TSMC and Samsung are deploying these systems for 24/7 production schedules. This automation is compressing preventive maintenance windows while sustaining pulse-to-pulse energy stability below 0.4% variation.
EU F-Gas Regulation phase-down schedules are forcing reformulation of argon-fluorine gas mixtures toward lower global warming potential alternatives. Laser OEMs are qualifying new halide chemistries that maintain 193 nm output power under stricter emission quotas. East Asian semiconductor clusters in Taiwan and South Korea are stockpiling legacy gas formulations while awaiting certified replacement supply chains.
After-sales service unbundling is fragmenting how foundries contract for laser uptime guarantees. Tier-one logic manufacturers are separating parts procurement from field service labor, driving third-party maintenance provider entry. This pattern is most pronounced in Taiwan's Science Park ecosystem where independent service technicians now handle electrode replacement and gas refills.
Excimer Lasers for DUV Lithography Market Segmentation
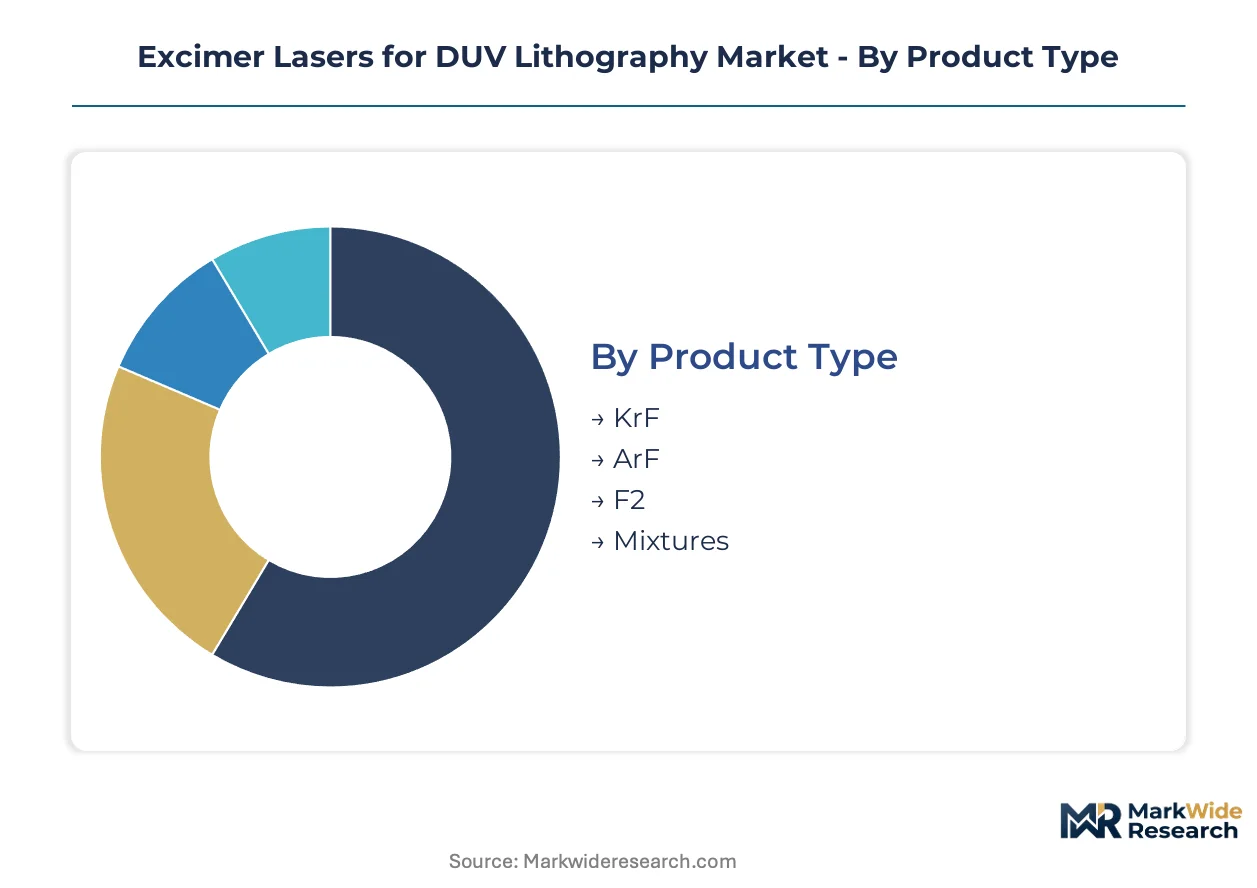
Segmentation in the excimer laser market tracks how wavelength specificity, application layer complexity, and customer procurement models determine upgrade cycles and replacement timing. Foundry capital expenditure patterns and regulatory chemistry constraints further fragment purchasing behavior across these dimensions.
Product Type:
Replacement cycles differ sharply by wavelength maturity, with newer ArF systems commanding shorter depreciation schedules than established KrF platforms.
- ArF:These 193 nm systems dominate leading-edge logic fabrication through immersion lithography extensions. TSMC and Samsung Foundry in Taiwan and South Korea are multiplying ArF exposure layers per wafer as node transitions compress below 3nm, stretching discharge chamber duty cycles and accelerating overhaul demand.
- KrF:Operating at 248 nm, these lasers retain substantial installed base in mature node production where cost-per-layer economics resist wavelength migration. Power semiconductor fabrication for silicon carbide devices in Japan and automotive microcontroller lines in Germany sustain KrF procurement despite slower technical refresh rates.
- F2:These 157 nm systems occupy niche research applications where extreme ultraviolet alternatives remain economically prohibitive.
- Mixtures:Custom noble-halide blends serve specialized mask etching and inspection equipment requiring non-standard spectral outputs.
Volume placements concentrate in ArF; the faster expansion belongs to KrF as mature node capacity resurges for automotive and power electronics.
Application:
Application segmentation reveals how process layer criticality determines laser specification tolerance and service contract structures.
- Semiconductor Fabrication:Front-end patterning of logic and memory devices consumes the dominant share of high-repetition-rate ArF capacity. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster anchor this demand through 24/7 production schedules.
- Mask Etching:Photomask manufacturing requires exceptional pulse energy stability for sub-resolution assist feature definition. Japan's METI efficiency mandates are compressing power consumption benchmarks for these systems.
- Wafer Inspection:Metrology applications leverage KrF and ArF sources for defect detection at nodes where electron-beam alternatives introduce throughput bottlenecks.
- Lithography Process:Process development and yield engineering consume mixed-wavelength capacity across research consortia and pilot lines.
Revenue gravity centers on semiconductor fabrication; mask etching is climbing the fastest as multi-patterning complexity multiplies photomask layer counts.
End User:
Customer type segmentation exposes divergent procurement models between centralized foundry purchasing and fragmented IDM upgrade decisions.
- Foundries:Taiwan Semiconductor Manufacturing Company and Samsung Electronics consolidate the largest procurement volumes through multi-system fleet purchases with uptime guarantee contracts. These customers unbundle after-sales service, driving third-party maintenance entry in Taiwan's Science Park ecosystem.
- Integrated Device Manufacturers:Analog and automotive specialists in Germany and Japan pursue selective KrF upgrades for 200mm facility modernization. Their procurement fragments across smaller batch orders with extended payment terms.
- Research Institutions:University consortia and national laboratories acquire F2 and mixture systems for exploratory patterning research.
- Equipment Manufacturers:Lithography tool OEMs source laser modules as subsystems for integrated scanner platforms.
Procurement volume concentrates in foundries; integrated device manufacturers are gaining share fastest as automotive semiconductor reshoring accelerates.
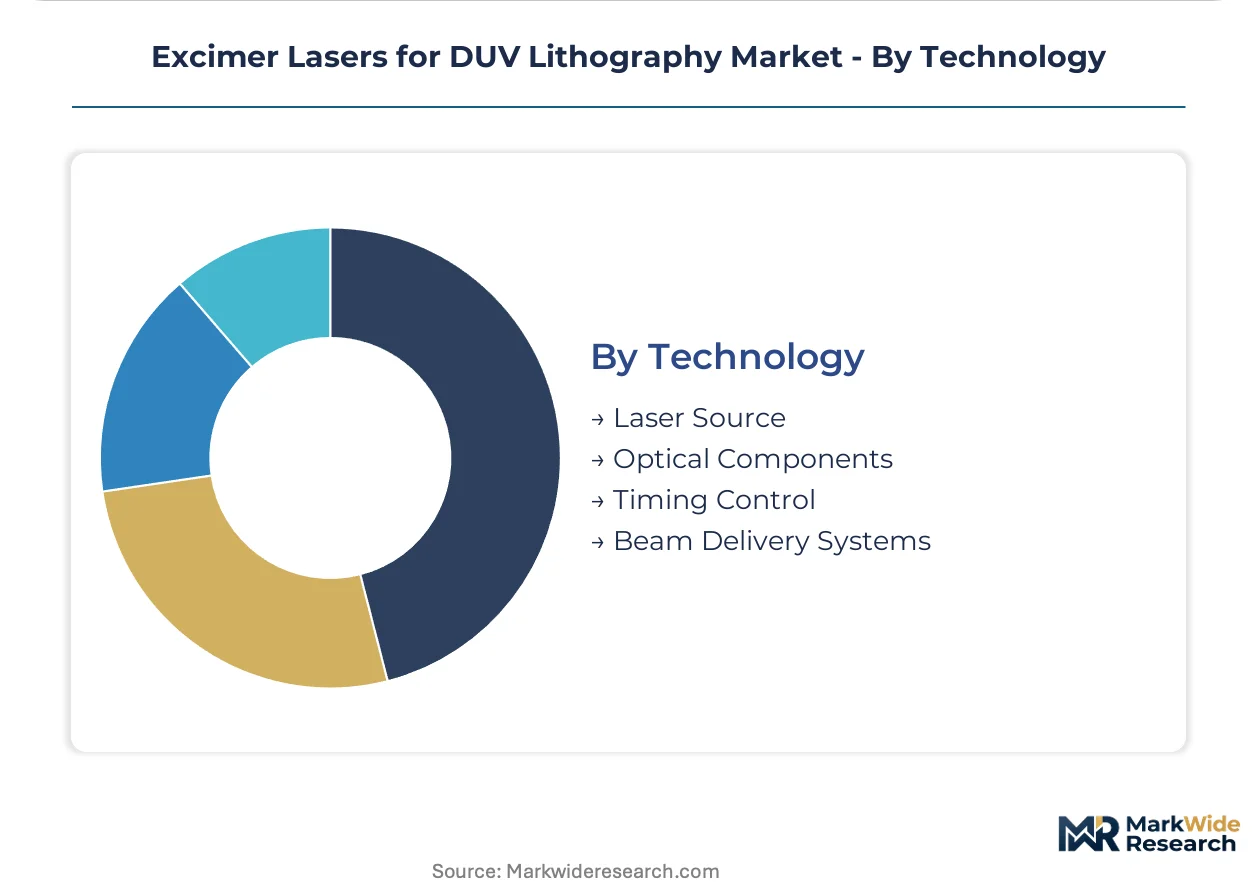
Technology:
Technology segmentation tracks how subsystem specialization determines supplier margins and captive integration strategies.
- Laser Source:Discharge chamber and gas handling systems constitute the core intellectual property for Coherent Corp. and Gigaphoton. Japan METI energy-efficiency mandates are forcing redesigns toward higher repetition rates with compressed electrode erosion tolerances.
- Optical Components:Beam delivery optics and line-narrowing modules represent the vertical integration frontier. Coherent leverages captive optical supply to tighten system integration.
- Timing Control:Pulse synchronization electronics enable overlay accuracy for multiple patterning sequences.
- Beam Delivery Systems:Illumination uniformity components face tightening alignment tolerances as numerical aperture increases in immersion lithography.
Value capture concentrates in laser source technology; beam delivery systems are expanding most quickly as numerical aperture scaling intensifies integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park tax incentives and Kaohsiung's Nanzi Export Processing Zone drive Taiwanese semiconductor equipment concentration. South Korea's Yongin and Pyeongtaek clusters anchor memory and logic foundry demand. German automotive semiconductor corridors sustain mature-node laser procurement.
Taiwan
TSMC's 3nm expansion at Tainan Science Park multiplies ArF immersion layer requirements per wafer. The National Development Council's Statute for Industrial Innovation extends R&D tax credits through 2029. Hsinchu Science Park hosts the densest excimer laser service technician pool outside Japan.
South Korea
Samsung Foundry's Pyeongtaek Giga Fab and SK Hynix's Yongin campus compress discharge chamber replacement cycles. The Ministry of Trade, Industry and Energy's K-Chips Act subsidizes domestic lithography equipment procurement. Seongnam's Pangyo Techno Valley clusters third-party laser maintenance providers.
Japan
Gigaphoton's Tochigi manufacturing base and domestic foundry demand sustain KrF laser refurbishment markets. METI's Top Runner Program mandates industrial laser energy efficiency improvements of 15% by 2030. Yokohama's Kanagawa Science Park concentrates mask etching equipment procurement.
Germany
Infineon's Dresden fab and Bosch's automotive microcontroller lines stabilize KrF demand for 200mm analog processes. The EU F-Gas Regulation's 2030 phase-down targets constrain fluorinated gas supply chains. Saxony's Silicon Saxony cluster coordinates laser gas recycling infrastructure development.
United States
Intel's Arizona and Ohio fab investments drive selective ArF capacity additions for domestic logic production. The EPA's Significant New Alternatives Policy program reviews fluorinated gas substitutes for semiconductor manufacturing. Oregon's Silicon Forest hosts Applied Materials' process development centers utilizing DUV lithography.
Excimer Lasers for DUV Lithography Market Competitive Landscape
Top-tier vendors anchor discharge chamber and gas handling intellectual property, while mid-tier specialists concentrate on beam delivery subsystems and aftermarket service contracts. The vendor structure consolidates around three strategic archetypes: integrated laser source manufacturers, captive optical component suppliers, and independent field service providers. Competitive positioning depends on backward integration into optical supply chains and geographic proximity to East Asian foundry clusters.
Within the integrated source tier, Gigaphoton and Coherent Corp. exemplify full-system manufacturers with captive discharge chamber technology. TRUMPF anchors European service infrastructure for gas recycling and refurbishment cycles. These three companies represent distinct geographic anchoring strategies—Japanese, American, and German respectively—while occupying comparable positions in the laser source archetype.
| Leading Market Players |
|---|
| IPG Photonics Corporation |
| Jenoptik AG |
| TRUMPF |
| MKS Instruments, Inc. |
| Novanta, Inc. |
| Gigaphoton |
| Lumentum Holdings Inc. |
| Keyence Corporation |
| Coherent Corp. |
| Others |
Pricing and Supply Chain Analysis
Leading-edge logic foundries in Taiwan and South Korea operate on long-term fleet procurement contracts with uptime guarantee pricing, compressing spot-market liquidity and anchoring contract-based long-term offtake as the dominant pricing model.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with foundries paying premiums for sub-48-hour gas replenishment cycles during chamber overhaul windows. Price differentiation hinges on after-sales service bundling and discharge chamber duty-cycle certification grades. Cost compression in KrF refurbishment lines is intensifying because IDM customers in Germany and Japan negotiate extended payment terms. Memory-centric buyers exhibit highest price sensitivity; logic foundries with 24/7 production schedules show lowest sensitivity due to downtime cost exposure.
Supply Chain Analysis
Single-source vulnerability sits with fluorinated gas purification infrastructure concentrated in Germany and Japan. Discharge chamber ceramic electrode supply draws from Japanese materials specialists and German precision ceramics manufacturers. Supply chain risk centers on EU F-Gas Regulation phase-down timelines constraining noble-halide mixture availability. Distribution runs through lithography tool OEMs for integrated scanner platforms and direct OEM relationships for replacement source modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorinated gas supply constraints under EU regulatory phase-down schedules prop pricing power for qualified chemistry suppliers, sustaining incumbent margins despite EUV displacement pressure at leading-edge nodes.
For Market Incumbents: Cement captive optical component supply chains to tighten beam delivery integration against third-party subsystem entrants. Prioritize discharge chamber automation R&D to compress preventive maintenance windows for TSMC and Samsung Foundry customers. Defend against EUV lithography substitution by extending ArF immersion relevance through multiple patterning layer multiplication below 3nm. For New Entrants and Emerging Players: Digital-channel aftermarket service platforms offer the most penetrable entry vector, unbundling parts procurement from field service labor for Taiwan Science Park foundries. Target laser gas recycling infrastructure build-out in Germany's Silicon Saxony cluster, where EU circular economy frameworks subsidize closed-loop fluorinated gas recovery. Pursue joint development agreements with automotive IDMs modernizing 200mm KrF lines for silicon carbide power devices. For Investors and Strategic Acquirers: The window for entry favors beam delivery subsystem specialists with numerical aperture scaling expertise. Long-term viability hinges on positioning for mature-node DUV persistence as EUV captures critical layers at 5nm and below. Watch ASML's DUV-EUV layer split announcements at TSMC and Samsung node roadmaps as the primary inflection signal for ArF immersion demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Coherent Corp. tightens beam delivery system alignment tolerances through in-house line-narrowing module production. |
| Laser Gas Recycling Infrastructure Deployment | TRUMPF anchors European service networks compliant with EU F-Gas Regulation circular economy frameworks. |
| High-Repetition-Rate Chamber Redesign | Gigaphoton accelerates discharge chamber duty cycles to meet Japan METI efficiency mandates for industrial lasers. |
| Third-Party Maintenance Provider Entry | Independent technicians in Taiwan's Science Park ecosystem unbundle foundry service contracts from OEM parts procurement. |
| Automotive IDM 200mm Facility Modernization | Infineon and Bosch sustain KrF laser demand through selective upgrades for microcontroller and sensor production lines. |
Research Methodology
Multi-period observation of foundry capital expenditure cycles, discharge chamber replacement rates, and fluorinated gas inventory levels anchored the trend analysis, supplemented by interviews with lithography tool OEM procurement directors, excimer laser field service engineers, semiconductor fab operations managers, and EU regulatory affairs specialists. Secondary validation drew from SEC equipment manufacturer filings, Japan METI industrial efficiency reports, EU ECHA regulatory impact assessments, and Taiwan National Development Council science park investment disclosures. Bottom-up triangulation across replacement part shipment data and top-down reconciliation against foundry capacity build-out announcements ensured cross-verification.
Input-output matrices modeled excimer laser source demand as a function of ArF immersion layer counts per wafer, EUV penetration rates by node, and regulatory chemistry constraints across the analysis window. Segmentation dimensions included wavelength specificity, application layer criticality, end-user procurement model, and technology subsystem specialization. CAGRs were derived through exponential smoothing of annual replacement cycle frequencies against foundry depreciation schedules. Forecast inputs incorporated EU F-Gas Regulation phase-down compliance timelines and Japan METI Top Runner Program efficiency benchmark trajectories.
The model holds under stable EUV displacement timelines and fluorinated gas supply continuity; deviation in regulatory phase-down acceleration or faster-than-expected EUV layer substitution would shift replacement demand trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Laser Transmitter Market
Optics
Optical Sensing Market
Optics
Optical Lens for Mobile Phone Market
Optics
Smart Glass Market
Optics
Optical Microscope Market
Optics
Fiber Optic Connectivity Market
Optics
US Photonics Market
Optics
Optical Telephoto Lens Market
Optics
Plastic Lens Market
Optics
Smart Photochromic Lenses Market
Optics
Germanium Lens Market
Optics
Global Fiber Optic Components Market
Optics
Digital Holographic Microscopy Market
Optics
Global Enhanced Vision System Market
Optics
India Laser Market
Optics
APAC Smart Glass Market