
 CMOS Smartphone Camera Lens Market | 2026-2036
CMOS Smartphone Camera Lens Market Size, Share, and Industry Trends Forecast 2026-2036
CMOS Smartphone Camera Lens Market Insights
Glass-polymer hybrid elements is pivoting away from all-plastic designs as flagship modules demand higher thermal stability and light transmission. Sunny Optical Technology leverages wafer-level optics manufacturing to sustain cost leadership in high-volume 7P and 8P lens stacks. Largan Precision anchors the premium tier through specialized aspherical grinding capabilities that supply Apple and Samsung flagship programs. Samsung Electro-Mechanics competes by integrating camera modules with its own actuator and filter divisions, tightening control over bill-of-materials complexity.
A CMOS smartphone camera lens is a precision-molded optical element or assembly that focuses incident light onto a complementary metal-oxide semiconductor image sensor, typically specified by effective focal length, f-number, and modulation transfer function performance at specified line pairs per millimeter. These lenses enable computational photography pipelines, depth sensing, and high-resolution video capture in handheld devices with severe thickness and thermal constraints. Wide angle and telephoto configurations dominate current shipment volumes, though macro lenses occupy a profitable niche serving content creators and specialized imaging applications. Optical image stabilization technology leads technology segment margins due to voice-coil motor complexity and yield sensitivity, while dual-camera architectures mature as baseline specifications across mid-tier smartphones.
China's SAMR enforces GB standards covering optical performance and environmental compliance for domestically sold lens assemblies, while the EU REACH regulation restricts phthalate plasticizers and heavy metals in coating chemistries used by European-bound products. Japan's METI coordinates JIS standards that influence autofocus motor interoperability and reliability testing protocols across East Asian supply chains. Stakeholders must monitor how divergent substance restrictions and performance certification requirements fragment qualification timelines for multinational smartphone programs.
Market Dynamics
Multi-lens array proliferation in flagship smartphones is compressing design cycles and forcing lens suppliers to synchronize development roadmaps with sensor and algorithm release schedules. This coordination burden now dominates supplier-customer relationships.
Growth Catalysts
- Computational photography pipelines:Depth sensing and night-mode algorithms require specialized lens-sensor calibration, pulling demand for high-precision 7P and 8P stacks.
- EU RoHS directive:Hazardous substance restrictions in optical coatings accelerate substitution toward lead-free glass formulations and compliant thin-film deposition.
- East Asian manufacturing clusters:Shenzhen, Seoul, and Taichung concentrate mold-making expertise, voice-coil motor integration, and wafer-level optics capability within tight logistics radii.
Market Restraints
- Specialized glass blank supply:Thermal stability requirements for hybrid glass-polymer elements tie pricing to limited qualified suppliers in Japan and Germany.
- GB standards enforcement:China's SAMR optical performance certification fragments qualification timelines for multinational smartphone programs serving domestic versus export markets.
- Periscope telephoto mechanical complexity:Prism assemblies and folded optics introduce yield sensitivity that constrains volume scaling.
Strategic Opportunities
- Automotive cabin monitoring:Driver attention and occupant sensing systems adapt smartphone lens architectures for infrared-capable, low-profile modules.
- India PLI scheme:Localized assembly incentives for electronics manufacturing attract module integrators establishing captive lens sourcing.
- AR/VR passthrough cameras:Mixed-reality headsets demand ultralight, high-resolution lenses with minimal distortion profiles.
Industry Challenges
- Aspherical grinding talent scarcity:Precision lens polishing requires multi-year apprenticeship pipelines that outpace current training capacity.
- Voice-coil motor calibration complexity:Optical image stabilization integration demands closed-loop testing infrastructure that extends certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMOS Smartphone Camera Lens Market |
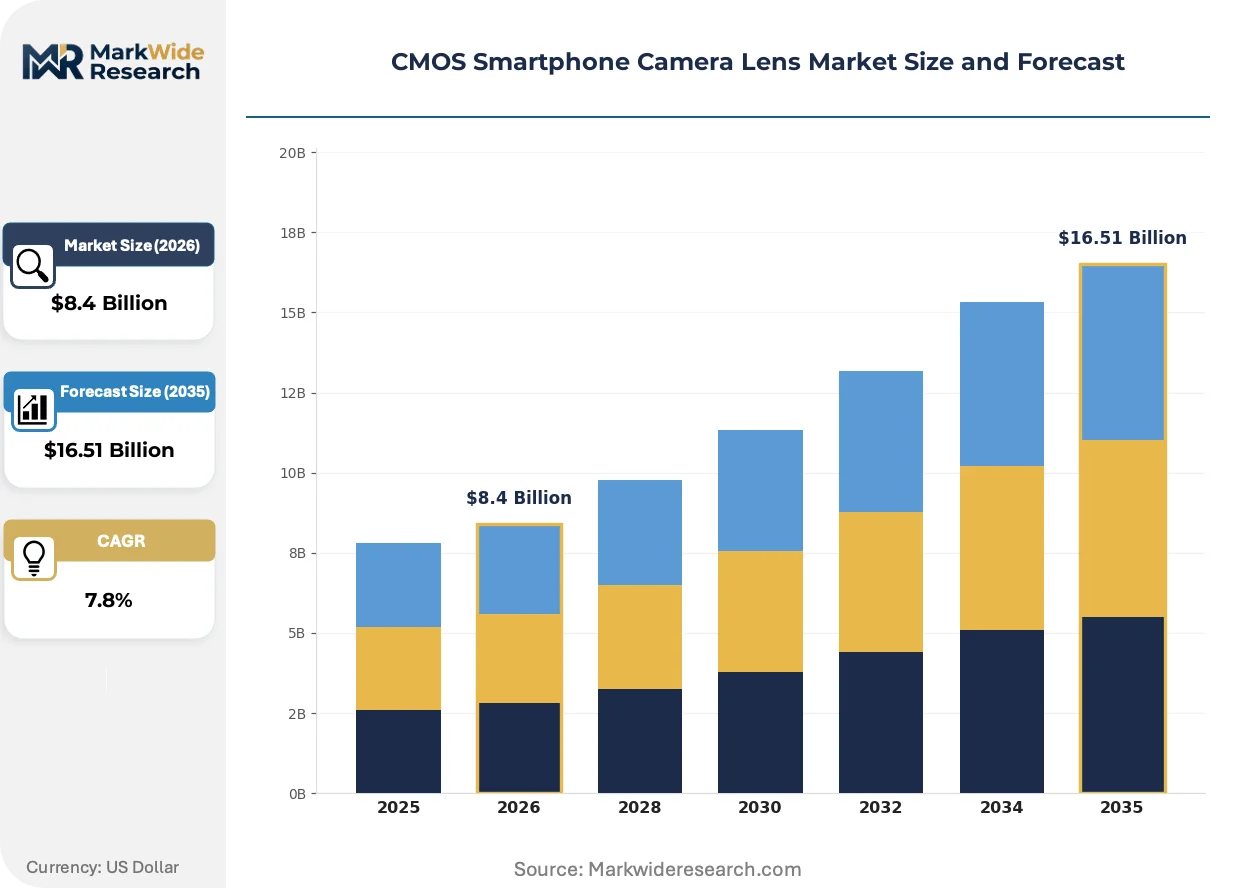
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Angle, Telephoto, Zoom, Macro Technology: Lens Coating, Optical Image Stabilization, Autofocus, Dual-Camera End User: Smartphone Manufacturers, Aftermarket Suppliers, Retailers, Consumers Application: Photography, Videography, Augmented Reality, Face Recognition |
| Companies Covered | Largan Precision, Sunny Optical Technology, Samsung Electro-Mechanics, Genius Electronic Optical, AAC Technologies, LG Innotek, OFILM Group, Asia Optical, Union Optical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMOS Smartphone Camera Lens Market Trends and Innovations
Wafer-level optics manufacturing is compressing unit economics for high-element-count lenses while computational demands reshape specification priorities across the supply base.
Continuous variable slurry polishing is automating the transition from spherical to freeform aspherical surfaces in mid-volume production. Tier-one module houses in Korea and Taiwan are adopting this equipment to reduce dependence on specialized Japanese grinding houses. The technology is automating yield recovery for complex 8P stacks that previously required manual rework.
EU REACH restrictions on phthalate plasticizers and heavy metals in coating chemistries are forcing reformulation of anti-reflective and hydrophobic thin films. European-bound lens assemblies now require substance-level documentation through the SCIP database. Premium tier suppliers with established green chemistry partnerships capture accelerated qualification pathways.
Smartphone OEMs are consolidating supplier panels and demanding joint development agreements with penalty clauses for roadmap misalignment. Module integrators now select lens partners based on simulation tool compatibility and shared IP libraries. This concentration is most visible in Korean and Chinese flagship programs where camera performance serves as primary differentiation.
CMOS Smartphone Camera Lens Market Segmentation
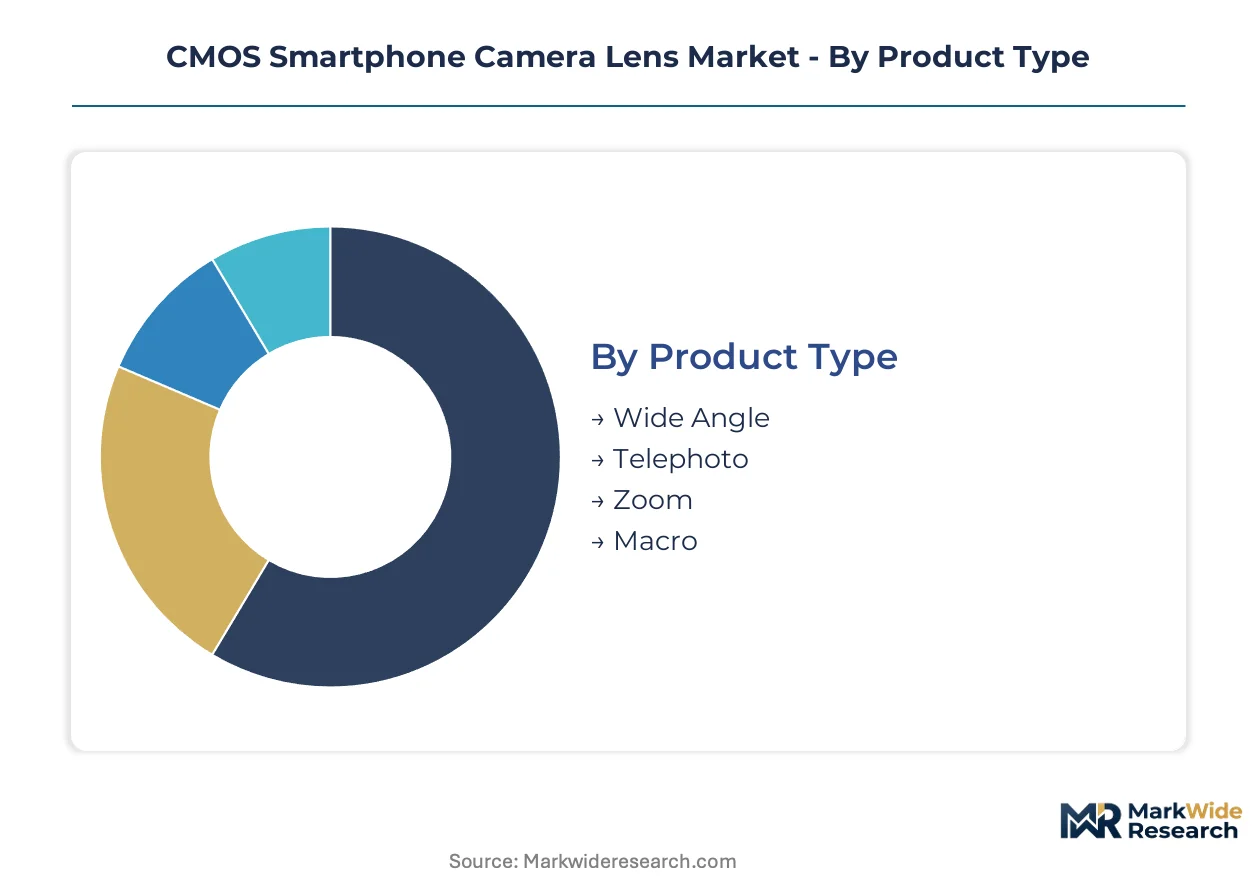
Segmentation in the CMOS smartphone camera lens market reveals how technical specifications, integration complexity, and end-use requirements fragment supplier capabilities and pricing power. Lens suppliers align manufacturing investments with the performance tiers and certification demands of each segment.
Product Type:
Supply concentration for molded glass and hybrid elements varies sharply across focal length categories, with premium telephoto and zoom assemblies commanding dedicated production lines in Taichung and Seoul.
- Wide Angle:These lenses utilize 5P to 7P plastic-polymer stacks with short effective focal lengths below 24mm equivalent. Demand concentrates in mid-tier smartphone programs from Chinese OEMs sourcing through Shenzhen module houses, where wafer-level optics manufacturing compresses unit costs for high-volume deployment.
- Telephoto:Periscope and folded-optics configurations require prism assemblies and extended optical paths that strain yield rates at Korean and Taiwanese integrators. Samsung Electro-Mechanics and LG Innotek anchor supply for flagship programs demanding 3x to 10x optical magnification.
- Zoom:Continuous optical zoom modules remain nascent, with liquid lens and variable-focus actuator technologies emerging from Israeli and Japanese development programs.
- Macro:Close-focusing optics serve content creator niches with dedicated minimum object distance specifications, typically 2cm to 10cm.
Today's leader: Wide Angle. Tomorrow's challenger: Telephoto.
Technology:
Margin structures across lens technologies reflect capital intensity, calibration infrastructure requirements, and intellectual property concentration in Japanese and Korean component suppliers.
- Lens Coating:Anti-reflective and hydrophobic thin-film deposition processes determine transmission efficiency and flare control. EU REACH restrictions on phthalate plasticizers and heavy metals force reformulation of coating chemistries for European-bound assemblies, with substance-level documentation through the SCIP database now mandatory.
- Optical Image Stabilization:Voice-coil motor integration demands closed-loop testing infrastructure that extends certification cycles. This technology leads segment margins due to actuator complexity and yield sensitivity at module integrators in Korea and Taiwan.
- Autofocus:Closed-loop voice-coil motor designs with hall-effect position sensing dominate flagship specifications.
- Dual-Camera:Baseline architectures for computational depth mapping have matured across mid-tier smartphones, with calibration requirements now standardized.
Optical Image Stabilization commands premium positioning. Lens Coating faces regulatory-driven restructuring.
End User:
Procurement patterns diverge between captive module production for smartphone OEMs and the fragmented replacement lens aftermarket.
- Smartphone Manufacturers:Apple, Samsung, and Chinese flagship OEMs consolidate supplier panels and demand joint development agreements with penalty clauses for roadmap misalignment. Module integrators select lens partners based on simulation tool compatibility and shared IP libraries.
- Aftermarket Suppliers:Independent repair networks and component distributors source replacement lens stacks for device refurbishment, with quality tiers separating OEM-grade from compatible alternatives.
- Retailers:Consumer-facing channels for clip-on and accessory lenses serve photography enthusiasts seeking hardware augmentation.
- Consumers:Direct purchase of replacement modules remains limited to enthusiast repair communities.
Smartphone Manufacturers dictate specification roadmaps. Aftermarket Suppliers capture volume in refurbishment cycles.
Application:
Computational photography pipelines reshape priority rankings across imaging use cases, with depth sensing and low-light algorithms pulling demand for specialized lens-sensor calibration.
- Photography:Computational pipelines for night mode, HDR stacking, and portrait segmentation require 7P and 8P lens stacks with tight modulation transfer function tolerances. Flagship programs in Korea and China prioritize camera performance as primary hardware differentiation.
- Videography:Cinematic mode and spatial video capture demand optical image stabilization with minimal focus breathing and consistent aperture control.
- Augmented Reality:Passthrough cameras for mixed-reality headsets demand ultralight, high-resolution lenses with minimal distortion profiles, adapting smartphone architectures for near-eye display systems.
- Face Recognition:Structured light and time-of-flight companion modules require infrared-capable lens elements with specific wavelength transmission characteristics.
Photography anchors current revenue. Augmented Reality represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters spanning Shenzhen, Seoul, and Taichung concentrate mold-making expertise, voice-coil motor integration, and wafer-level optics capability within tight logistics radii. This concentration shapes procurement patterns and qualification timelines across the industry.
China
Domestic OEM procurement for multi-lens flagship modules drives volume demand through Shenzhen module houses. SAMR enforces GB standards covering optical performance and environmental compliance for domestically sold lens assemblies. Wafer-level optics manufacturing in Shenzhen compresses unit economics for high-volume 7P and 8P stacks serving mid-tier smartphone programs.
South Korea
Flagship smartphone camera performance serves as primary hardware differentiation for Samsung and domestic OEMs. MFDS coordinates standards that influence component interoperability across Korean supply chains. Seoul anchors integrated module production combining lens, actuator, and filter divisions under unified manufacturing control.
Taiwan
Specialized aspherical grinding capabilities supply Apple and Samsung flagship programs through precision-molding expertise. METI-influenced JIS standards shape reliability testing protocols adopted by Taiwanese integrators. Taichung concentrates dedicated production lines for premium telephoto and zoom assemblies with extended optical paths.
Japan
Limited qualified suppliers of thermal-stability glass blanks tie pricing for hybrid lens elements to Japanese material science capabilities. METI coordinates JIS standards governing autofocus motor interoperability across East Asian supply chains. Specialized grinding houses in industrial corridors supply precision polishing equipment to tier-one module manufacturers.
Germany
EU REACH restrictions on phthalate plasticizers and heavy metals in coating chemistries force reformulation of anti-reflective thin films for European-bound assemblies. ECHA mandates substance-level documentation through the SCIP database for lens components. German optical glass suppliers qualify lead-free formulations that accelerate certification pathways for compliant module integrators.
CMOS Smartphone Camera Lens Market Competitive Landscape
Consolidation of supplier panels dominates the current landscape as smartphone OEMs demand joint development agreements with penalty clauses for roadmap misalignment. The vendor base separates into three tiers: scale-driven wafer-level optics manufacturers, precision-grinding specialists serving flagship programs, and vertically integrated module houses controlling bill-of-materials complexity. Two strategic archetypes define positioning: captive suppliers with backward integration into actuators and filters, and independent lens houses competing on simulation tool compatibility and shared IP libraries. Competitive moves center on M&A for grinding talent acquisition and capacity expansion for 8P stack production.
Among East Asian specialists, Largan Precision and Sunny Optical Technology exemplify contrasting scale-versus-precision archetypes, while Samsung Electro-Mechanics represents the vertically integrated module house model. These three anchors illustrate how geographic proximity to Shenzhen, Seoul, or Taichung manufacturing clusters shapes competitive positioning. Largan Precision occupies a position tied to specialized aspherical capabilities. Sunny Optical Technology exemplifies cost leadership through wafer-level process adoption. Samsung Electro-Mechanics sits within the captive supply tier leveraging in-house actuator and filter production.
| Leading Market Players |
|---|
| Largan Precision |
| Sunny Optical Technology |
| Samsung Electro-Mechanics |
| Genius Electronic Optical |
| AAC Technologies |
| LG Innotek |
| OFILM Group |
| Asia Optical |
| Union Optical |
| Others |
Pricing and Supply Chain Analysis
Wafer-level optics manufacturing is compressing unit economics for high-element-count lenses while simultaneously redrawing competitive boundaries between scale-driven suppliers and precision specialists. This production-method transition concentrates cost leadership in Shenzhen-based module houses while fragmenting premium-tier pricing power among Taichung and Seoul grinding specialists.
Pricing Analysis
Specialized glass blank costs from Japanese and German suppliers pass through directly to hybrid lens stack pricing, with thermal-stability requirements anchoring premium tier quotations. Three-tier pricing structure across premium, standard, and economy levels separates Apple and Samsung flagship programs from mid-tier Chinese OEM sourcing and aftermarket refurbishment channels. Price differentiation hinges on aspherical grinding certification and voice-coil motor integration complexity. Mid-tier module integrators exhibit highest price sensitivity as wafer-level process adoption intensifies cost compression.
Supply Chain Analysis
Freight costs for precision-molded glass elements from Japan and Germany to East Asian module integrators remain secondary to yield-loss economics at destination. Supply concentrates in China, South Korea, and Taiwan, with mold-making expertise clustering in Shenzhen, Seoul, and Taichung within tight logistics radii. Raw material dependencies include optical glass blanks, voice-coil motors, and anti-reflective coating chemistries. Single-source vulnerability for thermal-stability glass formulations from qualified Japanese suppliers constitutes primary structural risk. Distribution runs through captive module production for smartphone OEMs and fragmented aftermarket refurbishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on wafer-level process adoption compressing unit economics for high-volume 7P and 8P stacks, while premium-tier pricing power consolidates among specialized grinding houses serving flagship programs.
For Market Incumbents: Cement cost leadership through backward integration into voice-coil motor production and captive filter manufacturing, mirroring Samsung Electro-Mechanics' module house model. Expand 8P stack capacity in Taichung to capture periscope telephoto demand from Korean and Chinese flagship OEMs. Defend against yield-sensitive prism assembly entrants by locking multi-year grinding talent pipelines.
For New Entrants and Emerging Players: Begin with automotive cabin monitoring applications, where infrared-capable smartphone lens architectures face limited established supply relationships. Target India's PLI scheme localization incentives for electronics manufacturing assembly. Pursue joint development agreements with mixed-reality headset developers seeking ultralight passthrough camera modules.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier wafer-level optics manufacturers facing margin compression from 7P stack commoditization. Long-term viability favors precision-grinding specialists with multi-year apprenticeship pipelines and Apple or Samsung flagship program qualification. Watch periscope telephoto yield rates as inflection indicator for premium-tier pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Optics Capacity Expansion | Sunny Optical Technology leverages Shenzhen manufacturing to sustain cost leadership in high-volume 7P lens stacks. |
| Specialized Aspherical Grinding Acquisition | Largan Precision anchors premium tier through multi-year talent pipelines serving Apple and Samsung flagship programs. |
| Voice-Coil Motor Integration | Samsung Electro-Mechanics tightens bill-of-materials control through captive actuator and filter production. |
| Automotive Lens Architecture Adaptation | Driver attention systems repurpose smartphone lens designs for infrared-capable cabin monitoring modules. |
| India PLI Scheme Localization | Module integrators establish captive lens sourcing to capture localized electronics assembly incentives. |
Research Methodology
Bottom-up smartphone OEM procurement modeling reconciled against top-down module integrator capacity tracking forms the analytical core. Primary interviews with lens design engineers, voice-coil motor procurement leads, optical coating specialists, and flagship program supply chain managers combine with secondary validation from SEC filings, customs trade data, SAMR GB standard certifications, and ECHA SCIP database disclosures. Top-down triangulation against sensor and algorithm release schedules ensures roadmap alignment assumptions.
Historical trendline analysis of multi-lens array proliferation rates and computational photography pipeline requirements shapes projection methodology. Segmentation dimensions span focal length category, lens element count, stabilization technology, and regional manufacturing cluster. CAGRs derive from shipment volume modeling against effective focal length specification trends, with voice-coil motor yield sensitivity and glass blank supply constraints as industry-specific forecast inputs across the analysis window.
Several conditions sit outside the modeled scope, including sudden shifts in EU REACH substance restrictions, periscope telephoto mechanical yield breakthroughs, and Chinese SAMR certification timeline accelerations. Forecasts reflect assumptions about continued East Asian manufacturing concentration and flagship smartphone camera performance differentiation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Middle East and Africa Image Sensors Market
Imaging
Thermal Camera Market
Imaging
3D Sensing and Imaging Market
Imaging
Printed Image Sensors Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Gel Imaging Documentation Market
Imaging
Infrared Imaging Market
Imaging
PET Imaging Systems Market
Imaging
Camera Accessories Market
Imaging
Photoacoustic Imaging Market
Imaging
Global Panoramic Camera Market
Imaging
Global Acoustic Cameras Market
Imaging
Ingaas Image Sensor Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Mobile Camera Module Market
Imaging
Near Infra-Red Imaging Market