
 Residential 1080P Laser Television Projector Market | 2026-2036
Residential 1080P Laser Television Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Residential 1080P Laser Television Projector Market Insights
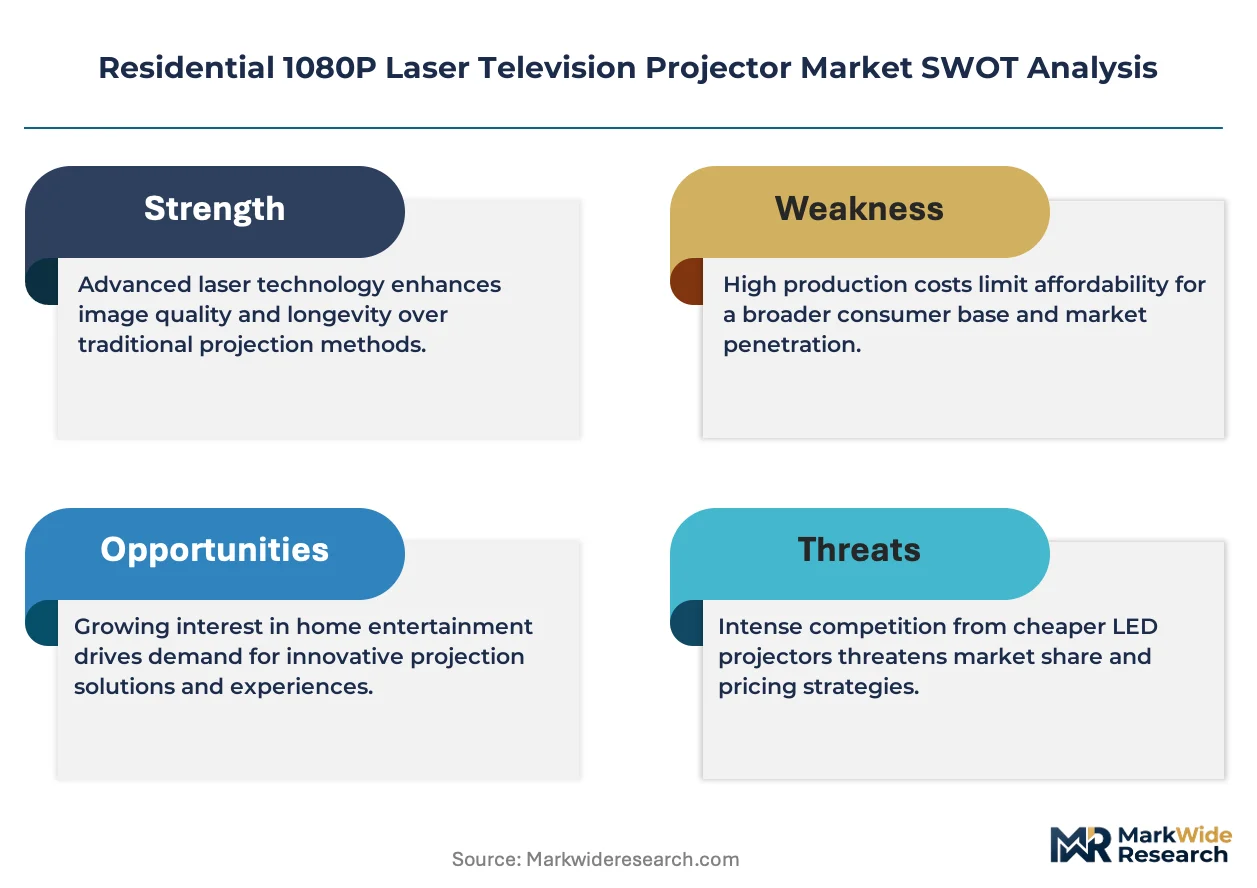
REACH compliance is expanding the cost-of-entry calculus for laser projector manufacturers sourcing rare-earth phosphors and optical components from European suppliers. Epson leverages captive lens production to sustain margin structures against rising material certification costs. Hisense anchors its position through integrated laser engine manufacturing in Qingdao, while Sony competes via premium image-processing silicon designed in Japan.
A residential 1080P laser television projector employs solid-state laser diodes—typically blue or red arrays paired with yellow phosphor wheels—to generate luminance exceeding 2,000 ANSI lumens with operational lifespans surpassing 20,000 hours, delivering cinematic-scale imagery in domestic environments without lamp replacement cycles. The ultra-short throw configuration leads product type segmentation by collapsing installation constraints in compact urban residences. Laser technology dominates the technology dimension through superior color gamut coverage against LED alternatives, while online retail channels capture the fastest-growing distribution flow by disintermediating traditional electronics storefronts.
The EU F-Gas Regulation constrains refrigerant-dependent cooling architectures in high-brightness units, while CE marking and FDA laser product safety standards govern eye-exposure thresholds and market access protocols across their respective jurisdictions. China's GB standards for laser display equipment impose additional optical radiation testing that shapes product design cycles for manufacturers targeting domestic certification. Stakeholders must monitor phosphor supply chain qualification timelines and cooling system redesign costs as regulatory stringency tightens across major demand centers.
Market Dynamics
Laser phosphor wheel miniaturization is compressing optical engine footprints while extending operational lifespans, enabling ultra-short throw installations in compact urban residences previously unreachable by projection systems.
Growth Catalysts
- EU F-Gas Regulation:Manufacturers redesigning cooling architectures for high-brightness units gain first-mover advantage in European distribution channels as refrigerant-dependent competitors face compliance delays.
- Home theater retrofit demand:Premium living space renovations in China and Japan incorporate dedicated projection rooms, pulling 1080P laser systems into residential specifications previously reserved for commercial cinema.
- Laser diode array efficiency gains:Blue and red diode power conversion improvements above 40% reduce thermal management requirements, shrinking chassis depth and expanding placement flexibility.
Market Restraints
- Rare-earth phosphor cost volatility:Yttrium and cerium supply concentration in Chinese processing facilities creates input price instability for yellow phosphor wheel production.
- GB standards optical radiation testing:China's certification timeline extends product design cycles by four to six months for manufacturers lacking domestic testing partnerships.
- Large-format LED television substitution:Direct-view microLED and miniLED panels above 85 inches capture price-sensitive consumers seeking ambient-light performance without installation complexity.
Strategic Opportunities
- India residential premiumization:Metro apartment developments in Mumbai and Bangalore specify built-in projection niches, creating untapped demand for compact laser television systems.
- Online retail channel expansion:Direct-to-consumer platforms disintermediate electronics storefronts, capturing margin previously allocated to distributor networks.
- IRA residential energy efficiency incentives:US homeowners accessing tax credits for low-power display technologies offset upfront laser projector premiums through operational cost positioning.
Industry Challenges
- Optical system calibration expertise:Ultra-short throw lens alignment requires specialized technician training unavailable in standard audiovisual installation networks.
- Multi-jurisdiction laser safety certification:FDA 21 CFR 1040.10, IEC 60825-1, and GB 7247.1 testing divergence forces redundant documentation and timeline fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential 1080P Laser Television Projector Market |
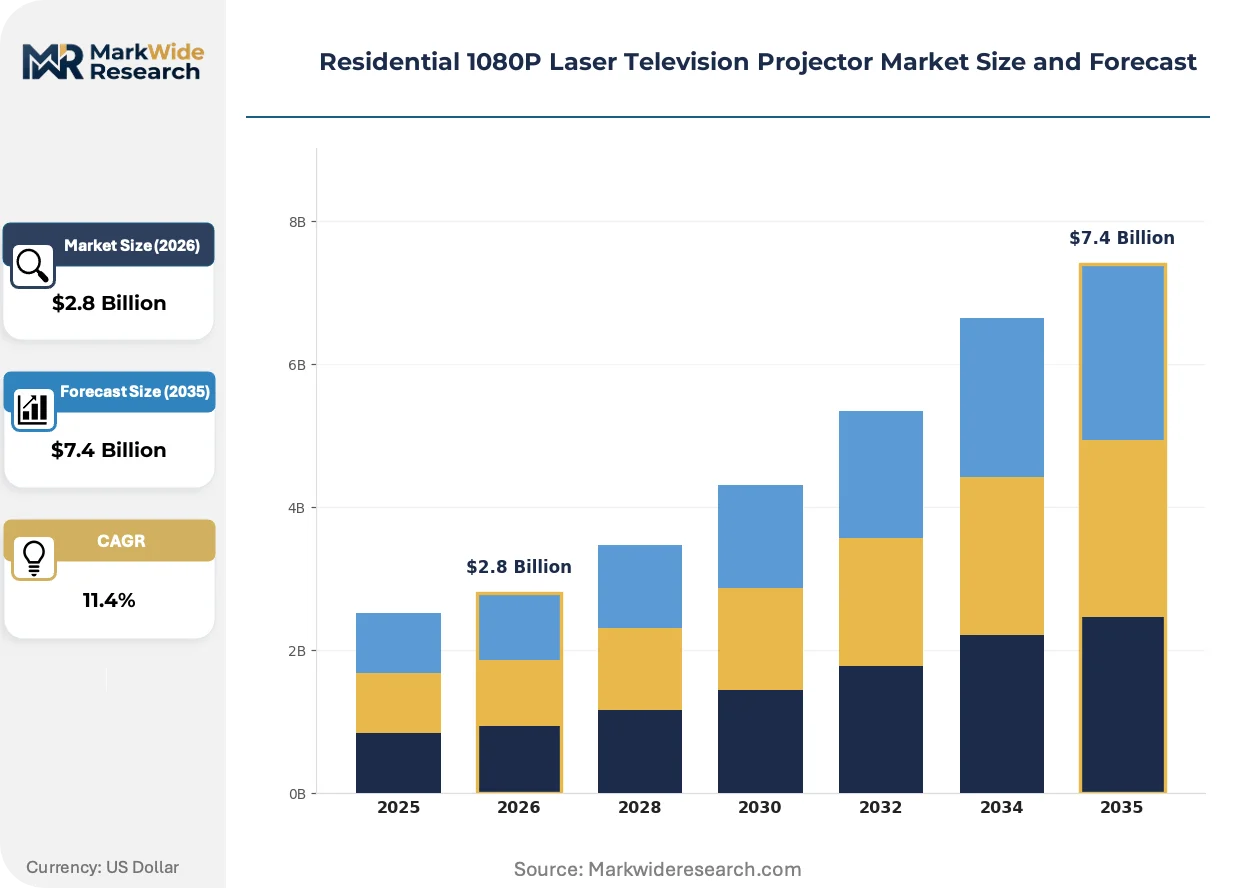
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry-Level, Mid-Range, High-End, Ultra-Short Throw Technology: Laser, LED, DLP, LCD End User: Home Theater Enthusiasts, General Consumers, Educational Institutions, Corporate Users Distribution Channel: Online Retail, Electronics Stores, Wholesale Distributors, Rental Services |
| Companies Covered | ViewSonic, Epson, Sony, AWOL Vision, Formovie, Leica, Valerion, XGIMI, Hisense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential 1080P Laser Television Projector Market Trends and Innovations
Optical engine convergence with smart television platforms is dissolving category boundaries between projection and integrated display systems, compressing go-to-market timelines for hybrid product architectures.
Hybrid laser-LED light source architectures are unifying the color stability of solid-state diodes with the cost structure of phosphor-converted systems. Home theater installers specify these configurations for multi-purpose living rooms where dedicated darkening is impractical. The technology is unifying previously separate premium and mass-market product tiers into single platform families with modular brightness specifications.
REACH substance restriction expansions are forcing reformulation of phosphor binder chemistries and optical coating compounds. European suppliers face qualification backlogs for alternative rare-earth processing agents, compressing available component sourcing windows. High-brightness projector manufacturers targeting CE marking are accelerating in-house materials testing to circumvent third-party laboratory queues.
Consumer acquisition patterns are fragmenting across rental-versus-own preferences, with subscription-based hardware refresh programs emerging in urban Japanese and South Korean markets. Traditional electronics retailers cede ground to manufacturer-direct leasing platforms that bundle installation and maintenance. This shift concentrates most visibly in Tokyo and Seoul apartment districts where space constraints favor temporary ownership models over permanent fixture investments.
Residential 1080P Laser Television Projector Market Segmentation
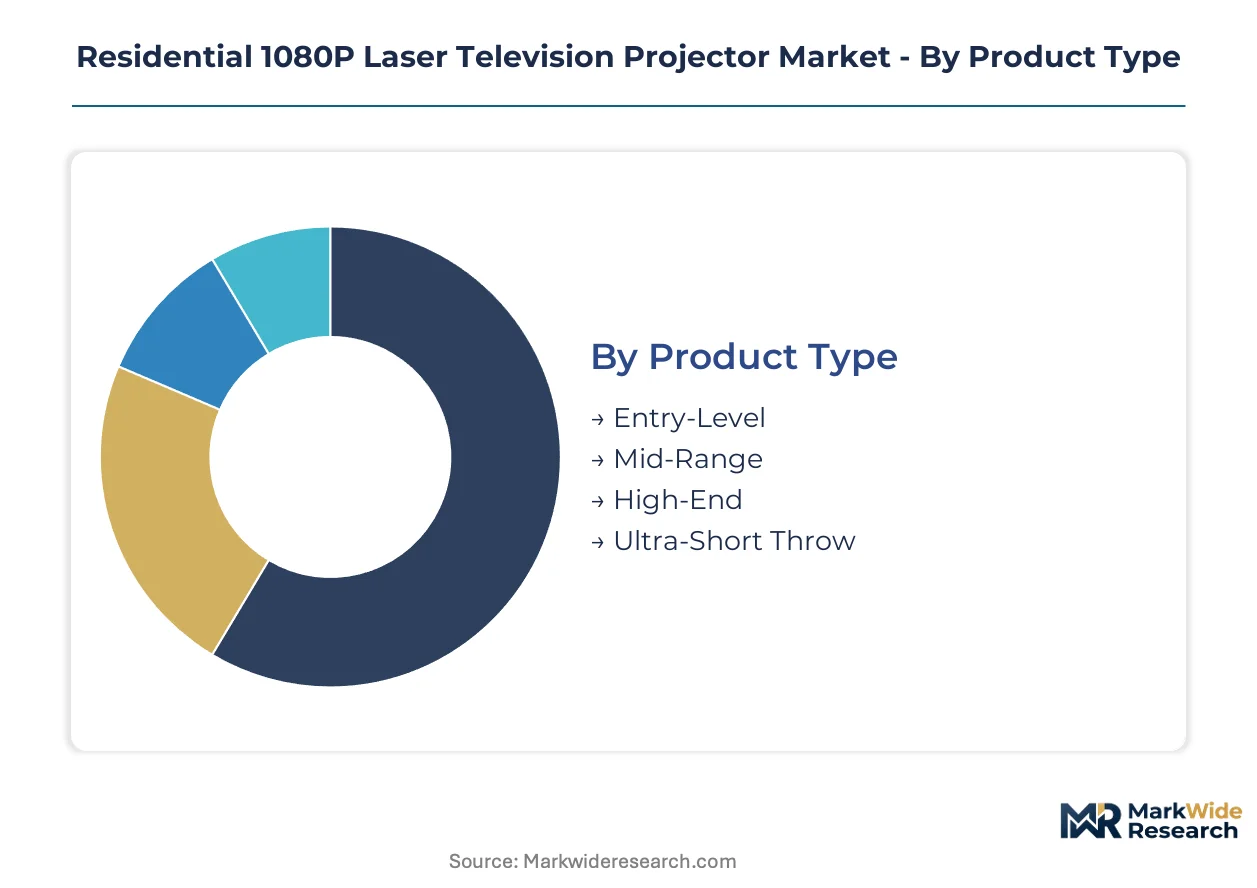
Product architecture in the residential 1080P laser television projector market fragments across installation geometry, light source physics, and buyer sophistication. Each segmentation dimension carries distinct capital requirements, certification burdens, and margin structures that shape manufacturer portfolio decisions.
Product Type:
Capital intensity escalates dramatically with throw ratio compression and optical precision requirements.
- Ultra-Short Throw:Complex aspheric mirror arrays and precision-calibrated lens barrels dominate the bill of materials. Demand concentrates in Tokyo and Shanghai high-rise apartments where wall-to-sofa distances fall below 2 meters, with installation constraints driving specification in compact urban residences.
- High-End:Tri-laser RGB architectures and cinema-grade color calibration engines define this tier. Demand clusters in dedicated home theater renovations across Beijing and Los Angeles, with acoustic integration requirements pulling systems into premium residential specifications.
- Mid-Range:Single-laser phosphor wheels with supplemental LED arrays balance performance against thermal management costs.
- Entry-Level:Simplified optical blocks and reduced lumen output target price-sensitive first-time projector buyers.
Ultra-Short Throw absorbs the bulk of installed capacity; High-End is expanding most quickly.
Technology:
Light source selection determines thermal design complexity, color gamut certification pathways, and long-term maintenance economics.
- Laser:Solid-state diode arrays paired with phosphor wheels or direct RGB configurations deliver 20,000+ hour lifespans and wide color gamut coverage. Demand concentrates in China and Japan where GB standards and JIS certification frameworks favor established laser safety documentation.
- LED:Phosphor-converted and RGB LED engines compete on immediate cost but sacrifice peak luminance. Demand persists in Southeast Asian markets with less stringent optical radiation testing and ambient-light viewing requirements.
- DLP:Texas Instruments micromirror chipsets enable high-speed color sequential processing with minimal motion artifacts.
- LCD:3LCD architectures from Japanese and Taiwanese panel suppliers maintain share in cost-sensitive segments through mature manufacturing scale.
Laser captures the dominant technology position; LED maintains residual share in emerging markets.
End User:
Buyer sophistication determines specification complexity, installation service bundling, and replacement cycle timing.
- Home Theater Enthusiasts:Calibrated color accuracy, low input lag, and acoustically isolated installation environments define purchasing criteria. Demand concentrates in dedicated media room renovations across suburban Los Angeles and Shenzhen, with ISF certification and THX alignment driving premium positioning.
- General Consumers:Streaming platform integration, voice control compatibility, and minimal setup complexity dominate decision frameworks. Demand spreads through online retail channels in tier-two Chinese cities and midwestern United States suburbs, with all-in-one smart platform bundling reducing perceived installation risk.
- Educational Institutions:Daylight-viewable brightness and network management capabilities prioritize institutional procurement.
- Corporate Users:Portable form factors and wireless presentation systems serve hybrid meeting room deployments.
Home Theater Enthusiasts absorb the bulk of high-margin volume; General Consumers are climbing the fastest.
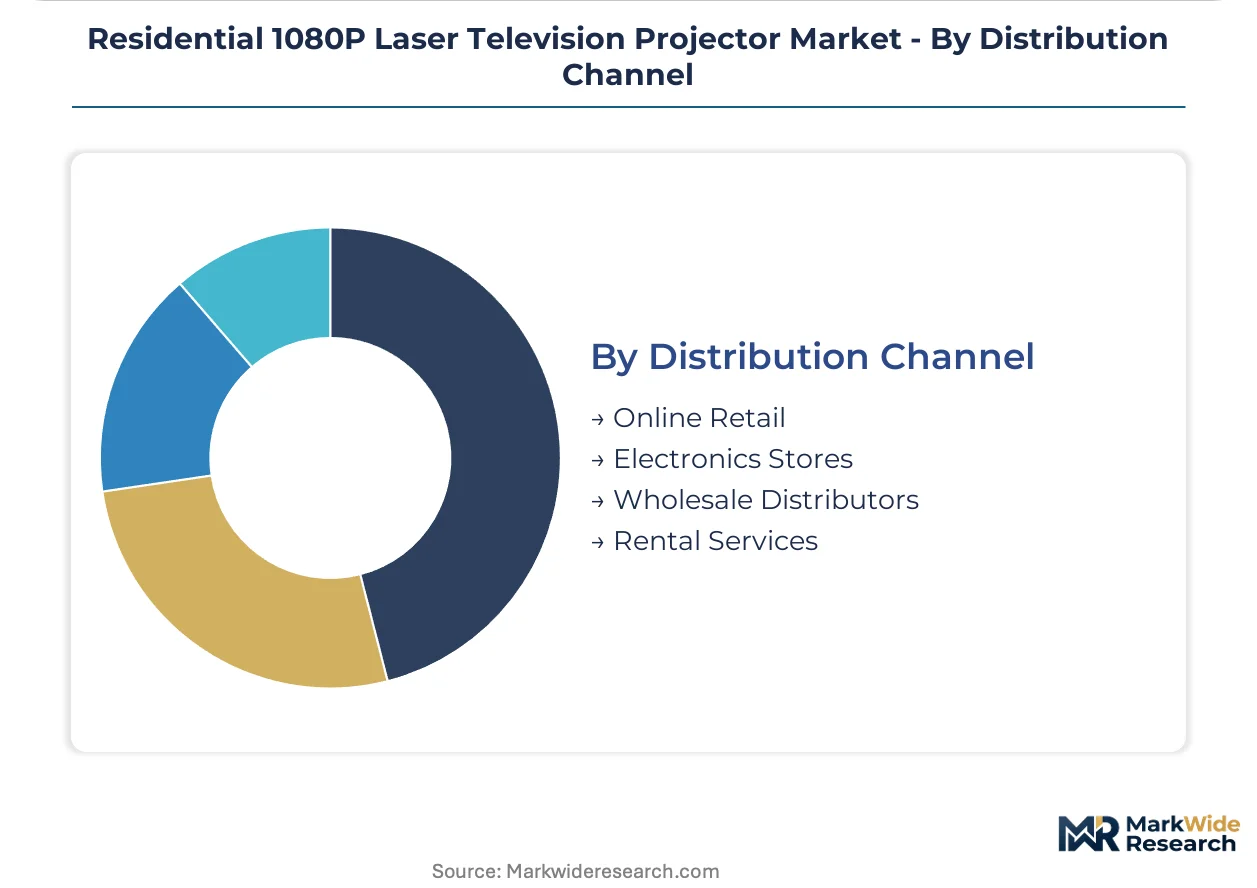
Distribution Channel:
Channel selection determines margin retention, installation service integration, and customer acquisition cost structures.
- Online Retail:Direct-to-consumer platforms bypass distributor markups while enabling manufacturer-controlled messaging and bundling. Demand concentrates in Amazon and Tmall ecosystems across the United States and China, with augmented reality preview tools and chatbot-assisted specification reducing return rates.
- Electronics Stores:Physical demonstration environments and commissioned sales staff sustain relevance for high-consideration purchases. Demand persists in Japanese Bic Camera and Yodobashi Camera locations, with side-by-side brightness comparison displays converting hesitant projector adopters.
- Wholesale Distributors:Regional AV integrators and custom installation firms source through specialized B2B networks.
- Rental Services:Subscription hardware refresh programs emerge in Tokyo and Seoul apartment districts favoring temporary ownership.
Online Retail captures the steepest expansion trajectory; Electronics Stores retain conversion advantages for premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao Economic and Technical Development Zone concentrates laser engine manufacturing capacity, while Los Angeles County's home theater retrofit market drives premium specification demand.
China
GB standards for laser display equipment impose optical radiation testing that extends certification timelines. Home theater enthusiasts in Shenzhen and Beijing drive demand for ultra-short throw configurations in compact high-rise apartments. Hisense maintains integrated laser engine production in Qingdao, supplying domestic and export markets.
United States
IRA residential energy efficiency incentives offset upfront premiums for low-power display technologies. The FDA governs laser product safety standards for eye-exposure thresholds under 21 CFR 1040.10. Los Angeles and Dallas suburbs host dedicated media room renovations specifying cinema-grade color calibration.
Japan
METI oversees JIS certification frameworks favoring established laser safety documentation. Tokyo and Osaka apartment districts favor ultra-short throw installations with wall-to-sofa distances below two meters. Bic Camera and Yodobashi Camera sustain physical demonstration environments for high-consideration purchases.
Germany
EU F-Gas Regulation constrains refrigerant-dependent cooling architectures in high-brightness units. REACH compliance expands cost-of-entry for manufacturers sourcing rare-earth phosphors from European suppliers. Munich and Berlin custom installation firms specify premium-tier systems for dedicated projection rooms.
India
BIS certification requirements shape product design cycles for manufacturers targeting domestic market access. Metro apartment developments in Mumbai and Bangalore specify built-in projection niches for compact laser television systems. Maharashtra and Karnataka host emerging distribution infrastructure for online retail channel expansion.
Residential 1080P Laser Television Projector Market Competitive Landscape
Chinese producers anchor one tier; Japanese and German specialists hold differentiated positions in premium calibration and optical component supply. The vendor base distributes across integrated platform manufacturers, captive lens producers, and smart television convergents. Three archetypes dominate: laser engine integrators, image-processing silicon designers, and ultra-short throw optical specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the integrated manufacturing tier, Hisense and Epson exemplify divergent sourcing strategies. Hisense occupies a position anchored in Qingdao-based laser engine production. Epson represents captive lens manufacturing as a margin defense mechanism. Sony sits within the image-processing silicon designer archetype, with Japanese-designed components distinguishing premium positioning. AWOL Vision and XGIMI occupy positions in the ultra-short throw specialist segment.
| Leading Market Players |
|---|
| ViewSonic |
| Epson |
| Sony |
| AWOL Vision |
| Formovie |
| Leica |
| Valerion |
| XGIMI |
| Hisense |
| Others |
Pricing and Supply Chain Analysis
Rare-earth phosphor wheel assemblies trace a cost cascade from Chinese yttrium and cerium processing facilities through three distinct pricing tiers downstream. Premium ultra-short throw configurations absorb elevated input costs through integrated optical engine manufacturing, while entry-level manufacturers face margin compression from spot-market phosphor pricing volatility.
Pricing Analysis
Short lead-time premiums for GB-certified optical radiation testing separate expedited market entry from standard six-month certification cycles. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in laser diode array efficiency grades and after-sales calibration service bundling. Cost compression in the entry tier intensifies because large-format LED television substitution erodes price-floor support. General consumers exhibit highest price sensitivity, while home theater enthusiasts accept premiums for ISF-certified color accuracy.
Supply Chain Analysis
CE marking and FDA laser safety certification gates constrain supplier qualification timelines for European and North American market access. Optical component sourcing concentrates in China, Japan, and Germany, with phosphor binder chemistries drawing from REACH-compliant European suppliers. Single-source vulnerability concentrates in rare-earth processing facilities. Distribution runs through online retail platforms disintermediating traditional electronics storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state laser diode arrays are displacing legacy lamp-based projection systems across residential specifications, compressing replacement cycles and reshaping manufacturer R&D allocation.
For Market Incumbents: To counter large-format LED television substitution in the 85-inch-plus segment, Hisense and Epson should deepen backward integration into captive laser engine production and accelerate cooling architecture redesigns for EU F-Gas Regulation compliance. Certification investment in multi-jurisdiction laser safety documentation defends channel access against emerging entrants facing timeline fragmentation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in India's metro apartment developments offers white-space penetration for compact ultra-short throw configurations targeting Mumbai and Bangalore built-in projection niches. Direct-to-consumer online retail channel entry bypasses distributor markups. Leasing platform partnerships in Tokyo and Seoul apartment districts capture temporary ownership preference shifts. For Investors and Strategic Acquirers: Consolidation of third-party optical radiation testing laboratories is the leading indicator that supply-side bottlenecks are intensifying. Long-term viability over the next decade rests on manufacturers controlling phosphor supply chain qualification timelines. Acquisition targets should display in-house materials testing capabilities circumventing third-party laboratory queues. Watch for Hisense or Epson vertical integration moves into rare-earth processing partnerships as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Engine Manufacturing | Qingdao-based captive production insulates Hisense against phosphor cost volatility and REACH compliance delays. |
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous FDA, IEC 60825-1, and GB 7247.1 documentation accelerates market entry across China, Japan, and the United States. |
| Online Retail Channel Expansion | Amazon and Tmall ecosystems capture margin previously allocated to Bic Camera and Yodobashi Camera distributor networks. |
| Hybrid Light Source Architecture Development | Laser-LED unification merges color stability with phosphor-converted cost structures for multi-purpose living room penetration. |
| Subscription Hardware Refresh Programs | Temporary ownership models in Tokyo and Seoul apartment districts concentrate demand away from permanent fixture investments. |
Research Methodology
Multi-period observation of laser diode efficiency gains, phosphor supply chain qualification timelines, and online retail channel share shifts anchored the trend analysis, supplemented by interviews with optical system engineers, home theater installation technicians, consumer electronics procurement managers, and regulatory compliance officers at laser display manufacturers. Secondary validation drew from FDA 21 CFR 1040.10 filings, METI JIS certification databases, GB standards optical radiation test reports, and SEC 10-K disclosures from listed projector manufacturers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Input-output matrices modeled demand drivers across product type, technology, end user, and distribution channel dimensions, with additional segmentation by regional regulatory framework clusters. CAGRs were derived from fitted growth curves against historical adoption patterns and projected replacement cycle compression. Forecast inputs incorporated laser phosphor wheel miniaturization trajectories and IRA residential energy efficiency incentive uptake rates across the projection horizon.
Inputs from regulatory filing databases and primary field interviews were available through the study window; gaps in real-time phosphor spot pricing data and subscription program churn rates introduce uncertainty bands around margin projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Laser Transmitter Market
Optics
Optical Measuring Systems Market
Optics
Optical Telephoto Lens Market
Optics
Tunable Laser Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Smart Photochromic Lenses Market
Optics
Fiber Optical Receivers Market
Optics
Fiber Optics Market
Optics
Global Super Hi Vision Market
Optics
Interchangeable Lens Market
Optics
Optical Profilometer Market
Optics
Smart Vision Systems Market
Optics
Photonics Sensor Market
Optics
India Laser Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Global Enhanced Vision System Market