
 Smart Home Healthcare Market | 2026-2036
Smart Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Healthcare Market Intelligence
Hospital systems are rotating procurement authority toward home care providers and insurance payers. Medtronic leverages its cardiac rhythm portfolio to anchor remote patient monitoring contracts with large payer networks. Abbott competes through continuous glucose monitoring systems that extend hospital-grade accuracy into residential settings. Dexcom specializes in wearable sensor platforms that dominate the diabetes management channel.
Smart home healthcare encompasses connected medical devices, software platforms, and sensor networks that collect physiological data from residential environments and transmit it to clinicians or algorithms for real-time intervention, typically operating through FDA-cleared or CE-marked systems with cloud-connected architectures. Remote monitoring devices and wearable sensors capture the largest revenue pools, while telehealth platforms are displacing episodic office visits as reimbursement codes mature. Artificial intelligence and big data analytics sit at the margin concentration point, where algorithmic triage commands premium pricing from payers seeking to reduce emergency department utilization.
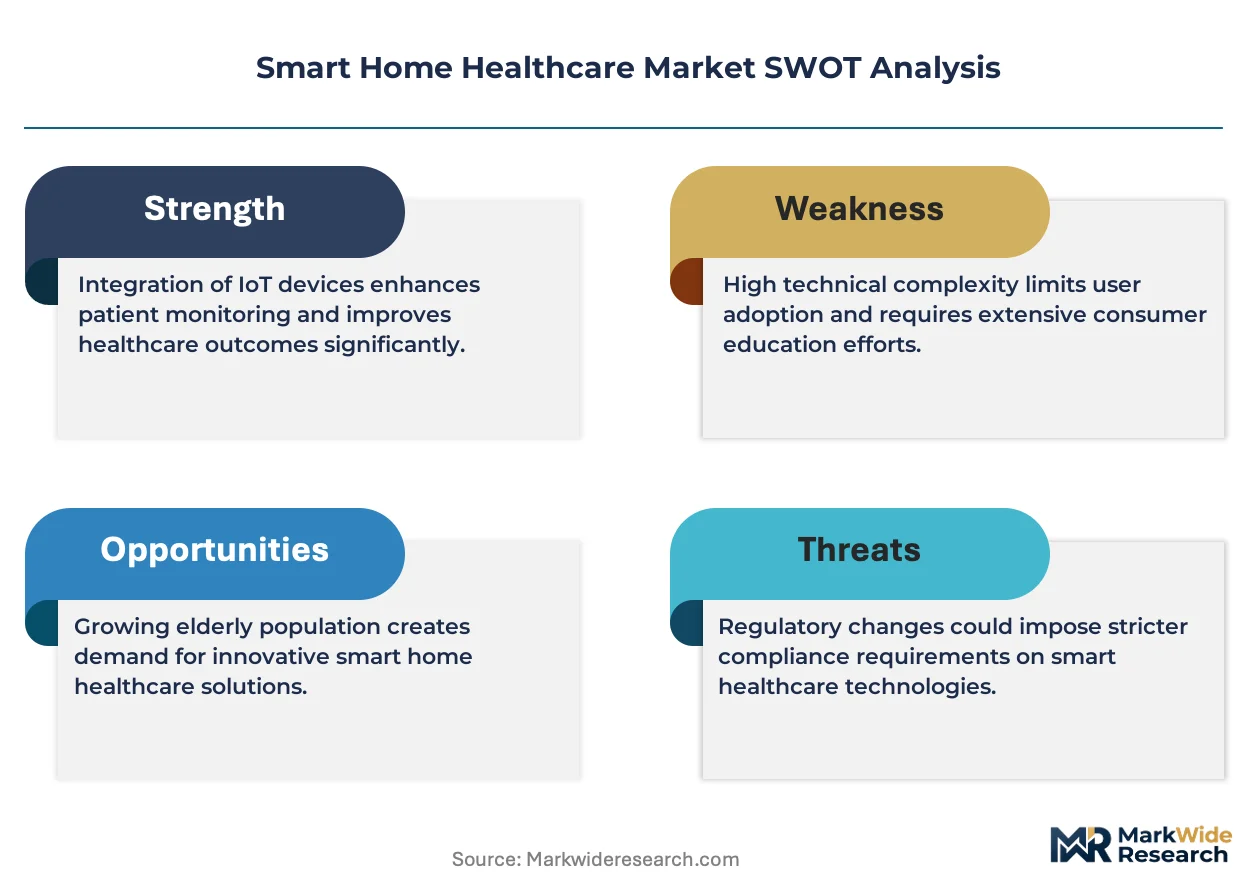
FDA Software as a Medical Device guidance, EU MDR conformity requirements, and HIPAA security rules collectively shape product development timelines, data architecture investments, and market access pathways for connected health vendors. The EU AI Act adds algorithmic transparency obligations that will filter vendor capabilities by regulatory sophistication. Stakeholders must monitor reimbursement parity legislation and cybersecurity certification mandates as the primary variables determining which product categories achieve scalable deployment.
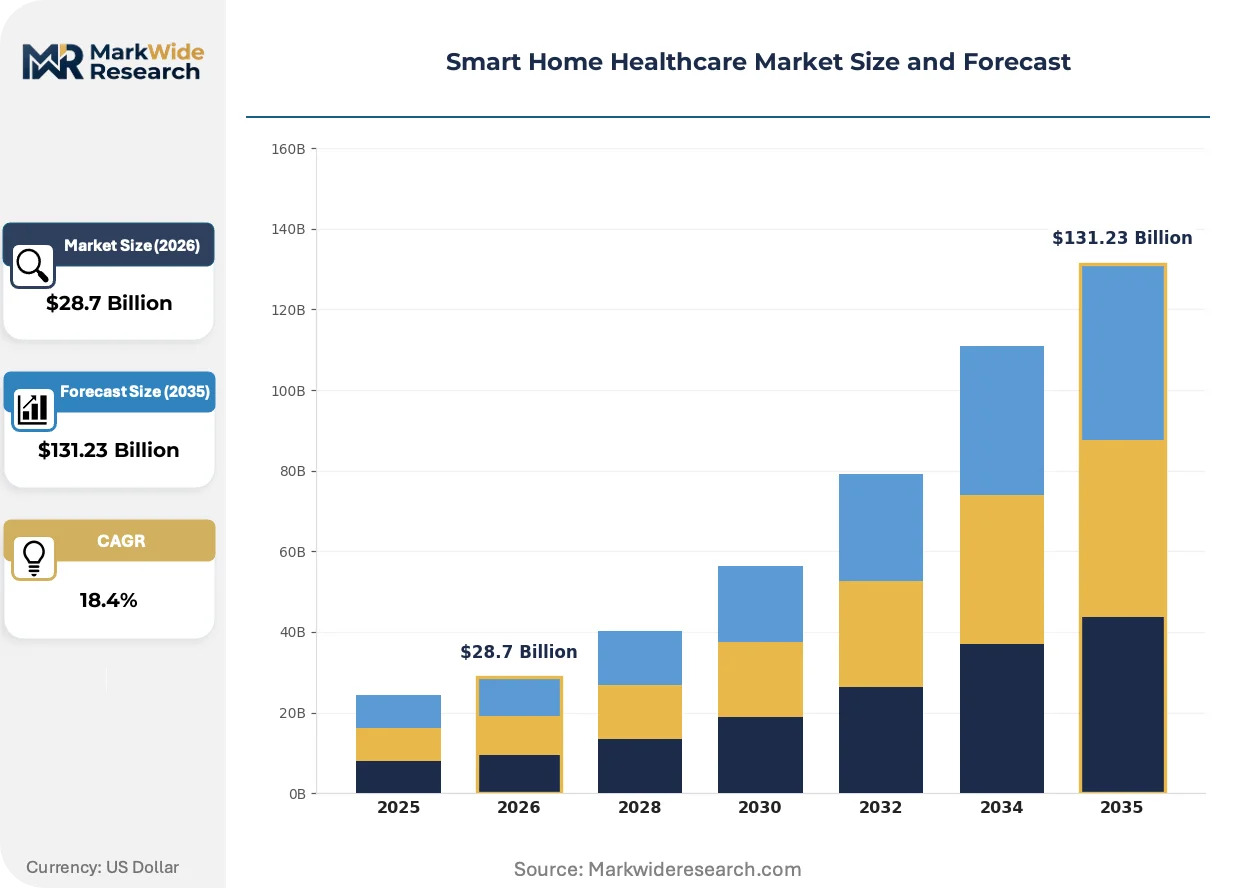
Market Dynamics
Hospital procurement authority is rotating toward home care providers and insurance payers, compressing traditional device margins while expanding subscription-based remote monitoring contracts. This power shift is restructuring vendor relationships and accelerating platform consolidation.
Growth Catalysts
- FDA Software as a Medical Device guidance:Clearer premarket pathways accelerate connected health product commercialization, reducing regulatory uncertainty for algorithm-driven diagnostic tools.
- Aging demographics in Japan and Germany:Reimbursement shifts toward in-home care create sustainable revenue streams for chronic disease monitoring platforms.
- Continuous glucose monitoring sensors:Hospital-grade accuracy in residential settings is expanding addressable patient populations beyond traditional clinical boundaries.
Market Restraints
- EU MDR conformity assessment bottlenecks:Extended notified body capacity constraints delay CE marking timelines for connected medical devices.
- Semiconductor supply concentration in East Asia:Sensor module availability faces geographic single-point vulnerability.
- HIPAA security architecture requirements:Cloud infrastructure investments impose capital intensity on smaller platform vendors.
Strategic Opportunities
- Algorithmic triage in United States payer networks:Emergency department utilization reduction contracts command premium pricing for AI-enabled risk stratification.
- EU AI Act transparency obligations:Regulatory sophistication filters will advantage established vendors with compliance infrastructure.
- Integration of ambient sensors with wearable platforms:Passive monitoring in residential environments enables new behavioral data revenue streams.
Industry Challenges
- Interoperability with legacy electronic health record systems:HL7 FHIR implementation requires specialized health IT integration expertise.
- Cybersecurity certification mandates:IEC 62304 software lifecycle processes extend development timelines for connected device firmware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Healthcare Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $131.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Monitoring Devices, Wearable Sensors, Smart Medication Dispensers, Telehealth Platforms, Emergency Alert Systems Application: Chronic Disease Management, Elderly Care, Fitness Tracking, Postoperative Care, Remote Diagnostics Technology: IoT, Artificial Intelligence, Cloud Computing, Bluetooth Low Energy, Big Data Analytics End User: Home Care Providers, Insurance Companies, Remote Clinics, Assisted Living Facilities, Rehabilitation Centers |
| Companies Covered | Medtronic, Abbott, Dexcom, Apple, Google, Withings, Tunstall Group, VitalConnect, Medical Guardian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Healthcare Market Strategic Shifts & Innovations
Artificial intelligence architectures are compressing clinical decision timelines while ambient sensing technologies expand data capture beyond wearable boundaries. Algorithmic transparency requirements and reimbursement parity legislation are simultaneously reshaping product roadmaps and go-to-market strategies.
Edge computing for real-time physiological signal processing is fragmenting cloud dependency in remote patient monitoring architectures. Home care providers in Germany and Japan are deploying local inference engines to reduce latency for cardiac arrhythmia detection. This distributed architecture is fragmenting traditional platform vendor control over data workflows and enabling regional technology partnerships.
EU AI Act algorithmic transparency mandates impose documentation burdens on machine learning-based diagnostic outputs. Medical device manufacturers must maintain technical files demonstrating training data provenance and performance validation across demographic subgroups. Cardiovascular risk prediction algorithms face the most stringent conformity assessment requirements, driving consolidation toward vendors with established quality management systems.
Subscription contracting for continuous monitoring services is displacing capital equipment sales in United States payer relationships. Large insurance networks negotiate multi-year remote patient monitoring agreements that bundle hardware, connectivity, and clinical interpretation. This shift is most advanced in diabetes management, where per-member-per-month pricing now dominates Medicare Advantage channel economics.
Smart Home Healthcare Market Segmentation
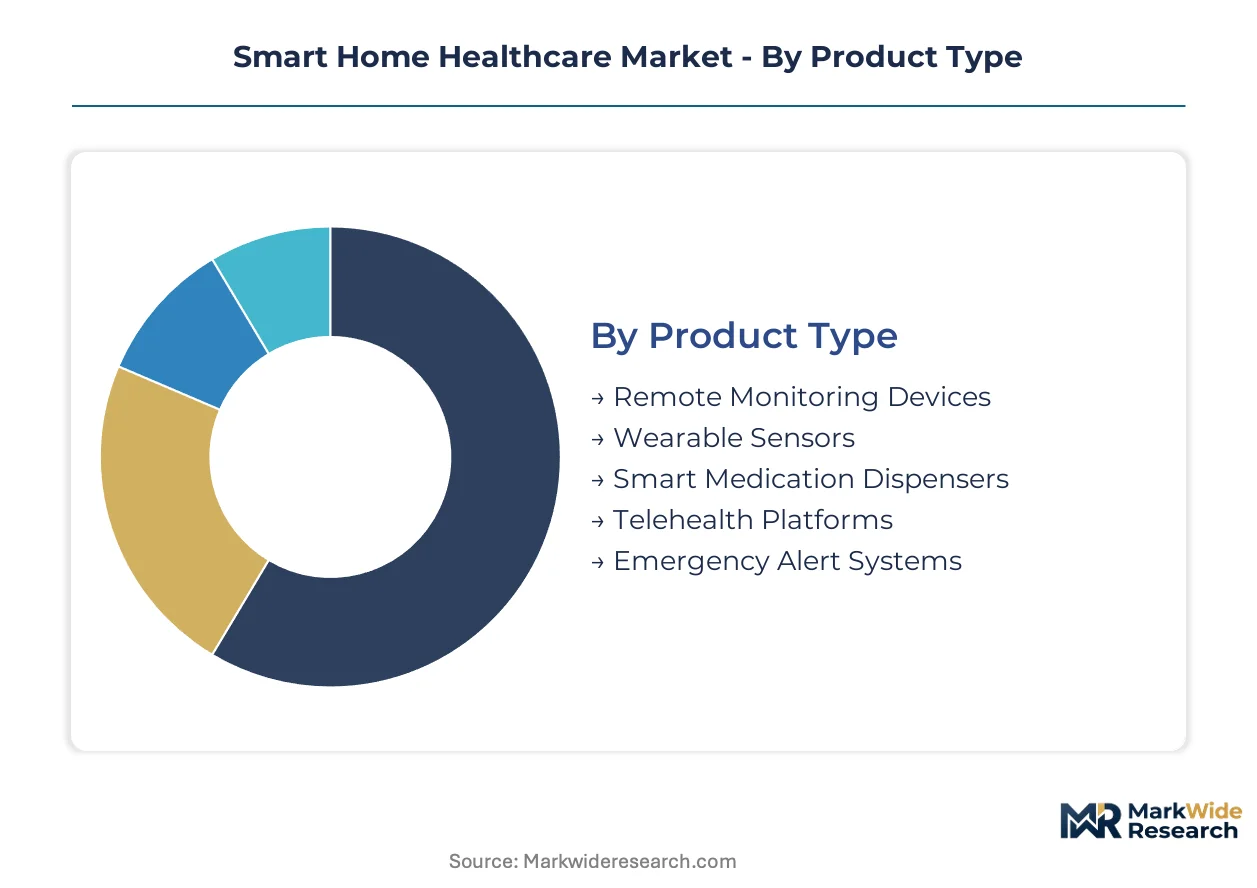
Segmentation in smart home healthcare reveals how regulatory pathways, reimbursement structures, and technology maturity create divergent commercial trajectories across product categories and customer channels. Understanding these divides enables vendors to allocate R&D resources toward segments with sustainable margin profiles and scalable deployment potential.
Product Type:
FDA Software as a Medical Device guidance and EU MDR conformity requirements create tiered compliance burdens that reshape competitive positioning across hardware categories.
- Remote Monitoring Devices:Cardiac rhythm monitors and pulse oximeters transmit physiological data through FDA-cleared or CE-marked systems with cloud-connected architectures. Hospital systems in the United States rotate procurement authority toward home care providers seeking to reduce emergency department utilization through real-time intervention capabilities.
- Wearable Sensors:Continuous glucose monitoring platforms and multi-parameter biosensors capture the largest revenue pools through subscription-based contracting with Medicare Advantage networks. Germany and Japan deploy local inference engines to reduce latency for cardiac arrhythmia detection, fragmenting traditional vendor control over data workflows.
- Smart Medication Dispensers:Automated pill organizers with adherence tracking face HIPAA security architecture requirements that impose capital intensity on smaller platform vendors.
- Telehealth Platforms:Video consultation and asynchronous messaging systems displace episodic office visits as reimbursement codes mature across United States payer networks.
- Emergency Alert Systems:Fall detection pendants and ambient monitoring hubs serve elderly care applications with lower regulatory barriers but compressed margins.
Established volume favors remote monitoring devices; emerging adoption favors wearable sensors.
Application:
Reimbursement parity legislation and aging demographics concentrate demand in clinically validated use cases with measurable outcome metrics.
- Chronic Disease Management:Diabetes, heart failure, and hypertension monitoring platforms command premium pricing through emergency department utilization reduction contracts. United States insurance networks negotiate multi-year agreements bundling hardware, connectivity, and clinical interpretation.
- Elderly Care:Aging populations in Japan and Germany accelerate in-home care adoption through reimbursement shifts that create sustainable revenue streams for passive monitoring technologies.
- Fitness Tracking:Consumer-grade wellness devices operate outside medical device regulatory frameworks, limiting clinical integration but preserving margin flexibility.
- Postoperative Care:Surgical recovery monitoring reduces readmission penalties for hospital systems, driving pilot deployments with limited scale.
- Remote Diagnostics:Algorithm-driven triage tools face EU AI Act transparency obligations that filter vendor capabilities by regulatory sophistication.
Chronic disease management anchors current revenue; elderly care is expanding most quickly as demographic shifts mature.
Technology:
Data architecture investments and algorithmic transparency obligations determine which technology layers achieve scalable deployment across regulated markets.
- IoT:Sensor networks and connected device ecosystems form the foundational infrastructure for residential physiological data capture.
- Artificial Intelligence:Machine learning-based diagnostic outputs require technical files demonstrating training data provenance and performance validation across demographic subgroups under EU AI Act mandates.
- Cloud Computing:HIPAA security rules and GDPR compliance shape data residency requirements and infrastructure vendor selection.
- Bluetooth Low Energy:Low-power wireless protocols enable continuous wearable operation with minimal patient burden.
- Big Data Analytics:Population-level risk stratification commands premium pricing from payers seeking to optimize resource allocation across member networks.
Cloud computing underpins current scale; artificial intelligence is climbing the fastest as algorithmic triage matures.
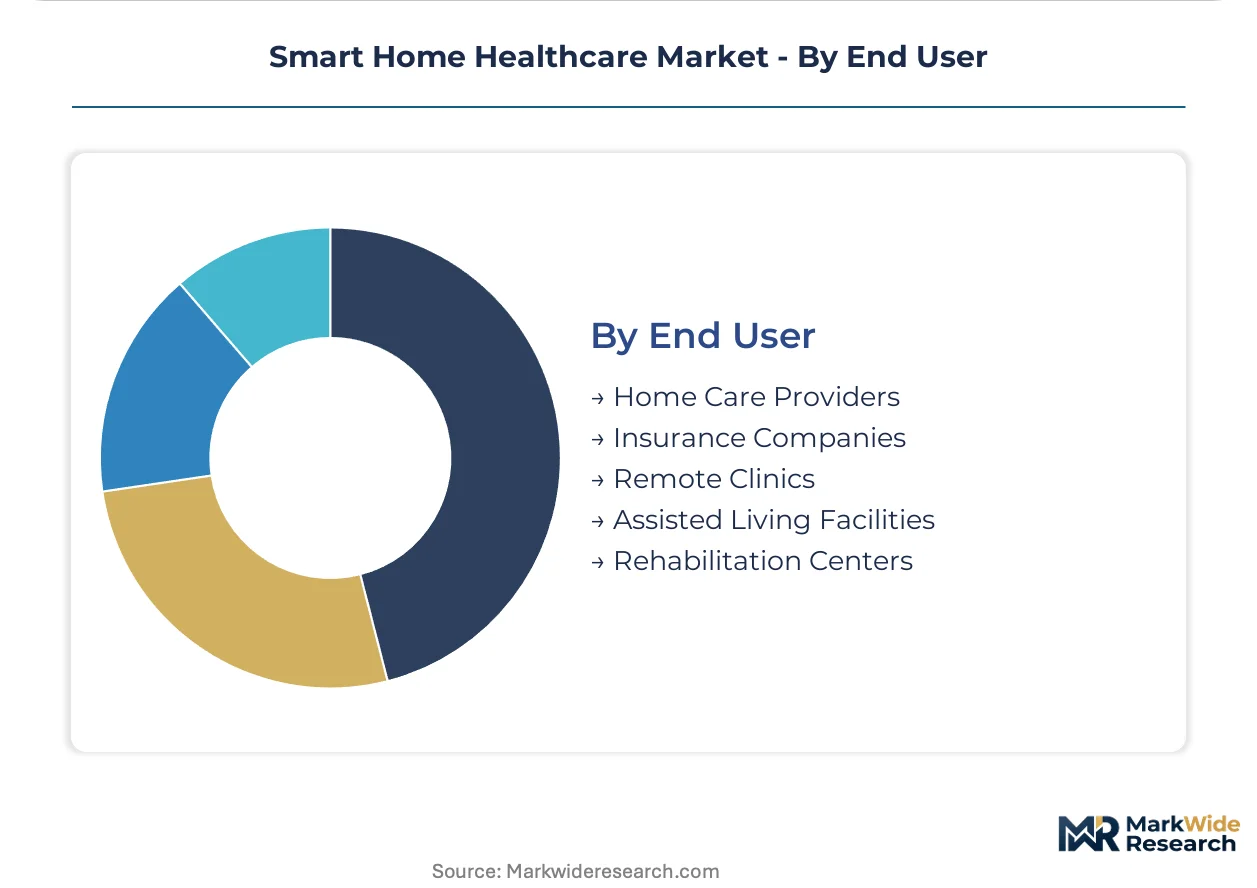
End User:
Procurement authority rotation and contracting model evolution reshape channel economics across institutional and commercial buyers.
- Home Care Providers:Regional nursing services and visiting nurse associations drive device selection for chronic disease management programs.
- Insurance Companies:Large payer networks anchor remote patient monitoring contracts through per-member-per-month pricing structures that displace capital equipment sales.
- Remote Clinics:Federally qualified health centers and rural health networks seek interoperable platforms with legacy electronic health record systems.
- Assisted Living Facilities:Senior housing operators deploy ambient sensors and emergency alert systems with lower clinical oversight requirements.
- Rehabilitation Centers:Post-acute care facilities represent a contracting channel with specialized integration needs and extended sales cycles.
Insurance companies dominate contract value; home care providers are gaining share fastest as procurement authority rotates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-connected healthcare data centers along the US East Coast fiber corridor anchor transatlantic patient monitoring traffic. Submarine cable landing stations in Germany and Japan handle parallel data flows for aging-population remote care networks.
United States
Medicare Advantage per-member-per-month contracting drives demand for continuous glucose monitoring platforms. FDA Software as a Medical Device guidance accelerates premarket pathways for algorithm-driven diagnostic tools. The Boston-Cambridge corridor concentrates cardiac rhythm monitoring R&D alongside payer network headquarters in Hartford and Minneapolis.
Germany
Reimbursement shifts toward in-home care create sustainable revenue streams for chronic disease monitoring platforms. EU MDR conformity assessment bottlenecks delay CE marking timelines for connected medical devices. The Rhine-Ruhr industrial belt hosts medical device manufacturing clusters while Berlin anchors digital health startup density.
Japan
Aging demographics accelerate in-home care adoption through government-funded remote monitoring programs. METI standards for medical device software shape local product certification requirements. The Kanto region around Tokyo concentrates hospital system procurement authority rotating toward home care providers.
United Kingdom
NHS long-term plan commitments expand remote patient monitoring pilots into standard care pathways. MHRA recognition of FDA approvals streamlines dual-market entry for US vendors. The Oxford-Cambridge arc clusters health AI development alongside London-based payer network decision centers.
Switzerland
Swissmedic's streamlined CE marking parallel process attracts EU-bound device manufacturers. Precision medicine initiatives in Basel and Zurich drive demand for continuous physiological data integration. The Lake Geneva region concentrates pharmaceutical headquarters seeking companion diagnostic partnerships with sensor platform vendors.
Smart Home Healthcare Market Key Industry Players
Listed leaders compete with private specialists across platform consolidation and subscription contracting dimensions. The vendor base organizes around three strategic archetypes: diversified medical device conglomerates anchoring payer network relationships, pure-play sensor specialists dominating disease-specific channels, and consumer technology platforms leveraging retail distribution for wellness-adjacent products. M&A activity concentrates on algorithmic triage capabilities and regional home care provider networks. Vertical integration into cloud infrastructure and clinical interpretation services displaces pure hardware margins.
Within the medical device conglomerate tier, Medtronic and Abbott exemplify vendors leveraging cardiac rhythm and glucose monitoring portfolios to anchor multi-year remote patient monitoring contracts. Dexcom occupies a position representing the pure-play sensor specialist archetype, with its wearable platform dominating diabetes management channel economics. These three anchors illustrate how regulatory sophistication and payer network access filter competitive positioning across FDA-cleared and CE-marked product categories.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Dexcom |
| Apple |
| Withings |
| Tunstall Group |
| VitalConnect |
| Medical Guardian |
| Others |
Cost & Logistics Intelligence
Per-member-per-month subscription contracting locks United States Medicare Advantage networks into multi-year remote patient monitoring agreements that bundle hardware, connectivity, and clinical interpretation, anchoring both supply access and price visibility across the forecast horizon.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared cardiac rhythm platforms from CE-marked multi-parameter biosensors and unregulated consumer wellness trackers. Price differentiation hinges on certification grade—specifically FDA Software as a Medical Device clearance versus EU MDR conformity—and volume scale through payer network contracting. Cost compression in the standard tier is intensifying because semiconductor supply concentration in East Asia constrains sensor module availability. Home care providers exhibit the highest price sensitivity as procurement authority rotates from hospital systems, while large insurance networks negotiate least-sensitive enterprise pricing.
Supply Chain Analysis
Strait of Malacca transit underwrites semiconductor component flows from Taiwan and South Korea to medical device assembly operations in Germany and Japan. Sensor module fabrication draws from Taiwanese foundries, South Korean memory suppliers, and Japanese precision component manufacturers. Single-source vulnerability concentrates in advanced CMOS image sensors and specialized biometric MEMS. Distribution runs through regional medical device distributors with FDA and CE marking expertise, who manage last-mile logistics to home care providers and insurance network fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates defensive moats in smart home healthcare, as FDA Software as a Medical Device guidance and EU MDR conformity requirements impose multi-year compliance timelines that filter vendor capabilities by documentation sophistication and quality management infrastructure.
For Market Incumbents: Fortify payer network relationships through algorithmic triage capabilities that command premium pricing for emergency department utilization reduction contracts. Deepen backward integration into cloud infrastructure to capture subscription revenue streams and defend against consumer technology platforms encroaching from wellness-adjacent categories. The EU AI Act transparency obligations threaten vendors without established technical file maintenance systems. For New Entrants and Emerging Players: Lead with ambient sensor integration for elderly care applications in Japan and Germany, where reimbursement shifts toward in-home care create white-space demand with lower regulatory barriers than cardiac rhythm monitoring. Target assisted living facilities with passive monitoring solutions that bypass FDA clearance requirements while building clinical validation track records for eventual payer network contracting. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vendors with established quality management systems and multi-market regulatory approvals. Long-term viability over the next decade rests on algorithmic differentiation and reimbursement code capture rather than hardware margins. Watch Medicare Advantage remote patient monitoring penetration rates as the primary inflection indicator for scalable deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Clears premarket pathways for algorithm-driven diagnostic tools in United States payer networks. |
| CE Marking Pathway under EU MDR | Unlocks German and Japanese aging-population reimbursement streams for chronic disease platforms. |
| Hospital System Partnership | Secures procurement rotation toward home care providers seeking emergency department reduction. |
| Software Companion Development | Extends hardware margins through subscription-based clinical interpretation services. |
| Reimbursement Strategy | Captures Medicare Advantage per-member-per-month pricing structures displacing capital equipment sales. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and payer network executives anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up unit economics triangulated against top-down payer spending estimates across product type, application, technology layer, and end-user channel dimensions.
Sensitivity analysis tested forecast outputs against reimbursement parity legislation timing, semiconductor supply disruption scenarios, and cybersecurity certification mandate acceleration. Segmentation modeling spanned remote monitoring devices, wearable sensors, telehealth platforms, and ambient monitoring systems across chronic disease management, elderly care, and postoperative care applications. CAGRs derived from installed base growth curves, replacement cycle analysis, and subscription pricing elasticity parameters.
Underlying assumptions cover reimbursement code expansion continuity, EU MDR notified body capacity normalization, and HIPAA security architecture investment trajectories, with deviation risk concentrated in algorithmic transparency obligation enforcement and cybersecurity incident response mandates. Practitioners should keep alternative scenarios live as FDA Software as a Medical Device guidance interpretation and EU AI Act implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
US Home Healthcare Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
House Call Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Home Care Products Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Global Health Caregiving Market